
 Remote Cooled Cube Ice Machines Market | 2026-2036
Remote Cooled Cube Ice Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Cooled Cube Ice Machines Market Analytics
EPA SNAP Rule 21 is restructuring capital planning for foodservice operators by restricting high-GWP refrigerants in new remote-cooled installations. Hoshizaki Corporation leverages its ammonia-ready compressor platforms to preempt compliance timelines. Manitowoc Ice anchors North American distribution through captive service networks. Scotsman Ice Systems specializes in compact modular architectures for urban kitchen footprints.
Remote cooled cube ice machines are self-contained refrigeration systems that generate clear cube ice through vertical evaporator plates while rejecting condenser heat to a distant location via refrigerant lines, typically operating between 300 and 2,000 pounds of daily ice production capacity. The equipment serves high-volume commercial kitchens where ambient heat rejection would strain HVAC loads. Modular ice makers command the largest installed base due to scalable configuration across chain restaurant buildouts, while under-counter units capture fastest growth from boutique hospitality concepts with space-constrained floor plans. Ice storage bins represent a mature margin pool where aftermarket attachment rates sustain recurring revenue streams.
EPA SNAP regulations and DOE commercial refrigeration efficiency standards shape equipment specifications and refrigerant selection across the United States market. OSHA ventilation requirements and local plumbing codes govern installation protocols for remote condenser placement. Stakeholders must weigh refrigerant transition pathways against compressor platform longevity before committing to capital deployment cycles.
Market Dynamics
EPA SNAP Rule 21 refrigerant phase-down mandates are compressing equipment replacement cycles across commercial foodservice operations, forcing operators to accelerate capital deployment toward low-GWP compressor platforms before compliance deadlines lock in technology choices.
Growth Catalysts
- Regulatory Compliance Deadlines:EPA SNAP regulations restricting hydrofluorocarbon refrigerants in new remote-cooled installations create immediate replacement demand among full-service restaurant chains operating legacy R-404A systems.
- Sun Belt Construction:Modular ice maker demand concentrates in the United States Sun Belt corridor where high ambient temperatures strain HVAC loads and remote heat rejection becomes economically essential.
- Energy Efficiency Standards:DOE commercial refrigeration efficiency standards drive specification upgrades toward variable-speed compressor platforms that reduce operating costs across 24-hour kitchen operations.
Market Restraints
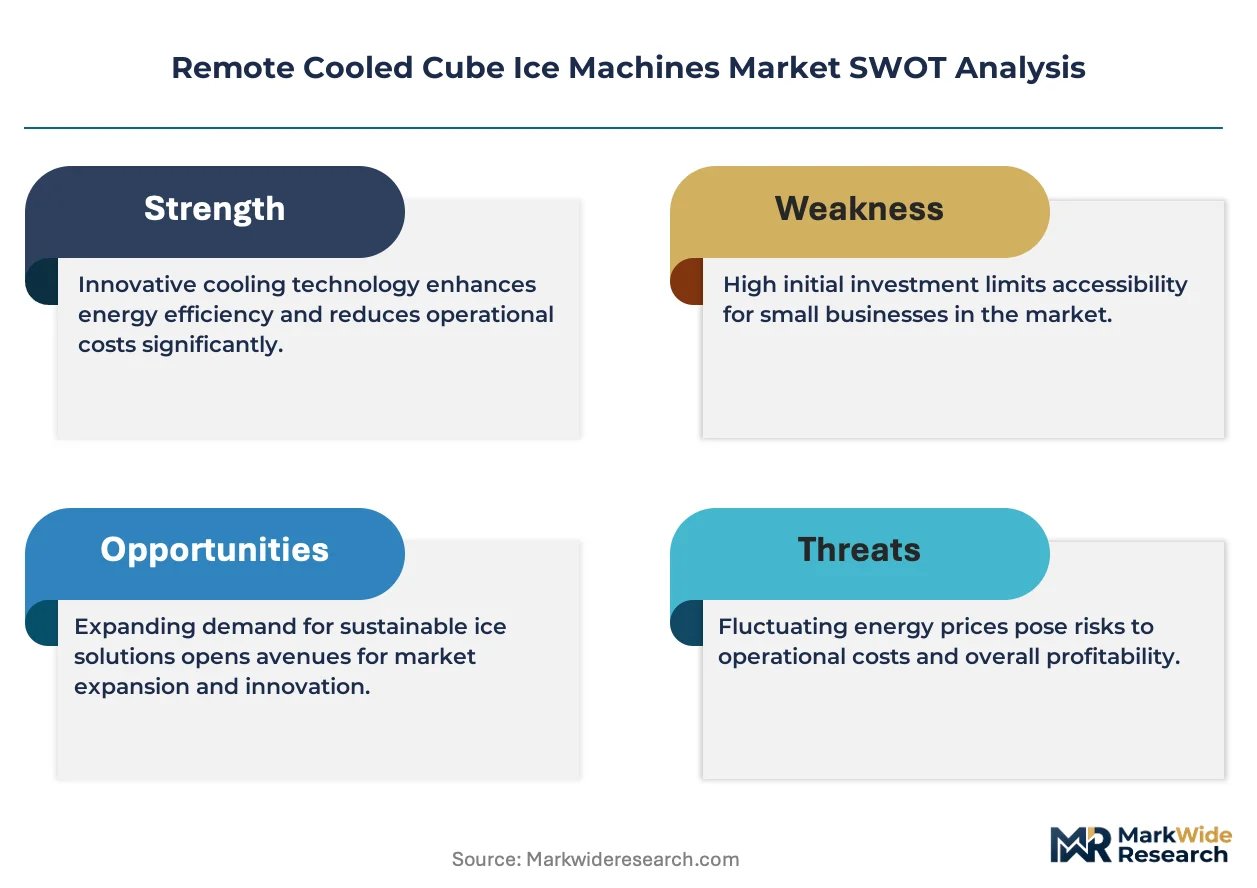
- Copper and Aluminum Volatility:Refrigerant line fabrication depends on copper tubing and aluminum condenser coils, exposing manufacturers to commodity price swings that compress margin predictability on fixed-price chain contracts.
- Specialized Service Concentration:Remote condenser installation and maintenance requires EPA Section 608 certified technicians, creating geographic coverage gaps in secondary markets that extend downtime risk.
- Water Quality Variability:Scale-prone municipal water supplies in southwestern states accelerate evaporator plate fouling, increasing preventive maintenance frequency and total cost of ownership calculations.
Strategic Opportunities
- Underpenetrated Boutique Hospitality:Urban micro-kitchens and ghost kitchen facilities in dense metropolitan cores present untapped demand for compact under-counter remote-cooled units with minimal footprint requirements.
- Natural Refrigerant Transition:Ammonia-ready and CO2 transcritical compressor platforms position early adopters to capture specification share as EPA SNAP timelines advance and state-level refrigerant restrictions proliferate.
- Aftermarket Service Integration:Ice storage bin attachment and predictive maintenance telemetry create recurring revenue streams that decouple manufacturer economics from pure equipment sales cycles.
Industry Challenges
- Refrigerant Handling Certification:EPA Section 608 technician shortage constrains installation capacity during peak construction seasons, creating project delays for multi-unit restaurant rollouts.
- Legacy System Integration:Remote condenser retrofit compatibility with existing kitchen HVAC infrastructure requires custom engineering that extends sales-to-commissioning timelines and strains contractor relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Cooled Cube Ice Machines Market |
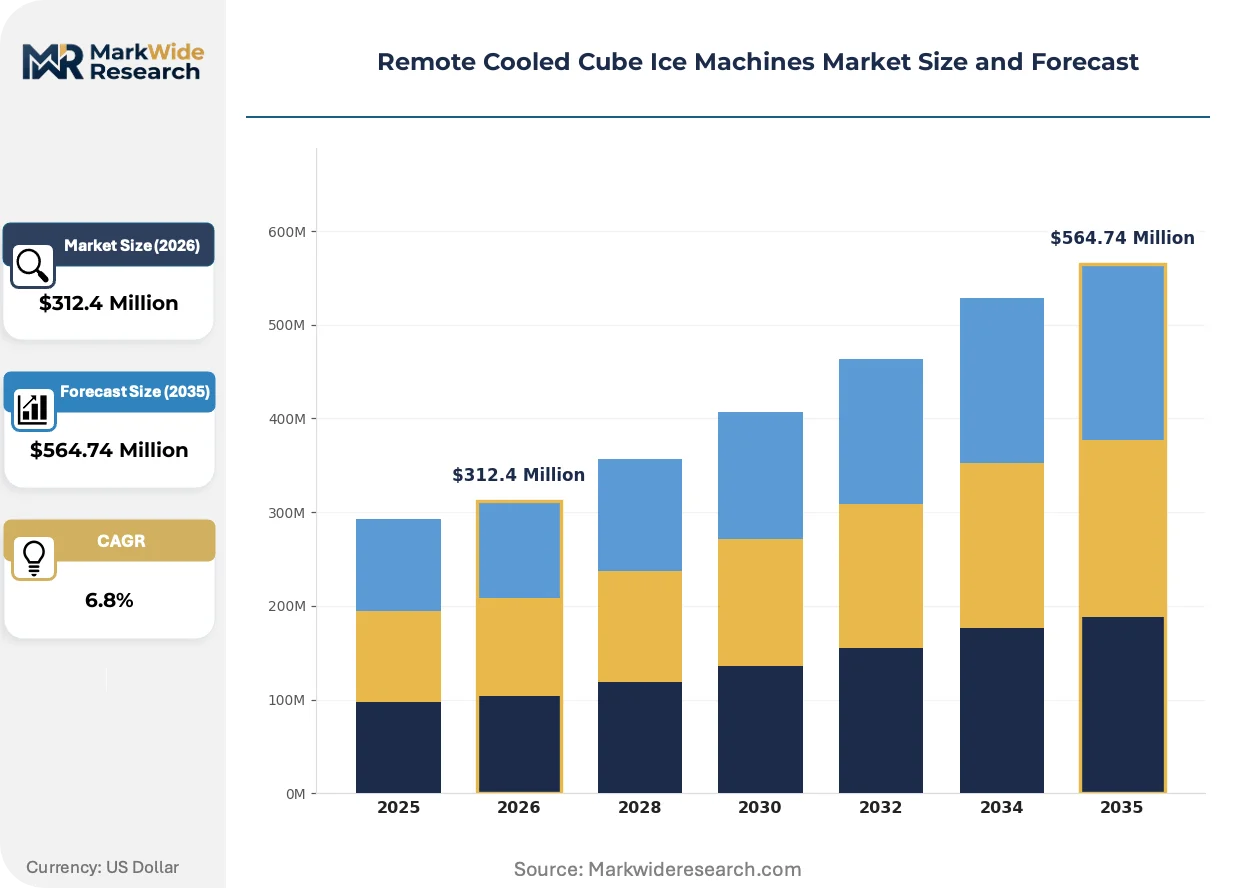
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
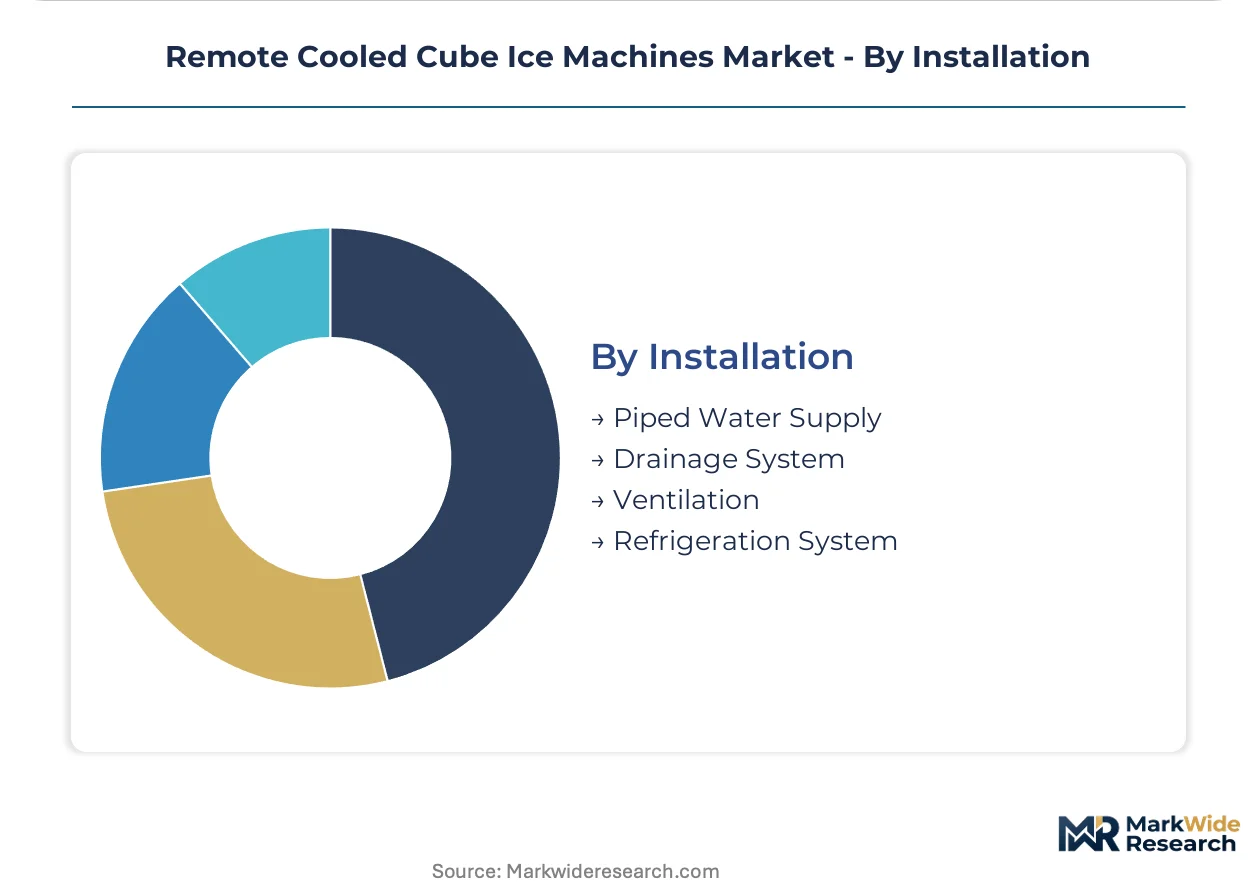
| Segmentation | Product Type: Modular Ice Makers, Under-Counter Ice Makers, Ice Storage Bins, Portable Ice Makers Application: Restaurants, Hotels, Bars, Healthcare Facilities End User: Commercial Kitchens, Food Services, Hospitals, Retail Stores Installation: Piped Water Supply, Drainage System, Ventilation, Refrigeration System |
| Companies Covered | Ice-O-Matic, Cornelius, Hoshizaki Corporation, Tamutom Refrigeration, Focusun Refrigeration, Manitowoc Ice, Follett LLC, LACOPINE, Scotsman Ice Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Cooled Cube Ice Machines Market Evolving Landscape
Equipment architecture is converging around intelligent compressor modulation and connected service platforms that transform capital goods into managed utility assets for high-volume foodservice operators.
Variable-speed scroll compressor technology is unifying energy performance with demand-responsive ice production. Chain restaurant operators deploy these platforms across flagship locations to shave peak electrical demand charges. The technology is unifying equipment specification standards across national accounts that previously accepted mixed-vendor portfolios.
The EPA SNAP Rule 21 refrigerant phase-down is restructuring procurement specifications toward A2L and natural refrigerant platforms. Equipment manufacturers must recertify compressor architectures under UL safety standards for mildly flammable refrigerants. Full-service restaurant chains in California and New York markets face the most compressed compliance timelines and are pre-buying transitional inventory.
Equipment-as-service contracting is displacing traditional capital purchase models among multi-unit operators. Third-party fleet managers assume ownership and maintenance burden in exchange for per-pound ice pricing. This model concentrates fastest in airport and stadium concession environments where capital flexibility outweighs long-term ownership economics.
Remote Cooled Cube Ice Machines Market Segmentation
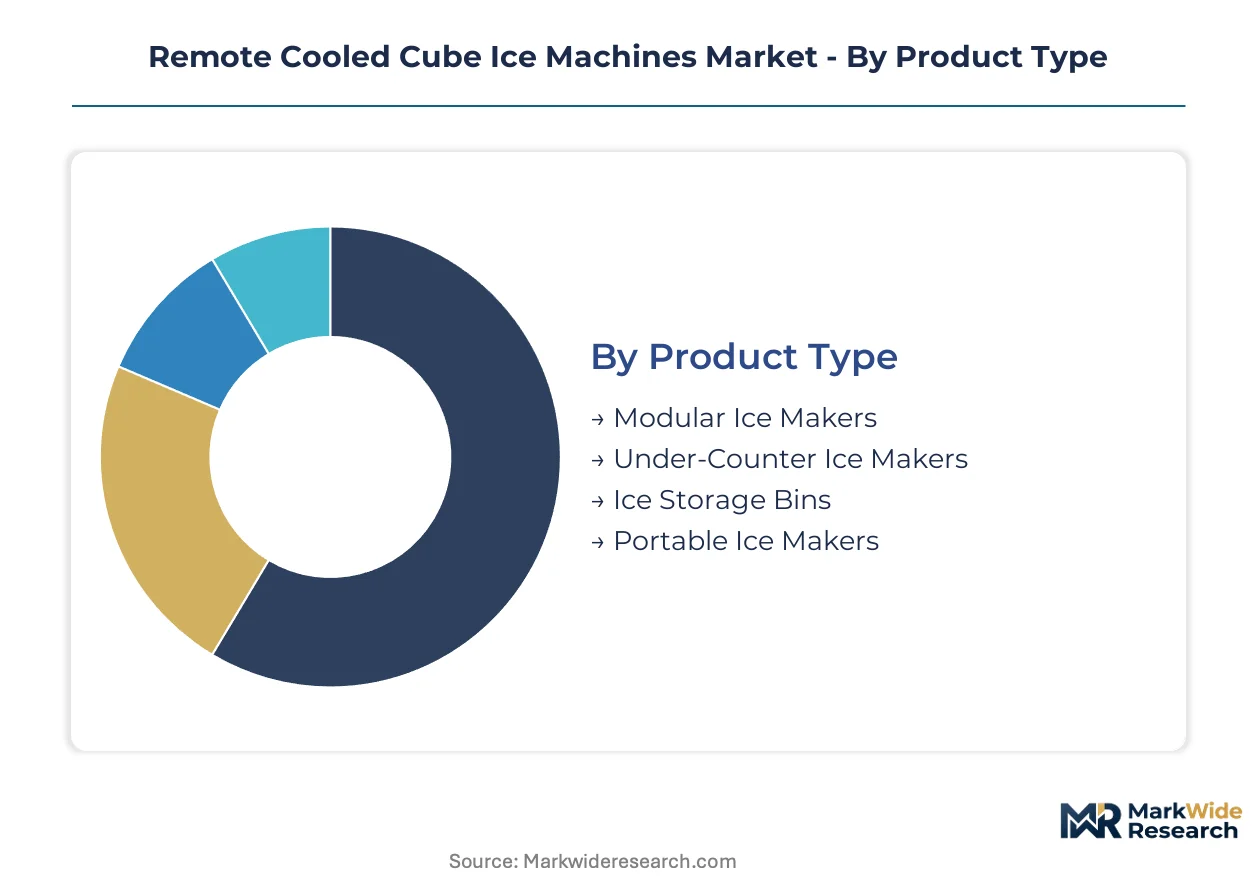
Remote cooled cube ice machines serve distinct operational contexts where heat rejection distance, production scale, and space constraints dictate equipment selection. Segmentation reveals how regulatory pressure and facility architecture fragment demand across product configurations and installation requirements.
Product Type:
Standalone units dominate chain restaurant deployments where centralized ice production feeds multiple service points, while embedded systems integrate into compact kitchen lines for space-constrained operators.
- Modular Ice Makers:These scalable units mount atop separate storage bins and reject condenser heat through remote lines up to 100 feet distant. Demand concentrates across the United States Sun Belt corridor where Arizona and Texas operators face extreme ambient temperatures that strain HVAC loads. EPA SNAP Rule 21 refrigerant phase-downs accelerate replacement cycles among full-service restaurant chains operating legacy R-404A platforms.
- Under-Counter Ice Makers:Compact self-contained architectures fit beneath standard kitchen counters with minimal footprint requirements. Urban micro-kitchens and ghost kitchen facilities in dense metropolitan cores drive fastest expansion as operators prioritize floor space efficiency over maximum production capacity.
- Ice Storage Bins:Insulated polyethylene or stainless steel vessels maintain ice quality between production and service periods.
- Portable Ice Makers:Mobile units with onboard water reservoirs serve temporary catering operations and event venues requiring rapid deployment without permanent plumbing connections.
Volume placements concentrate in modular configurations; the faster expansion belongs to under-counter units.
Application:
High-throughput environments with continuous ice demand justify capital-intensive remote-cooled installations, while intermittent-use settings accept simpler equipment economics.
- Restaurants:Full-service and quick-service chains constitute the core installed base, with remote heat rejection essential for kitchen climate control in high-volume operations. California and New York markets face compressed EPA SNAP compliance timelines that force accelerated equipment refresh decisions.
- Hotels:Property-wide ice provisioning from central production facilities reduces distributed maintenance burden across guest floors and banquet operations.
- Bars:Craft cocktail establishments prioritize clear cube quality for beverage presentation over maximum production throughput.
- Healthcare Facilities:Hospital dietary departments and clinical laboratories require sanitary ice production with rigorous cleaning protocols and redundant backup systems.
Restaurants anchor equipment shipments; healthcare applications gain specification share fastest as infection control standards tighten.
End User:
Capital deployment capacity and maintenance infrastructure separate enterprise-scale operators from independent facilities with constrained technical resources.
- Commercial Kitchens:Independent and multi-unit restaurant operations with dedicated facilities management staff absorb remote condenser complexity.
- Food Services:Contract management companies operating across institutional accounts standardize on modular platforms for fleet consistency.
- Hospitals:Healthcare systems specify redundant ice production with emergency power integration and automated sanitization cycles.
- Retail Stores:Convenience chains and grocery delis deploy compact units for fountain beverage and seafood display applications.
Commercial kitchens generate the largest equipment volume; hospital procurement is climbing the fastest as patient safety protocols intensify.
Installation:
System integration requirements determine project complexity and contractor specialization needs across new construction versus retrofit deployments.
- Piped Water Supply:Permanent municipal connections with filtration and softening systems protect evaporator plates from scale accumulation in southwestern states with hard water chemistry.
- Drainage System:Gravity or pumped waste removal for meltwater and cleaning cycles must comply with local plumbing codes governing foodservice discharge.
- Ventilation:Remote condenser placement requires OSHA-compliant access platforms and clearance zones for technician safety during maintenance operations.
- Refrigeration System:EPA Section 608 certified technicians must handle refrigerant line fabrication and charging, creating geographic coverage constraints in secondary markets.
Piped water and drainage dominate new construction specifications; refrigeration system retrofits face the steepest expansion trajectory as compliance deadlines compress replacement windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in the United States Sun Belt corridor concentrate remote-cooled ice machine deployment through accelerated depreciation incentives and state-level energy rebate programs targeting commercial kitchen infrastructure.
United States
Full-service restaurant chains across Arizona and Texas face extreme ambient temperatures that strain HVAC loads and necessitate remote heat rejection systems. EPA SNAP Rule 21 mandates accelerate equipment refresh cycles among operators running legacy R-404A platforms. Dallas-Fort Worth and Phoenix metropolitan clusters absorb the highest modular ice maker shipment volumes as chain buildouts expand.
Germany
Industrial foodservice operations and institutional catering networks drive specification demand for energy-efficient refrigeration platforms. The EU F-Gas Regulation restricts high-GWP refrigerants in new commercial installations, compressing replacement timelines. Bavaria's Munich-Stuttgart industrial corridor hosts concentrated equipment distribution networks serving central European markets.
China
Rapid hospitality sector expansion and international hotel chain penetration create specification pull for modular ice production systems. National dual carbon goals and provincial energy efficiency standards shape compressor platform selection criteria. Yangtze River Delta manufacturing clusters around Shanghai supply domestic and export market demand.
Japan
Compact urban kitchen footprints and premium beverage culture sustain demand for space-efficient under-counter configurations. METI energy efficiency labeling programs and building code standards govern equipment specification in commercial developments. Tokyo-Osaka metropolitan corridors concentrate boutique hospitality and high-end restaurant deployments.
Australia
Remote mining camp catering and coastal hospitality operations require robust ice production in high-temperature environments. National construction code energy efficiency provisions and state-level commercial refrigeration standards influence procurement decisions. Queensland and Western Australia resource corridor projects sustain modular equipment demand.
Remote Cooled Cube Ice Machines Market Competitive Landscape
United States producers anchor the premium-tier specification channel; Asian fabricators hold volume positions in cost-sensitive segments. The vendor base organizes around three strategic tiers: multinational refrigeration conglomerates with captive service networks, regional specialists in compact modular architectures, and emerging manufacturers targeting natural refrigerant transition windows. Competitive dynamics center on M&A activity consolidating distribution footprints and technology licensing arrangements accelerating A2L refrigerant platform certification.
Within the multinational tier, Hoshizaki Corporation and Manitowoc Ice occupy anchor positions representing divergent strategic postures toward compliance timelines and service network density. Scotsman Ice Systems exemplifies the compact modular specialist archetype targeting space-constrained urban installations. These three entities collectively illustrate how refrigerant transition readiness and geographic service coverage separate specification winners from commodity competitors.
| Leading Market Players |
|---|
| Ice-O-Matic |
| Cornelius |
| Hoshizaki Corporation |
| Tamutom Refrigeration |
| Focusun Refrigeration |
| Manitowoc Ice |
| Follett LLC |
| LACOPINE |
| Scotsman Ice Systems |
| Others |
Value Network & Pricing Analysis
EPA SNAP Rule 21 refrigerant phase-down mandates gate both qualified supply and premium-tier pricing access, restricting compressor platform certification to manufacturers with UL safety recertification capabilities while forcing full-service restaurant chains toward pre-qualified vendor lists that command 15-20% pricing premiums over uncertified alternatives.
Pricing Analysis
Short lead-time premiums dominate transaction structures, with spot inventory from Arizona and Texas distributors trading at standard contract rates while expedited delivery for California compliance deadlines extracts material surcharges. Three-tier pricing structure across premium, standard, and economy levels separates ammonia-ready platforms with predictive maintenance telemetry from basic R-404A replacement stock and refurbished legacy units. Cost compression in the economy tier is intensifying because aluminum condenser coil volatility compresses margin predictability on fixed-price chain contracts. Independent restaurant operators exhibit highest price sensitivity, while airport and stadium concession managers prioritize capital flexibility over unit economics.
Supply Chain Analysis
Refurbishment flows for ice storage bins and compressor modules create secondary supply channels that extend equipment lifecycle and pressure new-unit pricing, with certified remanufacturers in Ohio and Georgia capturing 8-12% of replacement demand. Manufacturing concentrates in China, the United States, and Italy, with Yangtze River Delta fabricators supplying cost-sensitive modular platforms and Ohio-based facilities anchoring premium-tier production. Copper tubing and aluminum condenser coils constitute critical input dependencies, with refrigerant line fabrication tethered to London Metal Exchange price swings. Single-source vulnerability in EPA Section 608 certified technician pools constrains installation capacity during peak construction seasons. Distribution runs through captive service networks for multinational conglomerates and independent HVAC contractors for regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The remote cooled cube ice machine market sits in a technology-transition phase, with variable-speed scroll compressor platforms displacing fixed-speed legacy architectures and enabling demand-responsive ice production that reshapes operator capital planning.
For Market Incumbents: Lock in specification share across national restaurant accounts by accelerating A2L refrigerant platform certification under UL safety standards before California and New York compliance deadlines crystallize vendor selection. Backward integration into compressor module production secures margin control against commodity volatility, while predictive maintenance telemetry deployment transforms transactional equipment sales into recurring service revenue streams that insulate against pure price competition.
For New Entrants and Emerging Players: Capture white-space demand in urban micro-kitchens and ghost kitchen facilities where compact under-counter configurations face minimal incumbent saturation and space-constrained operators prioritize footprint efficiency over brand recognition. Boutique hospitality corridors in Tokyo-Osaka and dense European metropolitan cores present the most penetrable geographic entry points, with equipment-as-service contracting models offering a differentiated go-to-market angle that decouples customer capital constraints from purchase decisions.
For Investors and Strategic Acquirers: EPA SNAP Rule 21 pre-buying announcements from full-service restaurant chains is the leading indicator that refrigerant transition windows are compressing and early-mover platform investments will capture disproportionate specification share. Long-term viability across the projection horizon favors manufacturers with ammonia-ready compressor architectures and captive service network density, with acquisition target archetypes clustering around regional specialists with compact modular expertise and underpenetrated geographic footprints. Practitioners should monitor state-level refrigerant restriction legislative calendars and chain restaurant capital expenditure disclosures for early inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| A2L Refrigerant Platform Certification | UL safety recertification unlocks California and New York specification access before compliance deadlines lock in vendor selection. |
| Backward Integration into Compressor Modules | In-house production of scroll compressor platforms insulates margin structure against copper and aluminum commodity volatility. |
| Predictive Maintenance Telemetry Deployment | Connected service platforms transform capital goods into managed utility assets with recurring revenue per-pound ice pricing. |
| Equipment-as-Service Contracting Model | Third-party fleet ownership decouples operator capital constraints from equipment procurement in airport and stadium concessions. |
| Compact Under-Counter Product Line Expansion | Urban micro-kitchen and ghost kitchen penetration captures fastest-growing segment with minimal incumbent competition. |
Research Methodology
Document review covered EPA regulatory filings, DOE commercial refrigeration efficiency standards, and SEC 10-K disclosures from publicly traded equipment manufacturers, complemented by interviews with foodservice facilities directors, EPA Section 608 certified technicians, chain restaurant procurement officers, and HVAC distribution channel managers. Secondary validation drew from customs trade data, state energy rebate program records, and municipal plumbing code variations across southwestern states. Bottom-up triangulation aggregated individual equipment shipments and installation permits, while top-down analysis cross-referenced against chain restaurant buildout announcements and hospitality sector construction indices.
Segmentation outputs span product type, application, end user, and installation configuration dimensions, with geographic clustering modeled at metropolitan statistical area resolution for Sun Belt corridor analysis. CAGRs were derived from regression against historical replacement cycle data and regulatory deadline acceleration effects, with compressor platform transition timelines and water quality variability across southwestern states serving as industry-specific forecast inputs throughout the modeling period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA SNAP rule implementation delays, copper price volatility, and technician certification program expansion rates. Practitioners should monitor state legislative calendars for refrigerant restrictions and chain restaurant quarterly capital expenditure disclosures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Industrial Dishwasher Market