
 Commercial Airport Full Body Scanners Market | 2026-2036
Commercial Airport Full Body Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Airport Full Body Scanners Market Outlook
Millimeter wave imaging with automated threat recognition is reshaping how full body scanners detect concealed objects without human image review. Smiths Detection leverages extensive installed bases across European hubs to sustain service revenue streams. L3Harris Technologies anchors North American procurement through TSA-certified platforms deployed at major federalized airports. Nuctech Company Limited dominates manufacturing scale, supplying cost-optimized units to emerging aviation markets across Africa and Latin America.
Commercial airport full body scanners are security screening systems that use non-ionizing electromagnetic radiation or low-dose X-ray backscatter to generate anatomically accurate images for detecting weapons, explosives, and contraband concealed under clothing, operating at frequencies between 24 GHz and 30 GHz for millimeter wave variants with resolution sufficient to identify anomalies as small as several millimeters. Millimeter wave technology leads installed capacity due to passenger privacy advantages and elimination of ionizing radiation concerns, while backscatter systems retain niche positions where penetration depth for dense materials outweighs throughput speed requirements. Portable and mobile deployment configurations represent the fastest-growing segment as airports seek flexible checkpoint reconfiguration during peak travel periods and temporary terminal expansions.
The FAA and TSA in the United States enforce certification standards under the Screening Partnership Program, while the European Union Aviation Safety Agency coordinates member state adoption of Common Evaluation Process protocols for detection performance validation. These frameworks shape demand by mandating minimum detection thresholds and data deletion protocols that filter non-compliant vendors from procurement shortlists. Stakeholders must monitor evolving algorithm transparency requirements and passenger consent regulations that could reshape software upgrade cycles and aftermarket service obligations.
Market Dynamics
Millimeter wave imaging with automated threat recognition is compressing detection workflows by eliminating human image review, forcing incumbent vendors to reengineer software architectures around algorithmic transparency mandates from multiple aviation regulators.
Growth Catalysts
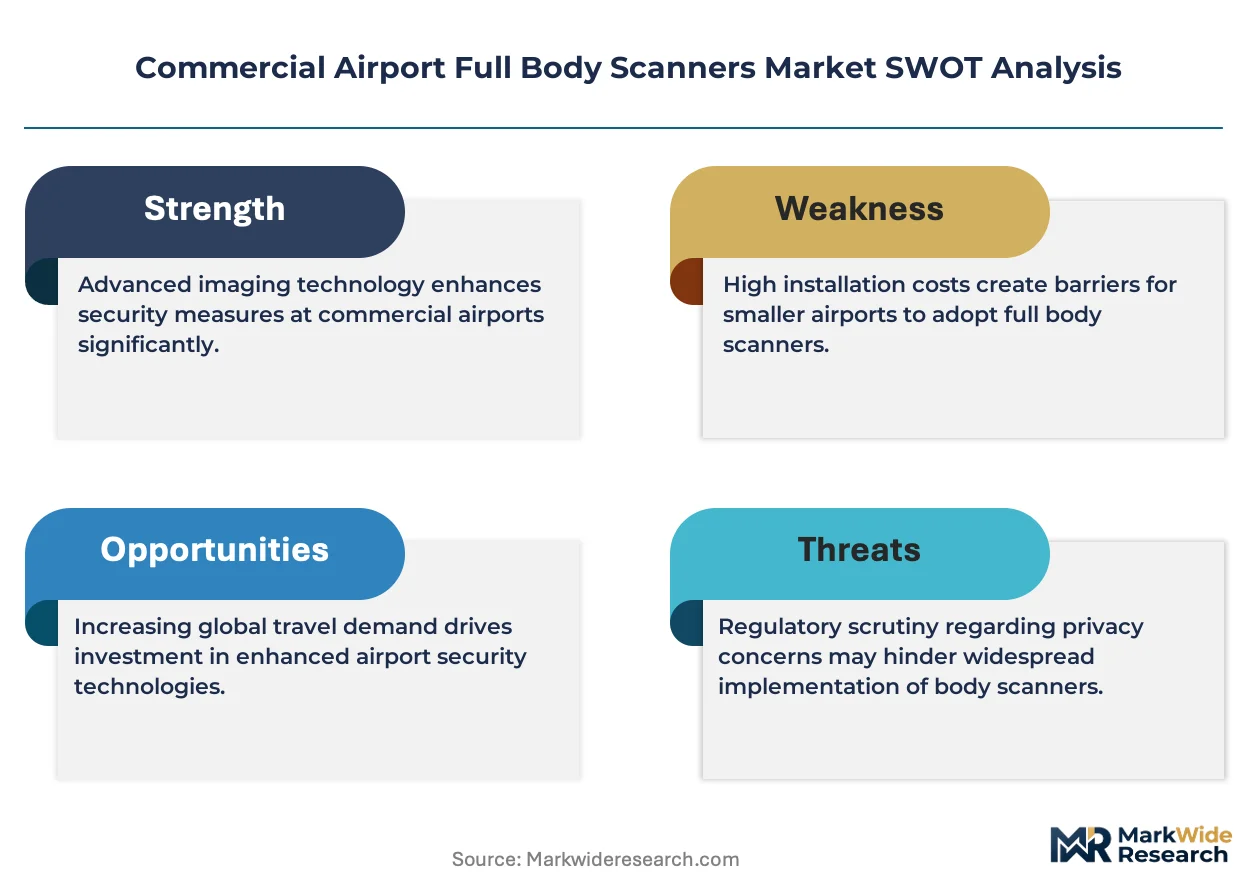
- TSA Screening Partnership Program mandates:Federal certification requirements in the United States create procurement pull-through at Category X airports, accelerating replacement cycles for legacy metal detection portals.
- India's airport infrastructure expansion:Greenfield terminal construction at Delhi, Mumbai, and Bangalore hubs is generating concentrated demand for passenger throughput optimization equipment.
- Privacy-preserving scan reconstruction:Generic avatar software overlays are neutralizing civil liberty objections that previously stalled deployment in European Union member states.
Market Restraints
- Semiconductor component concentration:Millimeter wave transceiver modules depend on gallium arsenide foundry capacity concentrated in East Asian manufacturing clusters, exposing lead times to geopolitical supply friction.
- Ionizing radiation liability exposure:Backscatter X-ray variants face persistent tort risk from passenger health claims, constraining deployment to secondary screening lanes where penetration depth justifies operational complexity.
- EASA Common Evaluation Process timelines:Extended validation protocols for algorithm updates delay feature rollouts by 18-24 months versus manufacturer development cycles.
Strategic Opportunities
- Southeast Asian greenfield airports:Vietnam and Indonesia are constructing passenger terminals without legacy baggage handling infrastructure, enabling integrated security checkpoint design from foundation.
- Mobile deployment configurations:Trailer-mounted scanner units address temporary terminal expansions and event-driven passenger surges at seasonal tourism destinations.
- EU AI Act algorithmic accountability rules:Automated threat recognition systems face mandatory explainability standards that favor vendors with established machine learning audit trails.
Industry Challenges
- Millimeter wave RF engineering talent scarcity:Specialized antenna design and signal processing expertise concentrates at defense contractors, constraining commercial vendor hiring pipelines.
- Legacy checkpoint integration complexity:Retrofitting existing terminal footprints requires structural reinforcement for scanner foundations and power distribution upgrades incompatible with 1990s electrical specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Airport Full Body Scanners Market |
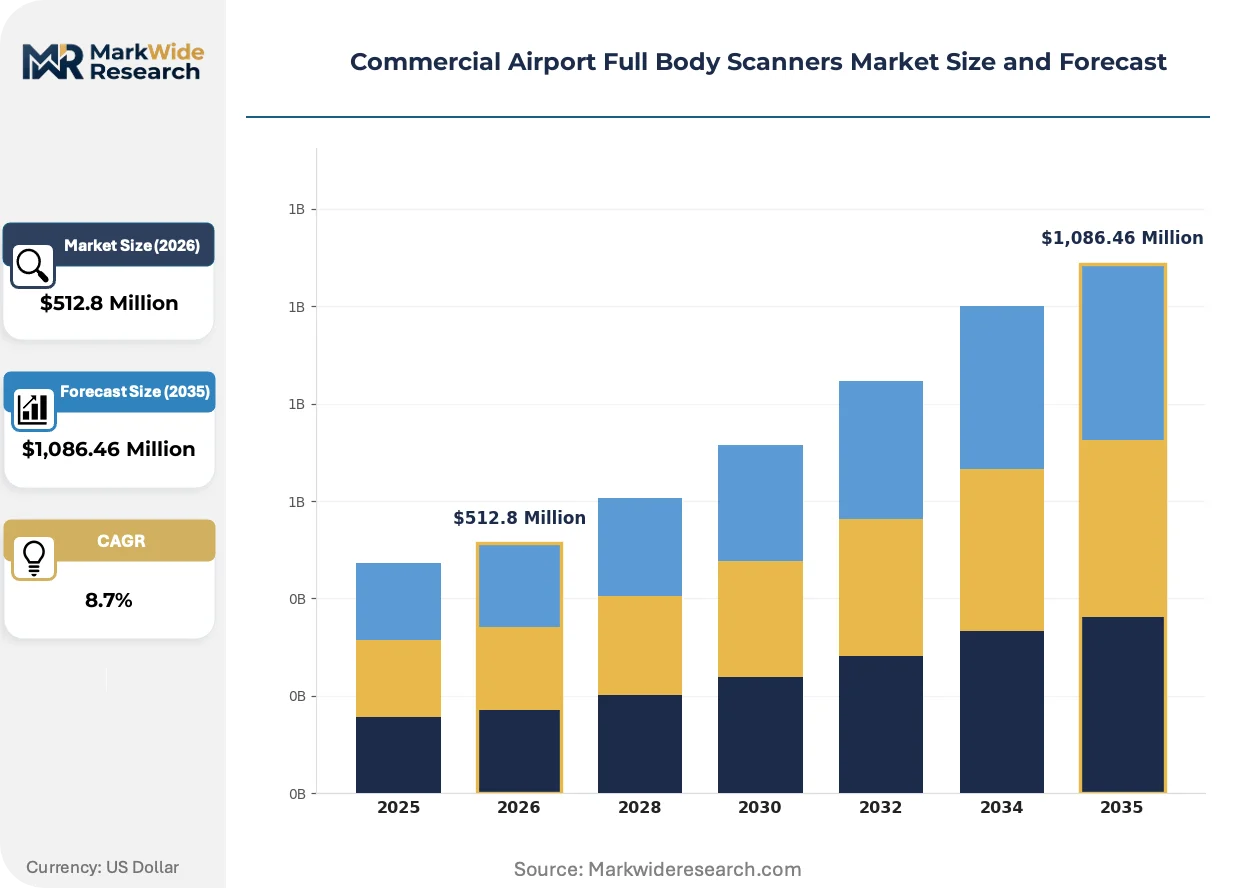
| Market Size in 2026 | $512.8 Million |
| Market Size in 2035 | $1,086.46 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Millimeter Wave, Backscatter, X-Ray, Dual-View End User: Airports, Security Firms, Government Agencies, Airlines Application: Passenger Screening, Baggage Inspection, Security Checks, Threat Detection Deployment: Fixed Systems, Portable Systems, Mobile Units, Customized Solutions |
| Companies Covered | L3Harris Technologies, Nuctech Company Limited, Smiths Detection, ODSecurity, LINEV Systems, Leidos, Rohde & Schwarz, Thales Group, Rapiscan Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Airport Full Body Scanners Market Strategic Shifts
Aviation security checkpoint design is pivoting from fixed infrastructure toward modular reconfiguration, with software-defined detection replacing hardware-centric threat identification across major hub procurement specifications.
Passive millimeter wave imaging is collapsing the distinction between primary and secondary screening lanes. The technology detects anomalies under clothing without passenger pose requirements or mechanical rotation. Major European hubs including Frankfurt and Amsterdam Schiphol are deploying these units at standard throughput positions. This compression is eliminating the bottleneck of dedicated secondary inspection zones, freeing terminal real estate for retail and passenger amenities.
The European Union Aviation Safety Agency is tightening algorithm transparency requirements through Common Evaluation Process updates. Manufacturers must now submit training data documentation and bias testing protocols for automated threat recognition software. Vendors with opaque machine learning architectures face exclusion from procurement shortlists. This regulatory pressure is accelerating open-architecture software development at established European suppliers.
Airport operators are unbundling hardware purchase from maintenance and software upgrade obligations. Large hub authorities in the United States and Gulf Cooperation Council states are negotiating performance-based service agreements where vendors retain equipment ownership. This shift transfers obsolescence risk to manufacturers and aligns upgrade cycles with regulatory mandate timelines rather than capital budget cycles. The model is most advanced at Dubai International and Hamad International, where integrated facility management contracts span entire security checkpoints.
Commercial Airport Full Body Scanners Market Segmentation
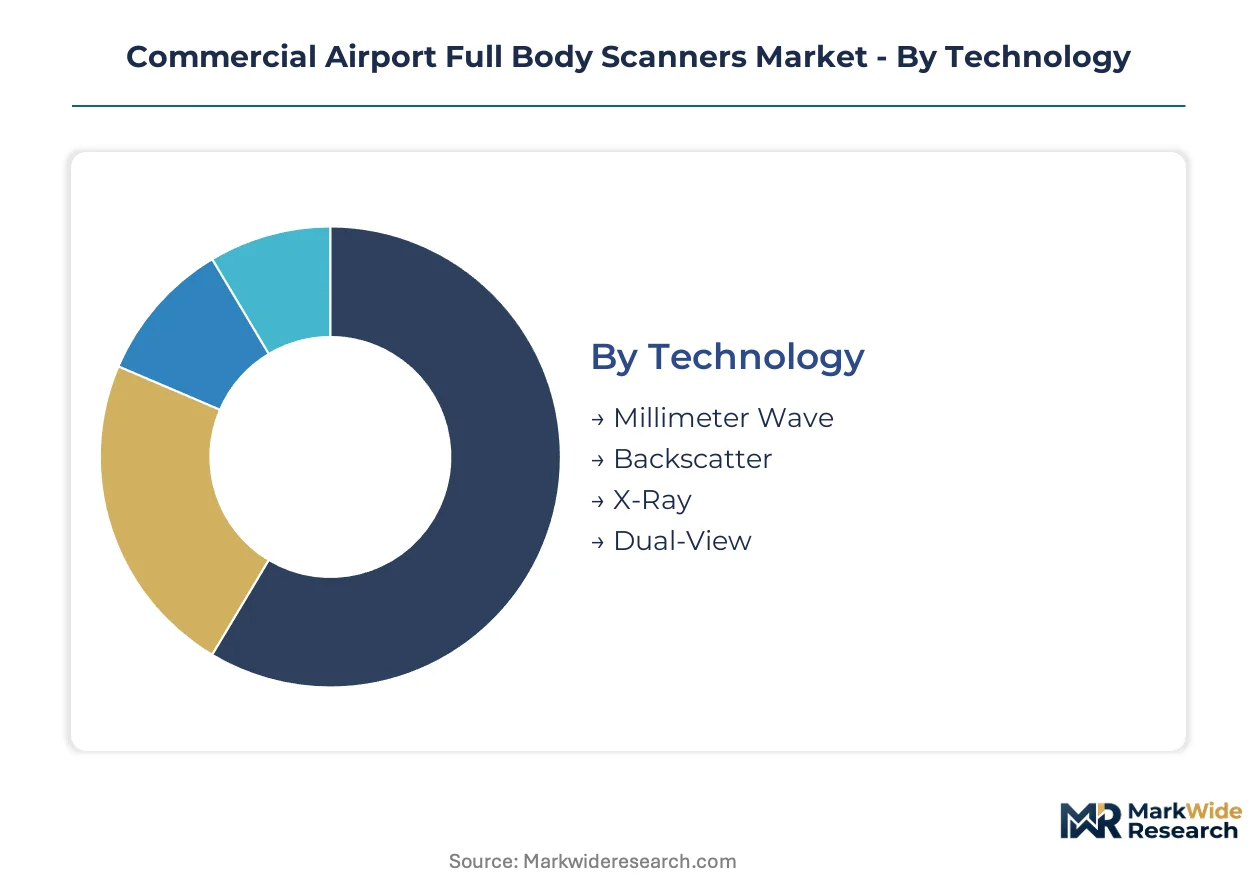
Technology configuration determines aftermarket service intensity across scanner deployments, with algorithm-dependent systems requiring continuous software validation and hardware-centric platforms demanding periodic component replacement. Procurement specifications increasingly unbundle equipment purchase from multi-year maintenance obligations, reshaping vendor revenue structures toward recurring service streams.
Technology:
Service contract attach rates vary sharply by detection modality, with software-defined architectures commanding premium support pricing due to regulatory recertification burdens.
- Millimeter Wave:Non-ionizing electromagnetic systems operating between 24 GHz and 30 GHz generate anatomically accurate images through active or passive antenna arrays. Demand concentrates at Category X airports in the United States where TSA mandates automated threat recognition without human image review, driving continuous algorithm update cycles. By volume, Millimeter Wave leads. By growth pace, Dual-View is ahead.
- Backscatter:Low-dose X-ray backscatter technology penetrates dense materials with single-sided exposure geometry, retaining niche deployment where contraband depth detection outweighs throughput speed constraints. European hubs including Frankfurt and Amsterdam Schiphol limit backscatter to secondary screening lanes due to persistent passenger health liability exposure, compressing addressable market scope.
- X-Ray:Transmission-based ionizing systems deployed primarily for baggage and cargo inspection rather than passenger screening, with regulatory restrictions constraining human exposure applications.
- Dual-View:Multi-perspective imaging architectures combining orthogonal projection angles to reduce false positive rates and eliminate passenger repositioning requirements.
Millimeter Wave dominates installed base. Dual-View configurations are expanding most quickly.
End User:
Budget authority fragmentation across stakeholder types creates divergent procurement timelines, with federal agencies enforcing multi-year certification cycles while commercial operators prioritize rapid deployment flexibility.
- Airports:Terminal operators at federalized and privatized hubs represent the core demand base, with infrastructure expansion in India and Southeast Asia driving greenfield installations without legacy checkpoint constraints. By volume, Airports lead. By growth pace, Security Firms are ahead.
- Security Firms:Third-party screening contractors operating under TSA Screening Partnership Program and equivalent European frameworks, absorbing equipment ownership risk through performance-based service agreements at Dubai International and Hamad International.
- Government Agencies:National aviation authorities and border control departments procuring for non-airport critical infrastructure including courthouses and government facilities.
- Airlines:Premium carriers deploying proprietary checkpoint solutions at dedicated terminals, though regulatory compliance complexity limits independent procurement scale.
Airports command procurement volume. Security Firms are gaining share fastest.
Application:
Functional use case determines throughput specifications and detection threshold calibration, with passenger-facing applications demanding higher resolution standards than cargo-oriented deployments.
- Passenger Screening:Primary checkpoint deployment for weapons, explosives, and contraband detection under clothing, with privacy-preserving avatar overlays neutralizing civil liberty objections that previously stalled European Union adoption. By volume, Passenger Screening leads. By growth pace, Threat Detection is ahead.
- Baggage Inspection:Checked luggage and carry-on screening typically handled by integrated CT systems rather than full body scanners, creating limited addressable overlap.
- Security Checks:Secondary screening protocols for alarm resolution and random selection protocols at high-risk route checkpoints.
- Threat Detection:Algorithm-driven anomaly identification spanning liquid explosives, non-metallic weapons, and improvised explosive device components, with EASA Common Evaluation Process updates mandating training data documentation and bias testing protocols.
Passenger Screening dominates deployment. Threat Detection applications are climbing the fastest.
Deployment:
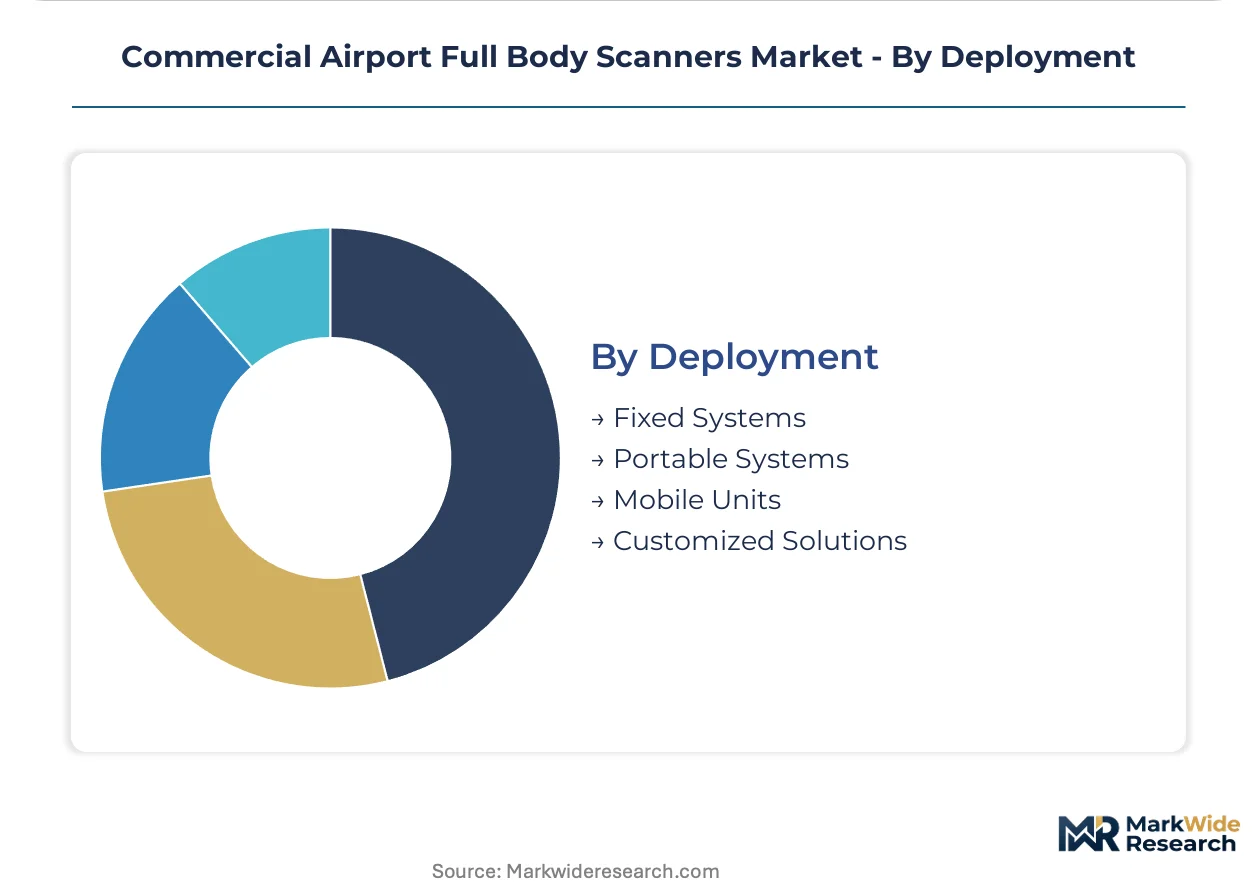
Physical configuration flexibility determines capital recovery profiles, with fixed infrastructure requiring structural reinforcement and mobile units enabling rapid reconfiguration during peak travel periods.
- Fixed Systems:Permanent foundation-mounted installations at primary checkpoint lanes, requiring structural reinforcement and power distribution upgrades incompatible with 1990s terminal electrical specifications. By volume, Fixed Systems lead. By growth pace, Mobile Units are ahead.
- Portable Systems:Rapidly relocatable units without dedicated foundations, deployed for temporary terminal expansions and seasonal tourism surges.
- Mobile Units:Trailer-mounted configurations enabling complete checkpoint relocation within hours, addressing event-driven passenger volume spikes and construction-related lane closures.
- Customized Solutions:Purpose-engineered installations for unique terminal geometries or integrated facility management contracts spanning entire security checkpoints.
Fixed Systems anchor procurement volume. Mobile Units show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports millimeter wave scanner components to North American and European integrators, while the United States ships certified detection platforms to allied aviation authorities. Germany and the Netherlands supply precision RF engineering to Middle Eastern hub operators. India sources complete systems from multiple origins for its greenfield terminal construction.
United States
TSA mandates at Category X airports drive replacement of legacy metal detection portals with automated threat recognition systems. FAA certification standards under the Screening Partnership Program filter non-compliant vendors from federal procurement shortlists. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor demand concentration as the nation's busiest passenger hubs expand checkpoint capacity.
Germany
Frankfurt and Munich airports deploy passive millimeter wave units at primary screening positions to eliminate secondary inspection bottlenecks. EASA Common Evaluation Process protocols mandate training data documentation for algorithm updates, extending validation timelines. Bavaria's RF engineering cluster supplies antenna design expertise to European scanner manufacturers.
China
Domestic airport construction at Beijing Daxing and Chengdu Tianfu generates procurement for throughput-optimized screening equipment. The national aviation regulator enforces detection performance standards aligned with ICAO guidelines. Shenzhen and Shanghai manufacturing bases concentrate gallium arsenide foundry capacity for millimeter wave transceiver modules.
India
Greenfield terminals at Delhi, Mumbai, and Bangalore bypass legacy infrastructure constraints entirely. Bureau of Civil Aviation Security directives mandate non-invasive screening compliance for all international gateway airports. The Delhi-NCR corridor concentrates demand as the nation's primary aviation hub undergoes phased expansion through 2030.
United Arab Emirates
Dubai International and Hamad International negotiate performance-based service agreements transferring equipment ownership risk to vendors. The General Civil Aviation Authority coordinates adoption of EU-equivalent detection standards for transit passenger screening. Abu Dhabi's integrated facility management contracts span entire security checkpoints, bundling hardware with continuous software validation.
Commercial Airport Full Body Scanners Market Competitive Environment
On the supply side, the industry is consolidating around vendors with established regulatory certification portfolios and recurring service revenue streams. Tier-one positions concentrate at defense-electronics conglomerates with TSA and EASA pre-qualifications. Three archetypes dominate: integrated security contractors absorbing equipment ownership risk, RF engineering specialists supplying subsystems to prime integrators, and state-affiliated manufacturers serving protected domestic markets. Competitive dynamics center on strategic partnerships for algorithm development and geographic expansion through local assembly licensing.
Among North American defense-electronics conglomerates, L3Harris Technologies and Leidos occupy positions anchored by federal procurement relationships. European specialists including Smiths Detection and Thales Group exemplify the integrated security contractor archetype through service-based revenue models. Rohde & Schwarz represents the RF engineering specialist tier, supplying precision measurement and signal processing capabilities to broader system integrators. Nuctech Company Limited anchors the state-affiliated manufacturer category, leveraging scale economics for emerging market penetration.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Nuctech Company Limited |
| Smiths Detection |
| ODSecurity |
| LINEV Systems |
| Leidos |
| Rohde & Schwarz |
| Thales Group |
| Rapiscan Systems |
| Others |
Value Chain & Pricing Dynamics
Gallium arsenide foundry capacity concentrated in Shenzhen and Shanghai manufacturing clusters funnels pricing power toward millimeter wave transceiver suppliers, compressing margins for scanner integrators downstream while algorithm-dependent service contracts capture recurring revenue pools from airport operators.
Pricing Analysis
Current-generation millimeter wave scanners with automated threat recognition command premium positioning against prior-generation units requiring human image review, while next-generation passive imaging systems are entering pilot pricing. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates TSA-approved deployments from emerging market installations. Cost compression in economy-tier hardware is intensifying because Nuctech's manufacturing scale in China feeds price competition across Africa and Latin America. Security firms operating under performance-based service agreements show highest price sensitivity, while federalized airports in the United States demonstrate lowest sensitivity due to mandate-driven procurement timelines.
Supply Chain Analysis
Extended payment terms from 90 to 180 days are becoming standard for airport procurement departments, with supply-chain finance facilities emerging as a vendor working-capital bridge. Millimeter wave scanner production draws from China, Germany, and the United States for critical subsystems, with gallium arsenide substrates, precision antenna arrays, and FPGA signal processors anchoring component bills of materials. Single-source vulnerability in East Asian gallium arsenide foundry capacity exposes lead times to geopolitical friction. Distribution runs through direct OEM relationships with major hub authorities, supplemented by regional integrators serving secondary airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large hub authorities negotiating performance-based service agreements, fragmenting procurement decisions away from traditional capital-budget cycles toward integrated facility management contracts spanning entire security checkpoints.
For Market Incumbents: Harden algorithm transparency documentation to preempt EASA Common Evaluation Process exclusion, while securing captive supply of gallium arsenide transceiver modules through backward integration into Chinese or German RF component suppliers. Passive millimeter wave imaging from European specialists threatens displacement of active-array architectures, making machine learning audit trails and training data archives essential defensive assets.
For New Entrants and Emerging Players: Mobile and portable deployment configurations for seasonal tourism destinations and temporary terminal expansions represent the most penetrable entry point, with trailer-mounted units bypassing fixed-infrastructure procurement complexity. Southeast Asian greenfield airports in Vietnam and Indonesia offer second-mover advantage through integrated checkpoint design without legacy retrofit constraints. A hardware-as-a-service go-to-market angle aligns with shifting buyer preference toward vendor-retained ownership models.
For Investors and Strategic Acquirers: Capital is best deployed toward RF engineering specialists with established TSA or EASA pre-qualifications and recurring service revenue exceeding 40 percent of total sales, as regulatory certification portfolios create durable competitive moats. The signal to watch is EASA algorithmic accountability rule implementation timing, which will accelerate consolidation around vendors with transparent machine learning architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Transparency Documentation | EASA Common Evaluation Process updates mandate training data archives for automated threat recognition certification. |
| Performance-Based Service Agreements | Dubai International and Hamad International contracts transfer equipment obsolescence risk to vendors. |
| Passive Millimeter Wave Deployment | Frankfurt and Amsterdam Schiphol installations eliminate secondary screening bottlenecks at primary lanes. |
| Mobile Configuration Development | Trailer-mounted units address event-driven passenger surges at seasonal tourism destinations. |
| Gallium Arsenide Supply Securement | East Asian foundry concentration creates single-source vulnerability for millimeter wave transceiver modules. |
Study Parameters
The analysis maps millimeter wave, backscatter, and passive imaging sub-sectors, each validated through airport procurement directors, TSA certification officers, RF engineering specialists, and security firm operations executives. Primary interviews with checkpoint design consultants and secondary validation against FAA Screening Partnership Program filings, EASA Common Evaluation Process protocols, ICAO security guidelines, and customs trade data for scanner component shipments anchored supply-side triangulation. Bottom-up unit deployment tracking across 45 countries converged with top-down aviation security spending estimates.
Assumptions held fixed include TSA mandate continuity at Category X airports and EASA algorithmic transparency rule implementation, while variables included India greenfield terminal construction pace and gallium arsenide supply chain stability. The projection horizon spans technology generation transitions, deployment configuration shifts, and end-user budget authority fragmentation. CAGRs derived from logistic diffusion modeling of scanner replacement cycles and infrastructure expansion pipelines, with passenger throughput optimization requirements and regulatory recertification timelines as primary forecast inputs.
Practitioners should monitor EASA Common Evaluation Process timeline extensions and India Bureau of Civil Aviation Security directive amendments for early signals of demand acceleration or deceleration. Forecasts reflect these documented assumptions; geopolitical disruption to East Asian semiconductor supply, abrupt regulatory reversal on automated threat recognition, or macroeconomic contraction in aviation passenger volumes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Parabolic Flight Tourism Market
Aerospace & Defense
Global Aircraft Enclosures Market
Aerospace & Defense
Germany Space Electronics Market
Aerospace & Defense
Military Radar Systems Market
Aerospace & Defense
Cluster Munitions Market
Aerospace & Defense
Unmanned Combat Aerial Vehicle Market
Aerospace & Defense
Asia-Pacific Airborne Fire Control Radar Market
Aerospace & Defense
Aerospace and Defense C-Class Parts Market
Aerospace & Defense
Global Non Lethal Biochemical Weapon Market
Aerospace & Defense
Passenger Drones Market
Aerospace & Defense
Sonobuoy Launcher Market
Aerospace & Defense
Aircraft Seat Frames Market
Aerospace & Defense
Jet Bridge Market
Aerospace & Defense
Rescue Hoist System Market
Aerospace & Defense
Global Air Traffic Control Equipment Market
Aerospace & Defense
Asia-Pacific Aircraft Manufacturing Market