
 Commercial Aircraft Cabin Seating Market | 2026-2036
Commercial Aircraft Cabin Seating Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Cabin Seating Market Outlook
Modular seat platforms is hardening as the dominant configuration pattern across narrowbody and widebody programs. Collins Aerospace leverages backward integration into composite frame production to control lead times on business-class platforms. Recaro Aircraft Seating anchors its position through R&D intensity in lightweight economy structures for single-aisle fleets. Safran competes by extending its avionics-seating bundled offerings into premium economy segments.
Commercial aircraft cabin seating encompasses passenger accommodation systems engineered to crashworthiness, flammability, and ergonomic standards, typically incorporating aluminum or composite frames, fire-blocking foam cushions, and thermoplastic or leather dress covers rated to 16g dynamic load and HIC injury criteria. The equipment serves to maximize certified passenger capacity while satisfying crew evacuation timing and passenger comfort metrics under Part 25/CS-25 airworthiness rules. Business class and premium economy configurations capture disproportionate margin pools as airlines prioritize ancillary revenue per available seat mile. Economy class remains the volume anchor, though high-density layouts face growing scrutiny from EASA and FAA on minimum seat dimensions and emergency egress compliance.
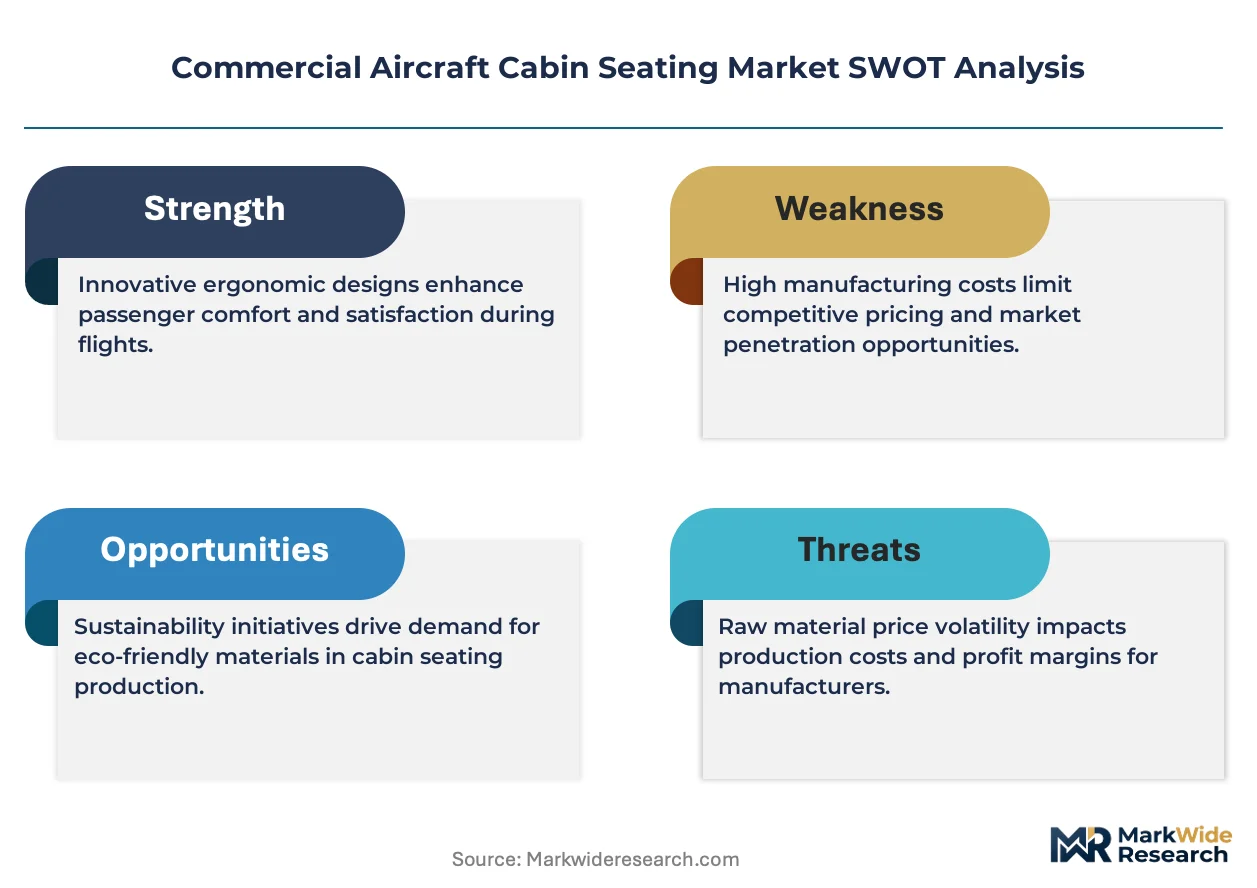
FAA Part 25.562 dynamic testing requirements and EASA CS-25 flammability protocols shape material selection and design validation cycles, directly extending development timelines and certification costs for new seat programs. China's CAAC harmonizes with these standards while adding domestic GB certification layers for COMAC C919 supplier qualification. Stakeholders must monitor evolving minimum-seat-pitch regulatory proposals in the US Congress and EU Parliament, as these would force structural redesigns across installed narrowbody fleets.
Market Dynamics
Modular seat platforms are compressing product development cycles while FAA and EASA flammability standards force material requalification across narrowbody and widebody programs. Airlines now demand platform flexibility that accommodates rapid cabin reconfigurations between premium and economy densities.
Growth Catalysts
- FAA Part 25.562 dynamic testing:Certification harmonization between FAA and EASA reduces duplicate testing costs for suppliers serving dual-approval markets, accelerating program launches.
- Southeast Asian low-cost carrier expansion:Fleet renewal programs across Indonesia, Vietnam, and the Philippines generate concentrated demand for lightweight economy-class seating.
- Composite frame adoption:Carbon fiber-reinforced thermoplastics cut seat weight by 15-20% versus aluminum, enabling payload-driven fuel savings that justify premium pricing.
Market Restraints
- Titanium and aluminum input volatility:Aerospace-grade metal pricing swings compress margins on frame production, particularly for mid-tier suppliers without long-term supply agreements.
- Certification timeline extension:EASA's evolving flammability protocols for thermoplastic dress covers add 8-12 months to qualification schedules, freezing working capital in development.
- Recaro and Collins duopoly concentration:Combined control of 60%+ installed base creates procurement leverage that squeezes second-tier competitors on aftermarket parts pricing.
Strategic Opportunities
- China COMAC C919 supply chain entry:CAAC's GB certification layer creates a protected domestic supplier ecosystem for seats on indigenous narrowbody programs.
- Premium economy segment expansion:Hybrid density configurations between business and economy capture ancillary revenue growth without full lie-flat complexity.
- Digital thread integration:Convergence of CAD-PLM systems with IoT-enabled seat health monitoring enables predictive MRO scheduling and unbundled service contracts.
Industry Challenges
- 16g dynamic load engineering talent scarcity:Crashworthiness simulation expertise concentrates at Collins, Recaro, and Safran, limiting supplier base expansion.
- Legacy fleet retrofit complexity:FAA's proposed minimum seat pitch rules would force structural rail modifications on thousands of installed narrowbody aircraft.
- Dual certification cost burden:Simultaneous FAA-EASA validation requires parallel test article builds, doubling qualification capital for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Cabin Seating Market |
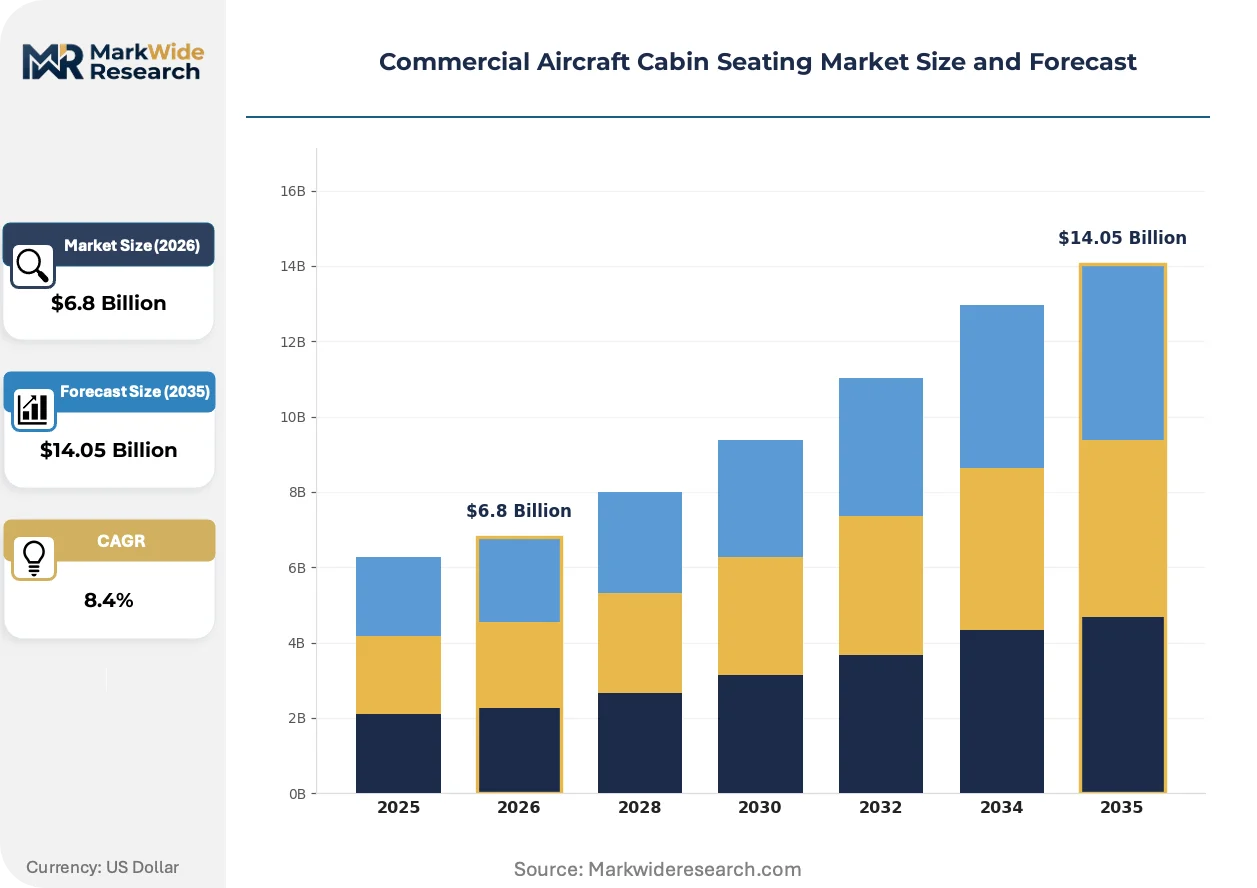
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Economy Class, Business Class, First Class, Premium Economy Material: Leather, Fabric, Synthetic, Foam Configuration: Single Aisle, Twin Aisle, High Density, Suite End User: Commercial Airlines, Charter Services, Leasing Companies, Cargo Airlines |
| Companies Covered | Stelia Aerospace, Panasonic Avionics Corporation, Collins Aerospace, Diehl Aviation, JAMCO Corporation, Safran, Thompson Aero Seating, Geven S.p.A, Recaro Aircraft Seating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Cabin Seating Market Strategic Shifts
Seat architecture is fragmenting into interchangeable modules that airlines reconfigure overnight. This shift demands new supplier capabilities in rapid-change hardware and software-integrated cabin management systems.
Modular platform technology is modularizing seat design into standardized rail-mounted units with swappable cushions, armrests, and IFE housings. Full-service carriers in Europe and Asia-Pacific now specify 4-hour changeover capability for seasonal density adjustments. This architecture compresses supplier SKU proliferation while enabling airline fleet utilization gains through cabin flexibility.
EASA's tightened CS-25 flammability protocols for thermoplastic components are disqualifying legacy foam formulations from new programs. Suppliers must reformulate fire-blocking layers and resubmit to 12-second vertical burn testing, extending development timelines. Widebody premium cabins face the steepest compliance costs due to complex dress cover geometries and integrated electrical systems.
Airline procurement teams are consolidating seat buys into platform-level contracts spanning 10-15 year fleet horizons, displacing transactional per-aircraft purchasing. Low-cost carriers in Southeast Asia pioneered this shift, and full-service networks in Germany and Japan are adopting similar frameworks. This concentrates supplier relationships around lifecycle cost guarantees rather than unit price competition.
Commercial Aircraft Cabin Seating Market Segmentation
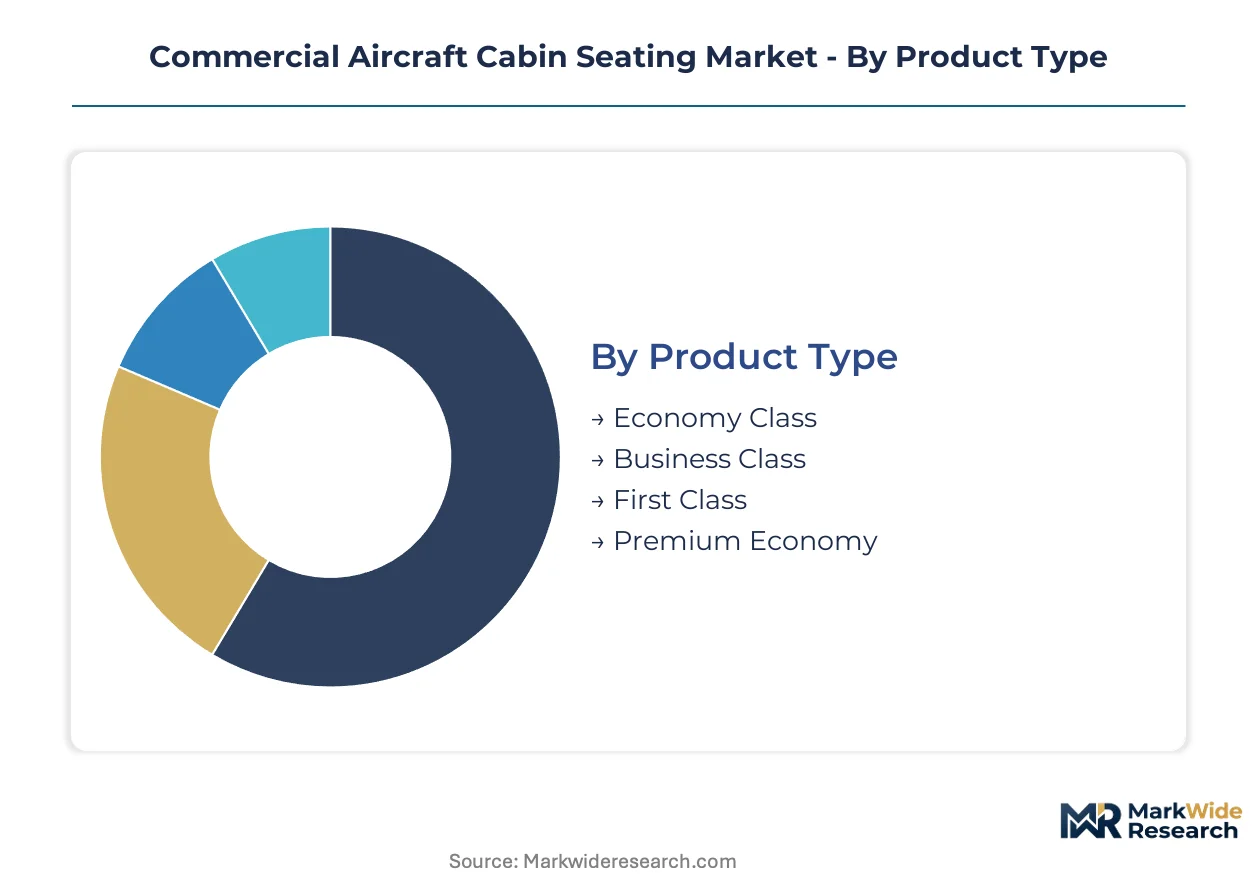
Segmentation in aircraft seating determines certification pathways, material selection, and supplier relationships. Each dimension carries distinct regulatory burdens and margin profiles that shape competitive positioning across the value chain.
Product Type:
Economy Class seats require FAA Part 25.562 and EASA CS-25 certification for 16g dynamic loads, while premium configurations face additional flammability testing for integrated electrical systems. Certification intensity scales directly with complexity and unit value.
- Economy Class:Aluminum or composite frames with fire-blocking foam cushions rated to basic 16g standards. Demand concentrates in Southeast Asian low-cost carrier fleet renewals where lightweight structures drive fuel savings on high-cycle narrowbody operations.
- Business Class:Lie-flat mechanisms and composite shells demand extended EASA flammability validation for thermoplastic dress covers and embedded IFE. Procurement concentrates with full-service carriers in Germany and Japan seeking ancillary revenue per available seat mile through premium density.
- First Class:Suite configurations with sliding doors and personal storage require bespoke structural certification beyond standard seat frames.
- Premium Economy:Hybrid density with recline mechanisms and increased pitch occupies the fastest-expanding cabin zone between economy and business.
Leading the category by volume: Economy Class. Growing fastest: Premium Economy.
Material:
Material selection hinges on EASA CS-25 flammability protocols and airline brand differentiation strategies. Each substrate carries distinct supply chain risks and reformulation timelines.
- Leather:Full-grain hides from European tanneries meet premium cabin aesthetic requirements. Demand anchors in Gulf carrier and East Asian full-service fleet specifications where brand positioning justifies maintenance-intensive natural materials.
- Fabric:Woven synthetics with fire-blocking back-coatings dominate economy applications. Procurement concentrates with low-cost carriers prioritizing durability and cleaning cycles over tactile quality.
- Synthetic:Polyurethane and vinyl formulations face EASA reformulation mandates as legacy thermoplastics fail revised vertical burn testing.
- Foam:Fire-blocking layers integrated into cushion cores require requalification under tightened CS-25 protocols, extending supplier development cycles.
Volume leader: Fabric. Steepest expansion trajectory: Synthetic as reformulation investments mature.
Configuration:
Configuration determines rail system compatibility, evacuation timing compliance, and modular reconfiguration capability. Structural standards vary by fuselage width and exit row proximity.
- Single Aisle:Narrowbody layouts at 28-32 inch pitch face scrutiny from proposed FAA minimum dimension rules. Demand concentrates in China's COMAC C919 supply chain and Indonesian low-cost carrier expansion programs.
- Twin Aisle:Widebody platforms accommodate complex premium geometries with staggered seating and direct aisle access. Procurement anchors with flag carriers in Japan and Germany operating long-haul hub networks.
- High Density:28-inch pitch configurations on single-aisle aircraft test regulatory limits on emergency egress timing.
- Suite:Enclosed first-class pods with closing doors require supplemental type certification for structural integration.
Dominant by installed base: Single Aisle. Climbing fastest: Suite configurations in Middle East carrier fleets.
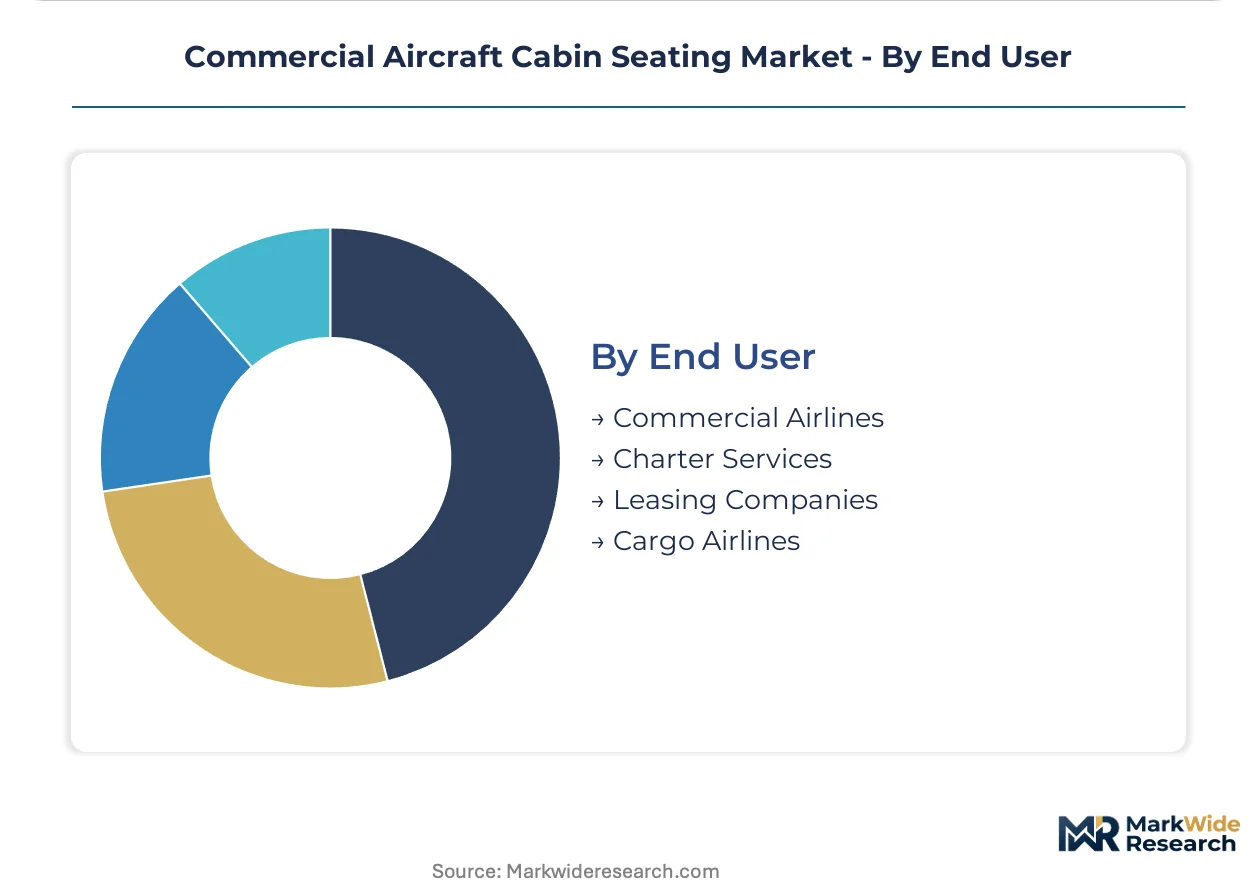
End User:
End-user category shapes procurement contracting structures, from lifecycle platform agreements to transactional per-aircraft purchases. Each segment carries distinct credit risk and specification authority.
- Commercial Airlines:Full-service and low-cost operators consolidate seat buys into 10-15 year platform contracts with lifecycle cost guarantees. Demand concentrates with Southeast Asian LCCs and European network carriers pursuing cabin flexibility.
- Charter Services:Seasonal operators and tour package carriers specify rapid-reconfiguration modular platforms for density adjustments between summer and winter schedules.
- Leasing Companies:Aircraft lessors demand certification transferability across lessee airlines, constraining supplier selection to platforms with broad operational approval.
- Cargo Airlines:Quick-change combi configurations and passenger-to-freighter conversions require seat tracks certified for both occupant and container loading.
Procurement volume leader: Commercial Airlines. Fastest contract structure evolution: Leasing Companies as lessors consolidate fleet standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Western Europe and North America while demand accelerates across Asia-Pacific fleet renewal programs. China builds indigenous certification capacity through CAAC's GB standards. Southeast Asian low-cost carriers drive volume procurement for narrowbody configurations.
United States
FAA Part 25.562 dynamic testing requirements shape supplier qualification timelines for domestic narrowbody programs. The agency's proposed minimum seat pitch rules threaten retrofit mandates across thousands of installed aircraft. Wichita, Kansas hosts concentrated aerospace manufacturing clusters where seat frame fabricators serve Boeing's commercial programs.
China
COMAC C919 supply chain localization creates protected demand for domestic seat suppliers meeting CAAC GB certification layers. The country's dual carbon goals pressure airlines toward lightweight composite structures. MRO corridors around Guangzhou and Tianjin concentrate seat refurbishment capacity for Asia-Pacific carrier fleets.
Germany
EASA CS-25 flammability protocols drive material requalification costs for suppliers serving European full-service carriers. The country's national aviation regulator maintains harmonized standards with FAA while adding EU-specific environmental compliance layers. Hamburg anchors premium cabin engineering clusters where business-class seat development concentrates.
Japan
Full-service carriers operating long-haul hub networks generate sustained demand for lie-flat business-class configurations. METI industrial policy supports domestic supplier participation in international joint development programs. The Kansai region around Osaka hosts specialized manufacturing facilities serving both commercial aviation and rail seating markets.
Indonesia
Lion Air Group and Garuda Indonesia fleet expansion programs concentrate Southeast Asian demand for high-density economy seating. The country's national aviation regulator aligns certification requirements with EASA standards to facilitate European route access. Jakarta-based MRO facilities develop seat overhaul capabilities serving regional low-cost carrier networks.
Commercial Aircraft Cabin Seating Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Tier-one suppliers control premium segments through captive composite production and bundled avionics integration. Mid-tier competitors survive on aftermarket parts and regional certification specialization. Consolidation pressure intensifies as airlines consolidate procurement into decade-long platform contracts. Vertical integration into frame manufacturing represents the dominant defensive maneuver.
Among European-based specialists, Stelia Aerospace and Geven S.p.A occupy positions within the premium cabin tier. Recaro Aircraft Seating exemplifies the focused pure-play archetype through concentrated investment in lightweight economy structures. These three companies represent distinct strategic postures: diversified aerospace conglomerate, regional Italian fabricator, and German engineering specialist.
| Leading Market Players |
|---|
| Stelia Aerospace |
| Panasonic Avionics Corporation |
| Collins Aerospace |
| Diehl Aviation |
| JAMCO Corporation |
| Safran |
| Thompson Aero Seating |
| Geven S.p.A |
| Recaro Aircraft Seating |
| Others |
Value Chain & Pricing Dynamics
Composite frame adoption is compressing unit economics while concentrating procurement leverage among tier-one suppliers with captive carbon fiber-reinforced thermoplastic production. This manufacturing transition simultaneously elevates entry barriers for mid-tier competitors and reshapes airline contract negotiations toward lifecycle cost guarantees rather than transactional per-seat pricing.
Pricing Analysis
Cost-down pressure on economy-class platforms accelerates because Southeast Asian low-cost carriers consolidate fleet-wide procurement into decade-long platform agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity and after-sales service bundling. Margin tightening traces to titanium and aluminum input volatility squeezing frame fabricators without long-term supply agreements. Low-cost carriers exhibit acute price sensitivity; full-service networks prioritize cabin flexibility over unit cost.
Supply Chain Analysis
Freight costs for aerospace-grade composite prepregs and fire-blocking foam formulations are elevating landed costs for European seat assemblers sourcing from Asian chemical suppliers. Manufacturing gravity centers on Germany, the United States, and China, with Hamburg and Wichita anchoring premium engineering clusters. Raw material dependencies rest on carbon fiber from Japan, aluminum from Russia and China, and specialized thermoplastics from South Korea. Single-source vulnerability concentrates in fire-blocking layer formulations facing EASA requalification mandates. Distribution runs through airframer-integrated procurement portals and lessor fleet standardization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over composite frame production and flammability-certified foam supply determines pricing power and program win rates.
For Market Incumbents: Extend platform-level contracting structures to lock out second-tier competitors from aftermarket parts revenue streams. Collins Aerospace and Recaro's duopoly control of 60% installed base creates procurement leverage that mid-tier suppliers cannot match without EASA CS-25 certification investment. Backward integration into carbon fiber-reinforced thermoplastic production secures lead time advantages as airlines demand 4-hour cabin reconfiguration capability. For New Entrants and Emerging Players: The premium economy-to-business price-point gap offers white-space entry for hybrid density configurations without full lie-flat complexity. China's COMAC C919 supply chain presents the most penetrable geography given CAAC's GB certification layer protecting domestic suppliers. Target aftermarket refurbishment corridors around Guangzhou and Tianjin with flammability-requalified foam cushion replacement programs. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play seating specialists possessing EASA-FAA dual certification and IoT-enabled predictive MRO capabilities given airline procurement consolidation into lifecycle contracts. Long-term viability hinges on digital thread integration converging CAD-PLM systems with seat health monitoring. Watch EASA's evolving minimum seat dimension proposals as the inflection signal forcing structural redesigns across installed narrowbody fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Frame Production | Captive carbon fiber-reinforced thermoplastic supply cuts lead times for Collins Aerospace business-class platforms. |
| EASA-FAA Dual Certification Investment | Harmonized validation reduces duplicate testing costs for suppliers serving Boeing and Airbus dual-approval markets. |
| Digital Thread Integration with IoT Monitoring | Converged CAD-PLM systems enable predictive MRO scheduling and unbundled service contracts for airline customers. |
| CAAC GB Certification for COMAC Supply Chain | Protected domestic supplier ecosystem locks out Western competitors from China's indigenous narrowbody programs. |
| Premium Economy Segment Expansion | Hybrid density configurations capture ancillary revenue growth without full lie-flat engineering complexity. |
Study Parameters
Independent corroboration across seat program managers at tier-one suppliers, airline procurement executives, and MRO facility directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with aftermarket parts specialists and flammability testing laboratory personnel. Secondary validation drew from FAA Part 25.562 certification databases, EASA CS-25 amendment tracking, and COMAC C919 supplier qualification records. Bottom-up build-ups across product type, material, configuration, and end-user segments were triangulated against top-down airframer delivery forecasts.
Comparable-period anchoring to historical narrowbody and widebody delivery cycles established the forecast baseline across the projection horizon. The analytical framework modeled segmentation dimensions including seat class tier, frame material substrate, fuselage configuration, and procurement contracting structure. CAGRs were derived from airframe production rates, fleet renewal schedules, and regulatory-driven retrofit mandates. Industry-specific inputs incorporated EASA flammability protocol evolution timelines and CAAC harmonization progress with FAA standards.
Inputs from airline procurement databases and seat supplier order backlogs were available through the study window; gaps in emerging market MRO capacity data introduce uncertainty bands around refurbishment revenue projections. Forecasts reflect documented assumptions regarding regulatory timeline adherence and airframer production rate achievement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market