
 UAV Market | 2026-2036
UAV Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Market Outlook
FAA Part 107 is decoupling commercial UAV operations from manned aviation licensing burdens, lowering capital barriers for service providers. SZ DJI Technology Co., Ltd leverages its Shenzhen manufacturing base to dominate consumer and prosumer camera drone shipments. General Atomics Aeronautical Systems anchors the large fixed-wing military segment with its Predator-series platforms. Northrop Grumman Corporation competes in the high-altitude endurance category through its Global Hawk family.
An unmanned aerial vehicle is a pilotless aircraft system comprising an airframe, propulsion unit, flight control computer, and data link operating via radio frequency or satellite communication, typically weighing from grams to multiple tons depending on mission profile; its primary purpose spans reconnaissance, payload delivery, precision agriculture, infrastructure inspection, and geographic mapping. Rotary-wing configurations sustain the largest volume share due to vertical takeoff flexibility in confined environments, while hybrid architectures are gaining traction where extended range combines with hover precision. Artificial Intelligence integration in flight autonomy differentiates premium platforms from GPS-dependent baseline systems, concentrating margin pools in real-time decision-making subsystems.
The FAA governs US airspace access through Part 107 and emerging beyond-visual-line-of-sight rulemaking, while EASA's EU drone regulation harmonizes category-based certification across European member states and China's CAAC mandates airworthiness standards for domestic manufacturers. These frameworks shape product design requirements, operator training obligations, and cross-border market access conditions. Stakeholders must monitor evolving detect-and-avoid mandates and spectrum allocation decisions for command-and-control links.
Market Dynamics
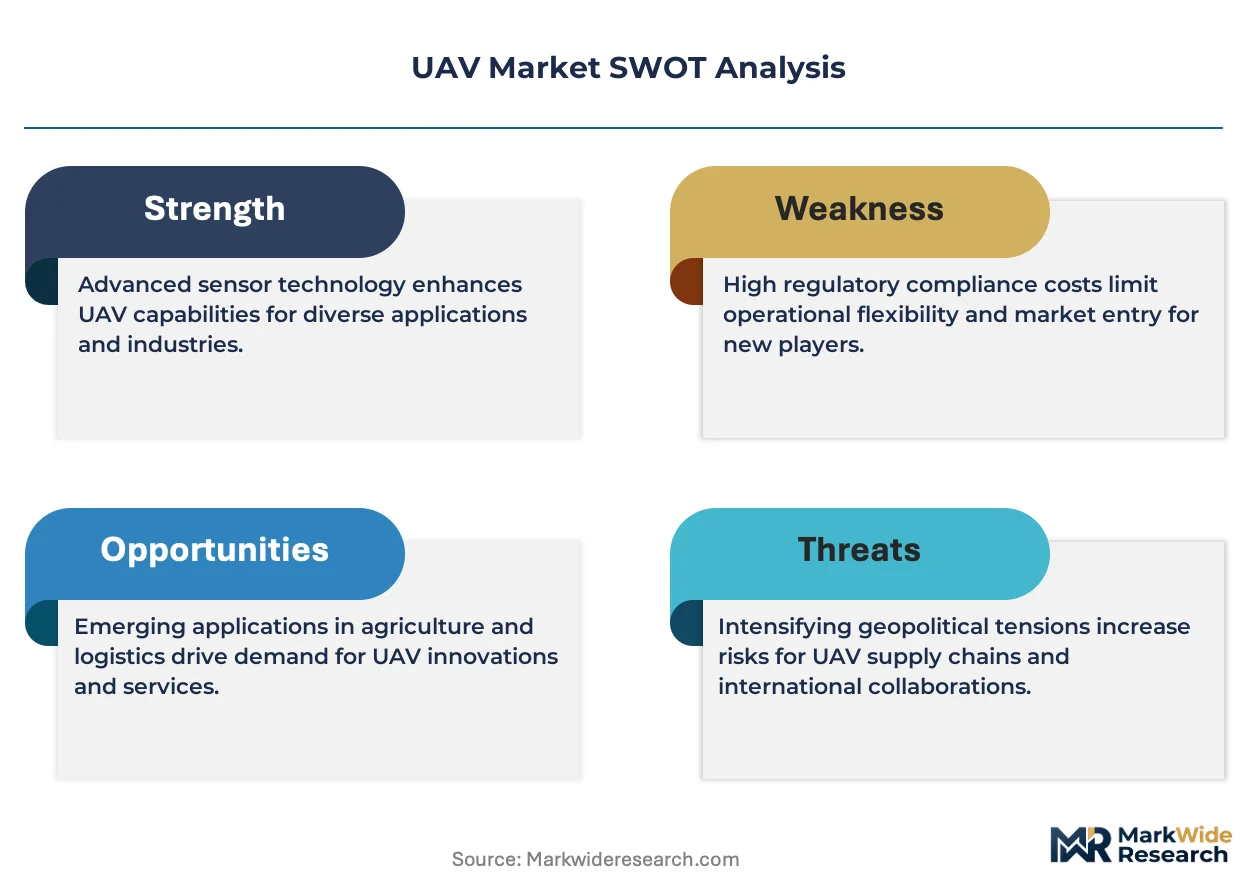
The UAV market is compressing around autonomous decision-making capabilities, where artificial intelligence integration is separating premium platforms from GPS-dependent baseline systems and redistributing margin pools toward real-time flight autonomy subsystems.
Growth Catalysts
- Part 107 Certification Framework:The FAA's remote pilot standardization in the United States is lowering capital barriers for commercial service providers by decoupling UAV operations from manned aviation licensing burdens.
- Precision Agriculture Expansion:Brazilian crop monitoring operations are accelerating fleet deployments for soil analysis and yield optimization across soybean and sugarcane belts.
- AI-Enabled Flight Autonomy:Real-time obstacle avoidance and mission replanning algorithms are differentiating platform tiers and expanding addressable use cases beyond line-of-sight constraints.
Market Restraints
- Detect-and-Avoid Mandates:Pending FAA rulemaking for beyond-visual-line-of-sight operations is creating certification uncertainty and extending product development timelines for commercial entrants.
- Spectrum Allocation Constraints:Command-and-control link congestion in C-band and L-band frequencies is limiting simultaneous airspace density in urban corridors.
- LiDAR Sensor Cost Structure:High-precision mapping payloads remain cost-prohibitive for small-scale agricultural operators, constraining adoption in developing markets.
Strategic Opportunities
- Turkish Defense Procurement:Combat-proven platform validation is reshaping regional military UAV acquisition patterns across Eastern Mediterranean and Central Asian markets.
- EU Drone Regulation Harmonization:EASA's category-based certification framework is creating standardized market access conditions across 27 member states for compliant manufacturers.
- Battery-Electric Range Extension:Solid-state energy density improvements are converging with hydrogen fuel cell prototypes to unlock long-endurance civilian applications.
Industry Challenges
- Embedded Systems Talent Scarcity:Flight control firmware engineering expertise concentrates in Shenzhen and Tel Aviv clusters, creating recruitment bottlenecks for Western OEMs.
- Type Certification Timelines:CAAC airworthiness validation protocols in China are extending market entry schedules for foreign platform developers by 18-24 months.
- Legacy System Integration:Military customers are demanding STANAG 4586 interoperability with existing ground control stations, complicating clean-sheet platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Market |
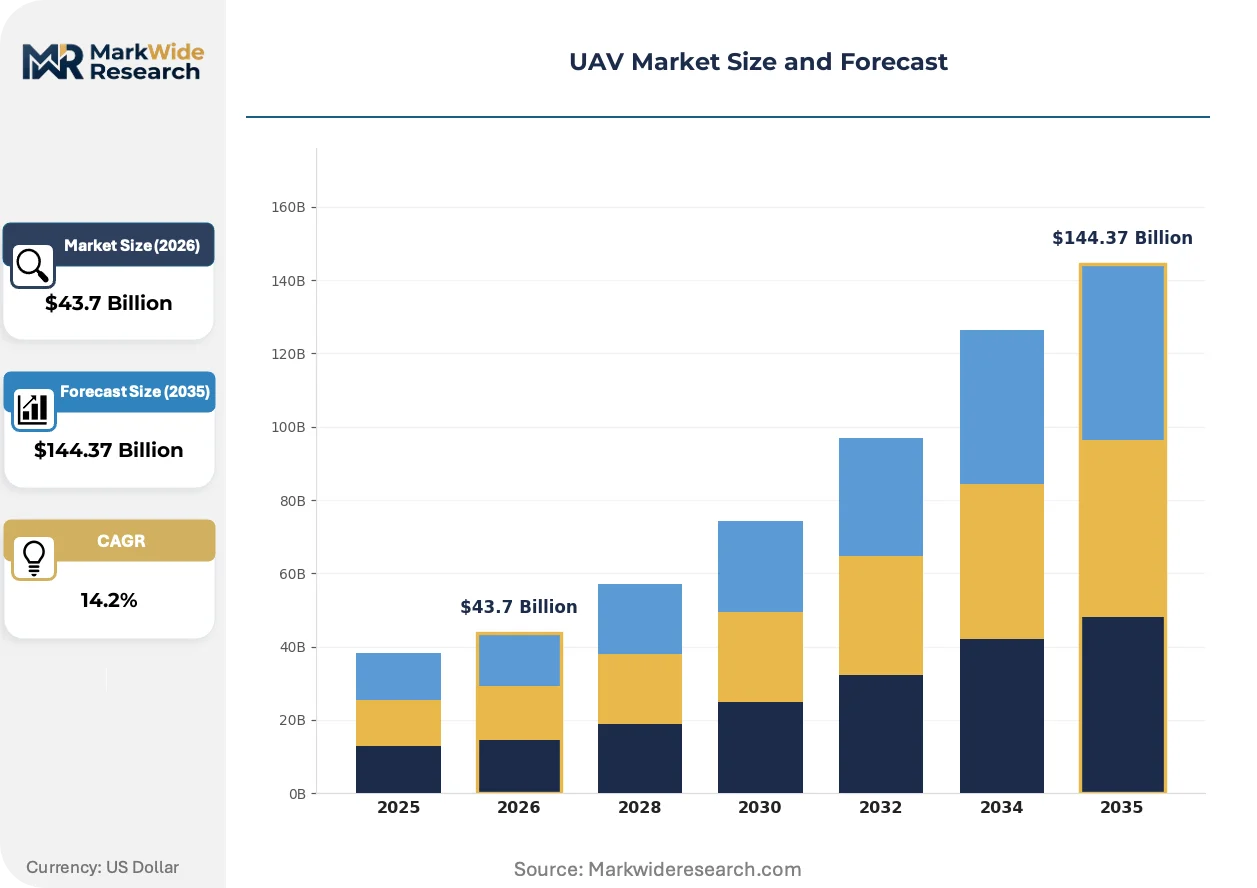
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $144.37 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Nano Application: Agriculture, Surveillance, Delivery, Mapping End User: Military, Commercial, Civil, Law Enforcement Technology: GPS, Computer Vision, Artificial Intelligence, IoT |
| Companies Covered | SZ DJI Technology Co., Ltd, General Atomics Aeronautical Systems, Northrop Grumman Corporation, AeroVironment, Inc., Lockheed Martin Corporation, Teledyne FLIR LLC, Israel Aerospace Industries Ltd., Baykar A.S., Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Market Strategic Shifts
Edge computing architectures are migrating flight intelligence from ground stations to onboard processors, compressing latency windows and enabling autonomous operations in contested electromagnetic environments.
Swarm coordination protocols are decentralizing mission execution across multiple small UAVs operating without continuous human oversight. Agricultural cooperatives in the Netherlands are piloting 50-unit fleets for synchronized crop spraying. This topology is compressing per-acre operational costs while redistributing platform specifications toward miniaturized, disposable airframes.
EASA's specific category framework for higher-risk operations is mandating design verification against quantitative safety objectives. Industrial inspection service providers are restructuring training programs around the new competency requirements. Heavy-lift cargo platforms above 25 kilograms are experiencing the steepest compliance cost increases.
Asset-as-a-service contracting is displacing capital purchase models among infrastructure inspection buyers. European utility operators are unbundling hardware ownership from flight-hour subscriptions. Germany's transmission grid sector is exhibiting the fastest contract structure migration, driven by regulatory pressure for standardized audit trails.
UAV Market Segmentation
UAV procurement decisions hinge on mission endurance, payload flexibility, and regulatory compliance thresholds. Segment boundaries are blurring as hybrid architectures and AI integration reshape platform specifications across military and civilian applications.
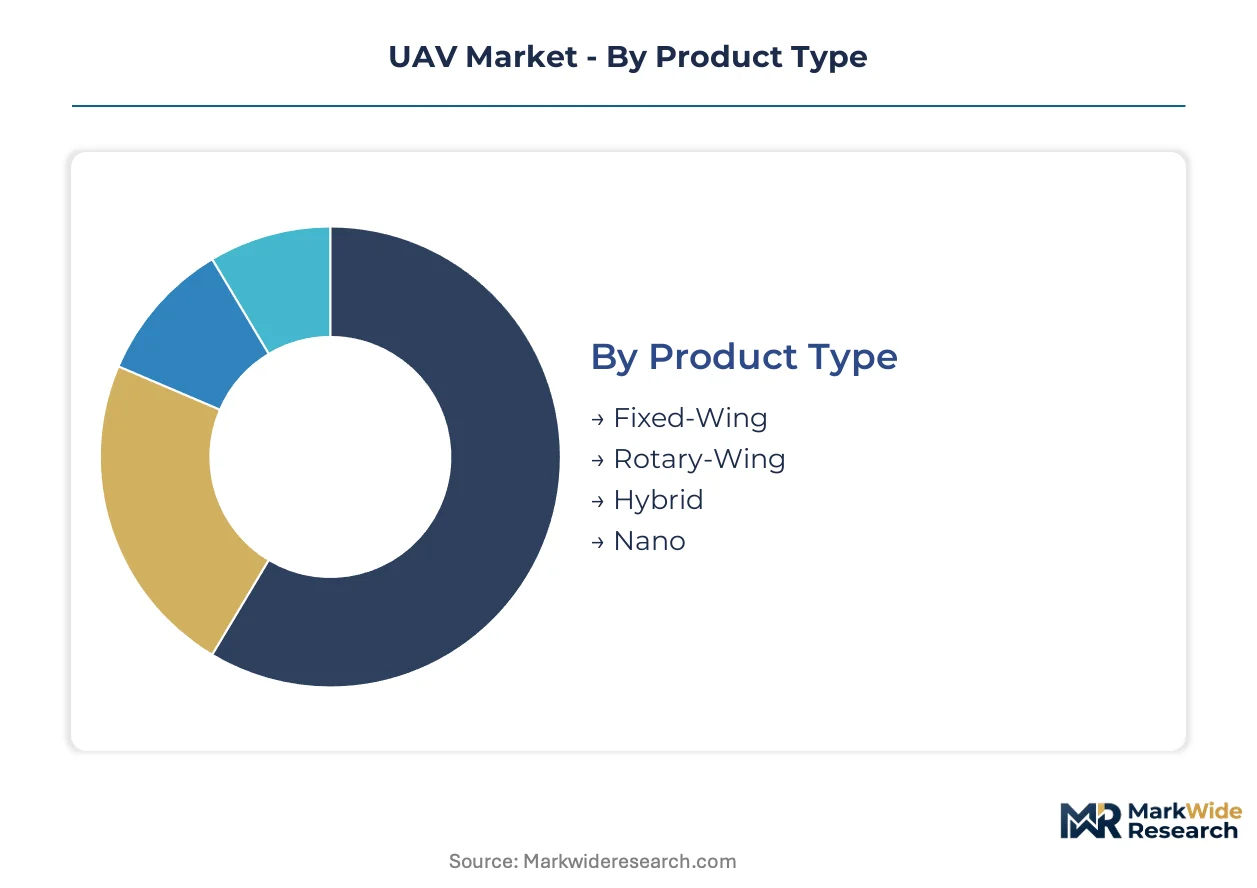
Product Type:
Buyers prioritize takeoff geometry and range trade-offs when selecting airframe configurations for specific operational envelopes.
- Fixed-Wing:These platforms maximize fuel efficiency through aerodynamic lift surfaces, enabling multi-hour endurance for corridor surveillance and geographic mapping missions. Demand concentrates with military operators in Turkey and the United States seeking extended-range intelligence collection, though runway dependency limits deployment flexibility in contested or austere environments.
- Rotary-Wing:Vertical takeoff and landing capability dominates volume share by eliminating infrastructure requirements; multirotor designs from Shenzhen manufacturers serve precision agriculture in Brazil and infrastructure inspection across European utility networks where hover stability enables close-proximity sensor positioning.
- Hybrid:Tiltrotor and tailsitter architectures combine runway independence with transit efficiency, attracting logistics operators testing beyond-visual-line-of-sight cargo routes.
- Nano:Sub-250-gram platforms exploit regulatory exemptions under FAA Part 107 and EASA open categories for consumer photography and tactical military reconnaissance.
Volume sits with Rotary-Wing; growth tilts toward Hybrid configurations as battery density improvements unlock viable commercial endurance.
Application:
Operational use cases determine payload specifications, autonomy requirements, and airspace access permissions.
- Agriculture:Multispectral imaging and variable-rate application systems enable soil mapping and targeted chemical deployment across Brazilian soybean belts and Dutch greenhouse cooperatives, with fleet economics improving through swarm coordination protocols.
- Surveillance:Real-time video feeds and signals intelligence packages serve border security agencies and law enforcement in the United States, Israel, and Turkey, where combat-proven platforms validate procurement decisions.
- Delivery:Last-mile logistics trials concentrate in urban corridors with FAA beyond-visual-line-of-sight exemptions and EASA specific category certification for payload weights below 25 kilograms.
- Mapping:Photogrammetry and LiDAR payloads support construction progress monitoring and mining volumetrics, though sensor cost structures constrain adoption among small-scale operators in developing markets.
Agriculture commands installed base; Surveillance applications are expanding most quickly through defense procurement acceleration.
End User:
Customer type dictates funding mechanisms, certification rigor, and operational risk tolerance.
- Military:Large fixed-wing platforms with satellite communication links and precision strike capabilities anchor procurement budgets; STANAG 4586 interoperability requirements complicate clean-sheet architectures for ground control station integration.
- Commercial:Service providers under FAA Part 107 and EASA open category frameworks perform infrastructure inspection and agricultural spraying on asset-as-a-service contracts, unbundling hardware ownership from flight-hour subscriptions.
- Civil:Research institutions and environmental agencies deploy platforms for wildlife monitoring and disaster response where regulatory frameworks permit experimental operations.
- Law Enforcement:Tactical teams in the United States leverage nano and small rotary-wing systems for situational awareness in urban operations, constrained by municipal privacy ordinances and evidence chain-of-custody requirements.
Military spending dominates value; Commercial users are gaining share fastest through subscription model adoption.
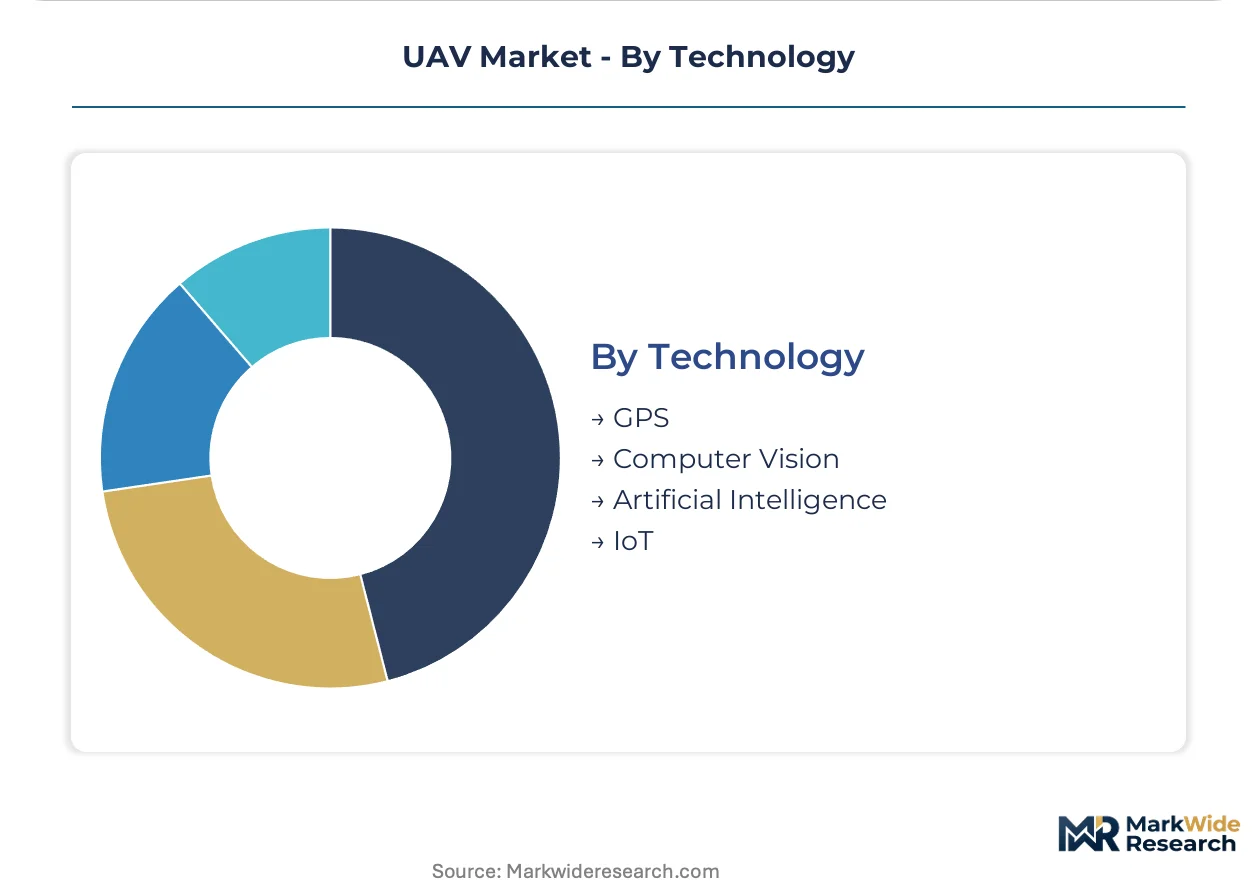
Technology:
Navigation and decision-making architectures separate premium platforms from baseline systems.
- GPS:Satellite-dependent waypoint navigation remains the cost-minimized default for consumer and entry-level commercial platforms, vulnerable to jamming in contested electromagnetic environments.
- Computer Vision:Optical flow and stereo depth estimation enable indoor navigation and close-proximity obstacle avoidance for inspection applications in European utility infrastructure.
- Artificial Intelligence:Onboard neural networks for real-time target recognition and autonomous mission replanning concentrate margin pools with defense contractors and high-end commercial service providers seeking beyond-visual-line-of-sight waivers.
- IoT:Mesh networking protocols and cloud connectivity support fleet management and predictive maintenance for agricultural cooperatives operating 50-unit swarms.
GPS retains volume dominance; Artificial Intelligence represents the steepest expansion trajectory as detect-and-avoid mandates drive autonomy requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement and precision agriculture operations are concentrating demand in five countries where regulatory frameworks and industrial clusters align to accelerate fleet deployments.
United States
Military intelligence collection and commercial infrastructure inspection drive platform demand across defense and civilian sectors. The FAA's Part 107 certification framework standardizes remote pilot qualifications while enabling beyond-visual-line-of-sight exemptions for select logistics trials. General Atomics anchors large fixed-wing production in California and Texas, supplying Predator-series platforms to domestic and allied military operators.
China
Consumer camera drone shipments and domestic airworthiness protocol development shape market dynamics. The MIIT accelerates certification timelines for indigenous manufacturers while CAAC mandates stricter validation for foreign platform entrants. SZ DJI Technology leverages its Shenzhen manufacturing base to dominate prosumer and enterprise rotary-wing segments across agricultural and mapping applications.
Brazil
Soybean and sugarcane belt operations are expanding multispectral imaging fleet deployments for soil analysis and yield optimization. ANVISA and the national civil aviation regulator coordinate aerial application safety standards for chemical spraying operations. Precision agriculture service providers cluster in Mato Grosso and São Paulo states, where cooperative ownership models improve fleet economics for medium-scale operators.
Turkey
Combat-proven platform validation is reshaping regional military procurement patterns across Eastern Mediterranean and Central Asian defense markets. Baykar's Bayraktar-series operational record accelerates foreign sales negotiations with governments seeking proven strike and surveillance capabilities. The Ankara-Konya industrial corridor hosts final assembly and ground control station integration facilities serving export contracts.
Germany
Utility infrastructure inspection and renewable energy site monitoring drive commercial service provider demand. EASA's specific category framework mandates design verification against quantitative safety objectives for higher-risk operations above 25 kilograms. The transmission grid sector in North Rhine-Westphalia and Bavaria exhibits the fastest migration toward asset-as-a-service contracting models, unbundling hardware ownership from flight-hour subscriptions.
UAV Market Competitive Environment
Shenzhen-based producers anchor the volume tier; Israeli and Turkish specialists hold the combat-proven defense segment. The vendor structure fragments across consumer prosumer, commercial services, and military-grade platforms with limited overlap in core competencies. Three archetypes dominate: vertically integrated hardware manufacturers, defense contractors with government R&D backing, and software-centric autonomy providers licensing perception stacks. Geographic expansion through local certification partnerships and portfolio diversification into adjacent sensor payloads represent the primary competitive moves.
Within the defense contractor archetype, General Atomics Aeronautical Systems, Northrop Grumman Corporation, and Baykar A.S. exemplify divergent national industrial strategies. General Atomics occupies a position anchoring large fixed-wing endurance platforms for intelligence and strike missions. Northrop Grumman sits within the high-altitude segment through its Global Hawk family. Baykar represents the emerging tier of regionally dominant combat-proven specialists reshaping procurement patterns outside traditional NATO supply chains.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd |
| General Atomics Aeronautical Systems |
| Northrop Grumman Corporation |
| AeroVironment, Inc. |
| Lockheed Martin Corporation |
| Teledyne FLIR LLC |
| Israel Aerospace Industries Ltd. |
| Baykar A.S. |
| Elbit Systems Ltd. |
| Others |
Value Chain & Pricing Dynamics
Military procurement offices in Turkey and the United States anchor demand for large fixed-wing platforms, locking in contract-based long-term offtake pricing with embedded service bundles that insulate prime contractors from spot-market volatility.
Pricing Analysis
Short lead-time premiums of 15-30% apply to combat-proven platforms with validated operational records, while spot inventory of consumer-grade rotary-wing systems from Shenzhen manufacturers trades at commodity-equivalent rates. Pricing stratifies across military-grade certification tiers under STANAG 4586, commercial service provider bundles under FAA Part 107, and exempted nano-platforms below 250 grams. Cost compression in the commercial inspection tier stems from asset-as-a-service contract proliferation unbundling hardware ownership. Small-scale agricultural operators in Brazil exhibit highest price sensitivity due to LiDAR payload cost barriers, while defense procurement offices in Ankara and Washington demonstrate lowest sensitivity tied to mission-critical specifications.
Supply Chain Analysis
Dual-sourcing mandates from European utility operators and US defense primes require qualified secondary suppliers for flight control computers and satellite communication links, compressing single-source dependency risk. Manufacturing gravity centers on China for consumer and prosumer airframes, Israel for military autonomy subsystems, and Turkey for combat-proven platform final assembly. Critical component feeds from Taiwanese semiconductor foundries, Japanese inertial measurement unit specialists, and South Korean battery cell producers create chokepoint exposure. Tariff exposure on Chinese-manufactured airframes entering North American and European markets represents the dominant structural risk. Distribution runs through direct military procurement channels, agricultural cooperative aggregators in Mato Grosso, and utility service provider networks in Germany's transmission grid sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAV market functions as a cost-of-compliance arena where EASA's specific category framework for operations above 25 kilograms erects certification barriers that reward incumbents with validated design verification capabilities against quantitative safety objectives.
For Market Incumbents: Extend airworthiness certification portfolios into EASA's specific category and FAA's emerging beyond-visual-line-of-sight frameworks before rulemaking finalization locks in competitor qualification gaps. Anchor defense relationships through STANAG 4586 interoperability investments that complicate clean-sheet platform displacement. Threat substitution from Chinese manufacturers with accelerated CAAC domestic timelines demands captive supply of flight control firmware talent clusters in Shenzhen and Tel Aviv. For New Entrants and Emerging Players: Part 107 in the United States opens a window for agricultural service providers in Brazil's Mato Grosso soybean belt where cooperative ownership models reduce customer acquisition friction against established equipment lessors. Target civil infrastructure inspection in Germany's North Rhine-Westphalia transmission grid where asset-as-a-service contract structures favor software-centric autonomy providers over hardware manufacturers. Go-to-market leverage rests on licensing perception stacks to incumbent OEMs rather than competing for airframe volume. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-centric autonomy providers with validated detect-and-avoid algorithms in Israeli and US defense corridors where embedded systems talent scarcity creates acquisition premiums. Long-term viability concentrates in platforms with demonstrated beyond-visual-line-of-sight waiver attainment and military operational validation. The signal to watch is FAA final rulemaking on detect-and-avoid mandates, which would trigger certification cost step-functions favoring pre-qualified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | EASA specific category and FAA BVLOS pre-qualification locks in competitor exclusion before rulemaking finalization. |
| Autonomy Stack Licensing | Software-centric providers capture margin pools in real-time decision-making subsystems without airframe capital intensity. |
| Defense Interoperability Investment | STANAG 4586 compliance complicates clean-sheet displacement and anchors long-term ground control station integration. |
| Cooperative Service Model Deployment | Agricultural fleet economics in Brazil's Mato Grosso improve through swarm coordination and shared ownership structures. |
| Talent Cluster Acquisition | Embedded systems firmware expertise in Shenzhen and Tel Aviv clusters addresses recruitment bottlenecks for Western OEMs. |
Study Parameters
Regulatory filings from the FAA, EASA, and CAAC, trade customs data from Brazilian and Turkish export authorities, and defense procurement databases from NATO and allied ministries formed the secondary backbone. Primary fieldwork incorporated structured interviews with flight operations directors at precision agriculture cooperatives, autonomy subsystem engineers at Israeli defense contractors, regulatory affairs leads at Chinese manufacturers, and procurement officers at European utility operators. Bottom-up platform shipment estimates by configuration and application triangulated against top-down defense budget allocations and commercial service provider fleet counts.
Bottom-up modeling of unit economics across fixed-wing, rotary-wing, hybrid, and nano configurations combined with top-down validation against national defense procurement disclosures and agricultural subsidy programs. Segmentation dimensions spanned product architecture, operational application, end-user funding mechanism, and navigation technology tier. CAGRs derived from logistic curve fitting of technology adoption patterns calibrated against historical airworthiness certification timeline data. Forecast inputs incorporated solid-state battery energy density improvement trajectories and hydrogen fuel cell prototype commercialization schedules for endurance extension.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled detect-and-avoid autonomy would alter the outlook if FAA rulemaking accelerates beyond current proposal timelines. Deviation in EASA's specific category enforcement intensity or CAAC's foreign platform validation protocol stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Leasing Market
UAV
Industrial Drones Market
UAV
Asia-Pacific Drone Motor Market
UAV
Micro Drone Market
UAV
Solar-Powered UAV Market
UAV
Drone Motors Market
UAV
Inspection Drones in Confined Space Market
UAV
Consumer Drone Market
UAV
Drone Identification System Market
UAV
Rc Helicopter Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Small UAV Market
UAV
North America Drone Software Market
UAV
Europe Tactical UAV Market
UAV
UAV Payload Market
UAV
FPV Drone Goggles Market