
 Color Meter Market | 2026-2036
Color Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Color Meter Market Outlook
Buyer concentration across automotive OEM coating lines is recalibrating procurement volumes toward fewer but larger instrument contracts. Konica Minolta Sensing leverages its Japan-based sensor foundry to dominate high-end portable spectrophotometry. X-Rite competes through dense calibration service networks across European automotive hubs. Thermo Fisher Scientific anchors its position in pharmaceutical and biotech colorimetric workflows with integrated LIMS compatibility.
A color meter quantifies chromatic attributes through tristimulus values or spectral reflectance curves, typically resolving color difference in Delta E units against reference standards. These instruments enforce batch-to-batch consistency in coatings, textiles, and processed food matrices where human visual assessment fails regulatory repeatability thresholds. Spectrophotometric technology commands premium positioning due to full-spectrum resolution needs in automotive metallic and pearlescent finishes. Portable form factors now lead unit shipments as on-floor quality control displaces centralized lab routing in manufacturing plants. RGB-based systems occupy economy-tier education and consumer electronics calibration segments where absolute accuracy matters less than speed.
FDA 21 CFR Part 11 compliance requirements shape validation protocols for color meters deployed in pharmaceutical tablet coating verification. ISO 11664 and CIE publication standards define measurement geometry and observer functions that manufacturers must certify for cross-border equipment acceptance. REACH substance restrictions in Europe constrain optical filter and housing material selections, raising redesign costs for benchtop instrument suppliers. Stakeholders must monitor convergence between inline online color monitoring and MES layer integration as smart factory architectures redefine instrument connectivity requirements.
Market Dynamics
Automotive paint shops in Germany and Japan are tightening color tolerance verification under updated ISO 11664 standards, forcing instrument suppliers to recalibrate product roadmaps around spectrophotometric precision and faster certification cycles.
Growth Catalysts
- ISO 11664 standard updates:Automotive OEM coating lines in Germany and Japan now mandate stricter Delta E verification, pulling demand toward high-resolution benchtop units.
- Pharmaceutical quality lab expansion:FDA 21 CFR Part 11 compliance requirements drive validation protocol investments for tablet coating verification in United States facilities.
- Portable form factor preference:On-floor quality control in manufacturing plants displaces centralized lab routing, accelerating unit shipments of handheld spectrophotometers.
Market Restraints
- Optical component supply concentration:Precision sensor foundries in Japan and South Korea control critical photodiode supply, creating single-source vulnerability for portable instrument manufacturers.
- REACH substance restrictions:ECHA constraints on optical filter materials and housing polymers force European benchtop suppliers into costly redesign cycles.
- RGB system substitution threat:Economy-tier education and consumer electronics calibration segments accept lower-accuracy RGB-based systems, capping price realization at the entry level.
Strategic Opportunities
- Inline online color monitoring convergence:Spectrophotometric sensors are integrating with MES layer architectures in smart factory deployments across automotive hubs.
- Pharmaceutical LIMS compatibility:Biotech workflows in the United States create demand for color meters with native data integration to laboratory information management systems.
- Metallic and pearlescent finish complexity:Full-spectrum resolution requirements in premium automotive coatings sustain premium positioning for multi-angle spectrophotometry.
Industry Challenges
- Calibration technician scarcity:Automotive OEM coating lines face shortages of personnel certified to ISO 17025 standards for instrument traceability.
- Cross-border certification timelines:CIE publication compliance verification delays product launches in markets with divergent national metrology institute requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Color Meter Market |
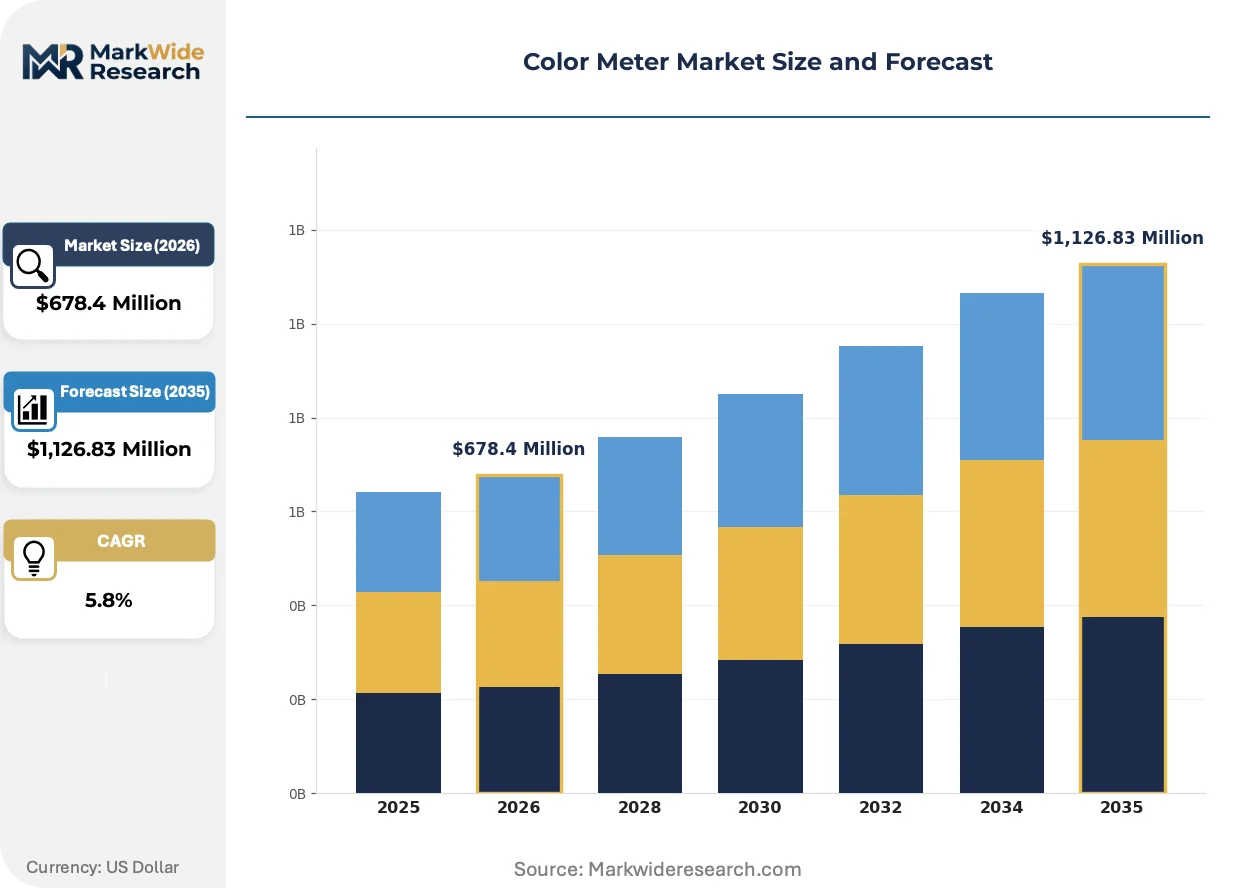
| Market Size in 2026 | $678.4 Million |
| Market Size in 2035 | $1,126.83 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Colorimetric, Spectrophotometric, RGB, Lab Application: Manufacturing, Quality Control, Textile, Coatings End User: Food Industry, Healthcare, Automotive, Cosmetic Form Factor: Portable, Benchtop, Handheld, Online |
| Companies Covered | Konica Minolta Sensing, Thermo Fisher Scientific, Hanna Instruments, X-Rite, Hach Company, BYK Gardner, Harvard Bioscience, Xylem Inc., Admesy BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Color Meter Market Strategic Shifts
Spectrophotometric technology is embedding deeper into manufacturing execution systems while regulatory frameworks tighten traceability requirements across pharmaceutical and automotive quality workflows.
Multi-angle spectrophotometry is integrating with robotic paint inspection stations in automotive assembly plants. German and Japanese OEM coating lines deploy these systems for real-time metallic finish verification. This convergence compresses defect detection cycles from hours to minutes while elevating capital intensity for tier-one suppliers.
REACH substance restrictions under ECHA jurisdiction are constraining optical filter material selections for benchtop instrument housings. European suppliers absorb redesign costs to maintain CE marking eligibility. Pharmaceutical and food safety labs face extended procurement timelines as alternative material qualification stretches validation protocols.
Service unbundling is fragmenting traditional instrument-plus-calibration bundles in European automotive hubs. Tier-two paint shops now procure hardware and metrology services through separate vendor relationships. This pattern concentrates in Germany where independent calibration laboratories compete with manufacturer-direct service networks.
Color Meter Market Segmentation
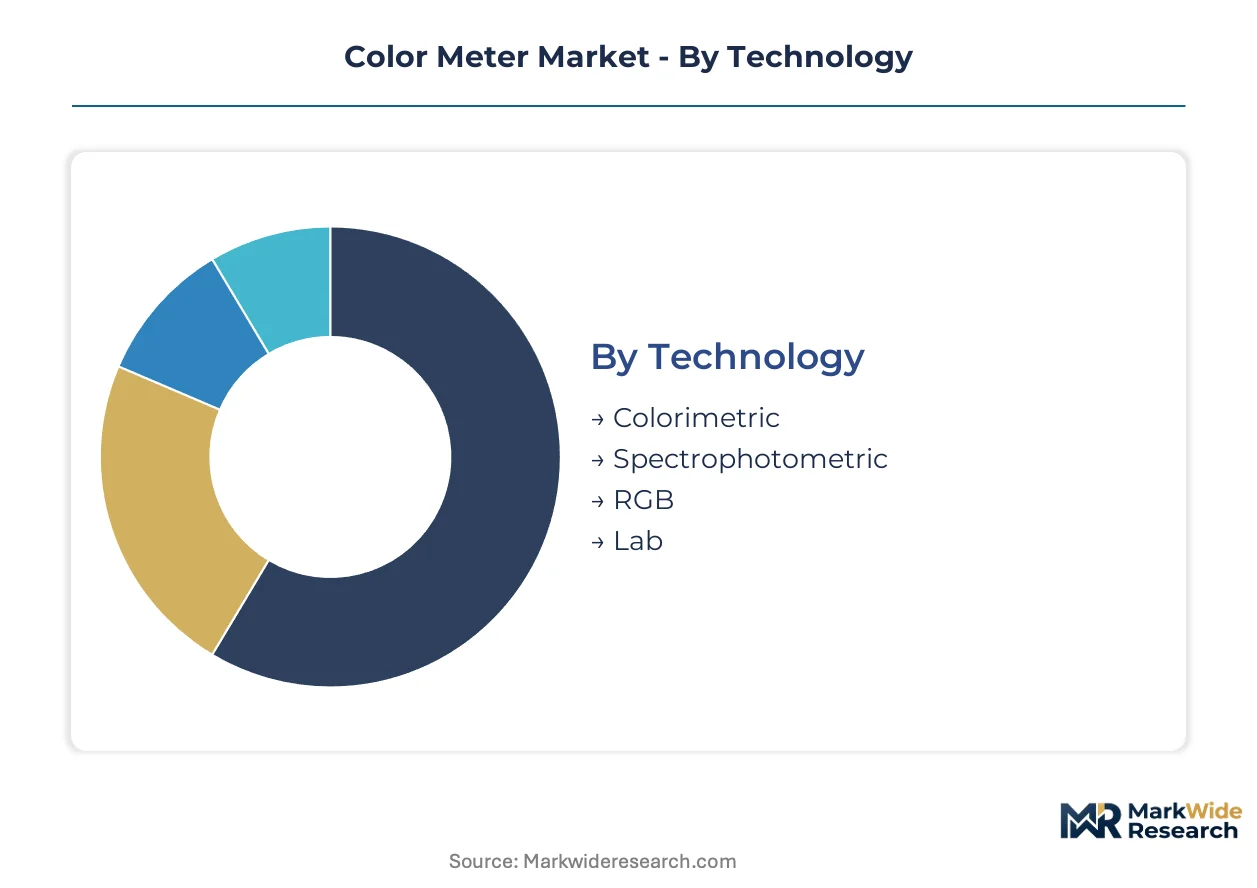
Color meter segmentation reflects divergent technical requirements across embedded production lines and standalone laboratory environments. Procurement patterns split sharply between instruments integrated into manufacturing execution systems and those deployed for isolated quality verification. Understanding these integration depths clarifies why certain technologies command premium positioning while others compete on unit economics.
Technology:
Integration depth varies dramatically across technology categories, with full-spectrum systems embedding directly into automotive paint shop control architectures while simplified sensors remain standalone.
- Spectrophotometric:These instruments resolve full spectral reflectance curves across 360-750nm wavelengths, enabling Delta E calculations for metallic and pearlescent automotive finishes. German and Japanese OEM coating lines embed multi-angle spectrophotometers directly into robotic inspection stations for real-time batch verification.
- Colorimetric:Tristimulus-based systems measure CIE XYZ values through filtered photodiode arrays, offering sufficient accuracy for food packaging and textile dye lots at lower cost points. Standalone deployment dominates in small-batch manufacturing where MES connectivity remains unnecessary.
- RGB:Simplified three-channel sensors serve consumer electronics calibration and educational laboratory settings where absolute spectral fidelity matters less than speed and portability.
- Lab:CIELAB color space converters process raw tristimulus data into perceptually uniform coordinates, typically deployed as software modules within spectrophotometric or colorimetric hardware platforms.
Colorimetric systems lead volumes today; spectrophotometric technology is gaining share fastest.
Application:
Cost tier stratification separates capital-intensive inline installations from budget-allocated spot-check instruments across manufacturing floors.
- Coatings:Automotive paint shops in Germany deploy benchtop spectrophotometers for incoming pigment verification and portable units for cured finish audit. ISO 11664 standard updates mandate tighter Delta E tolerances, forcing recalibration investments.
- Quality Control:Pharmaceutical tablet coating verification in United States facilities requires FDA 21 CFR Part 11 compliant instruments with native LIMS integration and full audit trail documentation.
- Manufacturing:Inline color monitoring converges with MES layer architectures in smart factory deployments, embedding spectrophotometric sensors directly into process control loops.
- Textile:Dye house operations favor portable colorimeters for batch approval, with standalone deployment persisting where centralized laboratory routing remains economically justified.
Quality control applications absorb premium pricing; coatings demand is expanding most quickly.
End User:
Customer type concentration shapes procurement scale, with automotive OEMs negotiating multi-instrument contracts while cosmetic formulators purchase single units.
- Automotive:OEM coating lines in Germany and Japan specify multi-angle spectrophotometry for metallic finish verification, integrating instruments directly into paint shop control systems.
- Healthcare:Pharmaceutical quality labs in the United States drive validation protocol investments for tablet coating verification under FDA compliance requirements.
- Food Industry:Processed food matrices require batch-to-batch consistency verification where human visual assessment fails regulatory repeatability thresholds.
- Cosmetic:Formulation laboratories deploy portable colorimeters for raw material incoming inspection and finished product shade matching.
Automotive end users dominate capital deployment; healthcare compliance requirements are climbing the fastest.
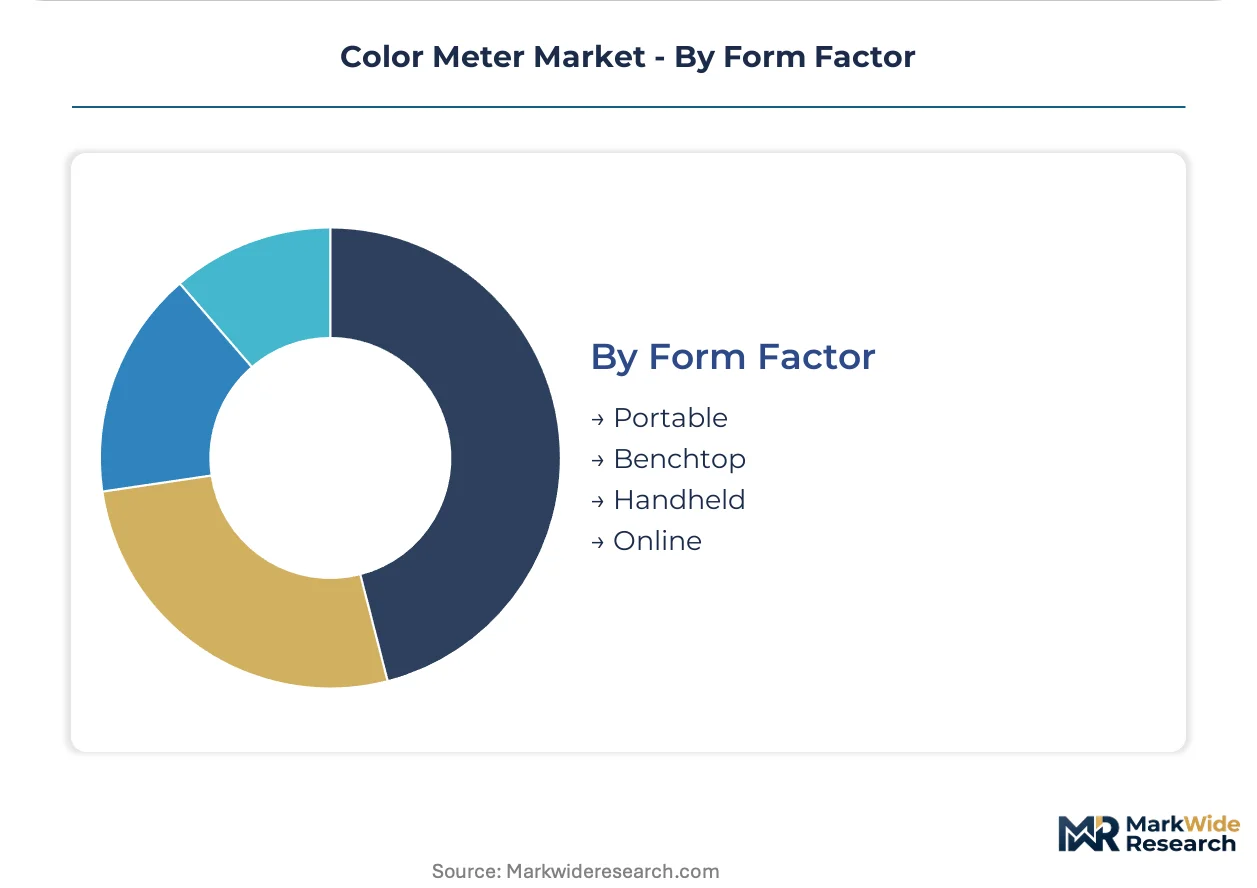
Form Factor:
Supply concentration in precision sensor foundries constrains portable instrument availability while benchtop production scales more readily.
- Portable:Handheld spectrophotometers displace centralized laboratory routing in manufacturing plants, with on-floor quality control accelerating unit shipments. Japanese sensor foundries control critical photodiode supply for these instruments.
- Benchtop:Pharmaceutical quality labs in the United States specify these units for tablet coating verification, with integrated LIMS compatibility anchoring competitive positioning.
- Handheld:Compact form factors serve textile dye houses and cosmetic laboratories where operator mobility outweighs spectral resolution requirements.
- Online:Inline spectrophotometric sensors integrate with MES layer architectures in smart factory deployments across automotive hubs, enabling real-time process adjustment.
Portable form factors lead unit shipments today; online integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration technician pools in Germany and Japan anchor the highest-value instrument deployments. These specialized workforces support ISO 17025-certified traceability protocols that automotive OEMs mandate for coating line verification.
Germany
Automotive paint shops in Stuttgart and Munich drive demand for multi-angle spectrophotometry under updated ISO 11664 standards. KBA enforcement of color tolerance verification forces tier-one suppliers into faster certification cycles. Bavarian coating clusters embed these instruments directly into robotic inspection stations for real-time metallic finish validation.
Japan
Precision sensor foundries in Osaka and Nagoya supply critical photodiode arrays for portable spectrophotometers. METI industrial standards shape domestic instrument specifications that export markets adopt. Kanto-based automotive OEMs integrate color verification into paint shop control architectures with sub-minute defect detection cycles.
United States
Pharmaceutical quality labs in New Jersey and Massachusetts expand validation protocol investments for tablet coating verification. FDA 21 CFR Part 11 compliance requirements mandate full audit trail documentation and native LIMS compatibility. Greater Boston biotech clusters anchor demand for benchtop units with integrated data management workflows.
China
Automotive coating lines in Shanghai and Guangzhou scale inline color monitoring with MES layer integration. GB standards and MIIT smart factory directives accelerate spectrophotometric sensor deployment into process control loops. Yangtze River Delta manufacturing hubs prioritize on-floor quality control over centralized laboratory routing.
South Korea
Display panel manufacturers in Gyeonggi-do and Seoul deploy RGB-based systems for consumer electronics calibration. MFDS pharmaceutical regulations create parallel demand for higher-accuracy benchtop units in domestic quality labs. Seoul Capital Area electronics clusters accept lower spectral fidelity where speed and unit economics dominate procurement criteria.
Color Meter Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: diversified instrumentation conglomerates with cross-sector calibration service networks, sensor foundry-integrated specialists with captive photodiode supply, and regional system integrators with localized compliance expertise. Competitive moves concentrate on M&A for calibration service footprint expansion and strategic partnerships for MES layer integration capabilities.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific and Xylem Inc. exemplify the scale-driven archetype with broad analytical instrument portfolios. Konica Minolta Sensing represents the sensor-foundry-integrated specialist model with Japan-based photodiode manufacturing. X-Rite occupies a position within the calibration service-intensive tier, anchoring European automotive hub presence through dense metrology networks.
| Leading Market Players |
|---|
| Konica Minolta Sensing |
| Thermo Fisher Scientific |
| Hanna Instruments |
| X-Rite |
| Hach Company |
| BYK Gardner |
| Harvard Bioscience |
| Xylem Inc. |
| Admesy BV |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM coating lines in Germany and Japan demanding ISO 11664-certified multi-angle spectrophotometry are forcing suppliers to absorb higher photodiode input costs while maintaining price discipline on portable units. This procurement specification tightening concentrates pricing power with Japan-based sensor foundries and fragments margin capture across downstream assembly tiers.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for benchtop colorimetric units serving pharmaceutical quality labs. Pricing stratifies across premium spectrophotometric, standard colorimetric, and economy RGB tiers, with certification grade under ISO 17025 and FDA 21 CFR Part 11 compliance driving substantial differentiation. Cost compression in the portable segment is intensifying because Japanese photodiode supply constraints limit production scale. Education and consumer electronics buyers exhibit highest price sensitivity, while automotive OEMs accept premium positioning for inline MES-integrated systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Japanese automotive coating lines, while independent calibration laboratories serve tier-two paint shops through unbundled service relationships. Manufacturing concentrates in Japan, Germany, and the United States, with precision photodiode arrays, optical filter substrates, and specialized housing polymers as critical inputs. Single-source vulnerability in Japanese sensor foundries creates structural risk for portable instrument manufacturers. Distribution runs through manufacturer-direct service networks in European automotive hubs and regional system integrators in Asian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Color Meter Market represents a late-cycle quality story as pharmaceutical and automotive end users shift procurement toward premium spectrophotometric specifications with native LIMS and MES integration requirements.
For Market Incumbents: Extend calibration service network density in European automotive hubs to defend against unbundling trends fragmenting traditional instrument-plus-service bundles. Deepen backward integration into photodiode supply through strategic partnerships with Japanese sensor foundries, as optical component concentration threatens production continuity for portable form factors. For New Entrants and Emerging Players: Independent calibration laboratories in Germany present the most penetrable channel partner type for service-only market entry without capital-intensive hardware manufacturing. Target textile dye house operations and cosmetic formulation laboratories in Asia-Pacific manufacturing clusters where standalone colorimetric deployment persists and price sensitivity exceeds specification stringency. For Investors and Strategic Acquirers: Asymmetric upside sits with sensor-foundry-integrated specialists possessing captive photodiode supply and established OEM relationships. Five-to-ten year viability favors acquisition targets with demonstrated FDA 21 CFR Part 11 validation protocol expertise and existing pharmaceutical quality lab installations. Monitor convergence between inline online color monitoring and MES layer integration adoption rates as the primary inflection indicator for smart factory instrumentation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Dense metrology coverage in Stuttgart and Munich automotive clusters captures unbundled procurement from tier-two paint shops. |
| Photodiode Supply Partnership | Strategic alliances with Osaka and Nagoya sensor foundries secure critical component access for portable spectrophotometer production. |
| LIMS Integration Development | Native laboratory information management system compatibility anchors competitive positioning in FDA-regulated pharmaceutical quality labs. |
| MES Layer Convergence | Inline spectrophotometric sensor integration with manufacturing execution systems enables real-time process control in smart factory deployments. |
| REACH Compliance Redesign | Alternative optical filter material qualification maintains CE marking eligibility under ECHA substance restrictions for European benchtop suppliers. |
Study Parameters
Bottom-up automotive and pharmaceutical end-use modeling reconciled against top-down spectrophotometric and colorimetric instrument production tracking forms the analytical core of this study. Primary interviews with quality control directors at automotive OEM coating lines, pharmaceutical regulatory affairs leads, calibration laboratory technicians, and optical component procurement managers combined with secondary validation from FDA 510(k) filings, ISO certification registries, ECHA substance restriction updates, and customs trade data for photodiode and optical filter imports.
Input-output matrices map unit shipments across technology, application, end user, and form factor dimensions against capital expenditure patterns in automotive paint shops and pharmaceutical quality labs over the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market value expansion, with specific modeling inputs including ISO 11664 standard update implementation timelines and FDA 21 CFR Part 11 compliance investment cycles.
Revisions become necessary when REACH substance restriction expansions, photodiode supply disruptions, or MES layer integration standardization shifts materialize beyond baseline assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Precision Measuring Tools Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Surface Measurement Equipment and Tools Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Volte Testing Market
Test and Measurement
Moisture Analyzer Market