
 J-Beauty Products Market | 2026-2036
J-Beauty Products Market Size, Share, and Industry Trends Forecast 2026-2036
J-Beauty Products Market Analytics
Asset-light licensing and cross-border e-commerce financing is reshaping how mid-size J-Beauty brands enter overseas markets without capital-heavy retail buildouts. Shiseido Company Ltd. leverages its domestic R&D infrastructure to sustain premium positioning across Asian duty-free corridors. Kao Corporation anchors volume through drugstore distribution networks that compete on accessibility rather than exclusivity. POLA Orbis Holdings differentiates through direct-to-consumer salon channels that control the full service experience.
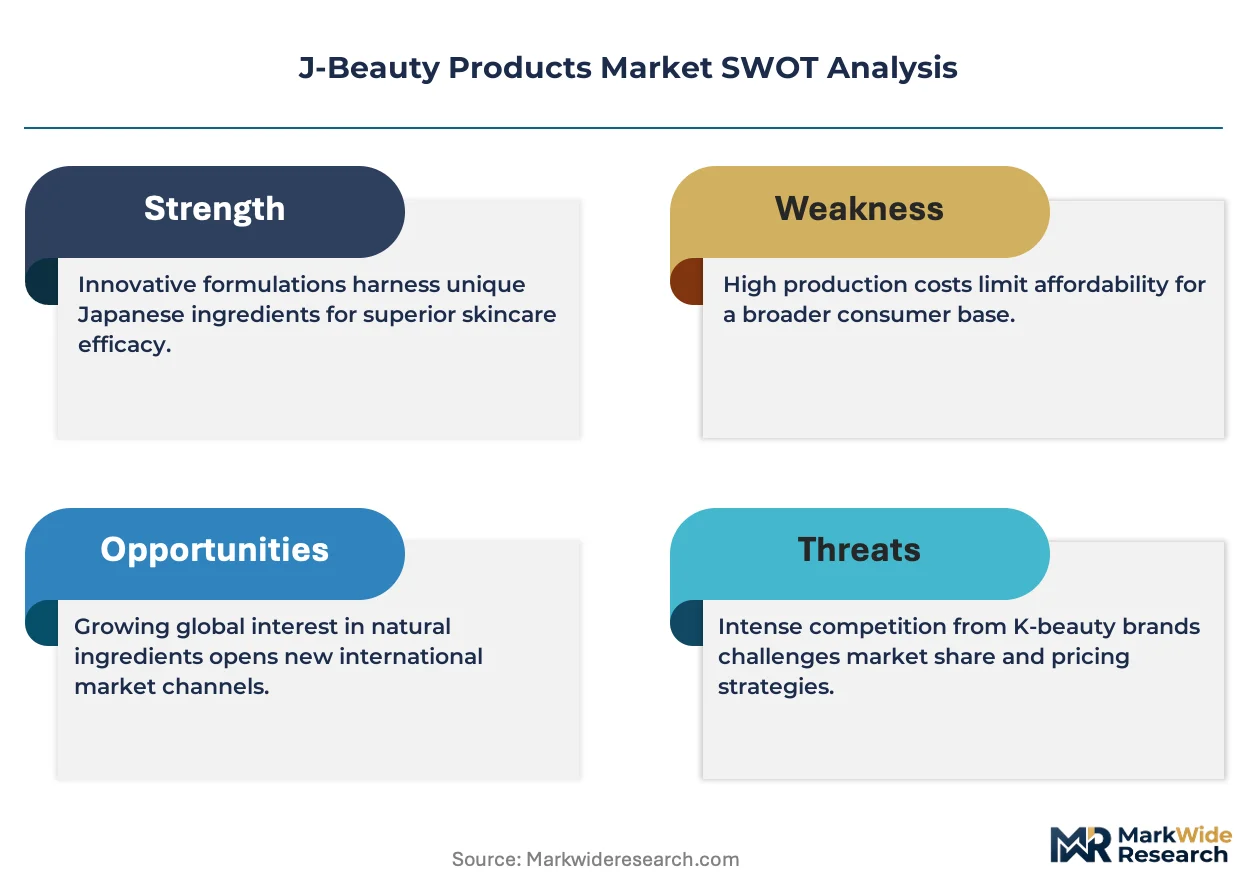
J-Beauty products encompass skincare, color cosmetics, haircare, and body care formulations developed under Japanese manufacturing protocols emphasizing fermentation-derived actives, multi-step ritual design, and minimalist preservative systems. These products serve consumers seeking efficacy-driven routines rooted in dermatological validation rather than trend cycles. Skincare occupies the dominant margin pool due to higher per-unit pricing and repeat purchase frequency across premium and mass tiers. The natural and hybrid formulation segments expand fastest as consumers scrutinize ingredient transparency alongside clinical performance claims.
Japan's Ministry of Health, Labour and Welfare quasi-drug framework and the U.S. FDA cosmetic registration requirements jointly determine which whitening, anti-aging, and sun protection claims reach international shelves. METI export promotion programs and ASEAN harmonization initiatives reduce technical barriers for brands scaling beyond domestic production bases. Stakeholders must monitor evolving EU REACH chemical restrictions and China's NMPA animal testing exemptions as these frameworks determine which heritage formulations qualify for market access.
Market Dynamics
Social commerce algorithms and quasi-drug certification requirements are restructuring how J-Beauty brands build cross-border demand, forcing manufacturers to reconcile ritual-based product architectures with platform-native content formats and abbreviated consumer attention spans.
Growth Catalysts
- Japan's quasi-drug framework:The Ministry of Health, Labour and Welfare's efficacy validation requirements for whitening and anti-aging claims create formulation credibility that commands premium shelf positioning across Southeast Asian retail channels.
- Fermentation-derived actives:Biotechnology advances in koji-derived kojic acid and rice ferment filtrates enable clinical-grade performance claims that satisfy dermatological scrutiny among professional consumers in Seoul and Bangkok.
- Urban professional clusters:Young professionals in Southeast Asian metropolitan centers are displacing Western skincare routines with Japanese multi-step rituals, driving repeat purchase frequency through subscription and replenishment commerce models.
Market Restraints
- Input cost volatility:Premium-grade sake lees and specialized fermentation substrates face supply concentration risks from domestic Japanese agricultural cooperatives, compressing margin structures for mid-tier brands.
- Regulatory friction:China's NMPA animal testing exemptions remain inconsistently applied to imported cosmetics, blocking heritage formulations containing novel botanical actives from the mainland market.
- Technical limitation:Minimalist preservative systems required for clean beauty positioning reduce shelf stability, forcing cold-chain logistics investments that elevate landed costs in tropical climates.
Strategic Opportunities
- Underpenetrated Vietnam and Indonesia:Emerging urban middle-class consumers in Ho Chi Minh City and Jakarta demonstrate rising appetite for Japanese skincare rituals, with local social commerce platforms lacking established J-Beauty anchor brands.
- Regulatory tailwind:ASEAN harmonization initiatives for cosmetic ingredient standards reduce technical barriers for brands scaling beyond domestic production bases into unified Southeast Asian distribution.
- Men's grooming convergence:Gender-neutral formulation architectures and simplified ritual designs are capturing male professional consumers previously excluded from category marketing.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in fermentation biotechnology and quasi-drug dossier preparation concentrates among aging researchers at legacy manufacturers, constraining new entrant R&D velocity.
- Compliance timeline compression:Accelerating EU REACH chemical restriction updates and China's evolving NMPA filing requirements force simultaneous multi-jurisdiction dossier management that strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | J-Beauty Products Market |
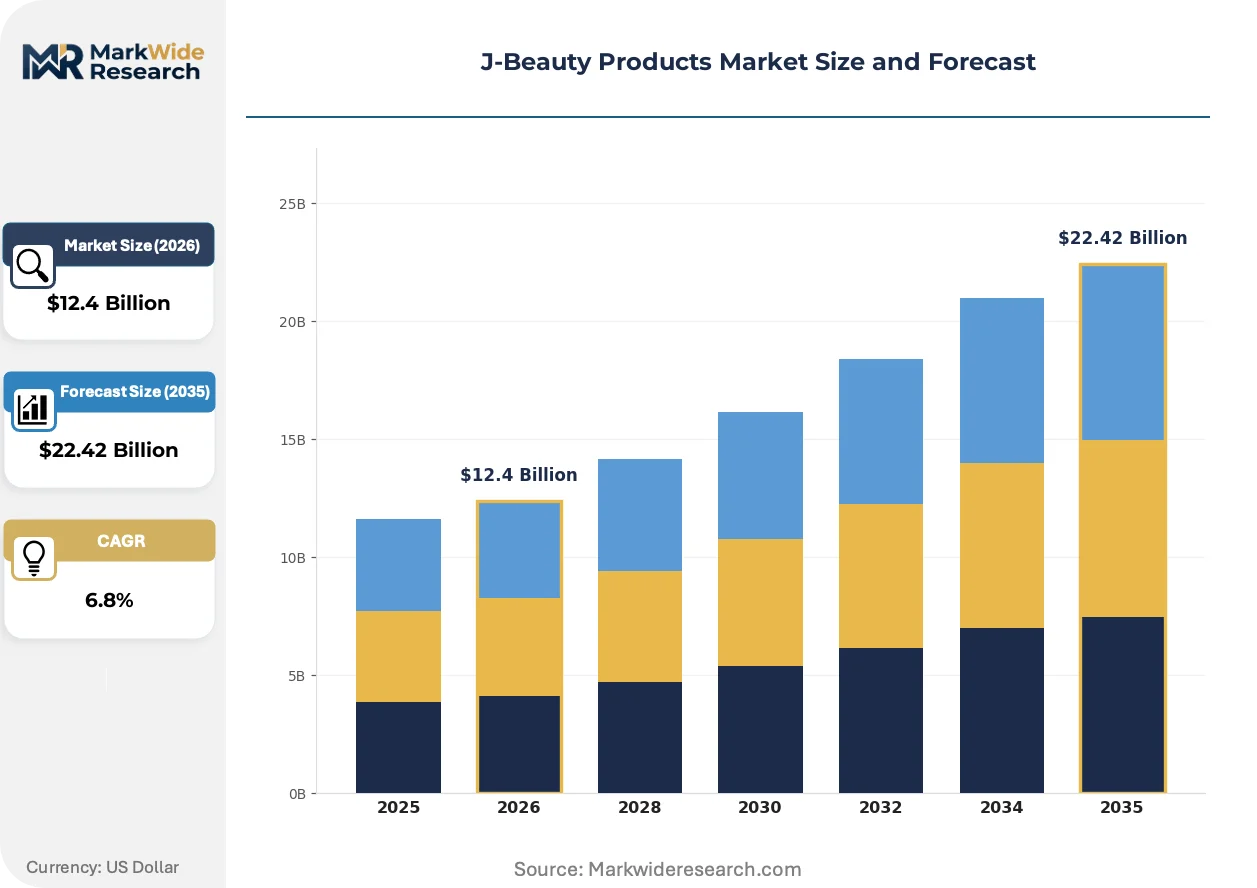
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Body Care Formulation: Natural, Organic, Synthetic, Hybrid Distribution Channel: Online, Specialty Stores, Department Stores, Pharmacies Customer Type: Millennials, Gen Z, Professionals, Seniors |
| Companies Covered | POLA Orbis Holdings, Mandom Corporation, Shiseido Company Ltd., Pias Corporation, Albion co, Ltd., Kao Corporation, FANCL Corporation, Noeivir Holdings, KOSE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
J-Beauty Products Market Evolving Landscape
Fermentation science advances and platform commerce mechanics are compressing product development cycles while elevating ingredient transparency expectations, forcing brands to reconcile heritage formulation philosophies with real-time consumer feedback loops.
Bioreactor-cultured exosomes and postbiotic complexes are migrating from professional salon channels to mass-market retail, enabling at-home efficacy claims previously restricted to clinical settings. Premium consumers in Tokyo and Osaka are adopting these actives within abbreviated ritual formats. The technology is migrating from service-dependent distribution toward standalone retail economics.
Japan's METI export promotion programs now coordinate with ASEAN cosmetic regulatory harmonization frameworks to streamline cross-border ingredient approvals. This policy alignment reduces technical documentation burdens for manufacturers scaling beyond domestic production. Mass-tier brands with established quasi-drug portfolios capture disproportionate benefit from accelerated market access timelines.
Platform-native discovery is displacing traditional department store counter relationships as the primary consumer acquisition channel. TikTok Shop and Instagram commerce integrations enable direct-to-consumer replenishment models that bypass wholesale margin structures. This behavioral shift concentrates among young professionals in Bangkok and Manila, where algorithmic content recommendation engines outperform legacy beauty advisor consultations for initial product trial.
J-Beauty Products Market Segmentation
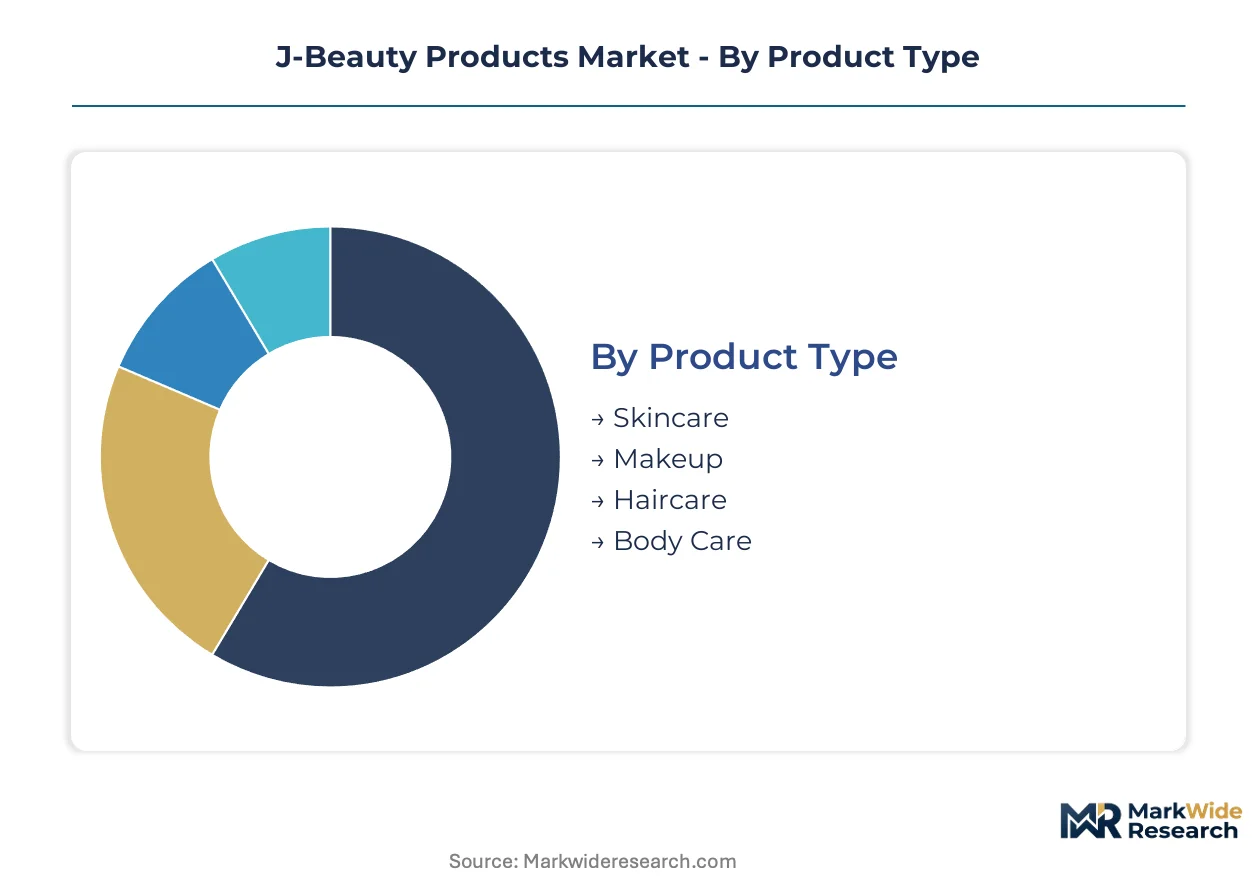
Segmentation in J-Beauty reveals how formulation philosophy, channel strategy, and demographic targeting intersect to determine margin capture. Manufacturers must align quasi-drug certification investments with the specific consumption rituals and purchasing behaviors of each slice.
Product Type:
Mature skincare architectures dominate revenue concentration while color cosmetics and adjacent categories emerge from ritual adjacency.
- Skincare:Multi-step ritual systems encompassing essences, serums, and moisturizers built around fermentation-derived actives. Young professionals in Seoul and Bangkok drive replenishment frequency through subscription models anchored by quasi-drug whitening and anti-aging claims.
- Makeup:Color cosmetics incorporating skincare-benefit positioning through hybrid formulations. Demand concentrates among Gen Z consumers in urban Southeast Asian centers seeking simplified routines that merge coverage with dermatological validation.
- Haircare:Scalp-focused treatments leveraging Japanese fermentation science for follicle health claims.
- Body Care:Bath and body formulations emphasizing minimalist preservative systems and sensorial ritual design.
Skincare handles the majority of throughput; Makeup is the fastest mover on share.
Formulation:
Cost tier stratification separates heritage biotechnology investments from accessible clean beauty positioning.
- Natural:Plant-derived actives and botanical extracts processed through traditional Japanese extraction methods. METI export promotion programs accelerate cross-border approval timelines for heritage formulations meeting ASEAN harmonization standards.
- Hybrid:Systems combining biotechnology-derived actives with clean label positioning. Professionals in Tokyo and Osaka favor these formulations for their reconciliation of clinical efficacy with ingredient transparency demands.
- Organic:Certified organic inputs subject to stricter agricultural cooperative sourcing constraints.
- Synthetic:Conventional chemical actives retained for sun protection and preservative functionality.
Natural formulations absorb the largest certification investment; Hybrid architectures are expanding most quickly as transparency expectations intensify.
Distribution Channel:
Volume concentration shifts from legacy retail toward platform-native discovery mechanisms.
- Online:Social commerce and direct-to-consumer platforms enabling algorithmic discovery and replenishment automation. TikTok Shop integrations in Bangkok and Manila outperform department store counters for initial trial among young professionals.
- Specialty Stores:Curated retail environments emphasizing education and ritual demonstration. These channels sustain premium positioning for quasi-drug portfolios requiring consultation-intensive purchase decisions.
- Department Stores:Traditional counter relationships anchored by beauty advisor consultations.
- Pharmacies:Drugstore networks competing on accessibility for mass-tier daily use formulations.
Online channels capture the steepest volume trajectory; Specialty Stores defend the highest margin concentration.
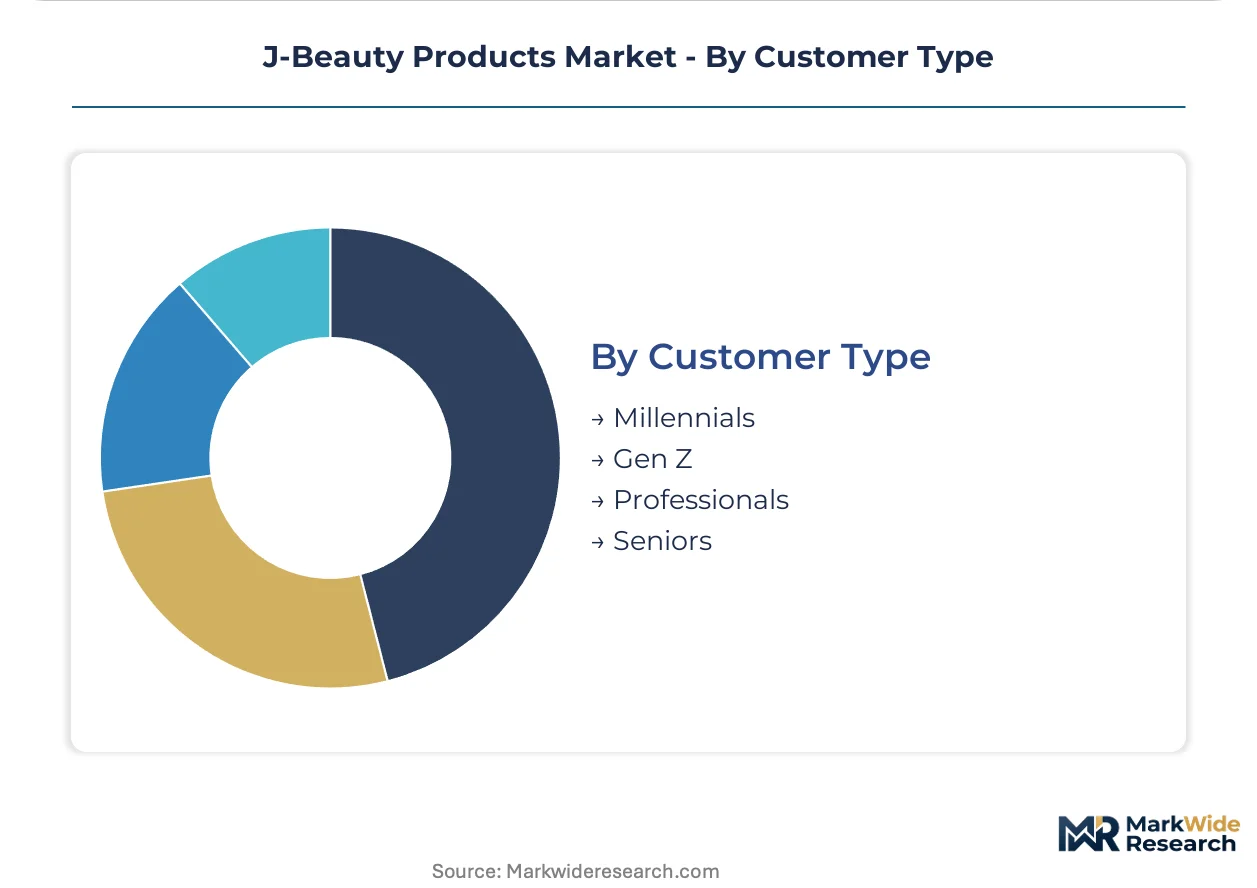
Customer Type:
Application intensity varies across life stage and professional status, determining ritual complexity and price point acceptance.
- Professionals:Time-constrained urban consumers in Seoul and Bangkok seeking abbreviated multi-step systems with proven efficacy. Their purchasing concentrates in premium hybrid formulations distributed through online replenishment models.
- Gen Z:Digital-native consumers discovering J-Beauty through platform algorithm recommendations. This cohort demonstrates highest trial velocity for makeup-skincare hybrids and fermentation-forward novelties.
- Millennials:Established routine adherents with sustained loyalty to heritage quasi-drug brands.
- Seniors:Mature consumers prioritizing anti-aging claims with dermatological validation.
Professionals generate the highest per-capita spend; Gen Z is climbing the fastest on customer acquisition metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japanese domestic channels while Southeast Asian markets absorb volume through compressed margin structures. Duty-free corridors in Tokyo and Osaka sustain 40-60% price premiums over Bangkok and Manila retail equivalents. This asymmetry shapes how brands allocate quasi-drug certification investments across regulatory jurisdictions.
Japan
Domestic demand for fermentation-derived actives and multi-step ritual systems anchors global formulation standards. The Ministry of Health, Labour and Welfare's quasi-drug framework validates whitening and anti-aging claims that command shelf positioning premiums. Manufacturing clusters in Osaka and Tokyo concentrate R&D infrastructure for koji-derived biotechnology.
South Korea
Young professionals in Seoul drive cross-border adoption of Japanese hybrid formulations through social commerce platforms. The MFDS cosmetic regulatory framework recognizes Japan's quasi-drug testing protocols, accelerating ingredient approval timelines. Beauty districts in Gangnam and Hongdae serve as trend incubation zones for abbreviated ritual formats.
Thailand
Bangkok's urban professional clusters displace Western skincare routines with Japanese multi-step systems purchased through TikTok Shop integrations. ASEAN harmonization initiatives streamline cross-border ingredient approvals from Japanese manufacturers. Siam Paragon and EmQuartier retail corridors concentrate premium quasi-drug distribution.
Vietnam
Emerging middle-class consumers in Ho Chi Minh City demonstrate rising appetite for Japanese skincare rituals through underpenetrated social commerce channels. The country's cosmetic regulatory authority aligns with ASEAN ingredient standards, reducing technical barriers for heritage formulations. District 1 and District 7 retail zones lack established J-Beauty anchor brands.
Indonesia
Jakarta's young professional demographic purchases Japanese body care and haircare formulations through platform-native discovery mechanisms. METI export promotion programs coordinate with ASEAN regulatory frameworks to accelerate market access timelines. Mall-based retail in South Jakarta sustains premium positioning for salon-channel brands.
J-Beauty Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation substrate and bioreactor technology. The vendor base concentrates around three structural tiers: legacy conglomerates with domestic R&D infrastructure, mid-size specialists leveraging asset-light licensing, and emerging direct-to-consumer platforms. Competitive positioning hardens around quasi-drug certification velocity, cross-border e-commerce financing access, and fermentation biotechnology IP. Dominant moves include strategic partnerships with ASEAN distributors and portfolio diversification into men's grooming architectures.
Within the legacy conglomerate tier, Shiseido Company Ltd. and Kao Corporation exemplify divergent channel strategies. Shiseido anchors premium positioning through duty-free infrastructure and R&D-intensive quasi-drug portfolios. Kao occupies mass-tier volume through drugstore network density competing on accessibility. POLA Orbis Holdings represents the direct-to-consumer salon channel archetype, controlling full-service experiences that bypass wholesale margin structures. These three Japanese entities illustrate how domestic regulatory expertise translates into differentiated international expansion economics.
| Leading Market Players |
|---|
| POLA Orbis Holdings |
| Mandom Corporation |
| Shiseido Company Ltd. |
| Pias Corporation |
| Albion co, Ltd. |
| Kao Corporation |
| FANCL Corporation |
| Noeivir Holdings |
| KOSE Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in domestic Japanese fermentation substrate production is compressing supplier margins while elevating pricing leverage for heritage brands with captive agricultural cooperative relationships. This utilization dynamic forces mid-tier manufacturers to absorb input cost volatility or sacrifice quasi-drug certification investments.
Pricing Analysis
The customization-premium spread between configured-to-order salon formulations and standard retail SKUs widens as direct-to-consumer channels capture replenishment economics. Three-tier pricing structure across premium quasi-drug, standard hybrid, and economy mass tiers reflects certification investment depth. Pricing pressure stems from Southeast Asian social commerce platforms demanding margin concessions for algorithmic visibility. Gen Z consumers in Bangkok and Manila exhibit highest price sensitivity; professionals in Seoul and Tokyo accept premium positioning for dermatological validation.
Supply Chain Analysis
Tariff exposure between Japan and ASEAN member states dominates supply chain risk calculations for heritage formulations containing novel botanical actives. Manufacturing concentrates in Osaka and Tokyo biotech clusters, with secondary packaging and final assembly migrating to Vietnam and Thailand. Sake lees and koji-derived substrates draw from domestic Japanese agricultural cooperatives, creating single-source vulnerability for fermentation-forward brands. Distribution runs through platform-native direct-to-consumer channels alongside traditional duty-free corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
J-Beauty represents a high-growth disruption anchored by biotechnology advances in postbiotic complexes and regulatory harmonization across ASEAN cosmetic frameworks.
For Market Incumbents: Pre-empt platform-native entrants by securing exclusive TikTok Shop algorithm partnerships in Bangkok and Manila before mid-tier specialists replicate Shiseido's duty-free playbook. Deepen backward integration into domestic fermentation substrate production to insulate margin structures from agricultural cooperative pricing power. Quasi-drug certification velocity remains the critical defensive lever against clean-beauty challengers.
For New Entrants and Emerging Players: Vietnam's underpenetrated social commerce infrastructure in Ho Chi Minh City offers white-space acquisition costs below Indonesian and Thai equivalents. Target male grooming segments with simplified ritual architectures previously excluded from category marketing. Anchor go-to-market strategy through local influencer partnerships on emerging platforms rather than competing for department store counter space.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer salon-channel specialists with captive replenishment automation. Five-to-ten year viability favors asset-light licensing models with cross-border e-commerce financing access over capital-heavy retail buildouts. Monitor ASEAN harmonization implementation timelines as the inflection signal for accelerated market access economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Quasi-Drug Certification Acceleration | Japan's Ministry of Health, Labour and Welfare validation commands premium shelf positioning across Southeast Asian retail channels. |
| Direct-to-Consumer Platform Integration | TikTok Shop and Instagram commerce integrations enable replenishment models that bypass wholesale margin structures in Bangkok. |
| Fermentation Biotechnology Investment | Bioreactor-cultured exosomes migrate professional salon efficacy claims into mass-market retail economics. |
| Men's Grooming Portfolio Extension | Gender-neutral formulation architectures capture male professional consumers previously excluded from category marketing. |
| ASEAN Regulatory Harmonization Alignment | METI export promotion programs reduce technical documentation burdens for manufacturers scaling beyond domestic production. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with brand managers, category buyers at Southeast Asian retailers, fermentation biotechnology R&D directors, and regulatory affairs specialists; and secondary validation through Japan's Ministry of Health, Labour and Welfare quasi-drug filings, ASEAN cosmetic regulatory harmonization documentation, METI export promotion program disclosures, and customs trade records. Bottom-up demand modeling triangulated against top-down market sizing across product type, formulation, distribution channel, and customer demographic dimensions.
Forecast inputs considered quasi-drug certification pipeline velocity, social commerce platform penetration rates in named Southeast Asian urban centers, and fermentation substrate supply constraints from domestic Japanese agricultural cooperatives. Segmentation modeling captured skincare, makeup, haircare, and body care architectures across natural, hybrid, organic, and synthetic formulation tiers. CAGRs were derived from regression analysis of historical adoption curves and projected regulatory harmonization impacts across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in ASEAN consumer discretionary spending or yen-denominated input cost volatility would shift the trajectory. Forecasts reflect documented assumptions about platform algorithm efficacy and regulatory approval timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
Global Cosmetic Antioxidant Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Europe Bath Soap Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Anti-Pollution Skin Care Products Market
Cosmetics & Skincare
Detox Face Oil Market
Cosmetics & Skincare
Epigenetic Cosmetic Products Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Makeup Remover Market