
 Dbaas and Cloud Database Market | 2026-2036
Dbaas and Cloud Database Market Size, Share, and Industry Trends Forecast 2026-2036
Dbaas and Cloud Database Market Analysis
The gap between premium managed offerings and commodity compute tiers is shifting as enterprise buyers demand SLA-backed automation, serverless scaling, and built-in compliance tooling rather than raw infrastructure. Amazon Web Services leverages its first-mover infrastructure footprint to sustain pricing power across relational and NoSQL workloads. Microsoft anchors enterprise trust through deep Azure integration with existing productivity stacks. Google competes on analytical performance, differentiating BigQuery and Spanner for high-concurrency workloads.
Database as a Service and Cloud Database denotes cloud-hosted data management systems delivered via subscription, encompassing automated provisioning, patching, backup, and scaling across distributed nodes with latency targets typically below ten milliseconds for transactional workloads. The architecture eliminates capital-intensive on-premises hardware while enabling elastic capacity for variable query loads. Public cloud deployments capture the dominant share of new workloads, though hybrid configurations are gaining traction among regulated sectors requiring on-premise data sovereignty. NoSQL databases represent the fastest-expanding database type segment, driven by unstructured data proliferation in IoT and mobile applications, while relational databases retain the largest margin pool from legacy enterprise migrations.
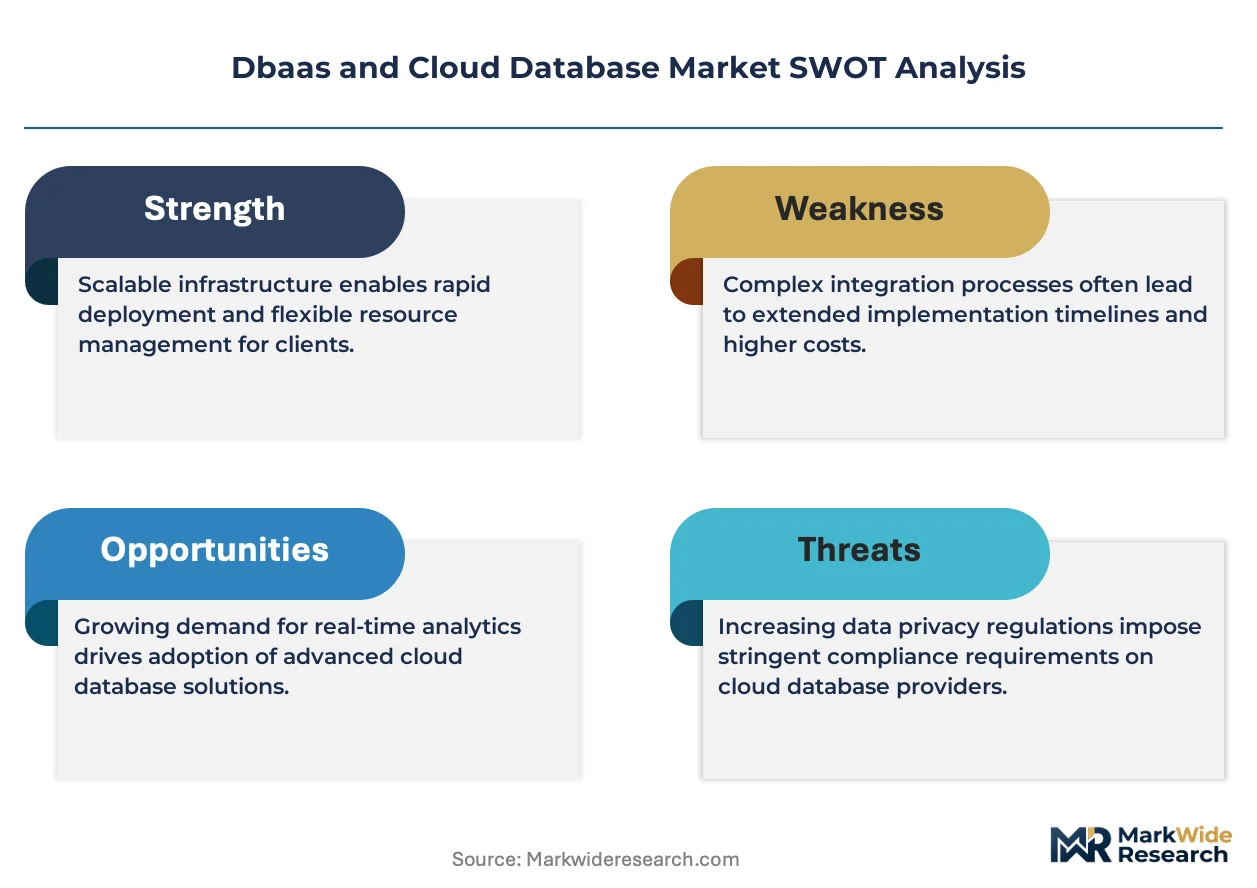
The EU AI Act, GDPR, and ISO 27001 framework collectively reshape vendor roadmaps by mandating explainable automated decisions, cross-border data governance, and certified information security management. The Federal Risk and Authorization Management Program in the United States imposes additional compliance burdens on providers seeking federal contracts. Stakeholders must weigh regional certification requirements against platform consolidation benefits when selecting multi-cloud architectures.
Market Dynamics
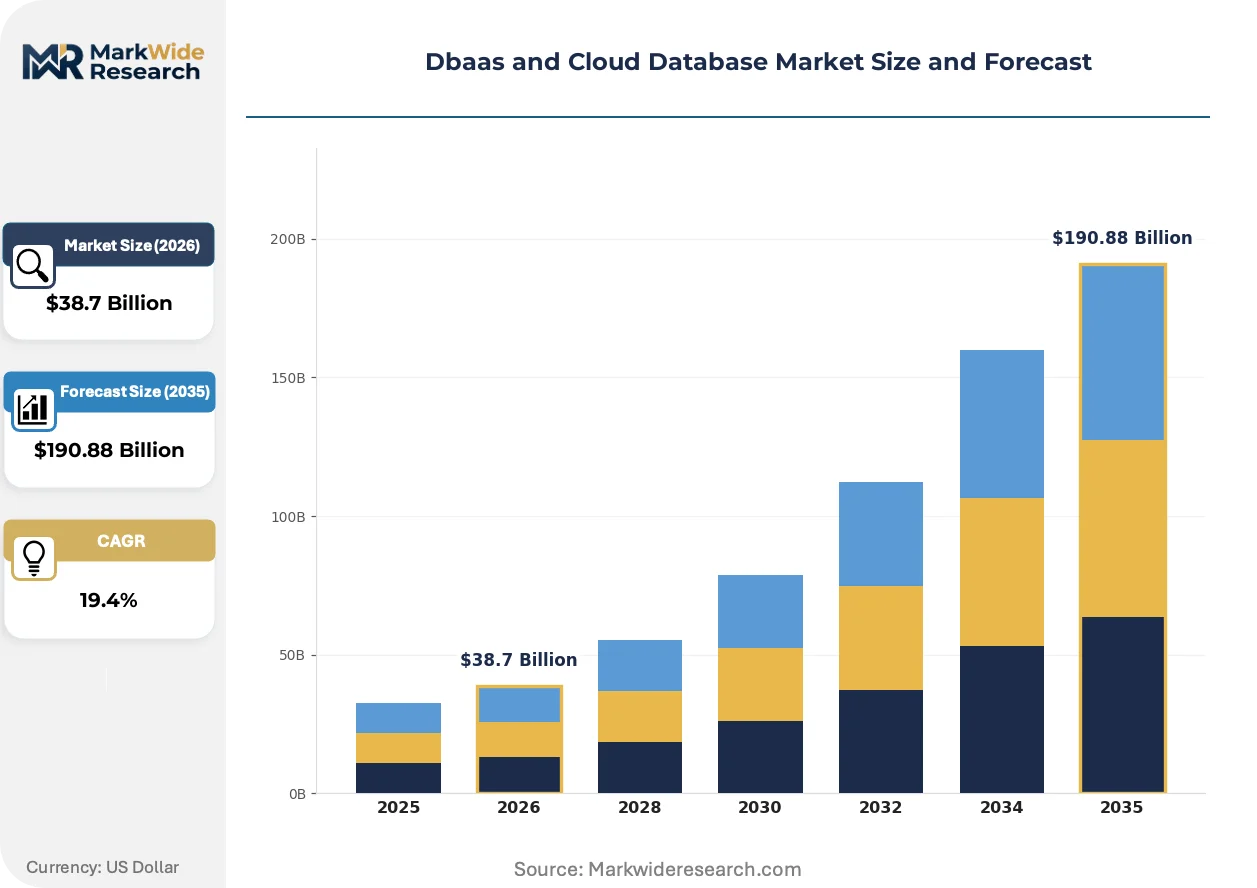
Enterprise migration from capital-intensive on-premises infrastructure to consumption-based cloud database models is compressing procurement cycles and forcing vendors to embed compliance automation directly into managed service tiers.
Growth Catalysts
- GDPR and EU AI Act mandates:Financial services and healthcare enterprises across Germany, France, and Italy are accelerating adoption of managed database services with built-in data residency controls and algorithmic audit trails.
- Serverless architecture proliferation:Development teams in SaaS and mobile gaming verticals are abandoning provisioned capacity models in favor of autoscaling query engines that eliminate capacity planning overhead.
- Unstructured data explosion:IoT sensor networks and generative AI training pipelines are generating petabyte-scale document and vector workloads that exceed relational database design limits.
Market Restraints
- Hyperscaler concentration risk:Three US-based cloud providers control the majority of managed database infrastructure, creating single points of failure and limiting buyer negotiating leverage.
- Egress cost volatility:Data transfer fees between cloud regions and on-premises environments can exceed compute costs, penalizing hybrid architectures and multi-cloud strategies.
- Latency floor constraints:Distributed consensus protocols impose theoretical minimums on transactional response times that conflict with sub-millisecond requirements in high-frequency trading and telco billing systems.
Strategic Opportunities
- Edge database deployment:Manufacturing and autonomous vehicle developers in Japan and South Korea are deploying lightweight SQL engines at factory floors and vehicle gateways to reduce round-trip latency.
- Vector database integration:Convergence of retrieval-augmented generation pipelines with operational datastores is creating new product categories for embedding search alongside transactional workloads.
- India's data localization requirements:RBI and MeitY mandates for financial and government data residency are compelling hyperscalers to establish in-country managed database regions with sovereign controls.
Industry Challenges
- Distributed systems engineering scarcity:Database reliability engineering and chaos testing expertise remains concentrated among senior practitioners at Silicon Valley and Tel Aviv technology firms.
- Legacy mainframe migration complexity:COBOL and IMS workloads at US federal agencies and European banks require specialized tooling and multi-year transformation programs that strain IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dbaas and Cloud Database Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Model: Database as a Service, Backup as a Service, Managed Database, Serverless Database Database Type: Relational Database, NoSQL Database, In-Memory Database, Graph Database End User: SMEs, Large Enterprises, Government, Educational Institutions |
| Companies Covered | Amazon Web Services, Microsoft, Google, IBM, Oracle, Alibaba Cloud, Snowflake, MongoDB, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dbaas and Cloud Database Market Emerging Trajectories
Database architectures are fragmenting into specialized engines optimized for specific workload patterns rather than converging on universal platforms. This specialization is forcing vendors to integrate cross-engine query federation and unified control planes.
Disaggregated storage-compute architectures are modularizing the traditional monolithic database stack into independently scalable layers. Financial services firms with spiky analytical workloads are adopting these designs to decouple expensive compute from persistent storage. The separation is modularizing vendor business models and enabling consumption-based pricing that aligns costs with actual query execution rather than provisioned capacity.
REACH chemical substance restrictions and emerging EU battery passport requirements are extending supply chain traceability mandates into database schema design. Industrial manufacturers must now embed material provenance and carbon intensity fields into operational datastores. German automotive suppliers and French aerospace subcontractors are rebuilding master data management architectures to satisfy these audit requirements.
Enterprise buyers are unbundling database procurement from hyperscaler compute contracts and negotiating direct relationships with specialized database vendors. This disintermediation is most pronounced among Series C and public SaaS companies in the United States that have reached sufficient scale to justify dedicated database infrastructure teams. The shift is compressing sales cycles for independent vendors while eroding the attach rate of bundled managed services.
Dbaas and Cloud Database Market Segmentation
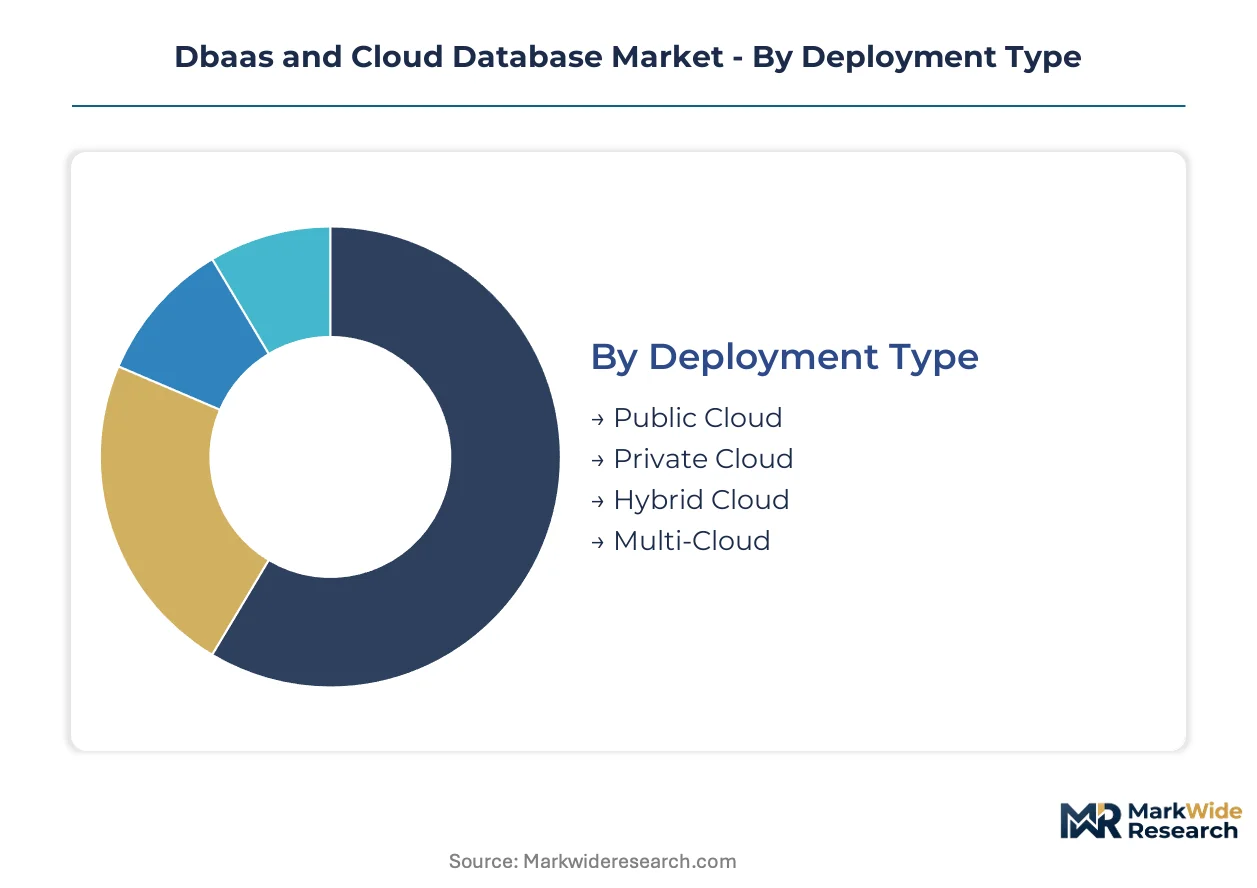
Database architecture choices directly determine compliance posture, latency boundaries, and operational cost structures. Segmentation reveals where enterprise buyers concentrate spending versus where emerging workloads are migrating.
Deployment Type:
Volume deployment favors standardized configurations with minimal customization overhead. Premium deployment demands sovereign controls and contractual data residency guarantees.
- Public Cloud:Shared infrastructure pools deliver elastic capacity with sub-ten-millisecond latency targets for transactional workloads. Financial services firms in the United States and Germany are standardizing on public managed services for non-regulated tier-2 applications, driven by serverless autoscaling economics.
- Private Cloud:Dedicated single-tenant environments enforce hardware-level isolation for classified workloads. Defense contractors and European pharmaceutical manufacturers with EMA audit requirements are consolidating procurement around private deployments to satisfy data sovereignty mandates.
- Hybrid Cloud:Split architectures place hot transactional data on-premises while archiving cold analytics to cloud object storage. Japanese automotive suppliers leverage hybrid configurations to keep factory-floor sensor data local while feeding aggregate training sets to cloud ML pipelines.
- Multi-Cloud:Orchestrated deployments across independent hyperscalers eliminate single-provider concentration risk. Series C SaaS vendors with federal contract ambitions are adopting multi-cloud to satisfy FedRAMP redundancy requirements without vendor lock-in.
Mature deployment sits with Public Cloud. Newer deployment is concentrated in Multi-Cloud.
Service Model:
Margin concentration follows automation depth. Higher-automation tiers command pricing premiums through reduced engineering overhead.
- Database as a Service:Fully abstracted platforms handle provisioning, patching, and backup without customer intervention. Indian fintech startups under RBI data localization mandates are adopting DBaaS from in-country hyperscaler regions to compress time-to-market.
- Backup as a Service:Point solutions automate snapshot scheduling, cross-region replication, and granular recovery workflows. Healthcare systems in France facing ANSM clinical data retention rules are prioritizing BaaS for audit-ready restore capabilities.
- Managed Database:Human-in-the-loop operations teams handle performance tuning and incident response for complex workloads. German automotive OEMs with legacy SAP HANA estates are contracting managed services to bridge skills gaps in distributed systems engineering.
- Serverless Database:Consumption-priced query engines eliminate capacity planning through autoscaling compute and storage independently. Mobile gaming studios with spiky concurrent user patterns are standardizing on serverless to align infrastructure costs with session-based revenue.
Revenue scale favors Managed Database. Expansion is climbing fastest in Serverless Database.
Database Type:
Workload specialization is fragmenting the universal database ideal. Engine selection now hinges on data structure, consistency requirements, and query pattern.
- Relational Database:ACID-guaranteed tabular stores with SQL interfaces dominate legacy migration pipelines. US federal agencies modernizing COBOL workloads are prioritizing PostgreSQL-compatible managed services to preserve existing application logic.
- NoSQL Database:Schema-flexible document, key-value, and wide-column engines absorb unstructured data at petabyte scale. IoT platform vendors in South Korea are deploying MongoDB-compatible clusters to ingest manufacturing sensor streams without predefined schemas.
- In-Memory Database:DRAM-resident data structures deliver microsecond response times for real-time analytics. Telco billing systems in Japan require in-memory engines to process prepaid account updates within strict latency floors.
- Graph Database:Native storage of node-edge relationships accelerates traversal queries for network analysis. Fraud detection teams at Italian banks are adopting graph engines to map transaction webs and identify synthetic identity clusters.
Installed base concentrates in Relational Database. Vector-augmented workloads are gaining share fastest in NoSQL Database.
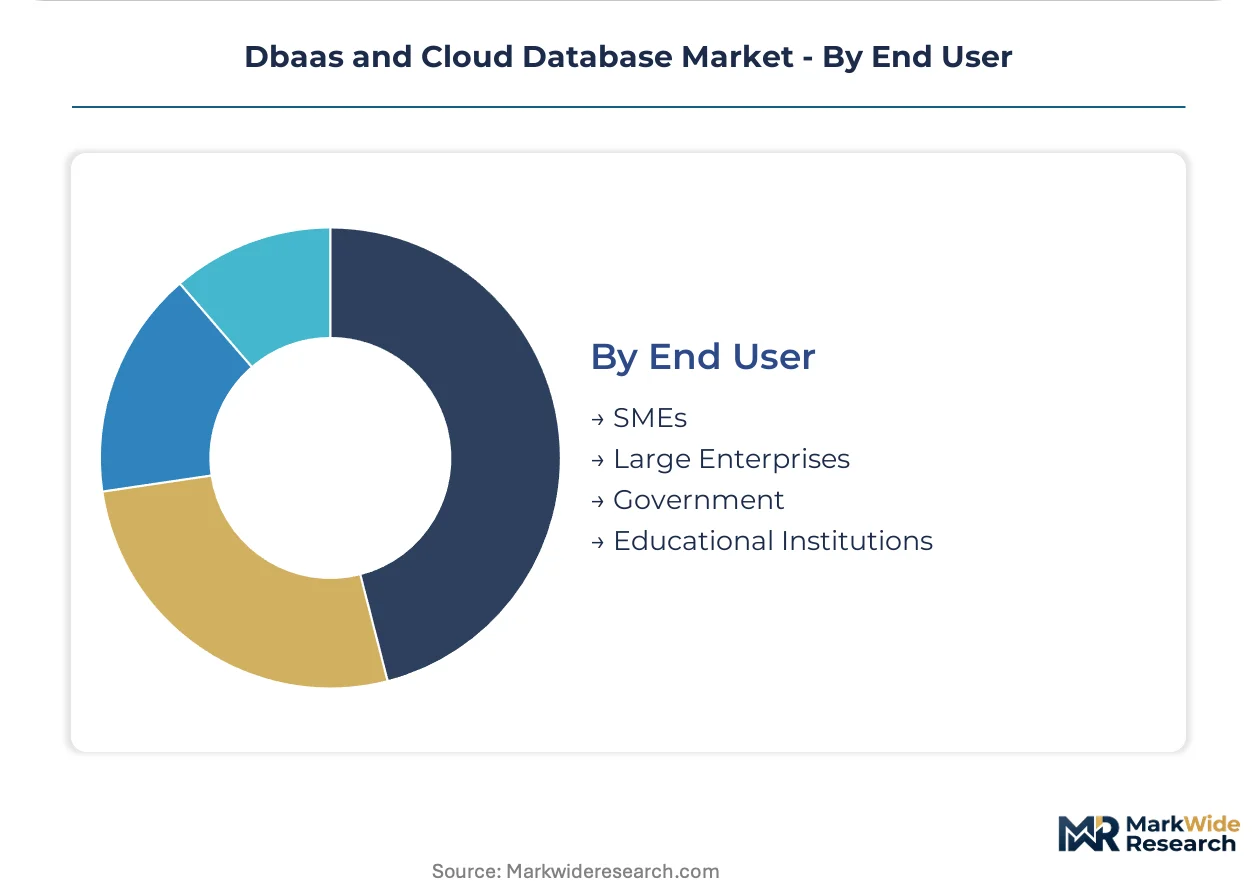
End User:
Procurement sophistication varies sharply by organizational scale and regulatory exposure.
- SMEs:Resource-constrained teams prioritize fully managed tiers with minimal operational overhead. Brazilian e-commerce marketplace sellers are adopting serverless PostgreSQL to avoid database administration hiring.
- Large Enterprises:Dedicated infrastructure teams negotiate custom SLAs and private connectivity options. Swiss pharmaceutical multinationals with Swissmedic validation requirements are contracting directly with database vendors to bypass hyperscaler bundling.
- Government:Sovereign cloud mandates and classified workload isolation dominate selection criteria. UAE federal entities under MOHAP health data rules are requiring in-country encryption key custody for all database deployments.
- Educational Institutions:Grant-funded research groups prioritize cost optimization and open-source compatibility. Australian universities with ARC linkage grants are standardizing on cloud-native PostgreSQL for reproducible computational research.
Contract value peaks with Large Enterprises. Account growth is expanding most quickly in SMEs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the densest concentration of cloud database engineering talent and hyperscaler headquarters, while enterprise adoption spreads through financial centers and manufacturing corridors worldwide.
United States
Financial services firms in New York and Chicago are migrating legacy mainframe workloads to managed PostgreSQL services under FedRAMP authorization requirements. The SEC and CFTC are tightening audit trail mandates for algorithmic trading databases. Seattle hosts AWS's primary engineering campus, where serverless database development cycles compress quarterly release schedules.
Germany
Automotive OEMs in Stuttgart and Munich require sub-millisecond latency for connected vehicle telemetry streams. The KBA and BSI are enforcing ISO 27001 certification for cloud databases processing vehicle safety data. Frankfurt's financial district concentrates demand for sovereign cloud instances with contractual data residency guarantees.
India
Bengaluru's fintech startups are adopting in-country DBaaS regions to satisfy RBI data localization mandates for payment transaction logs. MeitY's cloud security guidelines are forcing hyperscalers to establish dedicated encryption key custody within Indian territory. Mumbai's banking consortiums are negotiating direct contracts with database vendors to bypass bundled hyperscaler pricing.
Japan
Tokyo's telecommunications operators require in-memory databases for prepaid billing systems with strict latency floors under METI operational standards. Osaka's manufacturing automation sector deploys edge SQL engines at factory floors to reduce round-trip latency for quality control systems. The PMDA is extending audit requirements to clinical trial databases hosted on cloud infrastructure.
United Kingdom
London's hedge funds are standardizing on multi-cloud database architectures to eliminate single-provider concentration risk under FCA operational resilience rules. Edinburgh's fintech clusters demand vector database integration for fraud detection pipelines. The Information Commissioner's Office is enforcing GDPR Article 44 transfer mechanism documentation for cross-border database replication.
Dbaas and Cloud Database Market Vendor Landscape
Capital-heavy hyperscalers compete with asset-light specialized database vendors for enterprise workload contracts. The market structure concentrates around three US-based infrastructure providers controlling majority capacity, with independent vendors carving vertical niches through workload-specific optimization. Strategic archetypes include full-stack cloud operators, open-source commercializers, and analytical engine specialists. Dominant competitive moves encompass sovereign cloud region expansion and disaggregated storage-compute architecture licensing.
Among full-stack hyperscalers, Amazon Web Services, Microsoft, and Google occupy positions defined by infrastructure footprint depth and enterprise integration breadth. MongoDB exemplifies the open-source commercialization archetype, while Snowflake anchors the analytical performance tier. These named entities represent strategic positioning patterns rather than exhaustive market enumeration.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Oracle |
| Alibaba Cloud |
| Snowflake |
| MongoDB |
| SAP |
| Others |
Supply Flow & Price Mechanics
Distributed systems engineering talent concentrated in Silicon Valley and Tel Aviv creates labor-cost differentials that widen pricing-tier spreads between premium managed services and commodity infrastructure tiers.
Pricing Analysis
Uptime-guaranteed SLAs anchor value-based pricing for enterprise database contracts. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-cloud deployments with data residency guarantees from shared public infrastructure. Cost compression in the standard tier is intensifying because hyperscalers are bundling database services with compute commitments. SMEs exhibit highest price sensitivity and gravitate toward serverless consumption models; large enterprises with FedRAMP requirements accept premium pricing for contractual isolation.
Supply Chain Analysis
Dual-sourcing requirements from Series C SaaS vendors with federal contract ambitions are forcing hyperscalers to qualify secondary infrastructure partners across independent regions. Hardware supply concentrates in Taiwan for advanced semiconductors, South Korea for memory components, and the United States for specialized networking equipment. Raw material dependencies span silicon wafers, DDR5 memory modules, and optical transceivers. Single-source vulnerability around custom AI accelerators threatens capacity expansion timelines. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-automation capabilities, with the EU AI Act and GDPR enforcement timelines forcing subscale vendors toward exit or acquisition.
For Market Incumbents: To counter disintermediation by enterprise buyers unbundling database procurement from hyperscaler contracts, AWS and Microsoft should deepen sovereign cloud region expansion in India and Germany. Certification investment in ISO 27001 and FedRAMP High anchors renewal pricing power against independent vendors. For New Entrants and Emerging Players: RBI data localization mandates in India open a window for specialized database vendors to capture fintech workloads escaping bundled hyperscaler pricing. The most penetrable segment sits with mobile gaming studios requiring serverless autoscaling for spiky concurrent user patterns. A direct sales model targeting CTOs at Series B gaming companies bypasses channel conflict with established distributors. For Investors and Strategic Acquirers: Re-rating potential sits with vector database specialists given retrieval-augmented generation pipeline integration with operational datastores. Over a five-to-ten-year horizon, these vendors capture margin expansion from AI workload convergence. The acquisition target archetype combines edge SQL engine capabilities with automotive telemetry expertise. The signal to watch is PMDA audit requirement extensions to cloud-hosted clinical trial databases in Japan.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Region Expansion | Hyperscaler establishment of in-country database regions satisfies RBI and MeitY mandates for Indian financial data residency. |
| Disaggregated Storage-Compute Licensing | Modular architecture licensing enables consumption-based pricing alignment with actual query execution for spiky analytical workloads. |
| Vector Database Integration | Embedding search convergence with transactional workloads creates new product categories for RAG pipeline optimization. |
| Edge Database Deployment | Lightweight SQL engines at factory floors reduce round-trip latency for Japanese automotive quality control systems. |
| Direct Enterprise Contracting | Bypassing hyperscaler bundling compresses sales cycles for independent vendors targeting Swiss pharmaceutical multinationals. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with SEC filings, hyperscaler capex disclosures, and cloud infrastructure spending surveys. Bottom-up deployment type modeling and top-down market sizing triangulated value estimates across the analysis window.
Granularity-level framing segmented the market by deployment type, service model, database type, and end user organization size. CAGRs derived from regression analysis against hyperscaler infrastructure investment trajectories and enterprise migration pipeline data. Forecast inputs incorporated serverless adoption curves and vector database workload penetration assumptions throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for edge database deployment would alter the outlook. Forecasts reflect assumptions about GDPR and EU AI Act enforcement intensity. A model refresh is warranted upon material change in RBI data localization mandate scope or FedRAMP authorization timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Saudi Arabia Cloud Services Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Cloud IDE Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Cloud Management Market
Cloud Computing
Commercial Cloud Market
Cloud Computing
Automotive Cloud Based System Market