
 Cognitive Computing Market | 2026-2036
Cognitive Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Computing Market Analysis
Modular platform bundling is restructuring buyer choice in cognitive computing procurement. IBM Corporation leverages its Watson ecosystem to anchor enterprise clients seeking integrated AI governance layers. Microsoft competes through Azure OpenAI service bundles that extend cloud infrastructure into conversational AI workflows. Google specializes in deep learning accelerators and custom silicon that dominates training-intensive workloads.
Cognitive computing denotes systems that simulate human thought processes—pattern recognition, natural language inference, probabilistic reasoning—using neural architectures, knowledge graphs, and iterative feedback loops to automate complex decision tasks across unstructured data environments. Natural language processing applications lead current deployment volumes as enterprises automate document-intensive workflows in legal and customer service functions. Cloud-based deployment is accelerating fastest among mid-market buyers seeking to avoid capital-intensive on-premises GPU clusters. Edge computing configurations remain nascent but occupy strategic importance in manufacturing and autonomous systems where latency constraints override cloud economics.
The EU AI Act, FDA software-as-medical-device guidance, and China's SAMR algorithmic recommendation provisions collectively reshape product standards and market access pathways for cognitive computing vendors. HIPAA in the United States imposes additional data governance requirements that constrain how healthcare-facing cognitive systems ingest and process protected health information. Stakeholders must monitor divergence between risk-classification frameworks across jurisdictions to avoid compliance fragmentation that inflates engineering overhead.
Market Dynamics
Modular platform architectures are restructuring buyer decision frameworks across cognitive computing procurement, forcing vendors to bundle governance layers with core inference capabilities or risk displacement by integrated cloud-native alternatives.
Growth Catalysts
- FDA software-as-medical-device guidance:Clarified approval pathways accelerate cognitive diagnostic tools into clinical workflows, reducing regulatory uncertainty for healthcare AI developers.
- Healthcare diagnostic imaging:Radiology departments deploy neural architectures for lesion detection and triage prioritization, creating sustained demand for training-intensive GPU clusters.
- United States federal R&D incentives:Tax credits and grant programs channel capital toward domestic AI infrastructure, concentrating enterprise deployment decisions in North American data centers.
Market Restraints
- NVIDIA GPU supply concentration:Training workload dependence on a single silicon supplier creates input cost volatility and allocation risk for model development pipelines.
- EU AI Act algorithmic transparency mandates:High-risk system documentation requirements inflate engineering overhead and extend product launch timelines for European market access.
- On-premises infrastructure substitution:Cloud-based deployment alternatives displace capital-intensive private GPU clusters among mid-market buyers with limited IT budgets.
Strategic Opportunities
- Edge computing manufacturing applications:Latency-constrained quality inspection and predictive maintenance workflows in automotive and electronics assembly lines remain underpenetrated.
- Natural language processing legal automation:Contract analysis and discovery tools represent emerging application white space as law firms seek document-intensive workflow compression.
- China SAMR algorithmic recommendation provisions:Compliance tooling and audit services for content platforms create regulatory tailwind demand for transparency and explainability modules.
Industry Challenges
- Machine learning operations talent scarcity:Shortage of engineers capable of deploying production-grade inference pipelines at scale constrains vendor implementation velocity.
- HIPAA technical safeguard integration:Healthcare-facing systems require encrypted data flows and access logging that complicates cloud-native architecture adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Computing Market |
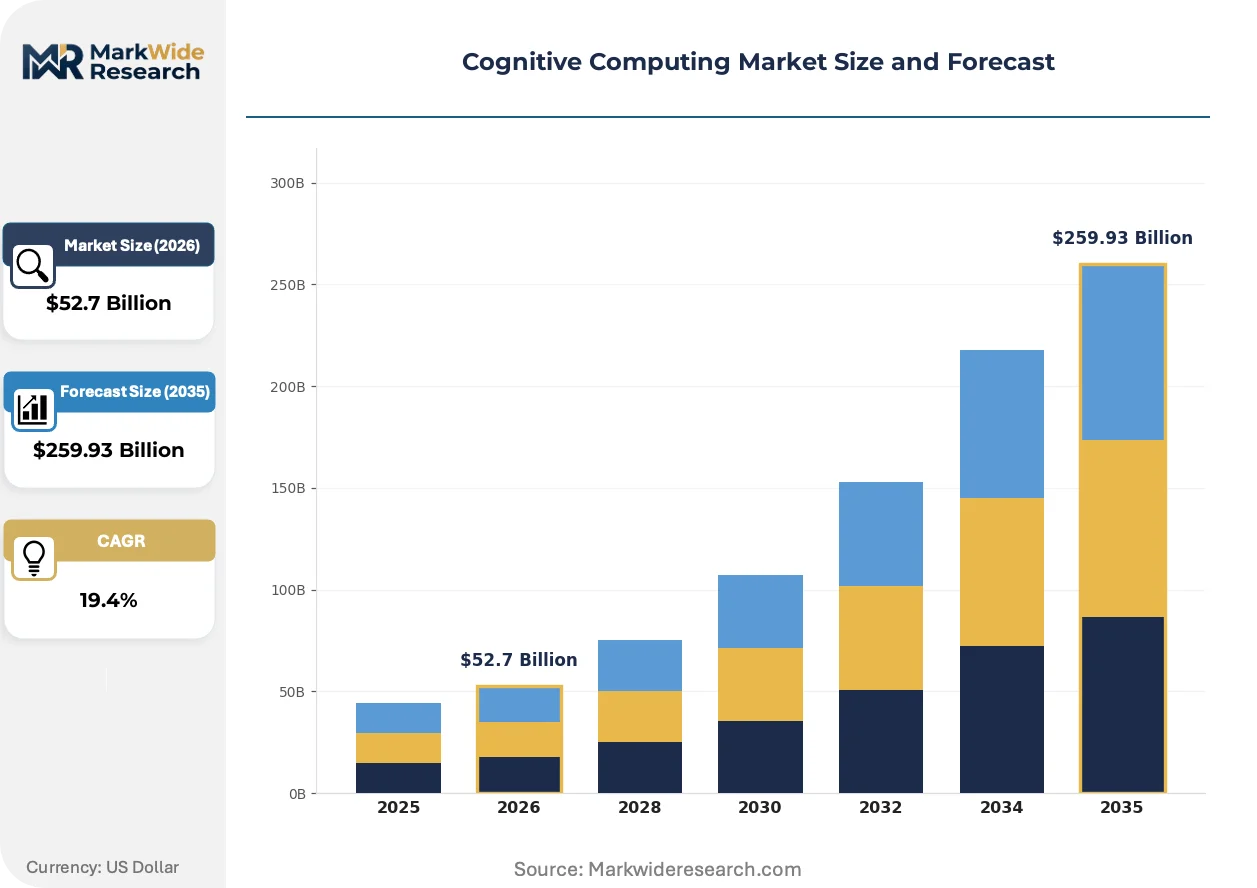
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $259.93 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, Edge Computing End User: Healthcare, BFSI, Retail, Government Application: Virtual Assistants, Data Analytics, Image Recognition, Natural Language Processing Solution: AI Platforms, Machine Learning, Deep Learning, Cognitive Analytics |
| Companies Covered | IBM Corporation, Microsoft, Google, Amazon Web Services, SAS Institute, Oracle Corporation, Tata Consultancy Services, CognitiveScale, SparkCognition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Computing Market Emerging Trajectories
Neural architecture search and automated model compression are compressing development cycles, while regulatory pressure on algorithmic accountability is forcing transparency features into product roadmaps ahead of commercial readiness.
Transformer-based large language models are expanding into enterprise document processing, automating contract review, customer correspondence, and knowledge base queries. Legal departments and shared service centers adopt these tools aggressively, compressing headcount requirements for routine text analysis while elevating demand for prompt engineering and output validation workflows.
The EU AI Act risk classification framework is mandating conformity assessments and post-market monitoring for high-risk cognitive systems. Healthcare and financial services deployments face the steepest compliance burden, with vendors restructuring product documentation and audit trail capabilities to satisfy notified body review timelines.
Buyer preference for consumption-based pricing is displacing perpetual license models in mid-market cognitive computing procurement. Managed service providers and system integrators capture margin by bundling cloud infrastructure, model tuning, and ongoing maintenance into single-vendor relationships, with this pattern most visible in United States professional services and insurance verticals.
Cognitive Computing Market Segmentation
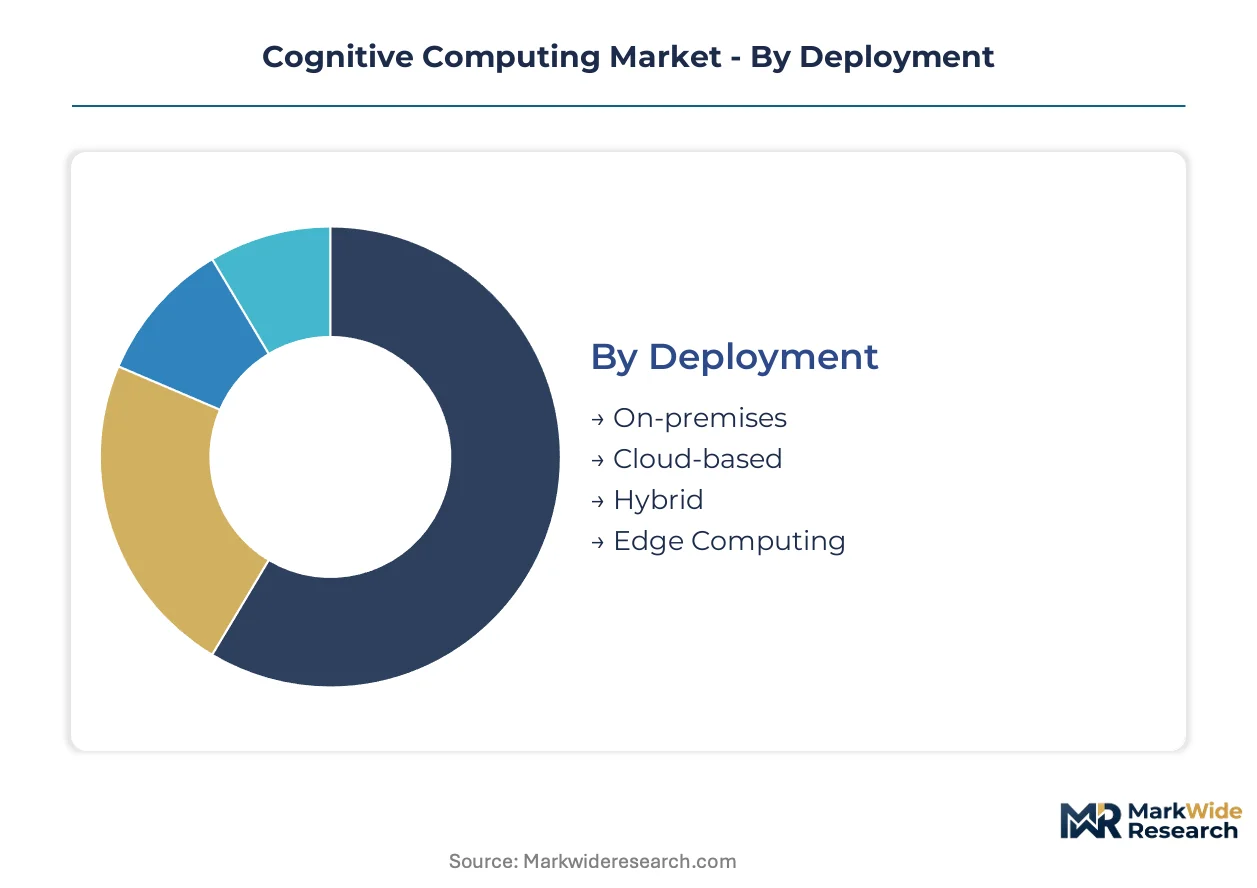
Cognitive computing vendors structure product portfolios around deployment flexibility and vertical specialization. Segment boundaries determine pricing architecture, compliance obligations, and sales channel selection across healthcare, financial services, and public sector procurement cycles.
Deployment:
Supply concentration in GPU manufacturing and hyperscaler infrastructure shapes deployment economics across enterprise buyers.
- On-premises:Dedicated server clusters with NVIDIA A100/H100 accelerators support classified workloads and HIPAA-regulated healthcare data. United States federal agencies and defense contractors mandate air-gapped environments for sensitive inference tasks, sustaining demand despite capital intensity.
- Cloud-based:Hyperscaler-managed GPU instances eliminate upfront hardware investment. Mid-market legal departments and insurance underwriters in the United States gravitate toward consumption-based Azure and AWS offerings to bypass infrastructure procurement cycles.
- Hybrid:Split architectures keep training workloads in cloud environments while inference runs locally. Manufacturing quality control systems in automotive assembly plants adopt this pattern to balance model iteration speed with production floor latency requirements.
- Edge Computing:Embedded inference chips in camera modules and industrial sensors enable real-time defect detection. Autonomous vehicle perception stacks and warehouse robotics drive early adoption despite limited software maturity.
Cloud-based deployments absorb the bulk of installed capacity; edge computing configurations are expanding most quickly.
End User:
Regulatory density varies sharply across verticals, determining documentation burdens and sales cycle length.
- Healthcare:FDA software-as-medical-device pathways govern diagnostic imaging and clinical decision support. Radiology departments deploy lesion detection algorithms under 510(k) clearance requirements, with HIPAA technical safeguards constraining cloud architecture choices.
- BFSI:Anti-money laundering transaction monitoring and credit risk scoring dominate procurement. United States banks face SEC and FFIEC guidance on model risk management, elevating demand for explainability tooling.
- Retail:Demand forecasting and personalized recommendation engines drive adoption. E-commerce platforms optimize inventory positioning across distribution networks using neural demand models.
- Government:Fraud detection in benefit administration and predictive maintenance for infrastructure assets anchor public sector deployments. Procurement runs through certified vendor schedules with extended security clearance requirements.
Healthcare commands the deepest compliance investment; BFSI shows the steepest budget expansion trajectory.
Application:
Functional specialization determines model architecture selection and hardware provisioning ratios.
- Natural Language Processing:Transformer-based document analysis automates contract review and customer correspondence workflows. Legal departments and shared service centers compress headcount for routine text processing while adding prompt engineering roles.
- Image Recognition:Convolutional neural networks power radiological lesion detection and manufacturing quality inspection. Training pipelines require substantial GPU cluster investment relative to deployment scale.
- Virtual Assistants:Conversational interfaces handle tier-one customer service escalation and internal IT helpdesk queries. Banking call centers deploy these tools to reduce average handle time metrics.
- Data Analytics:Pattern discovery across unstructured operational data supports supply chain optimization and predictive maintenance. Industrial equipment manufacturers embed these capabilities in service contract offerings.
Natural language processing holds the largest active deployment base; image recognition is climbing the fastest on diagnostic imaging demand.
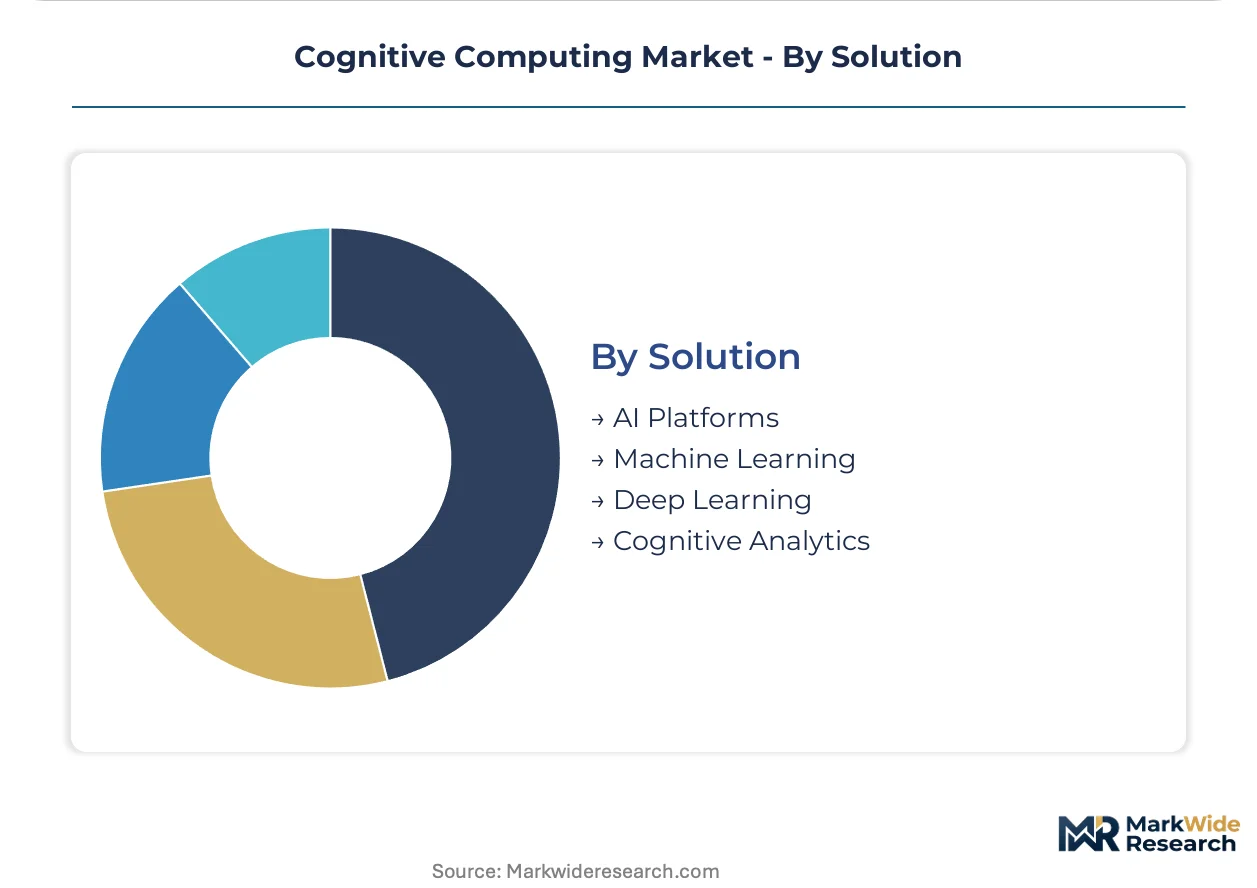
Solution:
Technology layer abstraction determines buyer technical sophistication requirements and implementation risk profiles.
- AI Platforms:Integrated development environments with model versioning, experiment tracking, and governance dashboards. Enterprise IT organizations standardize on these tools to consolidate fragmented data science tooling.
- Deep Learning:Neural architecture search and automated hyperparameter optimization for computer vision and speech recognition tasks. Autonomous system developers and medical imaging startups anchor demand.
- Machine Learning:Classical algorithm libraries and automated feature engineering for structured data prediction. Credit scoring and demand forecasting applications favor these approaches for interpretability requirements.
- Cognitive Analytics:Knowledge graph construction and probabilistic reasoning engines for complex decision support. Regulatory compliance and fraud investigation workflows exploit these capabilities for audit trail generation.
AI platforms capture the majority of enterprise spending; deep learning is gaining share fastest on generative model demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates cognitive computing infrastructure investment while China scales domestic model development. Europe tightens algorithmic governance frameworks. Japan and India expand enterprise adoption through cloud partnerships and IT services channels.
United States
Federal R&D tax credits and NIH AI research grants channel capital toward domestic GPU clusters and healthcare diagnostic tools. FDA software-as-medical-device guidance clarifies approval pathways for clinical decision support systems. The San Francisco Bay Area and Seattle anchor hyperscaler headquarters and venture-backed model development labs.
China
SAMR algorithmic recommendation provisions and dual carbon goals reshape compliance requirements for content platforms and data center operators. MIIT domestic cloud procurement preferences favor indigenous AI infrastructure vendors. The Yangtze River Delta and Pearl River Delta concentrate fintech and smart manufacturing cognitive deployments.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg deploy edge inference for quality inspection and predictive maintenance workflows. The EU AI Act risk classification framework mandates conformity assessments for high-risk industrial AI systems. Berlin hosts regulatory technology startups addressing algorithmic transparency tooling.
Japan
METI AI governance guidelines and aging workforce demographics accelerate robotic process automation and clinical decision support adoption. PMDA digital therapeutics pathways open regulatory channels for cognitive diagnostic tools. The Tokyo-Osaka corridor concentrates enterprise IT services and semiconductor packaging for AI accelerators.
India
IT services exporters in Bengaluru and Hyderabad build cognitive practices around contract analysis and customer service automation for North American and European clients. RBI model risk management guidance elevates demand for explainability tooling in financial services. PLI scheme incentives attract hyperscaler data center investment.
Cognitive Computing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the cognitive computing landscape. Hyperscaler cloud platforms anchor enterprise procurement through integrated infrastructure bundles. Specialized AI vendors concentrate on vertical compliance and edge deployment niches. Strategic moves center on M&A for talent acquisition and partnership structures for geographic market entry.
Within the hyperscaler tier, IBM Corporation and Microsoft occupy positions as diversified technology conglomerates with governance-integrated platform offerings. Google exemplifies the deep learning infrastructure specialist archetype through custom silicon development. These three anchors demonstrate how vendor archetypes align with buyer procurement priorities across regulated and latency-sensitive deployment scenarios.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft |
| Amazon Web Services |
| SAS Institute |
| Oracle Corporation |
| Tata Consultancy Services |
| CognitiveScale |
| SparkCognition |
| Others |
Supply Flow & Price Mechanics
NVIDIA H100 GPU spot price volatility cascades through cognitive computing procurement tiers, compressing margins for training-intensive deployments while hyperscaler cloud bundles absorb cost shocks through scale economics. Buyers face tiered access determined by silicon allocation priority and compliance certification levels.
Pricing Analysis
Margin tightening in on-premises deployments reflects NVIDIA accelerator allocation scarcity and extended lead times for A100/H100 clusters. Three-tier pricing structure across premium, standard, and economy levels separates air-gapped government workloads from consumption-based cloud instances and shared public GPU pools. HIPAA-certified healthcare configurations command substantial premiums over standard enterprise tiers. Mid-market legal departments exhibit highest price sensitivity, gravitating toward Azure and AWS consumption models to bypass capital procurement cycles.
Supply Chain Analysis
FDA software-as-medical-device qualification and EU AI Act conformity assessment gating create dual certification burdens for healthcare-facing silicon suppliers. Taiwan Semiconductor Manufacturing anchors advanced node production for NVIDIA and Google custom accelerators, while South Korea's Samsung Foundry and SK Hynix supply HBM memory stacks. Single-source dependency on NVIDIA for training-optimized GPUs constitutes the dominant structural vulnerability. Distribution runs through hyperscaler direct procurement, OEM server integrators, and specialized AI infrastructure resellers serving classified federal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cognitive computing vendor consolidation accelerates as regulatory compliance burdens and GPU supply concentration force subscale players toward exit or acquisition. The EU AI Act documentation requirements and HIPAA technical safeguard investments disproportionately strain engineering resources at firms below $50 million annual R&D spend.
For Market Incumbents: Extend governance-integrated platform bundling to capture mid-market buyers fleeing capital-intensive infrastructure ownership. IBM and Microsoft anchor this strategy through Watson and Azure OpenAI service ecosystems. Defensive moves should prioritize backward integration into custom silicon development or captive cloud capacity reservations to secure GPU allocation priority against emerging challengers.
For New Entrants and Emerging Players: Edge inference optimization for manufacturing quality inspection offers the most penetrable white space, as automotive and electronics assembly lines remain underserved by latency-tolerant cloud alternatives. A regulatory technology positioning—selling algorithmic transparency audit tooling for EU AI Act compliance—opens channel access without direct hyperscaler confrontation. Channel partnerships with system integrators accelerate credentialing for federal procurement schedules.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical AI specialists with FDA 510(k) clearances or established hospital system relationships in the United States, as regulatory moats compound valuation resilience. Long-term viability hinges on differentiation durability against hyperscaler bundling. Watch NVIDIA GPU allocation policy shifts as the critical inflection signal for subscale vendor distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure OpenAI service bundles extend Microsoft's cloud infrastructure dominance into conversational AI workflows. |
| Acquisition of Specialist Firm | Vertical AI vendors with FDA clearances command premium multiples due to regulatory pathway scarcity. |
| Strategic Partnership | System integrator alliances accelerate federal procurement credentialing for emerging cognitive computing vendors. |
| Product Launch | Edge inference chips for manufacturing quality inspection address latency-constrained automotive assembly applications. |
| Geographic Expansion | EU AI Act compliance tooling creates regulatory tailwind demand for transparency modules in European markets. |
Methodological Framework
Multi-period observation of hyperscaler capex disclosures, FDA 510(k) clearance volumes, and GPU allocation patterns anchored the trend analysis, supplemented by interviews with enterprise CTOs, healthcare biomedical engineers, AI platform engineers, and federal procurement officers. Secondary validation drew from SEC filings, NIH grant award databases, EU AI Act implementation guidance, and cloud infrastructure spend tracking. Bottom-up deployment estimates and top-down market sizing triangulated volume and value outputs.
Segment-weighting across deployment models, vertical end-uses, and application types structured the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to base-year estimates, with healthcare diagnostic imaging adoption curves and federal R&D incentive policy trajectories serving as primary industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including breakthrough architectures displacing transformer-based approaches, export control expansions restricting GPU access, and macroeconomic contractions deflating enterprise IT budgets. Forecasts reflect documented assumptions about regulatory implementation timelines and silicon supply normalization. A model refresh is warranted upon material change in NVIDIA manufacturing capacity allocation or EU AI Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Reinforcement Learning Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
AI Image Recognition Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market