
 Freeze Dried Coffee Market | 2026-2036
Freeze Dried Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Dried Coffee Market Analysis
Barista-level roasting expertise is collapsing across traditional coffee-growing regions, forcing manufacturers to automate quality control. Nestlé S.A. leverages captive freeze-drying facilities in Brazil to secure year-round supply. JAB Holding Company anchors its portfolio through vertical ownership of green bean traders across Central America. Strauss Group competes by specializing in micro-lot specialty freeze-dried lines for premium channels.
Freeze dried coffee preserves volatile aromatic compounds through sublimation at temperatures below −40°C, yielding shelf-stable granules that reconstitute without brewed bitterness. The process serves commercial buyers requiring consistent extraction profiles across remote or institutional settings. Specialty Coffee commands the widest margin pools as consumers trade up from conventional instant formulations. Single-Serve Packets are displacing bulk formats in airline and hospitality procurement, while E-Commerce channels capture the fastest volume growth among direct-to-consumer entrants.
FDA enforces strict moisture-content thresholds for imported soluble coffee under food safety modernization rules. The EU Green Deal deforestation regulation now mandates geolocation traceability for all coffee entering European ports, reshaping supplier qualification. Brazil's MAPA inspects processing facilities for Good Manufacturing Practice compliance before export licensing. Stakeholders must monitor how carbon border adjustments and origin-certification requirements reshape cost structures and sourcing geography.
Market Dynamics
The EU Green Deal deforestation regulation is compressing supplier qualification timelines while simultaneously redrawing sourcing geography toward traceable origins. Freeze-drying capacity investment now hinges on geolocation certification compliance rather than raw bean cost alone.
Growth Catalysts
- Urban Millennial Adoption in Brazil:Specialty coffee consumption clusters in São Paulo and Rio de Janeiro are normalizing premium freeze-dried formats previously confined to export markets.
- EU Green Deal Traceability Mandate:The regulation is accelerating supplier consolidation toward vertically integrated processors capable of satellite-verified origin documentation.
- Sublimation Technology Maturation:Advanced vacuum freeze-drying systems operating below −40°C now preserve aromatic compounds at commercial scale previously achievable only in laboratory settings.
Market Restraints
- Arabica Price Volatility:Input cost swings in Brazilian and Colombian spot markets compress margin predictability for processors locked into annual retail contracts.
- Energy Intensity:Freeze-drying cycles consume 2-3x the electricity of spray-dried alternatives, exposing producers to carbon border adjustment exposure in European markets.
- Specialty Barista Culture:Third-wave café proliferation in Southeast Asian cities presents a taste-standard substitute that limits instant coffee premiumization ceilings.
Strategic Opportunities
- Vietnamese Processing Expansion:Robusta-dominant supply chains in the Central Highlands offer untapped freeze-drying feedstock with lower deforestation regulatory risk than Brazilian equivalents.
- Single-Serve Hospitality Formats:Airline and hotel procurement is pivoting from bulk canisters to portion-controlled sachets with private-label branding potential.
- Indonesian Micro-Lot Specialization:Toraja and Gayo origin coffees command specialty premiums when processed through small-batch freeze-drying rather than conventional instant methods.
Industry Challenges
- Roasting Expertise Attrition:Traditional coffee-growing regions are losing generational knowledge of bean-specific roast profiles, forcing manufacturers to deploy spectroscopy-based quality control.
- Multi-Jurisdiction Certification Overlap:FDA moisture-content thresholds, EU geolocation requirements, and Brazil MAPA GMP inspections create parallel compliance timelines that delay product launches.
- Legacy Spray-Drying Asset Stranding:Conventional instant coffee facilities face write-down pressure as retail buyers specify freeze-dried aromatics in procurement tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Dried Coffee Market |
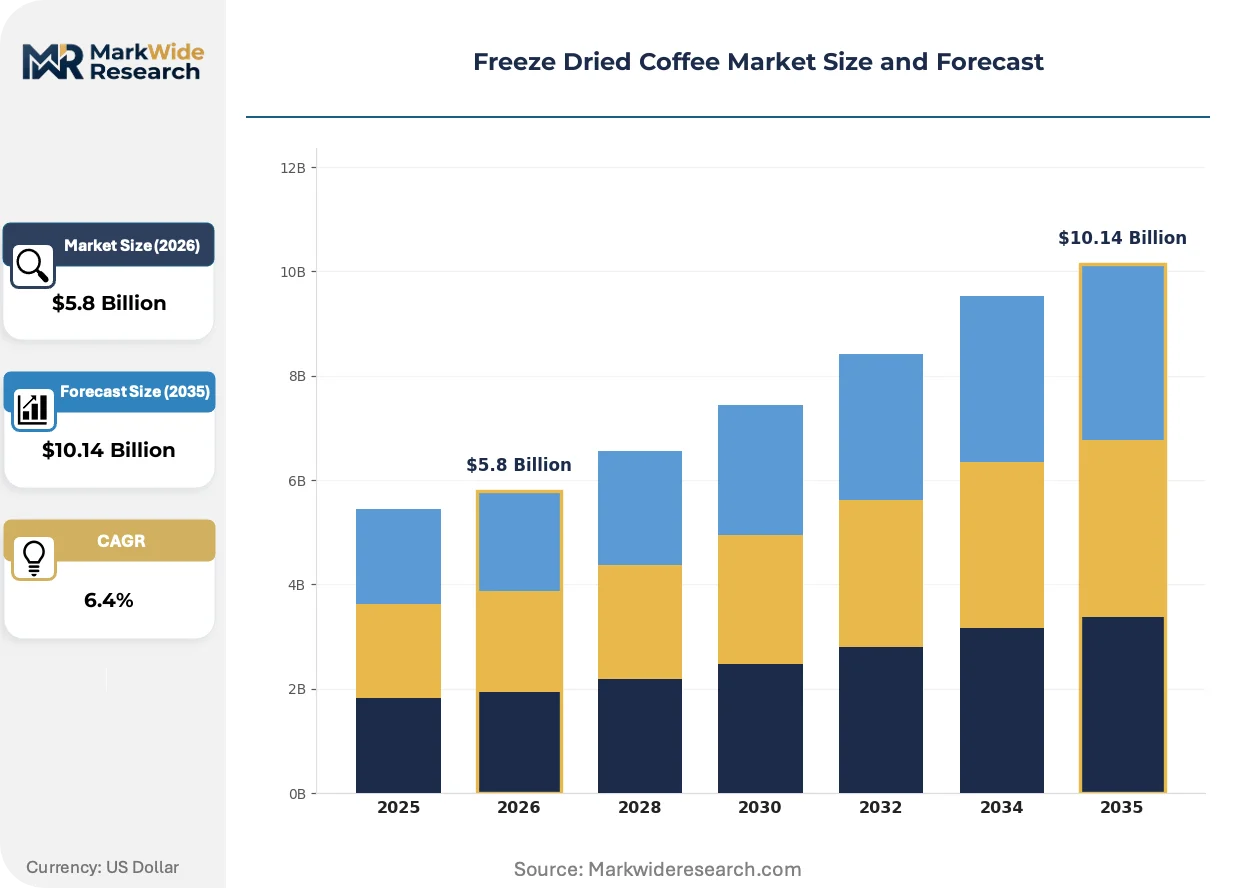
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Coffee, Specialty Coffee, Organic Coffee, Conventional Coffee Packaging Type: Single-Serve Packets, Bulk Bags, Glass Jars, Stand-Up Pouches Sales Channel: Supermarkets, E-Commerce, Specialty Stores, Wholesale End User: Households, Restaurants, Cafés, Offices |
| Companies Covered | Nestlé S.A., JAB Holding Company, Unilever PLC, The J.M. Smucker Company, Luigi Lavazza S.p.A., Strauss Group, Tchibo, Jacobs Douwe Egberts, Mount Hagen Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Dried Coffee Market Emerging Trajectories
Technology deployment and regulatory stringency are splitting competitive positioning between commodity-scale processors and specialty-focused micro-lot operators. The divergence is accelerating format innovation and traceability investment simultaneously.
Cryogenic grinding preceding freeze-drying is bifurcating extraction efficiency outcomes between premium and standard product tiers. Specialty roasters in Melbourne and Portland are adopting pre-sublimation cryomilling to maximize surface area for volatile compound retention. The process is compressing batch processing times by 15-20% while raising capital requirements, effectively separating well-capitalized processors from commodity competitors.
The EU Green Deal deforestation regulation is mandating polygon-level geolocation data for every coffee shipment entering Antwerp and Hamburg ports. Processors must now integrate satellite monitoring subscriptions and third-party audit trails into standard operating costs. Smallholder-dependent supply chains in East Africa face the steepest compliance adaptation burden relative to Brazilian estate-based alternatives.
Direct-to-consumer subscription models are displacing supermarket shelf placement as the primary customer acquisition channel for specialty freeze-dried entrants. Micro-roasters in Seoul and Tokyo are bypassing traditional retail distribution through Instagram-native brands with origin-story content marketing. The shift concentrates working capital requirements into digital advertising spend rather than slotting fee negotiations, favoring venture-backed entrants over legacy processors.
Freeze Dried Coffee Market Segmentation
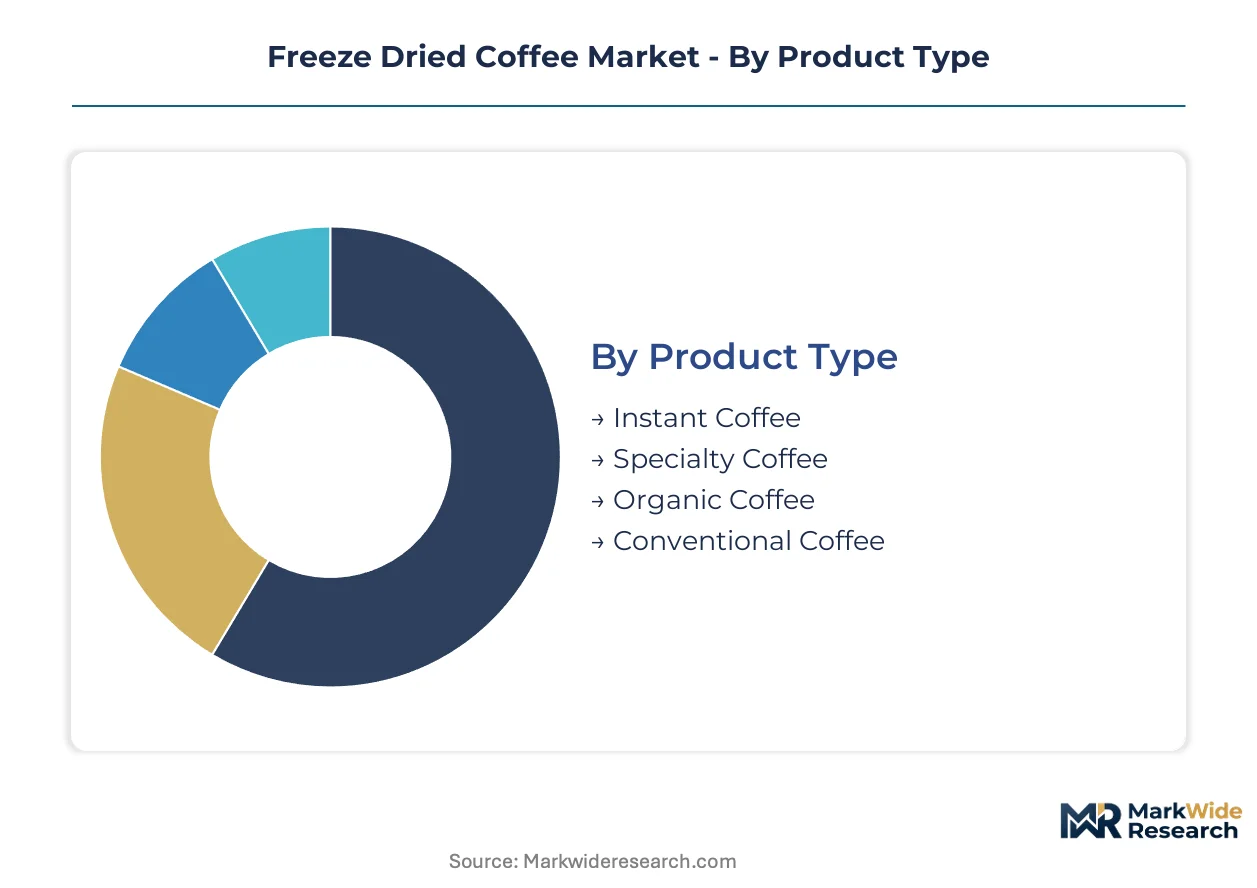
Segmentation in freeze-dried coffee reveals divergent margin structures and regulatory exposure across product tiers and channel strategies. Understanding these divisions exposes where capital deployment yields defensible positioning versus commodity trap risk.
Product Type:
Specialty and organic formats concentrate in export-led premium channels, while conventional instant dominates domestic volume plays in Brazil and Southeast Asia.
- Instant Coffee:Standardized granules from spray-dried or freeze-dried concentrate serve institutional procurement and value-tier retail. Demand concentrates in Brazilian supermarket chains and Southeast Asian hospitality distributors where price elasticity governs purchasing decisions.
- Specialty Coffee:Micro-lot Arabica processed through sublimation below −40°C preserves volatile aromatics for premium reconstitution. Urban millennial clusters in São Paulo and Seoul drive adoption through direct-to-consumer subscription models that bypass traditional retail slotting.
- Organic Coffee:Certified deforestation-free supply chains command EU Green Deal compliance premiums. Brazilian estate operators and Vietnamese cooperative aggregators compete for European port entry.
- Conventional Coffee:Commodity-grade Robusta blends from Indonesian and Vietnamese origins fill bulk hospitality contracts. Price volatility in Brazilian spot markets compresses processor margins on annual retail lock-ins.
Instant Coffee commands the established base. The steepest expansion runs through Specialty Coffee.
Packaging Type:
Format selection determines working capital intensity and shelf-life performance across divergent distribution economics.
- Single-Serve Packets:Portion-controlled sachets with nitrogen flushing extend aroma stability for airline and hotel procurement. Procurement is shifting from bulk canisters to private-label sachet programs across Southeast Asian hospitality chains.
- Bulk Bags:Multi-kilogram formats for foodservice and industrial reprocessing concentrate in Brazilian institutional supply. São Paulo office coffee service operators favor 5kg laminated bags for dispenser-fed consumption.
- Glass Jars:Premium positioning for gift and retail channels leverages transparency and reusability. European supermarkets specify jar formats for organic and specialty lines to signal quality tier.
- Stand-Up Pouches:Flexible packaging with resealable zippers balances portability and shelf presence for e-commerce fulfillment. Seoul and Tokyo direct-to-consumer brands favor pouches for reduced shipping cube and unboxing experience.
Bulk Bags anchor foodservice volume. The steepest climb in value terms belongs to Single-Serve Packets.
Sales Channel:
Channel strategy determines customer acquisition cost structure and margin capture potential across divergent competitive dynamics.
- Supermarkets:Brick-and-mortar retail in Brazil and Indonesia requires slotting fee negotiation and promotional calendar compliance. Conventional instant dominates shelf space while specialty lines fight for end-cap positioning.
- E-Commerce:Direct-to-consumer platforms capture the fastest volume growth among venture-backed entrants. Instagram-native brands in Tokyo and Seoul concentrate working capital into digital advertising rather than retail distribution.
- Specialty Stores:Curated retail in Melbourne and Portland emphasizes origin storytelling and small-batch provenance. Micro-lot freeze-dried lines command premium positioning through barista endorsement.
- Wholesale:B2B distribution to hospitality and institutional buyers requires volume commitments and contract pricing. Brazilian processors leverage captive freeze-drying capacity to secure year-round supply agreements.
Supermarkets retain the volume base. E-Commerce gains share fastest among emerging entrants.
End User:
End-use segmentation maps divergent taste standards and convenience requirements onto format and pricing architecture.
- Households:At-home consumption spans value-tier instant for price-sensitive buyers to specialty freeze-dried for urban millennial upgraders. Brazilian São Paulo clusters normalize premium formats previously confined to export markets.
- Restaurants:Foodservice procurement prioritizes consistent extraction profiles and labor efficiency. Southeast Asian restaurant chains specify single-serve sachets for portion control and brand differentiation.
- Cafés:Third-wave coffee culture in Seoul and Tokyo presents taste-standard substitutes that limit instant coffee premiumization ceilings. Specialty freeze-dried competes for backup and to-go applications rather than core espresso service.
- Offices:Workplace coffee service demands reliability and low maintenance across remote or institutional settings. Brazilian office distributors favor bulk bag formats with automated dispenser compatibility.
Households command the established consumption base. Restaurants show the steepest format upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MAPA certification requirements in Brazil anchor the dominant geography for freeze-dried coffee processing. The EU Green Deal deforestation regulation now mandates geolocation traceability for all shipments entering European ports. Southeast Asian processing clusters in Vietnam and Indonesia are capturing volume migration from traditional Brazilian supply chains.
Brazil
São Paulo and Rio de Janeiro urban millennial clusters normalize premium freeze-dried formats previously confined to export markets. MAPA inspects processing facilities for Good Manufacturing Practice compliance before export licensing. Nestlé S.A. leverages captive freeze-drying facilities in Minas Gerais to secure year-round supply agreements with institutional buyers.
Vietnam
Robusta-dominant supply chains in the Central Highlands offer freeze-drying feedstock with lower deforestation regulatory risk than Brazilian equivalents. The country's national food safety regulator enforces moisture-content thresholds aligned with import market requirements. Da Lat and Buôn Ma Thuột processing zones attract capacity investment from regional hospitality distributors.
Indonesia
Toraja and Gayo origin coffees command specialty premiums when processed through small-batch freeze-drying rather than conventional instant methods. The national food and drug regulator mandates Good Manufacturing Practice certification for export-oriented facilities. Medan and Surabaya industrial zones concentrate spray-drying legacy assets facing write-down pressure from retail buyer specification shifts.
Germany
Hamburg port entry points enforce EU Green Deal polygon-level geolocation data requirements for every coffee shipment. EFSA-aligned food safety modernization rules apply strict moisture-content thresholds for imported soluble coffee. Bremen logistics clusters integrate satellite monitoring subscriptions into standard operating costs for qualified suppliers.
United States
FDA moisture-content thresholds for imported soluble coffee reshape supplier qualification timelines under food safety modernization rules. Portland and Seattle specialty roasters adopt pre-sublimation cryomilling to maximize surface area for volatile compound retention. E-commerce direct-to-consumer channels capture fastest volume growth among venture-backed entrants bypassing traditional retail distribution.
Freeze Dried Coffee Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in freeze-dried coffee manufacturing. The upper tier commands captive supply chains and year-round processing capacity through backward integration into green bean trading. Specialists compete on micro-lot provenance and direct-to-consumer subscription models. Dominant competitive moves include capacity expansion toward geolocation-certified origins and portfolio diversification into single-serve hospitality formats.
Among Swiss-anchored conglomerates, Nestlé S.A. exemplifies the integrated archetype through captive facility ownership. JAB Holding Company represents portfolio-level consolidation across multiple beverage categories. Strauss Group occupies a position within the specialty-focused tier, competing through micro-lot differentiation for premium channels.
| Leading Market Players |
|---|
| Nestlé S.A. |
| JAB Holding Company |
| Unilever PLC |
| The J.M. Smucker Company |
| Luigi Lavazza S.p.A. |
| Strauss Group |
| Tchibo |
| Jacobs Douwe Egberts |
| Mount Hagen Coffee |
| Others |
Supply Flow & Price Mechanics
EU Green Deal deforestation regulations gate both supplier qualification and price differentiation simultaneously, forcing processors to absorb satellite-verified traceability costs while specialty tiers capture compliance premiums. Brazilian estate operators and Vietnamese cooperative aggregators now compete on certification depth rather than bean cost alone, compressing margin pools for uncertified commodity supply.
Pricing Analysis
Brazilian spot Arabica trades at structural premiums to Vietnamese Robusta, yet EU port entry spreads widen further for geolocation-certified micro-lots. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and aromatic compound retention metrics. Cost compression in conventional instant tiers intensifies because energy-intensive freeze-drying cycles expose producers to carbon border adjustment risk. Foodservice procurement teams show highest price sensitivity, while direct-to-consumer subscribers accept premiums for origin-story provenance.
Supply Chain Analysis
Brazil and Vietnam anchor green bean supply for freeze-drying feedstock, with Indonesian Toraja and Gayo origins gaining share in specialty micro-lot channels. Processing draws from Arabica and Robusta varietals, with cryogenic grinding equipment and vacuum sublimation chambers representing critical capital dependencies. Single-source vulnerability concentrates in Brazilian MAPA-licensed facilities facing inspection backlogs. Distribution runs through Hamburg and Antwerp port clusters for EU qualification, with Southeast Asian hospitality distributors bypassing traditional retail wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-wave café proliferation in Seoul and Tokyo presents a taste-standard substitute that freeze-dried incumbents must navigate through format innovation and convenience positioning.
For Market Incumbents: Shield core institutional contracts by securing captive freeze-drying capacity in geolocation-certified origins, particularly Vietnamese Central Highlands estates with lower EU regulatory risk. Absorb satellite monitoring subscription costs into standard operating overhead to preempt supplier consolidation. Deepen backward integration into green bean trading to lock in year-round supply agreements before spot price volatility compresses annual retail contract margins. For New Entrants and Emerging Players: Anchor in Indonesian micro-lot specialization, where Toraja and Gayo origin premiums remain underexploited by conventional instant processors. Target direct-to-consumer subscription channels in São Paulo and Seoul urban millennial clusters, bypassing slotting fee barriers through Instagram-native brand building. Lead with nitrogen-flushed single-serve sachet formats for airline and hospitality procurement pivots. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryogenic grinding and vacuum sublimation equipment tiers, favoring processors with venture backing over legacy spray-drying operators facing asset stranding. Acquisition target archetype: vertically integrated mid-cap specialists with existing EU Green Deal compliance infrastructure and established satellite-verified audit trails. Signal to watch: carbon border adjustment implementation timelines reshaping European import cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Geolocation Certification Investment | Satellite-verified origin documentation secures EU port entry against deforestation regulation enforcement. |
| Cryogenic Grinding Adoption | Pre-sublimation cryomilling maximizes volatile compound retention for specialty tier premiumization. |
| Single-Serve Format Pivot | Nitrogen-flushed sachets capture airline and hospitality procurement shifts from bulk canisters. |
| Direct-to-Consumer Channel Buildout | Instagram-native subscription models bypass retail slotting fees in São Paulo and Seoul clusters. |
| Vietnamese Processing Expansion | Central Highlands Robusta supply chains offer lower deforestation regulatory risk than Brazilian equivalents. |
Methodological Framework
Desk research of trade customs records, EU regulatory filings, and MAPA licensing databases preceded structured interviews with freeze-drying plant managers, green bean procurement leads at integrated processors, hospitality category buyers, and specialty coffee subscription brand operators. Primary fieldwork combined with secondary validation from SEC filings of listed beverage conglomerates and EFSA food safety guidance documents. Bottom-up volume modeling triangulated against top-down market sizing from customs data.
Variance decomposition across product type, packaging format, sales channel, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from weighted average growth assumptions across certified and uncertified supply tiers, with energy cost trajectories and carbon border adjustment exposure as industry-specific forecast inputs.
Underlying assumptions cover sustained EU Green Deal enforcement and Brazilian MAPA inspection capacity, with deviation risk concentrated in Arabica spot price volatility and Southeast Asian third-wave café substitution acceleration. Recalibration cycles align with material shifts in deforestation regulation implementation timelines and cryogenic equipment cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
High Protein Coffee Market
Coffee
Coffee Pods Market
Coffee
US Coffee Machine Market
Coffee
Australia Coffee Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Italy Coffee Market
Coffee
Caffeine Market
Coffee
US Coffee Roaster Market
Coffee
Take Out Coffee Market
Coffee
South America Coffee Market
Coffee
United States Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Coffee Roaster Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Middle East Coffee Market