
 PXI Source Measure Unit Market | 2026-2036
PXI Source Measure Unit Market Size, Share, and Industry Trends Forecast 2026-2036
PXI Source Measure Unit Market Analytics
Silicon carbide test fixtures are recalibrating PXI SMU product economics as wide-bandgap semiconductor volumes climb. Keysight Technologies leverages its RF instrumentation heritage to dominate high-frequency characterization segments. Chroma ATE anchors its position through captive power electronics test expertise in East Asian manufacturing hubs. National Instruments sustains software-defined instrument architecture as a competitive differentiator against hardware-centric rivals.
A PXI Source Measure Unit combines precision voltage sourcing and current measurement in a CompactPCI Express modular format, typically achieving sub-picoamp resolution with four-quadrant operation for semiconductor device characterization. The platform integrates programmable source-measure cycles with PXI trigger bus synchronization, enabling automated wafer-level parametric test in foundry environments. High-Precision SMUs command the dominant revenue share where sub-femtoamp sensitivity justifies premium positioning in quantum device research. Digital Technology adoption is accelerating fastest as software-defined architectures displace analog-heavy legacy platforms in telecommunications test. Modular SMU configurations concentrate margin pools in aerospace qualification programs requiring channel-count scalability.
FCC equipment authorization rules shape RF Technology SMU demand for pre-compliance electromagnetic testing in North American telecommunications labs. NMPA medical device regulations in China and EMA electromagnetic compatibility standards in Europe collectively restrict market access for instruments lacking validated calibration traceability. RoHS substance restrictions and REACH chemical compliance further constrain component sourcing for manufacturers serving European automotive verticals. Stakeholders must monitor how dual carbon goals in China and EU Green Deal industrial benchmarks redirect procurement criteria toward energy-efficient test platforms.
Market Dynamics
Silicon carbide wafer qualification protocols are compressing test cycle times and forcing PXI SMU architectures toward higher channel densities per rack unit. Foundry customers now demand synchronized multi-site parametric measurement that legacy GPIB-based systems cannot deliver.
Growth Catalysts
- Wide-bandgap semiconductor ramp:Silicon carbide and gallium nitride power device foundries in Taiwan and South Korea require four-quadrant characterization at 150°C junction temperatures. PXI SMUs with integrated thermal chuck control capture this workflow.
- REACH substance tracing:European automotive electronics suppliers must document RoHS compliance through calibrated measurement chains. Validated SMU platforms with ISO 17025 traceability satisfy this audit requirement.
- Quantum device research funding:National laboratories in the US and EU are scaling cryogenic probe stations. Sub-femtoamp SMU sensitivity enables single-electron transistor characterization at millikelvin temperatures.
Market Restraints
- Precision resistor supply concentration:Bulk metal foil resistors with sub-ppm temperature coefficients source primarily from Eastern European manufacturers. Geopolitical friction threatens calibration stability for high-precision SMU tiers.
- FCC pre-compliance cost burden:RF Technology SMU validation for electromagnetic interference testing adds fifteen to twenty percent to North American product development budgets. Smaller telecommunications instrument makers defer purchases.
- GPIB legacy inertia:Mature semiconductor fabs in Japan retain substantial installed bases of rack-and-stack source-measure systems. Capital replacement cycles extend beyond typical PXI SMU depreciation schedules.
Strategic Opportunities
- India PLI scheme leverage:Production-linked incentives for semiconductor and solar cell manufacturing are attracting greenfield fab investments. Early SMU deployment in these facilities establishes reference architectures for subsequent scale-up.
- Software-defined convergence:Integration of PXI SMU modules with AI-driven test pattern generation compresses time-to-yield for advanced node characterization. This hybrid architecture penetrates memory test segments previously served by dedicated ATE.
- EU Green Deal procurement criteria:Energy efficiency benchmarks for industrial test equipment favor modular platforms with intelligent power management. PXI SMU vendors can differentiate through standby power specifications and regenerative load options.
Industry Challenges
- Cryogenic calibration expertise scarcity:Validating sub-picoamp accuracy at liquid helium temperatures requires specialized metrology partnerships. Few service organizations outside national standards laboratories possess this capability.
- Multi-vendor synchronization complexity:Heterogeneous PXI chassis configurations from different suppliers introduce trigger latency mismatches. System integrators must engineer custom timing solutions for wafer-level parallel test.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PXI Source Measure Unit Market |
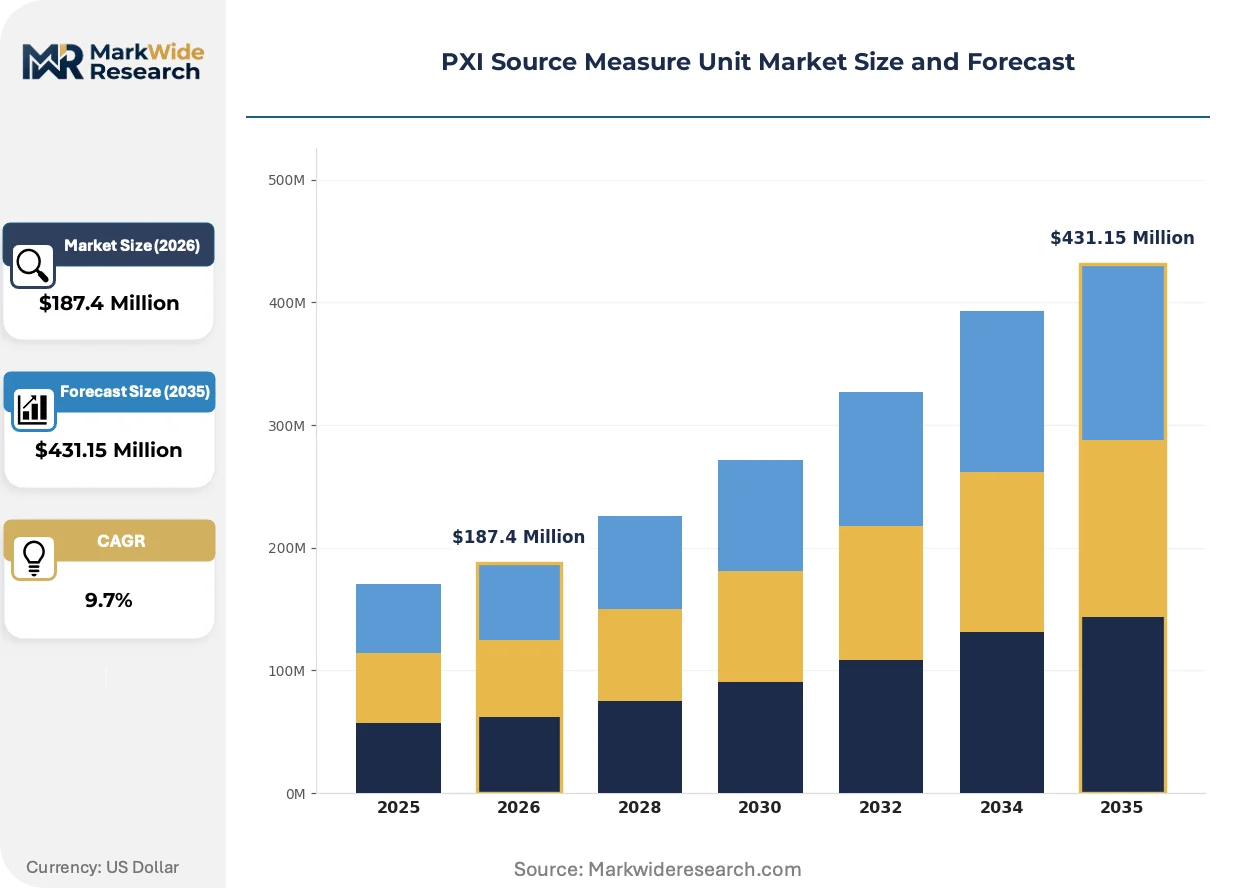
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Precision SMUs, Low-Current SMUs, Modular SMUs, Digital SMUs Technology: Analog Technology, Digital Technology, RF Technology, Mixed-Signal Technology Industry Vertical: Aerospace, Telecommunications, Automotive, Consumer Electronics Application: Device Characterization, Automation Testing, Power Measurement, Research & Development |
| Companies Covered | Keysight Technologies, National Instruments, Chroma ATE, Rohde & Schwarz, Yokogawa Electric Corporation, VX Instruments, Marvin Test Solutions, Acquitek, Pickering Interfaces, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PXI Source Measure Unit Market Evolving Landscape
Test automation architectures are pivoting from hardware-centric instrument stacks toward software-defined measurement workflows. This reconfiguration redistributes value capture from analog front-end design to algorithmic test optimization.
Digital Technology is rewriting how parametric test systems acquire and process device data. FPGA-based real-time averaging engines in PXI SMU modules cut measurement noise bandwidth without extending integration periods. Memory foundries in South Korea are deploying these architectures to maintain throughput during high-resolution leakage characterization. The technology is rewriting the throughput-versus-precision tradeoff that constrained previous-generation analog-heavy platforms.
EU MDR electromagnetic compatibility requirements for active implantable medical devices are tightening pre-market testing documentation. Manufacturers must demonstrate validated calibration traceability for all measurement equipment used in design verification. This regulatory pressure elevates demand for SMU platforms with embedded ISO 17025 certificate management. European medical electronics contract manufacturers are consolidating supplier relationships around vendors offering integrated compliance tooling.
Buyer concentration among East Asian foundry operators is compressing vendor negotiation cycles and unbundling traditional service contracts. Large semiconductor test labs now procure PXI SMU hardware through separate capital budgets while sourcing calibration and application support from third-party metrology providers. This procurement fragmentation is most pronounced in Taiwan, where dedicated test service companies manage multi-vendor instrument pools for foundry customers.
PXI Source Measure Unit Market Segmentation
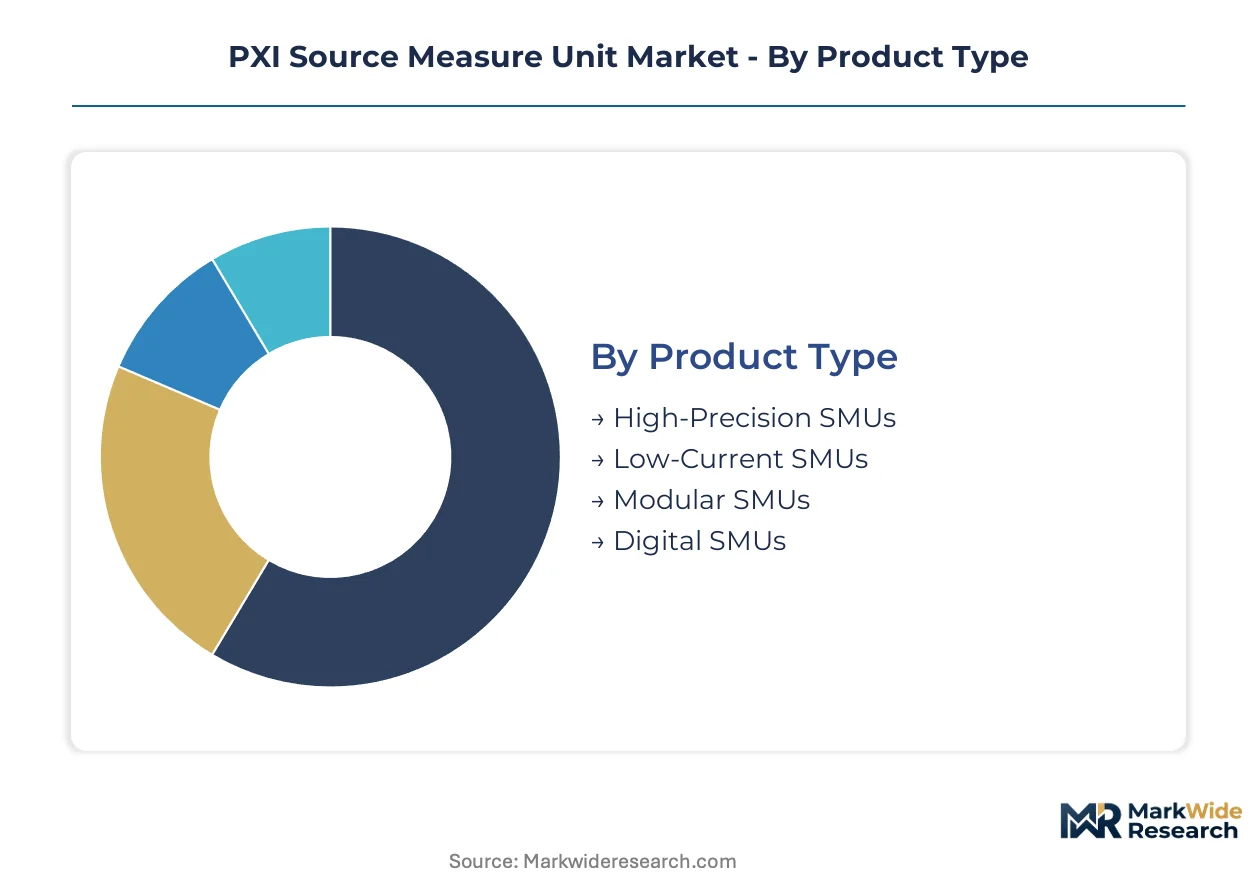
PXI SMU purchasing decisions split sharply between capital-intensive precision tiers and volume-driven modular configurations. Semiconductor foundries allocate equipment budgets across multiple segment boundaries simultaneously, forcing vendors to architect product lines that span technical specifications rather than discrete price bands.
Product Type:
High-Precision SMUs demand the steepest upfront capital commitment due to sub-femtoamp resolution requirements and specialized cryogenic calibration infrastructure. Low-Current SMUs occupy a mid-tier investment position, while Modular and Digital variants reduce per-channel acquisition costs through chassis-sharing economies.
- High-Precision SMUs:These instruments achieve sub-femtoamp current resolution through proprietary electrometer architectures and hermetic shielding. Quantum device research laboratories in the US and EU concentrate procurement here, driven by national laboratory funding for cryogenic probe station instrumentation. Calibration traceability requirements extend replacement cycles and lock in premium service contracts.
- Modular SMUs:CompactPCI Express form factors enable channel-count scaling from 4 to 512 slots per chassis without controller duplication. Aerospace qualification programs in Germany and France favor these configurations for satellite electronics screening, constrained by EU Green Deal energy efficiency benchmarks that penalize idle power draw in thermal vacuum test cycles.
- Low-Current SMUs:Picoamp-range instruments serve MEMS sensor foundries in Taiwan where leakage characterization dominates wafer-level parametric test.
- Digital SMUs:FPGA-based architectures with programmable measurement intervals displace analog-heavy legacy platforms in telecommunications device validation labs.
Most installed capacity flows through Modular SMUs. Expansion is steepest in High-Precision SMUs.
Technology:
Technology selection maps directly to measurement bandwidth requirements and software integration depth, with digital architectures commanding implementation premiums for real-time algorithmic control.
- Digital Technology:FPGA-based real-time averaging engines compress noise bandwidth without extending integration periods. Memory foundries in South Korea deploy these architectures to maintain throughput during high-resolution leakage characterization at advanced nodes. The technology displaces analog-heavy platforms previously constrained by throughput-versus-precision tradeoffs.
- RF Technology:Four-quadrant sourcing with electromagnetic interference pre-compliance capabilities addresses FCC equipment authorization rules for North American telecommunications labs. Validation costs add substantial overhead to product development budgets, deferring purchases among smaller instrument makers.
- Analog Technology:Legacy architectures persist in mature Japanese semiconductor fabs with extended capital replacement cycles.
- Mixed-Signal Technology:Hybrid architectures combine precision analog front-ends with digital signal processing for power electronics test in Taiwanese SiC foundries.
Digital Technology claims the dominant share of new procurement. RF Technology is climbing the fastest as pre-compliance testing mandates expand.
Industry Vertical:
Vertical selection determines channel density requirements and environmental qualification rigor, with aerospace programs demanding the most extensive thermal and vibration screening protocols.
- Aerospace:Satellite electronics qualification requires PXI SMU configurations with MIL-STD-883 environmental screening and channel-count scalability for batch testing. European space agencies in France and Germany specify EU Green Deal procurement criteria that prioritize modular platforms with regenerative load options and documented standby power specifications.
- Automotive:Wide-bandgap semiconductor characterization for electric vehicle powertrains drives four-quadrant testing at elevated junction temperatures. REACH substance tracing requirements from ECHA compel European suppliers to document RoHS compliance through calibrated measurement chains with ISO 17025 traceability.
- Telecommunications:5G baseband and mmWave device validation concentrates in South Korean and Taiwanese contract manufacturing clusters.
- Consumer Electronics:High-volume MEMS and display driver test prioritizes cost-per-channel metrics over absolute precision.
Automotive verticals absorb the largest equipment volumes. Aerospace is gaining share fastest on satellite constellation deployment timelines.
Application:
Application scope determines integration complexity with handler and prober equipment, with device characterization requiring the deepest metrology partnerships.
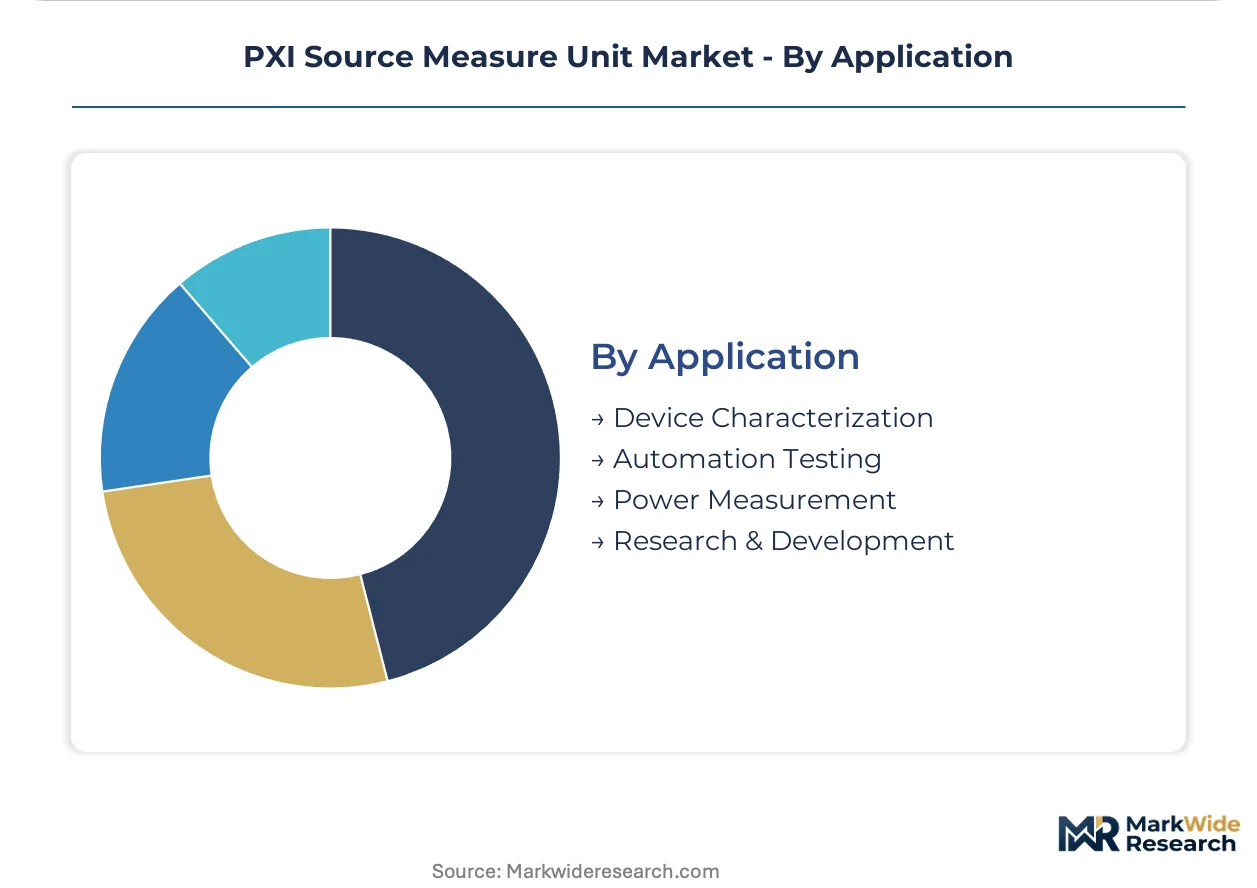
- Device Characterization:Wafer-level parametric test demands synchronized multi-site measurement with thermal chuck control for SiC and GaN power devices. Foundry customers in Taiwan and South Korea require sub-picoamp resolution at 150°C junction temperatures, compressing test cycle times and forcing architectures toward higher channel densities per rack unit.
- Research & Development:Cryogenic probe stations for single-electron transistor characterization require sub-femtoamp sensitivity at millikelvin temperatures. National laboratories in the US and EU scale these installations, constrained by scarce calibration expertise outside national standards laboratories.
- Automation Testing:Production handler integration prioritizes throughput and binning speed over absolute accuracy in high-volume memory test.
- Power Measurement:Regenerative load integration and intelligent power management address EU Green Deal industrial benchmarks for energy-efficient test platforms.
Device Characterization commands the dominant installed base. Research & Development is expanding most quickly on quantum computing investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor manufacturing clusters command the dominant procurement volumes for PXI Source Measure Units, with Taiwan and South Korea setting the pace for high-precision modular instrument adoption.
United States
National laboratories in New Mexico and California drive sub-femtoamp SMU demand for cryogenic quantum device research. FDA electromagnetic compatibility standards for active implantable medical devices elevate calibration traceability requirements. Boston-area medical electronics contract manufacturers consolidate supplier relationships around validated instrumentation platforms.
China
Dual carbon goals redirect procurement criteria toward energy-efficient test platforms in Yangtze River Delta foundries. NMPA tightened medical device electronics standards push manufacturers toward validated SMU platforms with ISO 17025 documentation. Shenzhen contract manufacturing clusters absorb modular configurations for consumer electronics validation.
Germany
EU Green Deal industrial benchmarks favor modular platforms with regenerative load options in satellite electronics qualification. ECHA REACH substance tracing compels automotive suppliers to document RoHS compliance through calibrated measurement chains. Bavarian aerospace programs specify intelligent power management in thermal vacuum test cycles.
South Korea
Memory foundries in Seoul Capital Area deploy FPGA-based real-time averaging engines to maintain throughput during high-resolution leakage characterization. MFDS medical device regulations elevate demand for embedded certificate management. Busan-Ulsan manufacturing hubs concentrate wide-bandgap semiconductor test fixture procurement.
Japan
Mature semiconductor fabs in Kanto retain substantial installed bases of rack-and-stack source-measure systems with extended capital replacement cycles. METI industrial standards shape electromagnetic interference pre-compliance testing mandates. Nagoya-area automotive electronics suppliers prioritize four-quadrant characterization for electric vehicle powertrain validation.
PXI Source Measure Unit Market Competitive Landscape
Global majors compete with regional champions across precision tiering and software integration depth. The vendor base organizes around three strategic archetypes: RF instrumentation heritage players leveraging high-frequency characterization expertise, captive power electronics specialists anchored in East Asian manufacturing hubs, and software-defined architecture advocates differentiating through programmable measurement workflows. Consolidation pressure intensifies through strategic partnerships for cryogenic calibration capabilities and geographic expansion into India PLI scheme beneficiary facilities.
Within the RF heritage tier, Keysight Technologies occupies a position exemplifying high-frequency electromagnetic testing dominance. Among East Asian specialists, Chroma ATE represents captive power electronics test expertise concentrated in Taiwanese manufacturing ecosystems. National Instruments anchors the software-defined instrument architecture vector, differentiating through FPGA-based programmable measurement intervals that displace analog-heavy legacy platforms.
| Leading Market Players |
|---|
| Keysight Technologies |
| National Instruments |
| Chroma ATE |
| Rohde & Schwarz |
| Yokogawa Electric Corporation |
| VX Instruments |
| Marvin Test Solutions |
| Acquitek |
| Pickering Interfaces |
| Others |
Value Network & Pricing Analysis
Sub-femtoamp precision tier divergence separates quantum research laboratories from mainstream semiconductor test facilities, manifesting in both acquisition premiums and captive calibration infrastructure investments. This bifurcation concentrates pricing power with vendors maintaining cryogenic metrology partnerships while compressing margins for modular configurations serving volume-driven contract manufacturers.
Pricing Analysis
Precision resistor and hermetic shielding material costs pass through directly to High-Precision SMU price points, with bulk metal foil resistor supply concentration in Eastern Europe amplifying cost volatility. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and thermal chuck integration depth. Cost compression in modular tiers intensifies as East Asian foundries unbundle hardware procurement from service contracts. Contract manufacturing clusters in Taiwan exhibit the highest price sensitivity, while national laboratories in the US and EU prioritize traceability over unit economics.
Supply Chain Analysis
Specialized freight handling for cryogenic calibration equipment elevates logistics costs for precision-tier instruments sourced from US and German metrology centers. Component manufacturing concentrates in Taiwan, South Korea, and Japan, with FPGA sourcing tethered to TSMC fabrication capacity. Single-source vulnerability pervades sub-ppm temperature coefficient resistor supply from Eastern European manufacturers. Distribution runs through direct OEM relationships for high-precision tiers and third-party test service companies for modular configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PXI Source Measure Unit demand compounds steadily as wide-bandgap semiconductor foundry capacity expands across East Asia, with silicon carbide qualification protocols creating durable replacement cycles for synchronized multi-site architectures.
For Market Incumbents: Deploy cryogenic calibration expertise as a defensive moat against modular competitors. Keysight Technologies and National Instruments should deepen metrology partnerships with NIST and PTB to lock in quantum research funding flows. Chroma ATE must expand captive power electronics test integration to defend against software-defined architecture displacement from FPGA-based rivals. For New Entrants and Emerging Players: Third-party calibration service providers represent an underserved buyer archetype in the fragmented Taiwan test service ecosystem. India PLI scheme beneficiary facilities offer the most penetrable geography for greenfield reference architecture deployment. A calibration-traceability-first go-to-market angle bypasses direct hardware competition with entrenched chassis vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where cryogenic calibration expertise scarcity constrains high-precision tier expansion. Long-term viability favors vendors with embedded ISO 17025 certificate management and regenerative load intellectual property. Watch NMPA medical device electronics standard enforcement in China as the inflection signal for validated platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Calibration Partnership | NIST and PTB alliances secure quantum research funding flows in US and EU national laboratories. |
| FPGA Architecture Migration | Software-defined measurement intervals displace analog-heavy legacy platforms in South Korean memory foundries. |
| India PLI Scheme Entry | Early SMU deployment in greenfield fabs establishes reference architectures for semiconductor scale-up. |
| ISO 17025 Certificate Integration | Embedded compliance tooling satisfies EU MDR and NMPA medical device electronics documentation mandates. |
| Regenerative Load Development | Intelligent power management specifications address EU Green Deal procurement criteria for aerospace qualification programs. |
Research Methodology
Direct dialogue with semiconductor test engineers, foundry equipment procurement managers, cryogenic probe station operators, and third-party calibration service providers grounded qualitative findings. Secondary validation drew from SEC instrument company filings, SEMI equipment market data, FDA electromagnetic compatibility guidance documents, and national laboratory funding announcements. Bottom-up channel checks across Taiwan and South Korean manufacturing clusters triangulated against top-down vendor shipment estimates.
Segment-level revenue outputs across the projection horizon reflect modeled interactions between wide-bandgap semiconductor capacity expansion, regulatory compliance cost pass-through, and software-defined architecture displacement rates. Technology, product type, industry vertical, and application dimensions structured the analytical framework. CAGRs derived from instrument replacement cycle analysis and foundry capital expenditure sensitivity to yield optimization pressures.
Underlying measurement precision varies by segment; High-Precision SMU forecasts carry tighter precision than Modular configurations given concentrated national laboratory demand visibility. Forecasts reflect assumptions about silicon carbide foundry ramp schedules and REACH substance tracing enforcement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
LCR Meter Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Photostability Chamber Market
Test and Measurement
Diamond Tester Market
Test and Measurement
CCTV Tester Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Electromagnetic NDT Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Digital Thickness Gauge Market