
 SME Cloud Market | 2026-2036
SME Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
SME Cloud Market Analysis
Buyer concentration among medium enterprises is pivoting as franchise networks and multi-location professional services firms consolidate procurement decisions across dozens of satellite offices. Amazon Web Services leverages its extensive data center footprint to anchor enterprise-grade reliability claims for distributed small business users. Microsoft Azure competes through deep integration with productivity software that many SMEs already license. Google Cloud Platform differentiates on analytics and machine learning tooling priced for mid-market experimentation.
SME Cloud denotes hosted computing resources—spanning virtualized servers, container orchestration, managed databases, and API-accessible storage—delivered via internet protocols to organizations with fewer than 250 employees and typically sub-$50 million annual revenue, with latency targets under 50 milliseconds for transactional workloads. Its primary purpose is to replace capital-intensive on-premises infrastructure with operational expenditure models that preserve cash flow for core business investment. Public Cloud deployments command the largest revenue share due to minimal upfront commitment and elastic scaling, though Hybrid Cloud architectures are gaining fastest as regulated industries seek to partition sensitive data. Within Service Type, Software as a Service retains the broadest penetration while Platform as a Service captures expanding margin pools from developer-centric SMEs building proprietary applications.
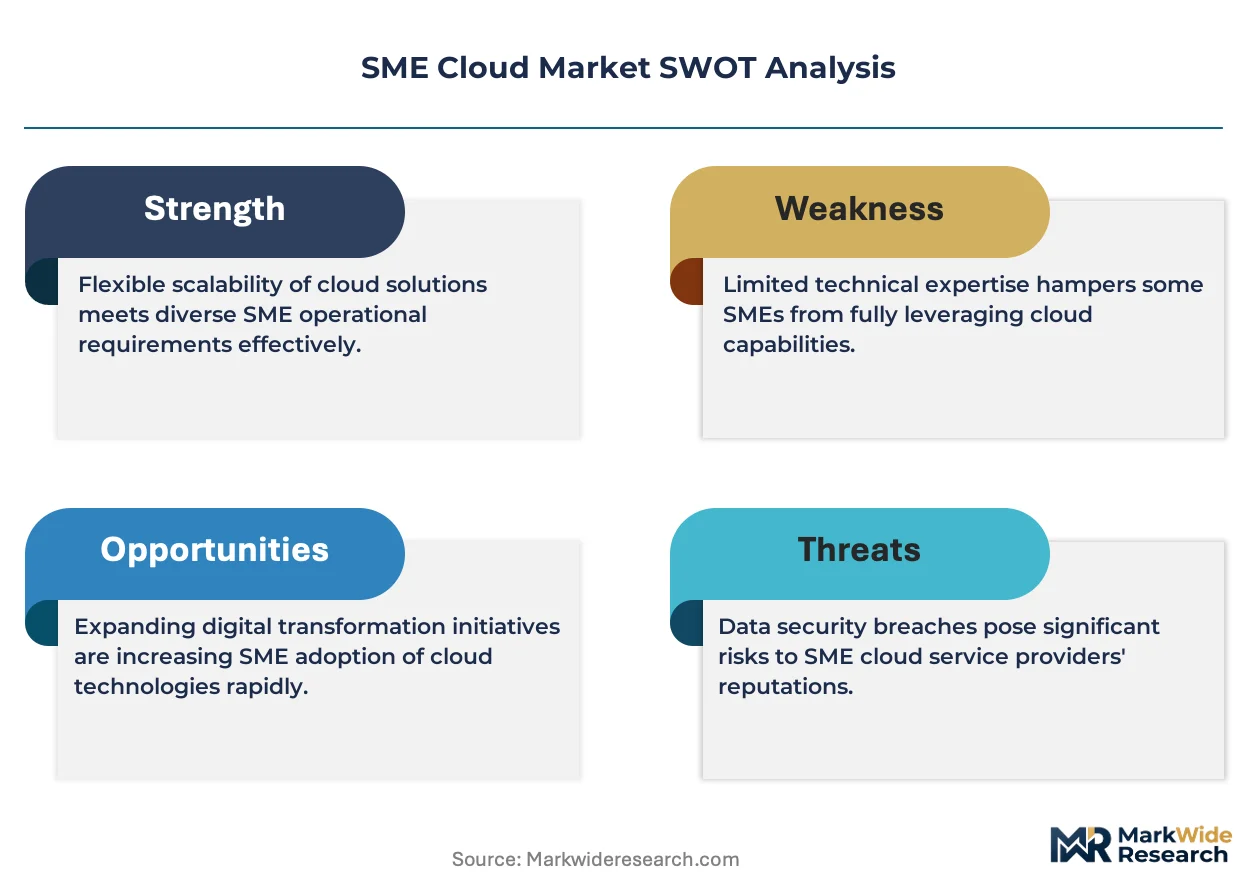
FDA guidelines on electronic health record interoperability, EU GDPR data localization mandates, and SEC cybersecurity disclosure rules for public SMEs collectively elevate compliance architecture to a primary purchasing criterion rather than afterthought. These frameworks force vendors to certify regional data residency, audit logging, and encryption standards before contract execution. Stakeholders must monitor evolving AI governance requirements that will determine which cloud-native services remain accessible to regulated small businesses without costly architectural retrofit.
Market Dynamics
GDPR and the EU AI Act are compressing vendor selection cycles as Mittelstand manufacturers demand certified data residency before contract execution, forcing providers to pre-build compliance architecture rather than retrofit later.
Growth Catalysts
- Healthcare digitization:FDA guidelines on electronic health record interoperability mandate cloud-native infrastructure for clinics, pulling SaaS deployments into ambulatory care networks.
- EU AI Act:The framework's risk-tiering system creates immediate demand for audit-logged, explainable AI hosting environments among professional services firms.
- Container orchestration:Kubernetes-based Platform as a Service offerings enable mid-market developers to build proprietary applications without capital-intensive server procurement.
Market Restraints
- Data sovereignty compliance costs:GDPR localization mandates force redundant infrastructure deployment across multiple EU member states, inflating operational expenditure for providers.
- Latency thresholds:Sub-50 millisecond transactional requirements exclude remote data center locations from serving manufacturing ERP workloads in industrial clusters.
- Hybrid complexity:Partitioning sensitive data between public and private environments demands specialized integration skills scarce among SME IT departments.
Strategic Opportunities
- Franchise network consolidation:Multi-location professional services firms are centralizing procurement decisions, creating volume contracts spanning dozens of satellite offices.
- Edge computing convergence:5G network slicing combined with micro data centers enables sub-10 millisecond latency for factory-floor IoT analytics.
- Green cloud incentives:EU Green Deal carbon reporting requirements position renewable-powered data centers as differentiated procurement criteria.
Industry Challenges
- Legacy ERP migration:Mittelstand manufacturers face multi-year timelines to extract business logic from decades-old on-premises systems without operational disruption.
- Skills scarcity:DevOps and cloud security expertise commands premium compensation that outstretches SME hiring budgets in secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SME Cloud Market |
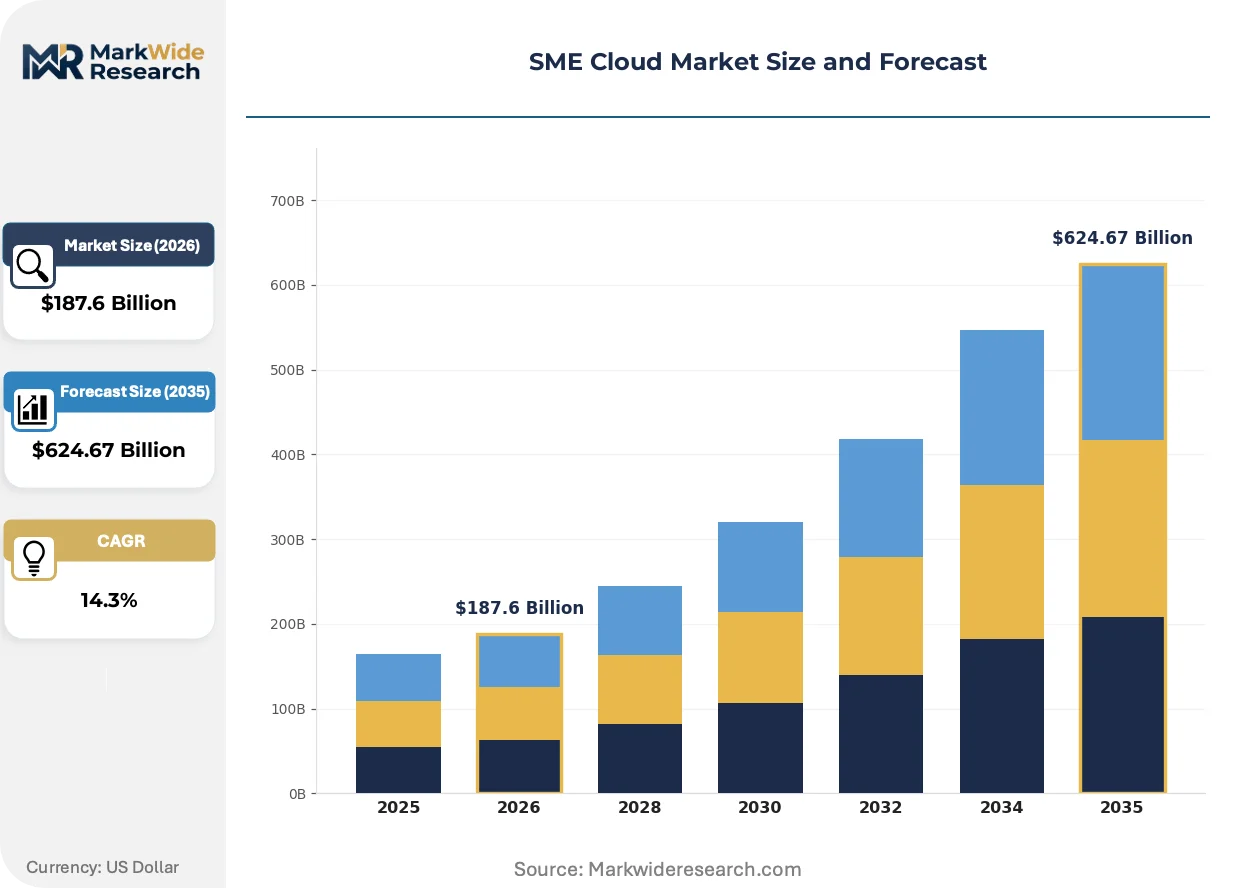
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Backup as a Service End User: Small Enterprises, Medium Enterprises, Startups, Nonprofits Solution: Data Storage, Cloud Computing, Virtualization, Security Services |
| Companies Covered | DigitalOcean, Oracle Cloud Infrastructure, Amazon Web Services, Alibaba Cloud, IBM Cloud, Microsoft Azure, Salesforce, OVHcloud, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SME Cloud Market Emerging Trajectories
Serverless computing architectures are compressing infrastructure management burdens while regulatory frameworks force transparent AI governance into standard service agreements.
Serverless function-as-a-service platforms are absorbing operational overhead previously assigned to dedicated virtual machines. Healthcare clinics in Germany are adopting these architectures fastest, driven by HIPAA-equivalent compliance requirements for patient data processing. The technology is absorbing capital that would otherwise flow to container management specialists, compressing mid-market provider margins.
GDPR Article 44 transfer mechanisms now require explicit adequacy decisions or standard contractual clauses for any cross-border data routing. Cloud vendors must maintain geographically segmented infrastructure with independent encryption key management. German automotive suppliers and French legal services firms represent the most affected segments, demanding contractual guarantees of EU-only data residency before signature.
Centralized procurement hubs within franchise headquarters are displacing location-by-location software licensing. Multi-site dental practices and accounting networks now negotiate enterprise terms covering fifty-plus satellite offices simultaneously. This concentration is most visible across the DACH region, where standardized service menus enable bulk purchasing power previously unavailable to individual SME locations.
SME Cloud Market Segmentation
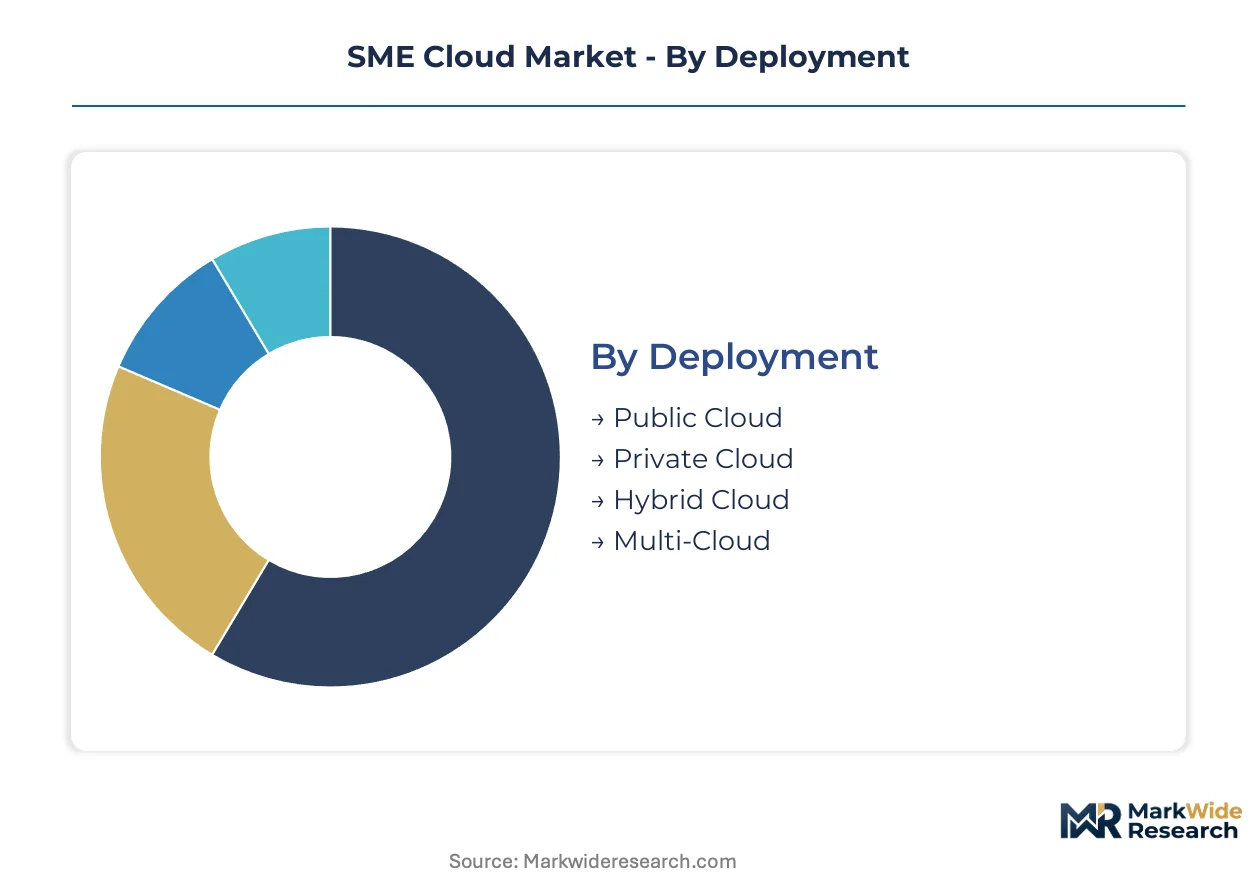
SME Cloud procurement patterns diverge sharply across deployment architectures and service tiers. Understanding these fault lines reveals where vendor investments concentrate and which segments resist commoditization.
Deployment:
Supply concentration among hyperscale providers anchors competitive dynamics in each deployment mode, with infrastructure ownership determining pricing leverage and compliance certification speed.
- Public Cloud:Shared infrastructure pools deliver compute, storage, and networking via internet protocols with zero capital commitment. German Mittelstand manufacturers migrating legacy ERP systems drive concentrated demand, though GDPR localization mandates now force redundant EU zone deployments that inflate operational expenditure.
- Hybrid Cloud:Partitioned architectures split sensitive workloads between on-premises private infrastructure and burst-capable public resources. French legal services firms and healthcare clinics in the DACH region represent the fastest-expanding customer base, compelled by CNIL enforcement of data residency and FDA-equivalent interoperability requirements for patient records.
- Private Cloud:Dedicated single-tenant environments provisioned within enterprise premises or exclusive third-party facilities. Swiss financial advisory partnerships and Luxembourg fund administrators purchase these configurations to satisfy FINMA and CSSF audit requirements without shared infrastructure risk.
- Multi-Cloud:Orchestrated workloads spanning two or more hyperscale providers to mitigate vendor lock-in and optimize price-performance per application tier. Dutch logistics cooperatives and Belgian franchise networks deploy these strategies to arbitrage regional pricing differentials across Frankfurt, Amsterdam, and Paris availability zones.
Today's leader: Public Cloud. Tomorrow's challenger: Hybrid Cloud.
Service Type:
Margin structures diverge across abstraction layers, with higher-level services capturing expanding value pools as SME technical sophistication matures.
- Infrastructure as a Service:Virtualized compute, storage, and networking resources provisioned via API or web console with hourly billing granularity. Italian industrial machinery subcontractors and Spanish agricultural cooperatives anchor volume demand, prioritizing capex elimination over managed service premiums.
- Platform as a Service:Container orchestration, managed databases, and developer tooling abstracting infrastructure management entirely. Kubernetes-based offerings from Frankfurt-region providers attract Portuguese software startups and Czech SaaS ventures building proprietary applications without server procurement cycles.
- Software as a Service:Application-layer functionality delivered through browsers or mobile clients with subscription pricing. Broadest penetration across all SME categories, though Austrian professional services firms and Danish architectural practices now demand EU AI Act-compliant audit logging for any embedded machine learning features.
- Backup as a Service:Automated data protection with geographic redundancy and granular recovery point objectives. Polish manufacturing SMEs and Hungarian healthcare clinics adopt these services fastest, driven by SEC-equivalent cybersecurity disclosure expectations and national data protection authority enforcement.
Infrastructure as a Service commands current volume. Platform as a Service climbs the fastest as developer-centric SMEs expand proprietary application portfolios.
End User:
Procurement authority concentration varies dramatically by organizational scale, reshaping vendor sales motion economics.
- Medium Enterprises:Organizations with 50-250 employees and centralized IT decision-making. Franchise headquarters in Germany and multi-location dental networks across the Netherlands consolidate fifty-plus satellite contracts into single enterprise negotiations, extracting volume pricing previously unavailable to dispersed locations.
- Small Enterprises:Firms with 10-49 employees and owner-operator technology purchasing. Irish professional services partnerships and Finnish design studios represent fragmented demand with high price sensitivity and minimal integration complexity requirements.
- Startups:Venture-backed or bootstrapped entities prioritizing elastic scaling and consumption-based pricing over long-term commitments. Stockholm fintech incubators and Lisbon Web3 ventures drive early adoption of serverless architectures and machine learning APIs.
- Nonprofits:Mission-driven organizations with constrained budgets and donor transparency requirements. Belgian social enterprises and Austrian cultural institutions leverage Google Cloud and Microsoft nonprofit credit programs to offset infrastructure costs.
Medium Enterprises dominate contract value today. Startups represent the steepest expansion trajectory as European venture deployment recovers.
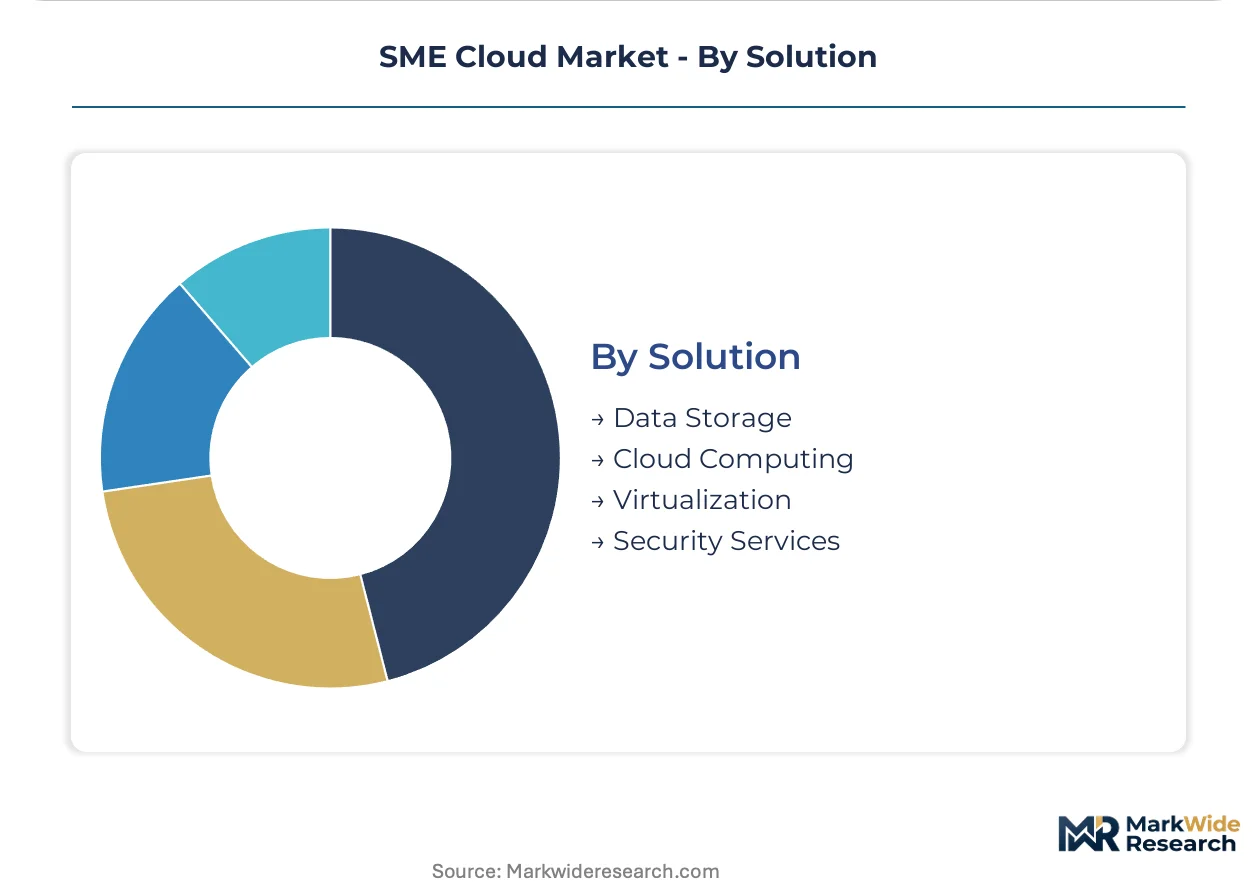
Solution:
Functional purchasing priorities reflect industry-specific compliance burdens and legacy system replacement cycles.
- Cloud Computing:Core processing and workload execution services including virtual machines, containers, and serverless functions. French automotive suppliers and German precision manufacturers migrating shop-floor ERP systems generate concentrated demand for sub-50 millisecond latency configurations.
- Data Storage:Object, block, and file storage with tiered durability guarantees and geographic replication. Italian healthcare clinics and Spanish diagnostic imaging centers drive growth, compelled by GDPR Article 44 transfer mechanism restrictions and national health data localization statutes.
- Security Services:Identity management, encryption key control, threat detection, and compliance certification bundles. Dutch financial advisory networks and Luxembourg wealth managers purchase these most intensively to satisfy DNB and CSSF cybersecurity examination protocols.
- Virtualization:Legacy workload abstraction enabling x86 server consolidation and disaster recovery flexibility. Czech industrial equipment distributors and Slovak logistics providers deploy these solutions to extend on-premises hardware lifecycles while planning phased cloud migration.
Cloud Computing anchors current procurement. Security Services gain share fastest as EU AI Act and national cybersecurity frameworks elevate compliance architecture to primary selection criterion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in Mittelstand cloud migration velocity, while the United Kingdom attracts venture-backed startup density despite tighter post-Brexit data transfer protocols. Regulatory fragmentation across jurisdictions forces providers to architect redundant compliance infrastructure rather than unified global stacks.
Germany
Mittelstand manufacturers in Baden-Württemberg and Bavaria drive concentrated demand for ERP cloud migration with sub-50 millisecond latency requirements. GDPR Article 44 transfer mechanisms and the EU AI Act risk-tiering system compel vendors to certify EU-only data residency before contract execution. Stuttgart's automotive supplier cluster anchors the fastest expansion of hybrid cloud deployments for factory-floor analytics.
United Kingdom
London-based fintech incubators and Manchester professional services networks prioritize elastic serverless architectures for rapid scaling. Post-Brexit UK GDPR divergence creates parallel compliance obligations alongside EU adequacy negotiations. The Cambridge tech corridor concentrates demand for machine learning APIs among venture-backed SaaS ventures.
France
Parisian legal services firms and Lyon healthcare clinics adopt hybrid configurations fastest under CNIL enforcement of data localization. The EU AI Act's audit-logging mandates reshape procurement criteria for AI-embedded SaaS applications. Sophia Antipolis technology park hosts expanding Platform-as-a-Service experimentation among French software startups.
United States
FDA electronic health record interoperability guidelines pull cloud-native infrastructure into ambulatory care networks across Texas and Florida. SEC cybersecurity disclosure rules for public SMEs elevate compliance architecture to primary selection criterion. Seattle and Austin metropolitan areas concentrate startup demand for consumption-based pricing models.
India
Bengaluru SaaS ventures and Mumbai financial services SMEs drive Kubernetes-based Platform-as-a-Service adoption for proprietary application development. RBI data localization directives for payment systems create jurisdictional partitioning requirements. Hyderabad's pharmaceutical outsourcing cluster generates specialized demand for HIPAA-equivalent compliant hosting environments.
SME Cloud Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Hyperscale providers anchor the premium tier through global data center footprints and enterprise-grade reliability certifications. Mid-market specialists capture regional compliance niches through localized infrastructure ownership. Competitive dynamics center on M&A consolidation of boutique compliance consultancies and strategic partnerships with telecommunications carriers for edge computing deployment.
Among hyperscale infrastructure operators, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify the diversified technology conglomerate archetype. Each occupies a distinct competitive position: Amazon Web Services anchors enterprise reliability claims through extensive physical infrastructure, Microsoft Azure leverages productivity software integration for existing licensee conversion, and Google Cloud Platform targets analytics and machine learning experimentation priced for mid-market access. Regional specialists including OVHcloud and DigitalOcean represent focused pure-plays competing on localized data residency guarantees and simplified pricing transparency for cost-constrained SME procurement committees.
| Leading Market Players |
|---|
| DigitalOcean |
| Oracle Cloud Infrastructure |
| Amazon Web Services |
| Alibaba Cloud |
| IBM Cloud |
| Microsoft Azure |
| Salesforce |
| OVHcloud |
| Google Cloud Platform |
| Others |
Supply Flow & Price Mechanics
Franchise procurement consolidation across German multi-location professional services firms is forcing hyperscale providers to pre-certify EU data residency and localized encryption key management, compressing margins on standardized infrastructure bundles while creating premium pricing tiers for compliant architectures.
Pricing Analysis
Capacity additions in Frankfurt and Amsterdam availability zones are reshaping price floors for Infrastructure-as-a-Service offerings across the DACH region. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance certification depth and latency guarantees. Cost compression in the standard tier is intensifying because redundant GDPR-localized deployments inflate operational expenditure without corresponding revenue capture. Italian industrial machinery subcontractors exhibit highest price sensitivity, while Swiss financial advisory partnerships accept premium positioning for FINMA-audited single-tenant configurations.
Supply Chain Analysis
India's PLI scheme for data center equipment and the EU's proposed Critical Raw Materials Act are reshaping server hardware sourcing strategies for European cloud operators. Supply concentrates in Taiwan for advanced semiconductors, China for rare earth magnet components in cooling systems, and Germany for precision manufacturing equipment. Raw material dependencies span high-purity silicon wafers, cobalt-bearing thermal interface materials, and copper cabling for power distribution. Single-source vulnerability in advanced GPU accelerators sourced from TSMC's foundry network poses structural risk. Distribution runs through direct hyperscale procurement teams and regional systems integrators serving Mittelstand manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SME Cloud market operates as a stable compounder anchored by regulatory mandates that permanently elevate compliance architecture from optional premium to baseline procurement requirement.
For Market Incumbents: Lock in franchise network headquarters through multi-year enterprise agreements covering fifty-plus satellite offices before competitors establish localized data residency certifications. Pre-build EU AI Act audit-logging capabilities into standard service agreements to neutralize emerging pure-play specialists competing on transparent AI governance. Channel control through telecommunications carrier partnerships for edge computing deployment represents the critical defensive lever. For New Entrants and Emerging Players: Managed service providers specializing in legacy ERP extraction for Baden-Württemberg manufacturers represent the most penetrable channel partner type for wedge positioning. Target Portuguese software startups and Czech SaaS ventures building proprietary applications on Kubernetes-based Platform-as-a-Service offerings, where hyperscale pricing complexity creates white-space opportunity. A compliance-first go-to-market emphasizing GDPR Article 44 transfer mechanism guarantees differentiates against commodity infrastructure positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists owning localized data center footprints in secondary EU markets underserved by hyperscale availability zones. Long-term viability centers on acquisition targets with proven FINMA, CSSF, or CNIL certification pathways and established relationships with Mittelstand manufacturing clusters. Monitor EU AI Act enforcement timelines as the critical inflection signal determining which cloud-native services remain accessible to regulated small businesses without costly architectural retrofit.| Strategic Initiative | Industry Significance |
|---|---|
| EU Data Residency Certification | GDPR Article 44 mandates force redundant infrastructure deployment across Frankfurt, Amsterdam, and Paris zones. |
| Edge Computing Partnership | 5G network slicing with telecommunications carriers enables sub-10 millisecond latency for factory-floor IoT analytics. |
| Legacy ERP Migration Service | Specialized extraction capabilities for decades-old on-premises systems capture Mittelstand manufacturing demand. |
| AI Governance Audit Logging | EU AI Act risk-tiering creates immediate demand for explainable AI hosting environments among professional services firms. |
| Green Cloud Certification | EU Green Deal carbon reporting positions renewable-powered data centers as differentiated procurement criteria. |
Methodological Framework
Coverage spans Germany, France, the United Kingdom, and the United States, with primary inputs from each market combined with secondary validation. Primary interviews engaged cloud procurement officers at franchise headquarters, DevOps leads at mid-market software ventures, compliance directors at healthcare clinic networks, and infrastructure planners at Mittelstand manufacturers. Secondary sources encompassed hyperscaler capital expenditure disclosures, SEC filings from publicly traded cloud providers, GDPR enforcement actions from national data protection authorities, and EU regulatory filings on the AI Act. Bottom-up demand aggregation across deployment modes and service tiers triangulated against top-down market sizing from infrastructure investment flows.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing evolution and mix shifts toward higher-abstraction services. Segmentation dimensions modeled include deployment architecture, service type, organization size tier, industry vertical, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to historical migration patterns and projected compliance-driven replacement cycles. Forecast inputs incorporate EU AI Act implementation timelines and FDA electronic health record interoperability mandate enforcement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU regulatory fragmentation and potential divergence in UK data protection standards post-Brexit. Assumptions underlying projections include sustained Mittelstand ERP migration velocity and stable hyperscale pricing discipline. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Europe Cloud Computing Market
Cloud Computing
Healthcare Cloud Computing Software Market
Cloud Computing
Public Cloud in BFSI Market
Cloud Computing
Global Marketing Cloud Platform Market
Cloud Computing
Cloud Enablement Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
Saudi Arabia Cloud Services Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Community Cloud Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Italy Cloud Computing Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
Cloud-Based Workload Scheduling Software Market