
 Asia-Pacific Marketing Cloud Platform Market | 2026-2036
Asia-Pacific Marketing Cloud Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Marketing Cloud Platform Market Analytics
Software development capacity across India and Singapore is shifting toward AI-native marketing infrastructure. Salesforce.com, Inc. leverages extensive partner ecosystems to sustain enterprise retention across Australian financial services. Oracle Corporation anchors its regional position through database integration with campaign execution layers. Adobe, Inc. competes on creative-cloud adjacency, differentiating through native content-to-activation pipelines.
A marketing cloud platform is an integrated software environment that unifies customer data management, campaign orchestration, analytics, and content delivery through API-connected modules operating on shared identity graphs. Its primary commercial purpose is enabling organizations to coordinate personalized engagement across email, social, web, and mobile touchpoints from a single data foundation. Public cloud deployment dominates new bookings due to faster time-to-value and lower capital requirements, though hybrid configurations are expanding among Japanese financial institutions with strict data residency rules. Email marketing remains the largest revenue pool by service type, while analytics services represent the fastest-expanding margin segment as attribution modeling grows more sophisticated.
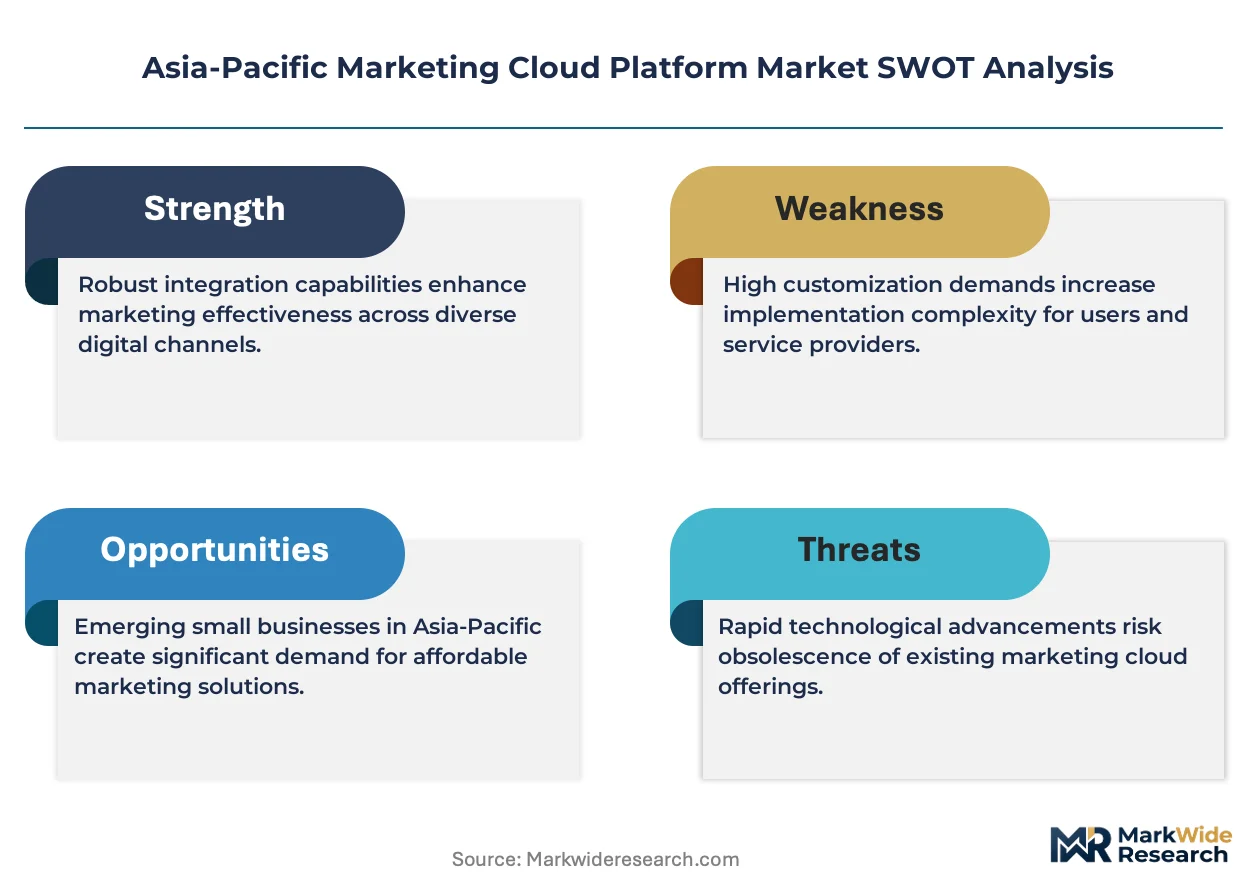
India's Digital Personal Data Protection Act and Australia's Privacy Act create compliance complexity that elevates demand for consent-management modules and region-specific data residency controls. Japan's Act on Protection of Personal Information, enforced by the Personal Information Protection Commission, further fragments acceptable data practices across the region. Stakeholders must evaluate whether to architect single-stack platforms or federated best-of-breed environments as regulatory divergence intensifies.
Market Dynamics
Cross-border data localization mandates are fragmenting platform architectures across the Asia-Pacific region, forcing vendors to engineer federated deployments that respect national sovereignty while preserving unified customer identity graphs.
Growth Catalysts
- Retail digitalization wave:Southeast Asian retail chains are deploying integrated campaign orchestration suites to unify offline POS data with online behavioral signals, compressing activation latency from days to hours.
- India's Digital Personal Data Protection Act:Consent-management infrastructure requirements are accelerating procurement of compliant marketing cloud modules among domestic e-commerce platforms and fintech operators.
- Real-time personalization engines:Australian enterprise banking and insurance sectors are commanding premium deployment budgets for sub-second recommendation systems embedded in mobile banking interfaces.
Market Restraints
- Data residency hardware costs:Japanese financial institutions face elevated capex for on-premise compute clusters satisfying Act on Protection of Personal Information localization rules, extending payback periods.
- API integration complexity:Legacy core banking systems in Australia and Singapore resist seamless connection to cloud-native activation layers, requiring expensive middleware development.
- Talent scarcity in AI-native infrastructure:Software development capacity for marketing-specific machine learning pipelines concentrates in Bangalore and Singapore, creating wage inflation and project bottlenecks.
Strategic Opportunities
- Vietnam and Philippines underpenetration:Mid-market retail and telecom verticals in these markets lack sophisticated attribution modeling, creating first-mover advantage for platforms offering localized language support.
- Consent-as-a-service modules:Regulatory divergence between India's DPDP Act, Australia's Privacy Act, and Japan's APPI is generating demand for modular compliance architectures that adapt to jurisdiction-specific rules.
- Creative-to-activation convergence:Native pipelines connecting design tools with campaign execution layers are compressing content production cycles for Australian media agencies and Indian D2C brands.
Industry Challenges
- Cross-border data flow engineering:Platform architects must engineer identity resolution systems that function across sovereign data boundaries without violating residency prohibitions, complicating multi-market rollouts.
- Attribution model standardization:Competing methodologies for multi-touch credit allocation create buyer confusion and extend sales cycles, particularly among Southeast Asian conglomerates with distributed marketing teams.
- Hybrid deployment orchestration:Japanese financial institutions demand seamless operation between private cloud instances and public edge nodes, requiring vendor investment in containerized workload management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Marketing Cloud Platform Market |
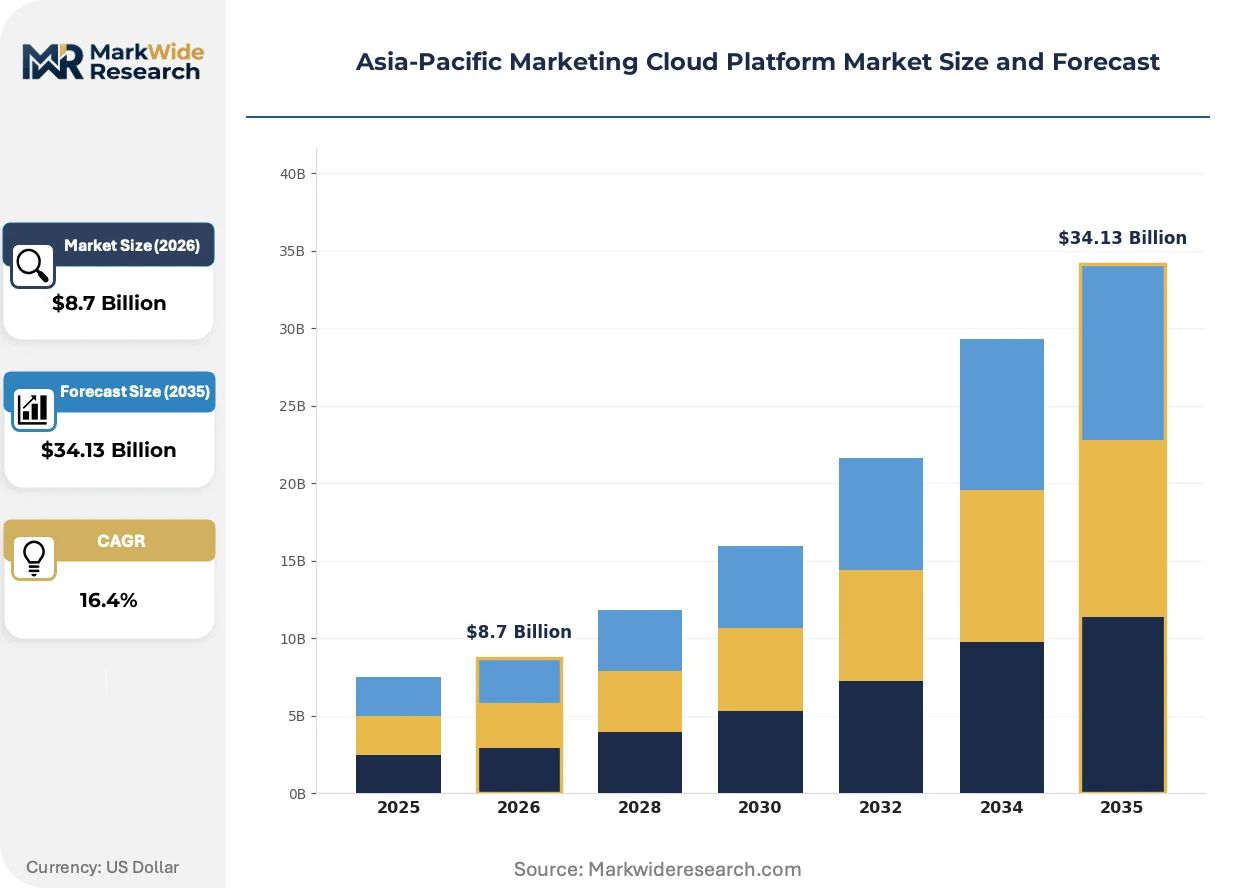
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Email Marketing, Social Media Management, Analytics Services, Content Management Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Retail, E-Commerce, BFSI, Healthcare Customer Type: SMEs, Large Enterprises, Startups, Non-Profits |
| Companies Covered | Adobe, Inc., Salesforce.com, Inc., Oracle Corporation, SAP SE, HubSpot, Inc., SAS Institute, Inc., IBM, Zoho Corporation Pvt. Ltd., Treasure Data, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Marketing Cloud Platform Market Evolving Landscape
Artificial intelligence is restructuring how marketing clouds ingest, model, and activate customer data, shifting competitive advantage from database scale to inference speed and creative generation quality.
Composable customer data platforms are modularizing marketing technology stacks across Asia-Pacific enterprises. These API-first architectures separate storage, identity resolution, and activation into interchangeable components. Australian banks and Indian e-commerce platforms are adopting this pattern to swap vendors for specific functions without full-stack replacement. The approach is compressing vendor lock-in periods and elevating procurement leverage for enterprise buyers.
India's Digital Personal Data Protection Act is mandating explicit consent mechanisms for every data processing purpose, with significant penalties for non-compliance. Marketing cloud vendors are embedding granular permission workflows and automated audit trails into their core platforms. Domestic Indian platforms and multinational deployments serving Indian subsidiaries are prioritizing these modules in product roadmaps to preempt regulatory enforcement.
Subscription-based pricing for marketing infrastructure is displacing perpetual license models among mid-market buyers in Southeast Asia. Indonesian and Vietnamese retail chains prefer operational expenditure structures that align costs with campaign volume rather than upfront capital deployment. This shift is compressing average contract values while extending customer lifetime through recurring engagement and continuous feature delivery.
Asia-Pacific Marketing Cloud Platform Market Segmentation
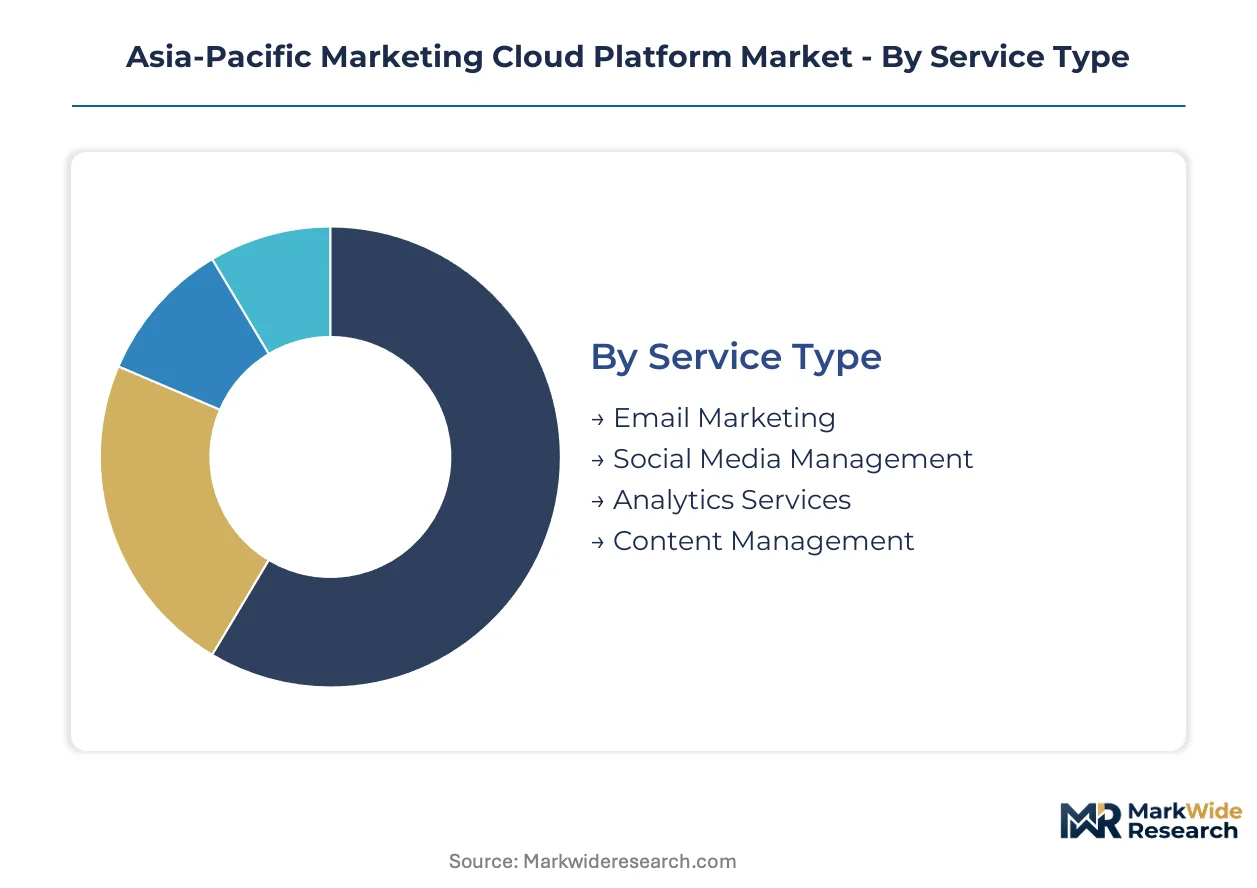
Marketing cloud platforms fragment across multiple dimensions that determine integration complexity, compliance burden, and total cost of ownership. Deployment choices and service configurations directly constrain how Australian banks, Indian e-commerce platforms, and Southeast Asian retail chains orchestrate customer engagement.
Service Type:
Standardization dominates high-volume channels while specialized modules command premium pricing for advanced attribution and creative production.
- Email Marketing:Core orchestration layer managing list segmentation, deliverability optimization, and triggered lifecycle campaigns through shared identity graphs. Australian enterprise banking and insurance sectors allocate substantial deployment budgets here for transactional and promotional streams.
- Analytics Services:Attribution modeling, predictive scoring, and real-time dashboarding modules operating on unified data lakes. This segment is expanding most quickly as Southeast Asian conglomerates demand multi-touch credit allocation across distributed marketing teams.
- Social Media Management:Publishing workflows, community response tools, and influencer tracking across regional platforms like LINE, WeChat, and WhatsApp.
- Content Management:Asset libraries, template systems, and dynamic personalization engines connecting creative production to campaign execution.
Leading the category by volume: Email Marketing. Gaining share fastest: Analytics Services.
Deployment Model:
Capital intensity and data sovereignty requirements create sharp segmentation between operational expenditure preferences and compliance-driven infrastructure investments.
- Public Cloud:Multi-tenant SaaS architectures delivering fastest time-to-value through API-connected modules and consumption-based pricing. Indonesian and Vietnamese retail chains favor this model for campaign volume alignment.
- Hybrid Cloud:Containerized workloads spanning private instances and public edge nodes. Japanese financial institutions are expanding this configuration to satisfy Act on Protection of Personal Information localization rules without sacrificing scalability.
- Private Cloud:Single-tenant environments with dedicated compute clusters for strict data residency requirements.
- On-Premises:Fully captive infrastructure with highest capital deployment and extended payback periods.
Public Cloud dominates new bookings. Hybrid Cloud shows steepest expansion trajectory among regulated sectors.
End User:
Vertical-specific compliance regimes and customer engagement patterns drive divergent platform configuration requirements across the region.
- BFSI:Sub-second recommendation engines embedded in mobile banking interfaces with real-time risk scoring and consent-managed personalization. Australian enterprise banking commands premium deployment budgets for these capabilities.
- Retail:Unified offline POS and online behavioral signal integration compressing activation latency from days to hours. Southeast Asian retail chains are expanding adoption of integrated campaign orchestration suites.
- E-Commerce:High-velocity attribution and abandoned-cart recovery systems with granular consent workflows under India's Digital Personal Data Protection Act.
- Healthcare:Strict patient data protection requirements with limited cross-border processing permissions.
Retail leads by deployment count. BFSI generates highest average contract values.
Customer Type:
Organizational scale determines whether buyers prioritize out-of-box functionality or demand extensive customization and dedicated support tiers.
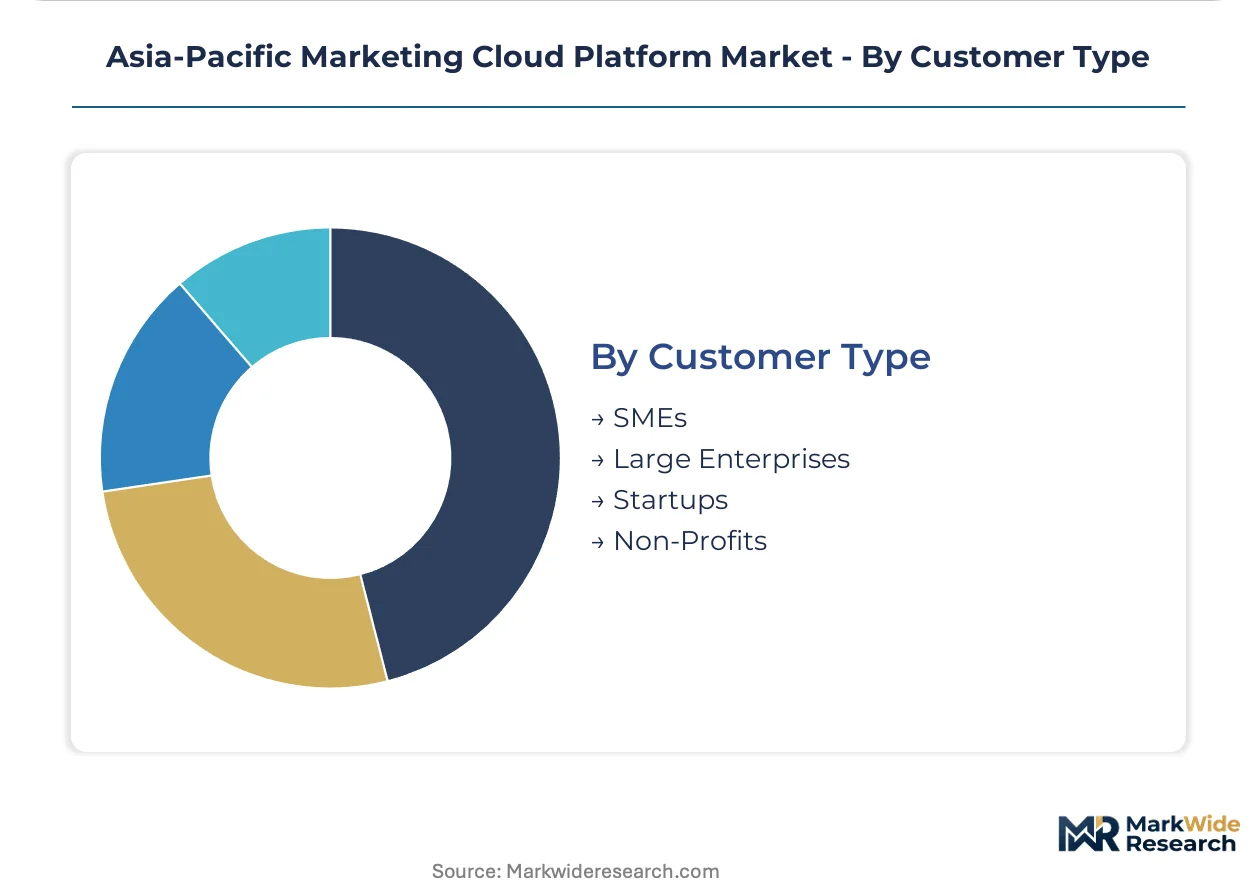
- Large Enterprises:Federated best-of-breed architectures with dedicated customer success management and custom integration development. Australian banks and Indian e-commerce platforms are adopting composable customer data platforms to preserve procurement leverage.
- SMEs:Standardized module bundles with subscription pricing aligning costs to campaign volume rather than upfront capital deployment.
- Startups:Lightweight entry tiers with rapid scaling pathways and minimal implementation services.
- Non-Profits:Discounted or donated capacity with simplified compliance features and grant-reporting integrations.
Large Enterprises anchor revenue concentration. SMEs are expanding most quickly as subscription models displace perpetual licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure investments across Singapore and Sydney anchor cloud-native marketing deployments throughout the Asia-Pacific basin. Submarine cable connectivity and sovereign data residency rules are reshaping where platforms locate compute capacity.
Australia
Enterprise banking and insurance sectors command premium deployment budgets for real-time personalization engines embedded in mobile interfaces. The Privacy Act mandates granular consent workflows that elevate procurement of compliance-ready modules. Sydney and Melbourne financial districts concentrate vendor customer success teams and implementation partnerships.
Japan
Financial institutions are expanding hybrid cloud configurations to satisfy Act on Protection of Personal Information localization requirements without sacrificing scalability. The Personal Information Protection Commission enforces strict cross-border transfer rules that fragment platform architectures. Tokyo's enterprise software corridor hosts localized engineering centers for containerized workload orchestration.
India
Domestic e-commerce platforms and fintech operators are accelerating procurement of consent-management infrastructure under the Digital Personal Data Protection Act. The Reserve Bank of India issues periodic guidance on customer data handling that shapes vendor product roadmaps. Bangalore's software development clusters concentrate AI-native marketing infrastructure talent, creating wage inflation for specialized machine learning pipelines.
Singapore
Regional headquarters for multinational marketing cloud vendors leverage the city-state's data center density to serve Southeast Asian retail chains. The Monetary Authority of Singapore's technology risk management guidelines influence platform security certifications. The Marina Bay financial district anchors enterprise sales operations targeting ASEAN conglomerates.
Vietnam
Mid-market retail and telecom verticals lack sophisticated attribution modeling, creating first-mover advantage for platforms offering localized Vietnamese language support. The Ministry of Information and Communications drafts data localization decrees that will reshape cross-border customer information flows. Ho Chi Minh City's emerging tech corridor attracts regional vendor investment in sales and support infrastructure.
Asia-Pacific Marketing Cloud Platform Market Competitive Landscape
Global majors compete with regional champions across deployment flexibility and regulatory adaptation. The vendor base organizes into three tiers: full-stack enterprise suites, modular best-of-breed specialists, and domestic platforms with native compliance features. Strategic differentiation concentrates on consent-management module sophistication and hybrid cloud orchestration capabilities. Leading competitive moves include federated partnership architectures and in-house development of AI-native inference engines.
Within the enterprise suite tier, Salesforce.com, Inc. and Oracle Corporation occupy positions defined by extensive partner ecosystems and database integration depth respectively. Adobe, Inc. anchors the creative-to-activation convergence vector through native content pipeline adjacencies. Zoho Corporation Pvt. Ltd. represents the domestic specialist archetype with India-centric compliance automation and localized pricing structures. These three exemplify how competitive positioning fragments across global scale, vertical integration, and regional regulatory proximity.
| Leading Market Players |
|---|
| Adobe, Inc. |
| Salesforce.com, Inc. |
| Oracle Corporation |
| SAP SE |
| HubSpot, Inc. |
| SAS Institute, Inc. |
| IBM |
| Zoho Corporation Pvt. Ltd. |
| Treasure Data, Inc. |
| Others |
Value Network & Pricing Analysis
India's Digital Personal Data Protection Act gates qualified supply for consent-management modules and premium-tier pricing access across the Asia-Pacific marketing cloud platform market. Vendors lacking compliant infrastructure face exclusion from Indian e-commerce and fintech procurement cycles, compressing margins for non-compliant tiers while elevating pricing power for certified deployments.
Pricing Analysis
Service-level agreements and implementation support unbundle from core platform subscriptions across Australian banking and Indian enterprise segments. Subscription-based SaaS pricing dominates new bookings, with premium differentiation anchored in real-time personalization engine performance and hybrid cloud orchestration capabilities. Price compression runs through standardized email marketing tiers as Indonesian and Vietnamese retail chains demand consumption-aligned operational expenditure models. SMEs exhibit highest price sensitivity, while Japanese financial institutions accept elevated capital deployment for private cloud instances satisfying data residency mandates.
Supply Chain Analysis
AI-native inference engine development rests on specialized machine learning talent concentrated in Bangalore and Singapore software clusters. Compute infrastructure draws from hyperscaler data center investments across Sydney, Singapore, and Tokyo, with API middleware dependencies on regional systems integrators in Melbourne and Mumbai. Single-source vulnerability concentrates in consent-management module engineering for India's DPDP Act compliance. Distribution runs through direct enterprise sales teams anchored in financial districts and channel partnerships serving mid-market Southeast Asian retail verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific marketing cloud platform market represents a consolidation play as regulatory divergence between India's DPDP Act, Australia's Privacy Act, and Japan's APPI forces subscale vendors toward acquisition or exit.
For Market Incumbents: Deepen hybrid cloud orchestration capabilities to capture Japanese financial institution procurement cycles demanding seamless private-public workload management. Fortify consent-management module sophistication against domestic Indian platforms leveraging native DPDP Act automation. Invest in containerized deployment engineering to defend against modular best-of-breed specialists fragmenting enterprise accounts.
For New Entrants and Emerging Players: Launch via localized Vietnamese and Filipino language support targeting mid-market retail and telecom verticals lacking sophisticated attribution modeling. Prioritize consent-as-a-service modular architectures that adapt to jurisdiction-specific regulatory divergence without full-stack replacement. Anchor initial beachhead in Southeast Asian SME segments where subscription pricing displaces perpetual licenses.
For Investors and Strategic Acquirers: Reserve Bank of India guidance tightening on customer data handling is the leading indicator that domestic compliance automation capabilities will command acquisition premiums. Position for five-to-ten year viability around vendors with federated identity resolution engineering spanning sovereign data boundaries. Monitor Personal Information Protection Commission enforcement actions in Japan as signals for hybrid cloud deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Consent-Management Module Development | India's DPDP Act mandates granular permission workflows, elevating procurement priority for compliant platforms. |
| Hybrid Cloud Orchestration Investment | Japanese financial institutions demand containerized workloads satisfying APPI localization without scalability sacrifice. |
| AI-Native Inference Engine Buildout | Real-time personalization engines in Australian banking command premium deployment budgets for sub-second recommendation systems. |
| Regional Language Localization | Vietnamese and Filipino mid-market retail chains lack attribution sophistication, creating first-mover advantage for localized platforms. |
| Composable Customer Data Platform Architecture | Australian banks and Indian e-commerce platforms adopt API-first stacks to preserve procurement leverage against vendor lock-in. |
Research Methodology
Document review covered vendor product roadmaps, regulatory filings with India's Digital Personal Data Protection Commission and Japan's Personal Information Protection Commission, and hyperscaler data center expansion announcements, complemented by interviews with chief technology officers at Australian enterprise banks, marketing operations directors at Indian e-commerce platforms, compliance officers at Japanese insurance carriers, and channel partners serving Southeast Asian retail chains. Secondary validation drew from SEC filings of listed marketing cloud vendors, Reserve Bank of India guidance circulars, and Monetary Authority of Singapore technology risk management guidelines. Bottom-up deployment counts across service types and deployment models were triangulated against top-down addressable market estimates derived from IT spending surveys.
Cross-referencing historical adoption velocity against panel input from procurement officers and integration specialists shaped the analytical framework across the projection horizon. Segmentation modeling incorporated deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster dimensions. CAGRs were derived through trend extrapolation adjusted for regulatory inflection points and infrastructure investment cycles. Forecast inputs included AI-native development capacity constraints in Bangalore and Singapore, and data center buildout timelines across Sydney and Tokyo.
Regulatory enforcement intensity shifts, hyperscaler pricing recalibration, and talent migration patterns across Indian and Singapore software clusters are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around sustained subscription pricing displacement and hybrid cloud preference persistence among regulated sectors. A compact set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Personal Cloud Market
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Healthcare Cloud Computing Software Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Application Hosting Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
Cloud CDN Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
Global Marketing Cloud Platform Market
Cloud Computing
Cloud Database Market