
 Cloud API and Management Platforms and Middleware Market | 2026-2036
Cloud API and Management Platforms and Middleware Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud API and Management Platforms and Middleware Market Outlook
Enterprise buyer concentration in the IT services sector is consolidating as systems integrators and managed service providers aggregate procurement across client portfolios. MuleSoft anchors its position through deep Salesforce ecosystem integration and enterprise workflow automation capabilities. IBM API Connect competes on hybrid cloud governance, leveraging mainframe heritage to serve regulated industries with strict data residency requirements.
Cloud API and management platforms and middleware constitute software infrastructure that mediates data exchange between distributed applications through standardized protocols including REST, GraphQL, and event-driven architectures, enabling real-time interoperability across heterogeneous systems. API Gateway solutions dominate current revenue flows due to their foundational role in traffic management and authentication, while Integration Platform deployments in hybrid cloud configurations represent the fastest-expanding segment as enterprises straddle legacy and cloud-native workloads. Security Management solutions within the solution dimension command premium pricing because regulatory pressure on data exposure has elevated API threat protection from operational feature to board-level priority.
The EU AI Act, GDPR, and the US SEC cybersecurity disclosure rules collectively reshape product roadmaps by mandating audit trails, access logging, and automated compliance reporting as standard platform capabilities. ISO 27001 and SOC 2 Type II certifications have become non-negotiable market access prerequisites for vendors serving BFSI and healthcare-adjacent IT services clients. Stakeholders must evaluate whether their API management investments can absorb emerging quantum-resistant encryption standards and cross-border data localization requirements without architectural overhaul.
Market Dynamics
Enterprise cloud migration is fragmenting workload placement across on-premises, multi-cloud, and edge environments, forcing API management vendors to architect for heterogeneity rather than platform loyalty.
Growth Catalysts
- Open Banking Mandates:BFSI institutions in the European Union deploy API gateways to satisfy PSD2 and GDPR interoperability requirements, accelerating procurement cycles for governance-enabled platforms.
- Event-Driven Architectures:Real-time data streaming protocols are displacing batch processing in retail and logistics, expanding addressable market for asynchronous API middleware.
- United States:SEC cybersecurity disclosure rules and fintech interoperability standards are compelling Fortune 500 enterprises to consolidate fragmented API tooling into unified management layers.
Market Restraints
- Specialized Talent Scarcity:Shortage of engineers proficient in GraphQL schema design and zero-trust security architecture inflates implementation timelines and professional services dependency.
- Hybrid Complexity Tax:Enterprises maintaining legacy SOAP services alongside cloud-native REST APIs face integration debt that slows platform standardization and extends payback periods.
- Input Cost Volatility:Cloud compute pricing from hyperscalers fluctuates unpredictably, compressing margins for API gateway vendors operating consumption-based pricing models.
Strategic Opportunities
- Quantum-Resistant Cryptography:NIST post-quantum standards are electrifying demand for cryptographic agility modules within API security stacks, creating first-mover advantage for compliant vendors.
- Healthcare Data Exchange:HIPAA-compliant API interoperability for electronic health records remains underpenetrated, with hospital systems seeking middleware that bridges HL7 FHIR and legacy HL7 v2 protocols.
- India:RBI's account aggregator framework and UPI ecosystem expansion are generating greenfield demand for domestic API infrastructure serving fintech and insurtech segments.
Industry Challenges
- Multi-Cloud Governance Fragmentation:DevOps teams struggle to maintain consistent policy enforcement across AWS API Gateway, Azure APIM, and Google Cloud Endpoints without centralized control planes.
- Compliance Velocity Gap:ISO 27001 and SOC 2 Type II certification cycles lag behind customer procurement timelines, disqualifying emerging vendors from regulated industry RFPs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud API and Management Platforms and Middleware Market |
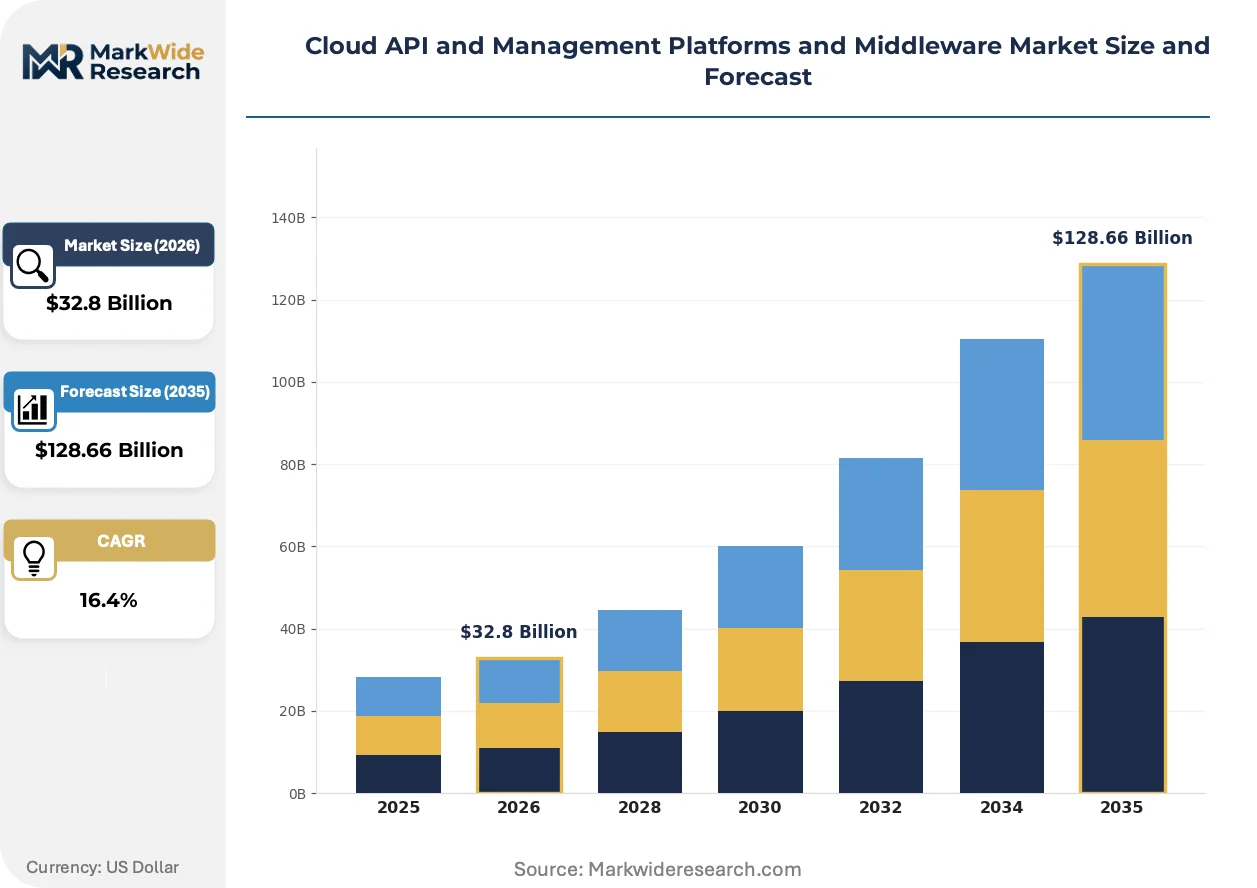
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $128.66 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: API Gateway, Integration Platform, Middleware Solution, Management Tool Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: IT Services, Retail, Telecommunications, BFSI Solution: Data Integration, Workflow Automation, Security Management, Performance Monitoring |
| Companies Covered | Kong, Tyk, Apigee, IBM API Connect, Zuplo, AWS API Gateway, MuleSoft, Cloudflare, Microsoft Azure API Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud API and Management Platforms and Middleware Market Strategic Shifts
Artificial intelligence is embedding into API operations through automated schema generation, anomaly detection, and natural language interface design, compressing the traditional development lifecycle.
GraphQL federation is electrifying enterprise architecture by enabling microservices to expose unified query endpoints without monolithic aggregation layers. Retail and media conglomerates are adopting federated schemas to consolidate product catalogs across acquired subsidiaries. This architecture is compressing time-to-market for cross-platform feature launches while reducing backend payload overhead.
The EU AI Act's risk classification framework is mandating audit trails and explainability hooks for automated decision systems accessed via APIs. Financial services and healthcare API providers must now embed logging granularity that satisfies both GDPR data subject requests and AI Act conformity assessments. European enterprises are responding by procuring governance platforms with built-in regulatory reporting modules rather than building compliance instrumentation ad-hoc.
Developer experience has become the primary procurement criterion as platform engineering teams evaluate API management tools through lens of onboarding friction and documentation quality. Self-service portal adoption is displacing traditional ticket-based API provisioning in technology and telecommunications verticals. This behavioral shift is most pronounced in the United States, where internal platform teams prioritize developer productivity metrics over raw throughput benchmarks in vendor selection.
Cloud API and Management Platforms and Middleware Market Segmentation
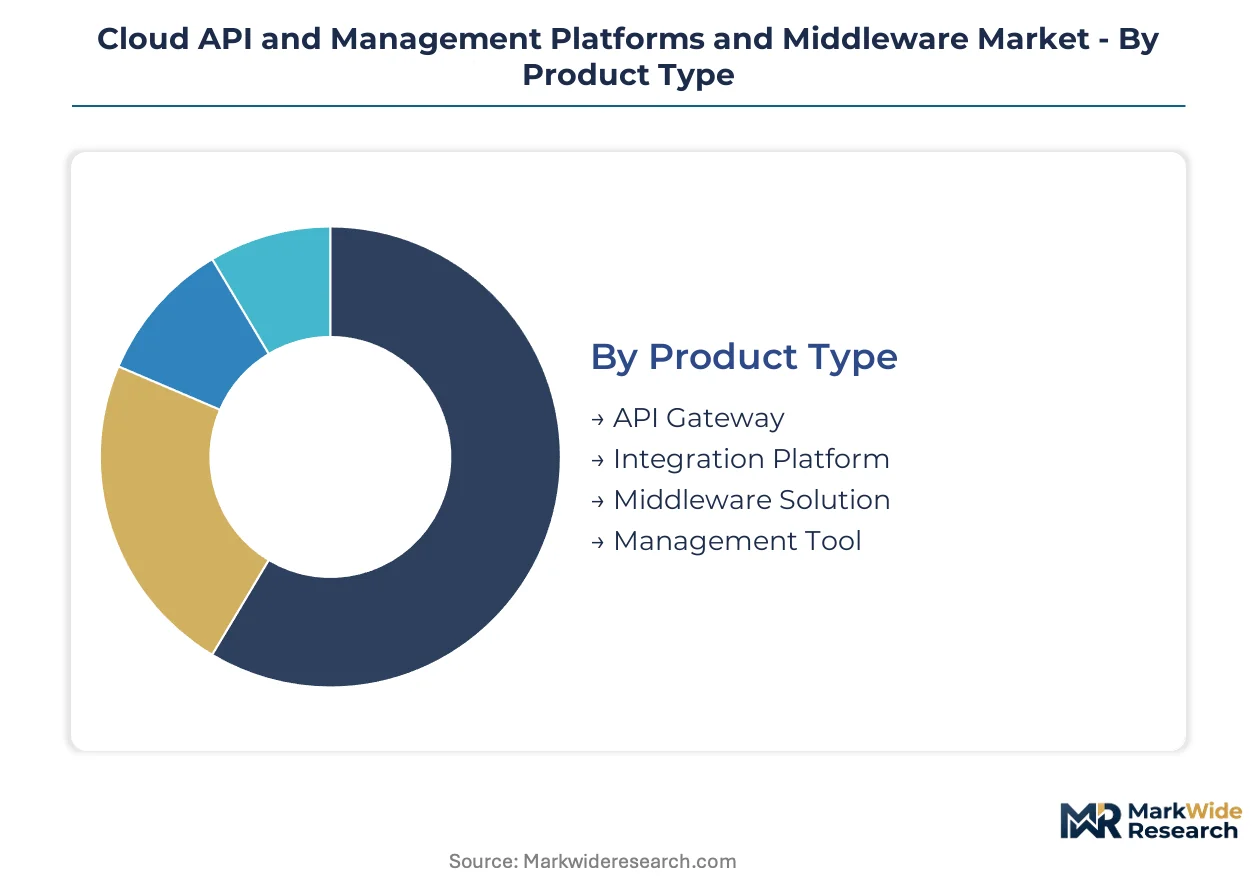
Segmentation in Cloud API and Management Platforms and Middleware reveals how procurement priorities diverge across infrastructure maturity levels. Buyers in regulated sectors prioritize governance depth over raw throughput, while cloud-native enterprises optimize for developer velocity and consumption economics.
Product Type:
Capital intensity varies sharply across product categories, with Integration Platforms demanding the heaviest upfront engineering investment for hybrid cloud orchestration.
- API Gateway:Traffic management and authentication middleware that sits at the edge of distributed systems. BFSI institutions in Germany and France deploy these to satisfy PSD2 open banking mandates, with procurement cycles accelerating under EU AI Act audit requirements.
- Integration Platform:Enterprise-grade orchestration engines connecting legacy SOAP services to cloud-native REST and GraphQL endpoints. United States healthcare systems and federal contractors absorb the bulk of hybrid deployment spending as they straddle on-premises EHR systems with cloud analytics.
- Middleware Solution:Message queuing and event-streaming infrastructure for asynchronous application communication.
- Management Tool:Lifecycle governance and developer portal software for API cataloging and version control.
API Gateway absorbs the bulk of installed capacity; Integration Platform is expanding most quickly as enterprises confront hybrid complexity.
Deployment:
Operational cost structures diverge dramatically between consumption-based public cloud models and fixed-capital on-premises installations.
- Hybrid Cloud:Split-workload architectures spanning private data centers and hyperscaler environments. United States Fortune 500 enterprises and defense contractors dominate demand, driven by SEC cybersecurity disclosure rules and data residency requirements for financial recordkeeping.
- Public Cloud:Fully managed API services operated by hyperscalers with pay-per-call pricing. Technology startups in India and Southeast Asian fintech clusters favor this model for UPI and account aggregator framework compliance without infrastructure ownership.
- Private Cloud:Single-tenant deployments within enterprise-controlled virtualized environments.
- On-Premises:Bare-metal installations in customer data centers with full operational responsibility retained in-house.
Public Cloud captures the greatest transaction volume; Hybrid Cloud is gaining share fastest among regulated industries.
End User:
Procurement sophistication correlates directly with sectoral regulatory exposure and API dependency depth.
- BFSI:Banking, financial services, and insurance institutions with stringent compliance obligations. European Union institutions under ECB supervision and United States banks facing OCC guidance deploy API gateways for real-time payment rails and open finance data sharing.
- IT Services:Systems integrators and managed service providers aggregating procurement across client portfolios. Indian IT majors and US-based consultancies drive standardization as they operationalize API management as a repeatable service line.
- Retail:Omnichannel merchants integrating POS, inventory, and fulfillment systems.
- Telecommunications:Network operators exposing subscriber and usage data through partner APIs.
BFSI commands the deepest per-seat investment; IT Services is scaling fastest through platform consolidation across client estates.
Solution:
Pricing power concentrates in capabilities that reduce regulatory liability and operational risk.
- Security Management:Threat protection, encryption, and access control modules for API attack surface reduction. Healthcare organizations under HIPAA and European entities under GDPR pay premium pricing for automated compliance reporting and audit trail generation.
- Workflow Automation:Low-code orchestration for business process integration across SaaS applications. United States mid-market enterprises and Indian insurtech startups adopt these to compress integration timelines without specialized engineering hires.
- Data Integration:Schema mapping and transformation engines for heterogeneous system interoperability.
- Performance Monitoring:Observability and latency analytics for API health and SLA enforcement.
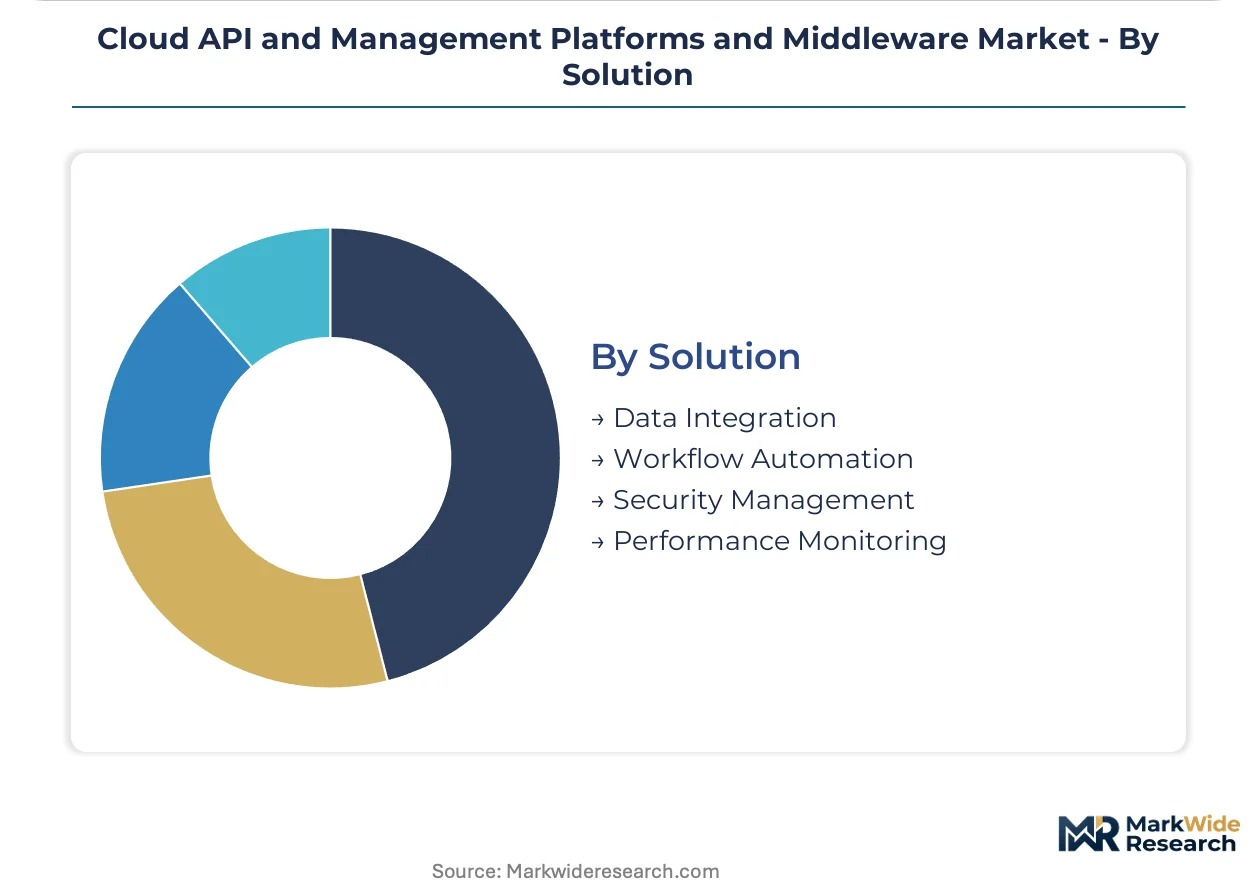
Security Management captures the highest margin premiums; Workflow Automation is climbing the fastest as business units bypass centralized IT for self-service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in the United States, where Fortune 500 cloud migration and fintech interoperability standards drive platform adoption. European Union regulatory mandates reshape investment patterns across Germany, France, and the Netherlands. Asian demand clusters in India and Japan, where domestic payment infrastructure and manufacturing digitization create distinct procurement profiles.
United States
SEC cybersecurity disclosure rules and OCC guidance compel banks and federal contractors to consolidate fragmented API tooling into unified management layers. The Federal Reserve's FedNow instant payment rail accelerates gateway procurement for real-time settlement infrastructure. Silicon Valley and New York Metro technology clusters absorb the bulk of hybrid cloud deployment spending as enterprises straddle legacy systems with cloud-native workloads.
Germany
PSD2 open banking mandates and BaFin supervisory requirements drive BFSI institutions toward governance-enabled gateway platforms. The EU AI Act's risk classification framework mandates audit trail granularity for automated decision systems accessed via APIs. Frankfurt's financial services cluster and Munich's industrial technology corridor anchor domestic demand for middleware bridging legacy SAP environments with cloud analytics.
France
CNIL enforcement of GDPR data subject rights and the EU AI Act's conformity assessment requirements elevate API logging and explainability to board-level priorities. The country's national banking regulator, ACPR, supervises open finance data sharing protocols through API gateways. Paris-based insurtech startups and Lyon manufacturing hubs procure workflow automation platforms to compress integration timelines without specialized engineering hires.
India
RBI's account aggregator framework and UPI ecosystem expansion generate greenfield demand for domestic API infrastructure serving fintech and insurtech segments. The central bank's digital payment security guidelines mandate encryption standards that elevate procurement for security management modules. Mumbai's financial district and Bengaluru's technology corridor concentrate platform adoption as IT services majors operationalize API management as repeatable service lines.
Japan
METI's Society 5.0 digitization roadmap and the Financial Services Agency's open banking guidelines accelerate middleware investment for manufacturing and BFSI verticals. The country's national IT regulator, MIC, oversees data localization requirements that favor hybrid cloud configurations. Tokyo's enterprise headquarters and Osaka's industrial automation clusters drive demand for event-driven architectures displacing batch processing in supply chain operations.
Cloud API and Management Platforms and Middleware Market Competitive Environment
United States-based hyperscalers and enterprise software vendors anchor one tier; European and Asia-Pacific specialists hold differentiated positions in security-first and developer-experience segments. Market structure exhibits moderate consolidation around ecosystem-integrated platforms, with fragmentation persisting in niche security and workflow automation modules. Three archetypes dominate: cloud-native challengers emphasizing consumption economics, incumbent enterprise suites leveraging mainframe heritage for regulated industries, and API-first specialists optimizing developer onboarding friction. Competitive dynamics center on strategic partnerships embedding management layers into broader cloud ecosystems, and portfolio diversification into adjacent security and observability capabilities.
Within the ecosystem-integrated tier, MuleSoft and IBM API Connect exemplify divergent heritage strategies—one anchored in SaaS workflow automation, the other in hybrid cloud governance for data-residency-sensitive clients. Kong represents the cloud-native challenger archetype, occupying a position where developer experience metrics and open-source community traction drive procurement decisions among technology startups and platform engineering teams. These three companies illustrate how competitive positioning fragments across enterprise procurement criteria: ecosystem loyalty, regulatory compliance depth, and developer velocity optimization.
| Leading Market Players |
|---|
| Kong |
| Tyk |
| Apigee |
| IBM API Connect |
| Zuplo |
| AWS API Gateway |
| MuleSoft |
| Cloudflare |
| Microsoft Azure API Management |
| Others |
Value Chain & Pricing Dynamics
BFSI procurement officers in Frankfurt and New York anchor enterprise spending, forcing API management vendors toward consumption-based SaaS tiers with governance premiums layered atop base throughput rates.
Pricing Analysis
High-volume API gateway traffic generates thin margins while security management modules and compliance automation capture outsized returns. Pricing stratifies across enterprise-grade governance platforms, mid-market integration suites, and developer-centric open-source gateways with commercial support tiers. Cost compression in public cloud gateway services intensifies as hyperscalers bundle API management into broader infrastructure contracts. Cloud-native startups in India exhibit acute price sensitivity, while United States federal contractors absorb premium pricing for FedRAMP-authorized deployments.
Supply Chain Analysis
Reverse logistics for on-premises middleware licenses involves certificate revocation flows, patch redistribution, and version rollback protocols that vendors manage through automated update infrastructure. Engineering talent concentrates in the United States, India, and Germany, with hyperscaler cloud regions feeding compute resources from Ireland, Singapore, and Virginia. The supply chain draws from specialized cryptography libraries, open-source runtime environments, and third-party identity federation services. Single-source vulnerability in NIST-certified encryption modules creates concentration risk. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GraphQL federation and event-driven architectures are displacing monolithic REST aggregation layers, compressing development cycles while demanding new governance instrumentation.
For Market Incumbents: Hedge against cloud-native challenger erosion by embedding quantum-resistant cryptography modules before NIST standards harden into procurement requirements. Deepen mainframe-to-cloud bridge capabilities for United States federal contractors facing data residency mandates. Acquire specialized workflow automation vendors to fill portfolio gaps in low-code orchestration. For New Entrants and Emerging Players: Capture whitespace in HIPAA-compliant healthcare data exchange where legacy HL7 v2-to-FHIR bridging remains underpenetrated. Target India's account aggregator framework implementations with domestic-hosted API infrastructure. Lead with developer experience metrics and self-service onboarding to differentiate against incumbent complexity. For Investors and Strategic Acquirers: The window for entry favors API-first specialists with proven GraphQL federation traction and established open-source community adoption. Long-term viability hinges on regulatory compliance depth rather than raw throughput scale. Monitor NIST post-quantum standard finalization as inflection signal for cryptographic agility platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Cryptography Integration | NIST compliance modules create first-mover pricing power in BFSI procurement cycles. |
| Healthcare Interoperability Certification | HL7 FHIR bridging capabilities unlock hospital system RFPs under HIPAA mandates. |
| Developer Portal Self-Service Launch | Low-friction onboarding displaces ticket-based provisioning in technology verticals. |
| Hyperscaler Marketplace Expansion | AWS and Azure distribution channels capture mid-market procurement velocity. |
| Regulatory Reporting Module Development | EU AI Act audit automation commands premium pricing from European enterprises. |
Study Parameters
Document review covered SEC cybersecurity disclosure filings, EU regulatory frameworks, and hyperscaler capex disclosures, complemented by interviews with platform engineering directors, API product managers, and enterprise architects at BFSI institutions. Primary fieldwork engaged CTOs at Fortune 500 enterprises, integration specialists at systems integrators, and procurement officers at healthcare systems. Secondary validation drew from ISO certification databases, SOC 2 audit registries, and open banking implementation reports. Bottom-up deployment estimates and top-down market sizing were triangulated against vendor revenue disclosures.
Segment-level outputs across the projection horizon reflect modeled adoption curves by deployment architecture, solution capability, and end-use vertical. The analytical framework incorporated organization size tiers, integration complexity levels, and regional regulatory clusters. CAGRs were derived from deployment velocity benchmarks, professional services attach rates, and consumption pricing elasticity. Forecast inputs included FedNow infrastructure rollout timelines, RBI account aggregator framework expansion, and EU AI Act enforcement phase transitions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to quantum computing timeline acceleration and cross-border data localization treaty revisions. Forecasts reflect assumptions about hyperscaler pricing stability and certification cycle durations. Practitioners should monitor NIST post-quantum standard publication, SEC cybersecurity disclosure rule amendments, and central bank real-time payment rail deployments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Microservices Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Automotive Cloud Based Solutions Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
North America Cloud Microservices Platform Market
Cloud Computing
Consumer Cloud Subscription Market
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Public Cloud Market