
 Global Server Virtualization Market | 2026-2036
Global Server Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Server Virtualization Market Outlook
Container-to-virtual-machine orchestration is rewriting how enterprises deploy and manage compute workloads. VMware sustains technology leadership through deep integration across hybrid environments. Microsoft leverages Azure Stack to anchor on-premises-to-cloud continuity. Red Hat competes through open-source virtualization stacks that appeal to cost-sensitive operators.
Server virtualization partitions physical servers into multiple isolated virtual instances, each running independent operating systems with allocated CPU, memory, and storage resources abstracted through a hypervisor layer. The technology enables workload consolidation, disaster recovery automation, and elastic capacity scaling across enterprise data centers. Hybrid cloud deployment models capture the widest margin pools as enterprises retain sensitive workloads on-premises while bursting to public infrastructure. Hardware-assisted virtualization leads in performance-critical segments due to native CPU extensions from Intel VT-x and AMD-V. OS-level virtualization grows fastest among cloud-native developers seeking lightweight isolation without full guest OS overhead.
FDA guidelines for healthcare data integrity, EU GDPR requirements for cross-border data residency, and China's GB standards for critical information infrastructure collectively shape product certification and geographic deployment choices. India's BIS and TRAI frameworks increasingly influence how multinational vendors architect regional data center footprints. Stakeholders must monitor evolving sovereign cloud mandates and hypervisor security certifications as procurement criteria harden across regulated industries.
Market Dynamics
Container-to-virtual-machine orchestration is collapsing the boundary between legacy virtualization and cloud-native infrastructure, forcing hypervisor vendors to rewrite their value propositions around workload portability rather than isolation density alone.
Growth Catalysts
- EU AI Act compliance mandates:Organizations across France and Germany are procuring certified virtualization stacks to maintain audit trails for AI training workloads, accelerating replacement of unlicensed hypervisor deployments.
- Healthcare data integrity requirements:FDA 21 CFR Part 11 guidelines for electronic records are driving US hospital systems toward hardware-assisted virtualization with immutable logging capabilities.
- India's data localization push:BIS and TRAI frameworks for critical information infrastructure are compelling cloud providers to establish domestic virtualization capacity, expanding addressable market for on-premises deployment.
Market Restraints
- Hypervisor licensing cost inflation:Per-socket pricing models from dominant vendors are compressing margins for managed service operators running high-density blade servers.
- Silicon supply concentration:Native virtualization extensions depend on Intel VT-x and AMD-V instruction sets, creating vulnerability to foundry capacity constraints in Taiwan and South Korea.
- Container substitution pressure:Kubernetes-native workloads are bypassing traditional hypervisor layers entirely, eroding addressable market among cloud-native development teams.
Strategic Opportunities
- Brazil's regulated cloud expansion:ANVISA and central bank guidelines for financial services data residency are opening whitespace for sovereign virtualization infrastructure in São Paulo and Rio de Janeiro metro clusters.
- Edge-to-core orchestration convergence:Integration of hypervisor management with 5G multi-access edge computing platforms is enabling new service tiers for manufacturing automation and autonomous vehicle infrastructure.
- Japan's METI green computing incentives:Subsidies for workload consolidation and server utilization optimization are accelerating virtualization refreshes in Tokyo-Osaka industrial corridors.
Industry Challenges
- Cross-hypervisor migration complexity:Converting VMware vSphere workloads to KVM or Hyper-V environments requires specialized engineering talent scarce outside major technology hubs.
- Security certification latency:Common Criteria EAL4+ and FIPS 140-2 validation timelines for new hypervisor releases routinely extend 18-24 months, delaying product launches in defense and intelligence segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Server Virtualization Market |
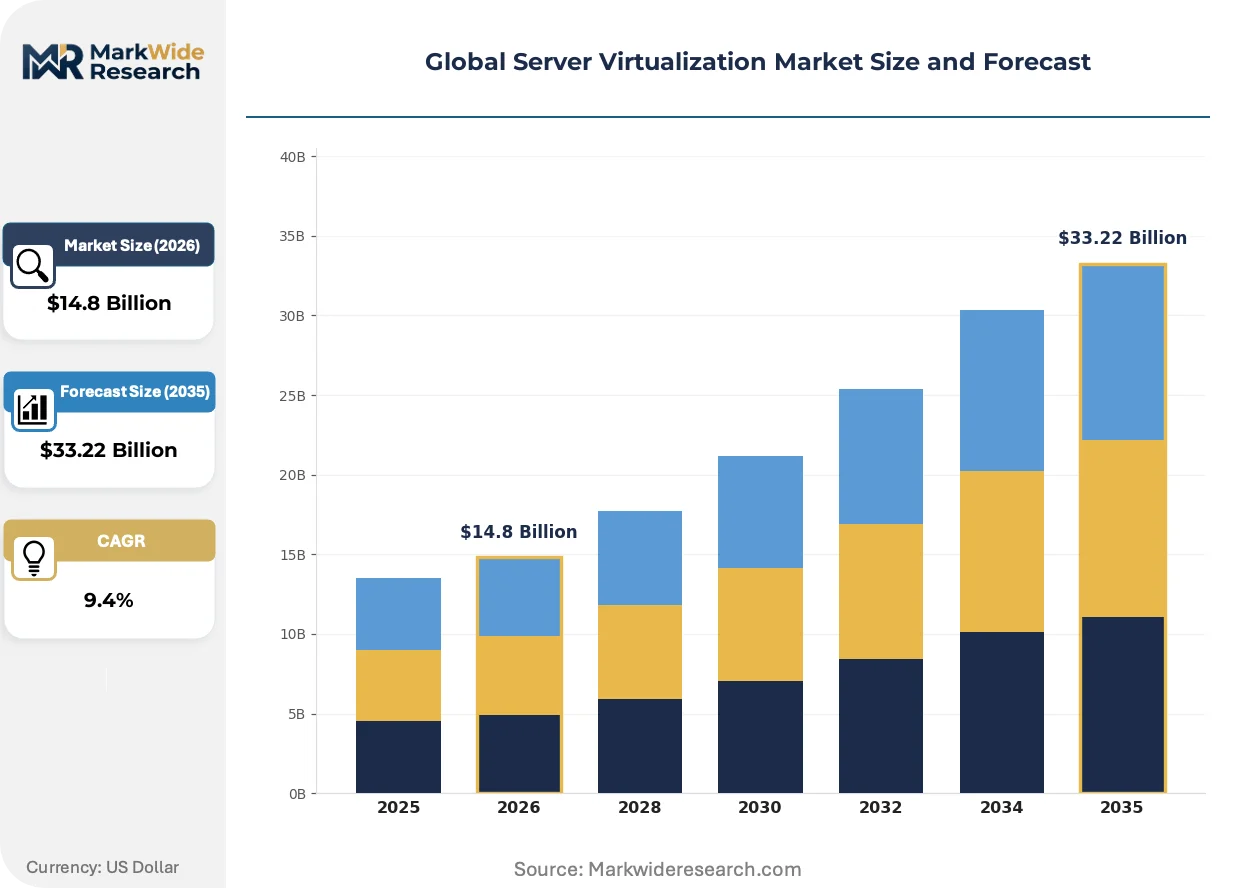
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
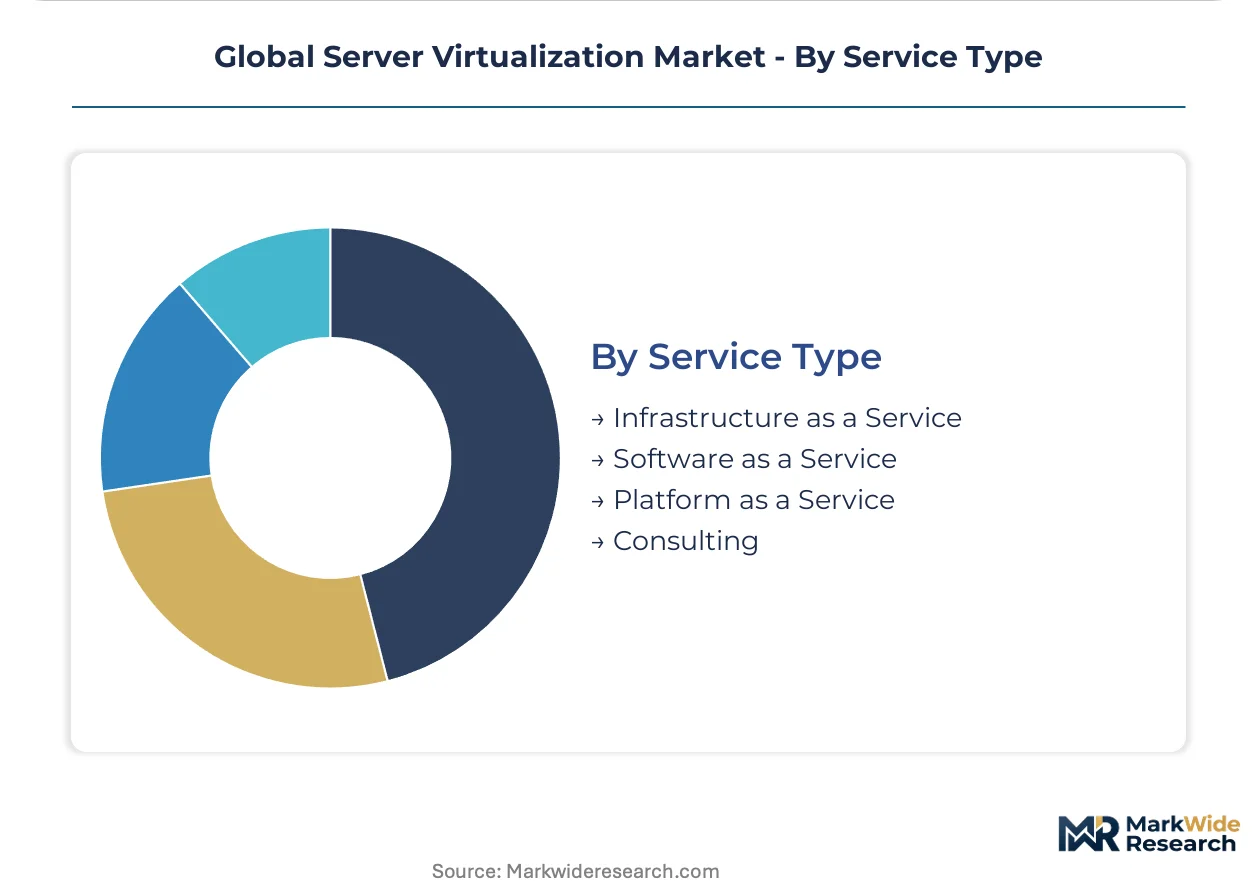
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Virtualization Type: Full Virtualization, Para-Virtualization, Hardware-Assisted Virtualization, OS-Level Virtualization End User Segment: SMEs, Large Enterprises, Government Agencies, Educational Institutions Service Type: Infrastructure as a Service, Software as a Service, Platform as a Service, Consulting |
| Companies Covered | Red Hat, Huawei, VMware, Amazon Web Services, IBM, Microsoft, Oracle, Cisco Systems, Citrix Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Server Virtualization Market Strategic Shifts
Virtualization technology is fragmenting into specialized layers optimized for distinct workload profiles, with hardware abstraction, container runtime, and serverless execution converging into unified control planes.
Confidential computing extensions are virtualizing memory encryption at the hardware level, isolating sensitive workloads from cloud provider administrators. Financial services firms in Switzerland and Singapore are piloting these capabilities for quantitative trading algorithms. The technology is virtualizing trust boundaries that previously required physical air-gapping.
China's GB standards for critical information infrastructure are mandating domestic hypervisor certification for government and state-owned enterprise procurement. MIIT compliance testing now covers virtualization security benchmarks previously absent from national standards. Domestic vendors are accelerating development to capture replacement demand as foreign platforms face exclusion from sensitive workloads.
Enterprise buyers are consolidating vendor relationships around integrated infrastructure stacks rather than best-of-breed point solutions. Procurement committees at German automotive manufacturers and US healthcare systems are bundling hypervisor, storage virtualization, and network overlay decisions into single sourcing events. This pattern concentrates purchasing power with full-stack providers and compresses evaluation cycles for standalone virtualization specialists.
Global Server Virtualization Market Segmentation

Segmentation in server virtualization reveals how procurement patterns split across infrastructure maturity levels and compliance requirements. Understanding these divides helps vendors align licensing models with customer operational capabilities and regulatory exposure.
Deployment Model:
After-sales service intensity varies sharply across deployment models, with hybrid configurations demanding continuous orchestration support while on-premises installations require periodic hardware refresh consulting.
- Hybrid Cloud:Workloads span on-premises hypervisors and public infrastructure through unified management planes. German automotive manufacturers and US hospital systems concentrate demand here, driven by EU AI Act audit trail requirements for AI training environments.
- On-Premises: Traditional data center virtualization retains sensitive workloads under direct physical control. India's BIS-mandated data localization and China's GB standards for critical infrastructure sustain procurement in domestic banking and government sectors.
- Public Cloud: Multi-tenant virtualization abstracts physical infrastructure entirely. Cloud-native developers in São Paulo and Singapore leverage this for burst capacity without capital expenditure.
- Private Cloud: Dedicated single-tenant virtualization within service provider facilities. Swiss financial services firms deploy this for quantitative trading algorithms requiring confidential computing extensions.
Hybrid Cloud holds the largest share; momentum sits with On-Premises as sovereign data mandates expand.
Virtualization Type:
Cost tier stratification separates hardware-assisted approaches commanding premium licensing from lightweight OS-level alternatives appealing to budget-constrained operators.
- Hardware-Assisted Virtualization:Native CPU extensions from Intel VT-x and AMD-V enable near-native performance for demanding workloads. US healthcare systems pursuing FDA 21 CFR Part 11 compliance favor this for immutable logging capabilities in electronic records systems.
- OS-Level Virtualization: Container-style isolation shares the host kernel without full guest OS overhead. Cloud-native development teams in India's technology corridors adopt this fastest for microservices deployment density.
- Full Virtualization: Complete hardware abstraction with unmodified guest operating systems. Legacy enterprise workloads in Japan's Tokyo-Osaka industrial corridors continue relying on this proven architecture.
- Para-Virtualization: Modified guest kernels cooperate directly with the hypervisor for efficiency. Specialized high-performance computing environments in Brazil's research institutions maintain niche deployments.
Hardware-Assisted Virtualization dominates revenue; OS-Level Virtualization is climbing the fastest as container adoption accelerates.
End User Segment:
Application criticality drives segmentation, with regulated industries accepting higher per-socket licensing costs for certified stacks while educational institutions prioritize open-source alternatives.
- Government Agencies:Sovereign cloud mandates and security certification requirements shape procurement. China's MIIT compliance testing and India's TRAI frameworks for critical information infrastructure compel domestic virtualization capacity expansion.
- Large Enterprises: Complex multi-site environments require unified management across heterogeneous infrastructure. German manufacturers bundle hypervisor, storage, and network decisions into consolidated sourcing events.
- SMEs: Limited IT staffing drives preference for managed service consumption models. Cost-sensitive operators in Brazil's emerging metro clusters seek open-source KVM stacks over proprietary alternatives.
- Educational Institutions: Research computing and student training environments demand flexible licensing. Japan's METI green computing incentives accelerate workload consolidation projects in university data centers.
Large Enterprises command the greatest volume; Government Agencies are gaining share fastest through sovereign infrastructure investment.
Service Type:
Customer sophistication determines service attachment, with infrastructure-as-a-service offerings capturing recurring revenue from operators lacking in-house virtualization expertise.
- Infrastructure as a Service:Fully managed virtualization capacity delivered on consumption basis. Managed service operators across India's domestic market leverage this to circumvent per-socket licensing inflation on high-density blade servers.
- Consulting: Migration engineering and architecture design for complex transformations. Cross-hypervisor conversions from VMware vSphere to KVM or Hyper-V require specialized talent concentrated in major technology hubs.
- Platform as a Service: Developer-centric abstraction layering container orchestration atop virtual infrastructure. Cloud-native teams in Singapore and Switzerland pilot confidential computing integrations through these offerings.
- Software as a Service: Application-level delivery without infrastructure visibility. Administrative tooling and monitoring platforms reach smaller operators unable to maintain dedicated virtualization engineering.
Infrastructure as a Service generates the largest revenue pool; Consulting shows the steepest expansion trajectory as migration complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based virtualization vendors export orchestration platforms to German automotive manufacturers and Indian cloud operators, establishing a transatlantic-Asian trade corridor that concentrates technology licensing revenue in North American headquarters while deployment spreads across three continents.
United States
Hospital systems and financial services firms drive procurement of hardware-assisted virtualization stacks with immutable logging capabilities. FDA 21 CFR Part 11 guidelines for electronic records integrity shape certification requirements for healthcare deployments. The Dallas-Fort Worth metro cluster hosts expanding data center capacity serving central US enterprise demand.
Germany
Automotive manufacturers and industrial machinery producers require hybrid cloud orchestration for AI training workload audit trails. EU AI Act compliance mandates accelerate replacement of unlicensed hypervisor installations across manufacturing facilities. The Stuttgart-Munich corridor concentrates sovereign cloud infrastructure investment for connected vehicle development.
India
Domestic cloud providers and technology services firms expand virtualization capacity to serve data localization requirements. BIS and TRAI frameworks for critical information infrastructure compel regional data center footprint expansion. Bengaluru and Hyderabad technology corridors anchor hypervisor deployment for financial services and government workloads.
China
State-owned enterprises and government agencies procure domestic-certified virtualization stacks under critical information infrastructure guidelines. MIIT compliance testing now covers virtualization security benchmarks previously absent from national standards. The Beijing-Shanghai axis drives replacement demand as foreign platforms face exclusion from sensitive workloads.
Japan
Industrial manufacturers and research institutions pursue workload consolidation for server utilization optimization. METI green computing incentives subsidize virtualization refreshes in energy-intensive data center operations. The Tokyo-Osaka industrial corridor hosts enterprise deployments combining legacy full virtualization with emerging confidential computing extensions.
Global Server Virtualization Market Competitive Environment
On the supply side, the industry is consolidating around integrated infrastructure stacks rather than standalone hypervisor offerings, with procurement committees bundling compute, storage, and network virtualization decisions into single sourcing events. Three archetypes dominate: full-stack platform vendors anchoring hybrid cloud continuity, open-source specialists capturing cost-sensitive operators, and cloud-native providers abstracting infrastructure entirely. Competitive moves concentrate on strategic partnerships for edge-to-core orchestration and portfolio diversification into confidential computing extensions.
Within the full-stack platform tier, VMware and Microsoft occupy positions defining enterprise hybrid cloud expectations, while Red Hat exemplifies the open-source alternative archetype appealing to managed service operators circumventing per-socket licensing inflation. Amazon Web Services anchors the cloud-native abstraction vector, representing infrastructure-as-a-service delivery that bypasses traditional hypervisor procurement entirely.
| Leading Market Players |
|---|
| Red Hat |
| Huawei |
| VMware |
| Amazon Web Services |
| IBM |
| Microsoft |
| Oracle |
| Cisco Systems |
| Citrix Systems |
| Others |
Value Chain & Pricing Dynamics
Intel and AMD's concentrated control over x86 virtualization extensions in the United States creates asymmetric margin capture, with downstream hypervisor vendors absorbing silicon supply volatility while cloud service providers extract recurring revenue from consumption-based delivery models.
Pricing Analysis
Current-generation hardware-assisted virtualization stacks command substantial premiums over prior-generation full-virtualization licenses and emerging OS-level alternatives. Pricing stratifies across certified enterprise tiers, open-source community editions, and managed service bundles, with FDA 21 CFR Part 11 and EU AI Act certification tiers driving substantial price differentiation. Cost compression in high-density blade server deployments intensifies as managed service operators resist per-socket licensing inflation. Educational institutions and SME segments exhibit the highest price sensitivity, while regulated healthcare and financial services firms accept premium positioning for immutable logging and confidential computing capabilities.
Supply Chain Analysis
Extended payment terms from Taiwanese foundry partners and supply-chain finance facilities anchored in South Korean semiconductor distributors now shape procurement liquidity for virtualization hardware vendors. Silicon wafer supply concentrates in Taiwan, South Korea, and the United States, with x86 CPU fabrication drawing from advanced node capacity at TSMC and Samsung. Memory module and network interface controller dependencies introduce single-source vulnerability from concentrated component suppliers. Distribution runs through authorized enterprise reseller networks and direct hyperscaler procurement channels, with logistics chokepoints at Shanghai and Rotterdam port complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container-to-virtual-machine orchestration is triggering platform-economics inflection, with VMware's Tanzu and Red Hat's OpenShift interoperability layers redefining where value accrues across the virtualization stack.
For Market Incumbents: Pre-empt container-native displacement by embedding hypervisor management into Kubernetes control planes, and deepen upstream integration into confidential computing silicon partnerships with Intel and AMD. VMware and Microsoft must neutralize open-source substitution pressure from KVM-based stacks in India's cost-sensitive domestic cloud market. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA-regulated financial services virtualization whitespace, where sovereign data residency mandates outpace incumbent localization. Target Japan's METI-subsidized green computing refresh cycles with workload consolidation tooling. Lead with consumption-based IaaS delivery to circumvent entrenched per-socket licensing relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across OS-level virtualization and edge-to-core orchestration sub-segments, favoring asset-light software acquisitions over infrastructure-heavy deployments. Target specialist firms with Common Criteria EAL4+ certification pipelines and 5G multi-access edge computing integrations. Monitor confidential computing pilot adoption at Swiss financial services firms as inflection signal for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Integration | Memory encryption extensions isolate Swiss quantitative trading algorithms from cloud administrators. |
| Edge-to-Core Orchestration Partnership | 5G MEC platform integration enables manufacturing automation service tiers in Japan's industrial corridors. |
| Sovereign Cloud Localization | Domestic hypervisor certification captures replacement demand under China's MIIT compliance testing. |
| Open-Source Stack Commercialization | KVM-based offerings circumvent per-socket licensing inflation for India's managed service operators. |
| Cross-Hypervisor Migration Tooling | Automated vSphere-to-KVM conversion addresses scarce engineering talent outside major technology hubs. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with virtualization platform engineers, enterprise IT procurement officers, cloud infrastructure architects, and managed service operations directors; and secondary validation against SEC filings from VMware and Microsoft, hyperscaler capex disclosures from Amazon Web Services, EU AI Act implementation guidance, and FDA 21 CFR Part 11 technical interpretation documents. Bottom-up deployment model sizing and top-down vendor revenue triangulation were cross-referenced for consistency.
Forecast inputs considered deployment model transitions, virtualization type substitution patterns, end-user segment compliance intensity, and regional sovereign cloud investment cycles across the projection horizon. Segmentation dimensions modeled include hardware abstraction layer, workload isolation mechanism, organization scale tier, industry vertical regulatory exposure, and geographic adoption pattern. CAGRs were derived from logistic diffusion curves fitted to historical virtualization penetration data and forward-looking capacity expansion announcements.
Stress conditions across Taiwan semiconductor foundry utilization, Intel and AMD product roadmap execution, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about container-to-VM orchestration adoption velocity and confidential computing hardware availability. Macroeconomic contraction, accelerated container substitution, or sovereign cloud mandate expansion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Global Cloud-Native Software Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
Automotive Cloud Based Solutions Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Cloud Computing Services Market