
 Global Distributed Cloud Market | 2026-2036
Global Distributed Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Global Distributed Cloud Market Foresight
ISO 27001 certification is reorganizing competitive entry barriers for distributed cloud providers, forcing operational discipline around data security governance. Microsoft Corporation leverages its Azure Arc platform to extend hybrid consistency across on-premises and edge environments. Amazon Web Services sustains infrastructure scale through its Wavelength partnerships with telecommunications carriers. Google differentiates through Anthos, anchoring containerized workload portability as a core architectural premise.
Distributed cloud denotes a computing architecture that distributes public cloud services to diverse physical locations while maintaining centralized operational control, typically operating at sub-50 millisecond latency thresholds for edge nodes. Its primary commercial purpose centers on enabling data residency compliance, low-latency processing, and resilient service delivery without sacrificing cloud-native management paradigms. Infrastructure as a Service dominates current spending as enterprises provision compute at edge points, while Network as a Service exhibits the steepest trajectory as 5G rollouts demand programmable connectivity fabrics. Edge Computing use cases command premium positioning due to manufacturing and autonomous system requirements, whereas Content Delivery remains mature with compressed margin pools.
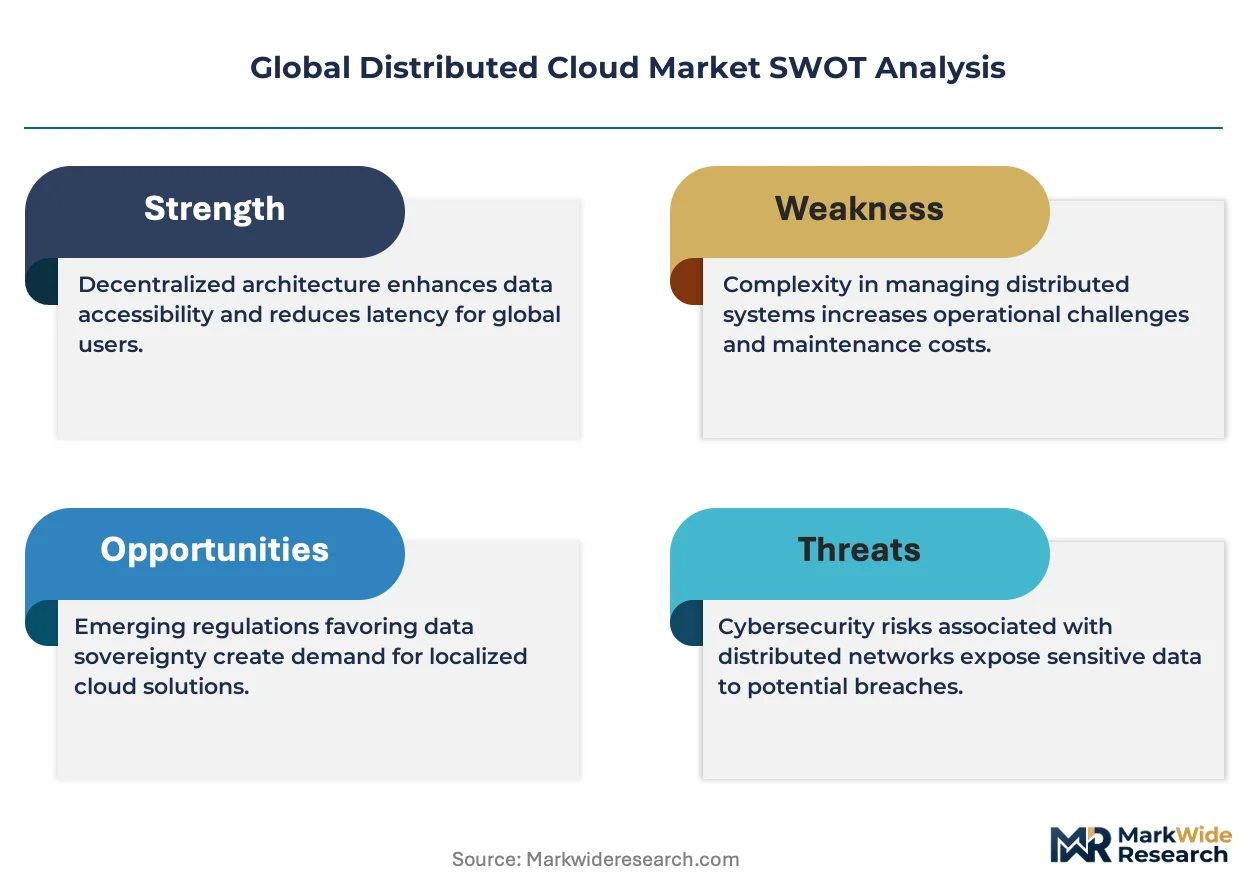
The EU AI Act, GDPR, and ISO standards collectively reshape product architecture by mandating traceable data lineage and regional residency controls. The US FCC and NHTSA influence edge deployment patterns through connected vehicle latency specifications and spectrum allocation rules. China's SAMR and GB standards enforce domestic data-localization thresholds that redirect multinational cloud strategies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance architectures that fragment operational economies.
Market Dynamics
Telecommunications operators are deploying distributed cloud nodes at 5G base stations to meet sub-10 millisecond latency requirements for network slicing, fundamentally restructuring infrastructure investment patterns away from centralized hyperscale facilities.
Growth Catalysts
- EU AI Act data-localization mandates:GDPR Article 44 restrictions on cross-border data transfers compel enterprises to provision sovereign cloud instances within member state borders.
- Industrial automation clusters:Manufacturing facilities in Germany deploy edge-compliant infrastructure to process sensor data without factory-floor-to-cloud round trips.
- Container orchestration portability:Kubernetes-native workload mobility enables consistent deployment patterns across on-premises, edge, and public cloud substrates.
Market Restraints
- Specialized hardware cost concentration:GPU and FPGA acceleration modules for edge AI inference carry 3-4x premiums over standard compute, compressing deployment economics outside high-value use cases.
- Supply chain geographic concentration:Taiwan-based semiconductor foundries dominate advanced node production for edge AI chips, creating single-point vulnerability for node provisioning timelines.
- Interoperability fragmentation:Absence of unified edge management APIs forces enterprises to maintain parallel operational toolchains across vendor environments.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics production create demand for localized edge infrastructure in Tamil Nadu and Gujarat industrial zones.
- Connected vehicle edge nodes:NHTSA latency specifications for V2X communication require roadside unit deployments that distributed cloud architectures uniquely satisfy.
- Energy sector digitalization:FERC Order 2222 aggregation rules for distributed energy resources drive utility investment in substation-level compute for grid optimization.
Industry Challenges
- Edge site engineering talent scarcity:Facilities combining IT and OT competencies require hybrid skill sets that current certification programs inadequately address.
- Multi-jurisdiction compliance orchestration:Simultaneous adherence to GDPR, China's GB standards, and sector-specific US regulations fragments architectural standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Distributed Cloud Market |
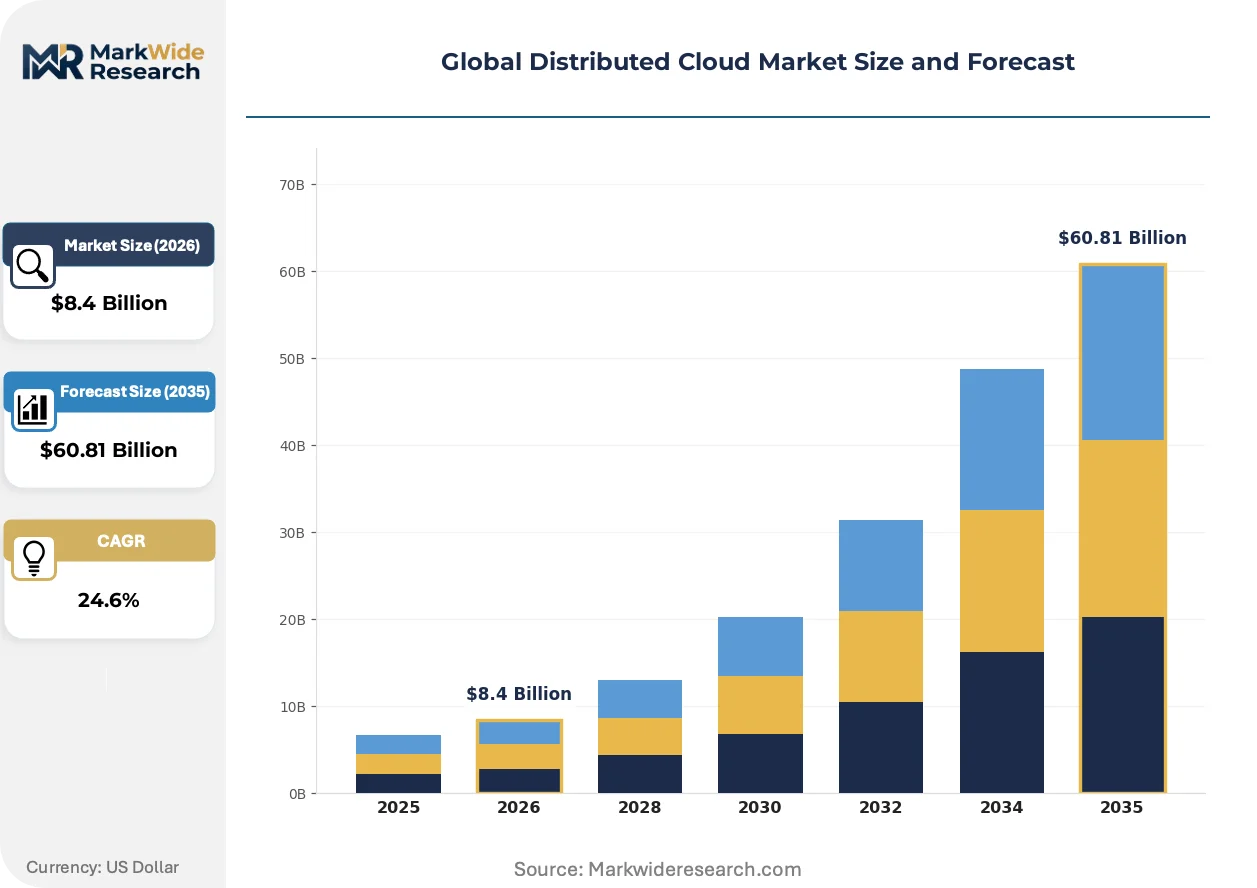
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Hybrid Cloud, Multi-Cloud, Private Cloud Service Offering: Infrastructure as a Service, Platform as a Service, Software as a Service, Network as a Service Use Case: Edge Computing, Content Delivery, Data Sovereignty Management, IoT Connectivity End User Industry: Telecommunications, Manufacturing, Government Agencies, Media & Entertainment |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google, IBM Corporation, Oracle Corporation, Alibaba Cloud, VMware, Teradata, F5, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Distributed Cloud Market Shifts & Advancements
Workload placement logic is migrating from static geographic rules toward real-time latency, cost, and compliance optimization, enabled by software-defined abstraction layers that treat physical infrastructure as fungible capacity pools.
Serverless edge computing is supplanting traditional virtual machine provisioning for event-driven workloads. Automotive manufacturers adopt function-as-a-service models for over-the-air update validation and predictive maintenance analytics. This shift compresses infrastructure management overhead while accelerating deployment velocity for software-defined vehicle programs.
GDPR enforcement actions by CNIL and other European data protection authorities are hardening residency requirements for AI training data. Cloud providers respond with country-specific substrate offerings that maintain operational consistency while satisfying Article 44 transfer mechanism constraints. Financial services and healthcare verticals in France and Germany exhibit strongest demand for these partitioned architectures.
Enterprise buyers now specify outcome-based edge service level agreements that bundle connectivity, compute, and application performance guarantees. Manufacturing procurement teams in Japan and South Korea negotiate uptime commitments tied to production line availability rather than infrastructure availability alone. METI industrial digitalization subsidies accelerate this contracting model shift across automotive and electronics assembly operations.
Global Distributed Cloud Market Segmentation
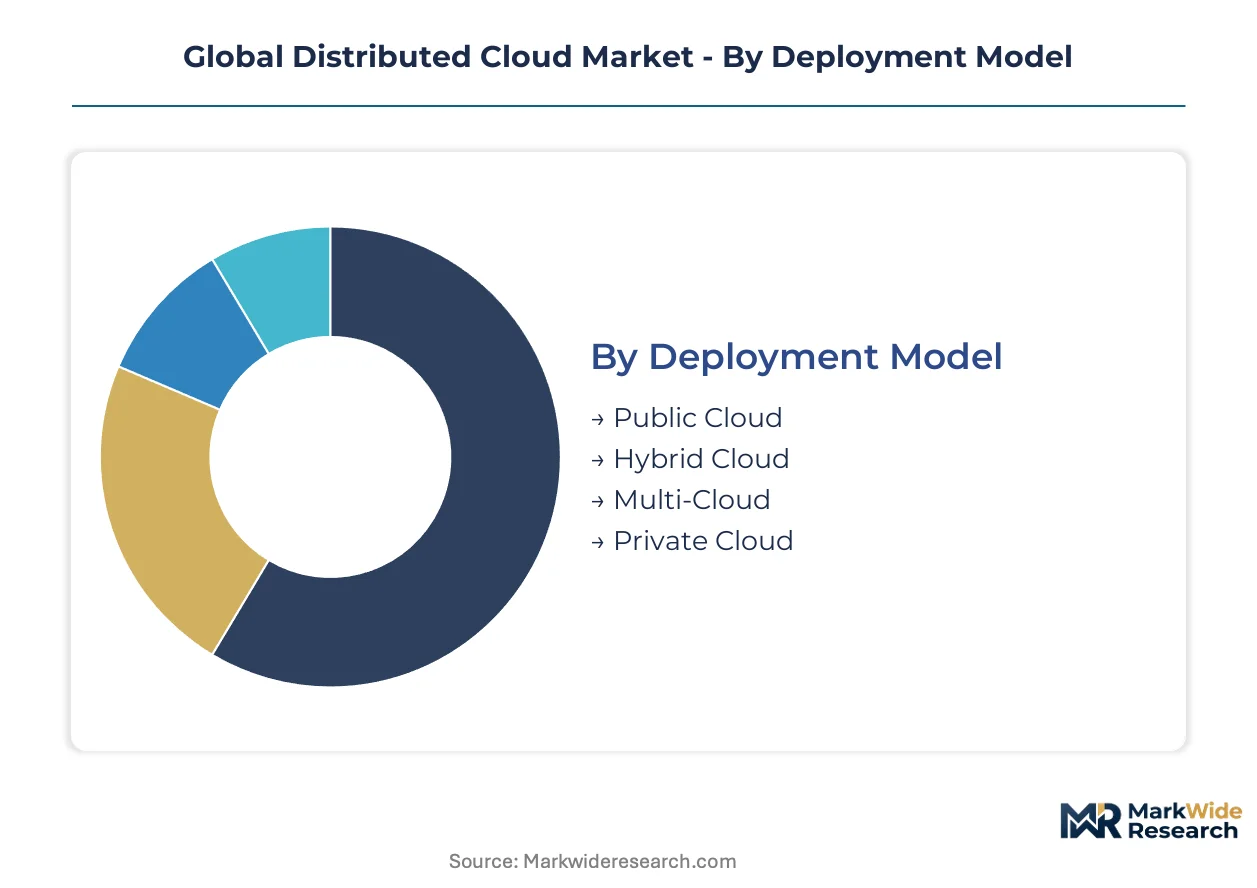
Distributed cloud architectures fragment across deployment topologies, service layers, and compliance requirements. Segmentation reveals where latency constraints, data residency mandates, and workload portability intersect with commercial pricing power.
Deployment Model:
Geographic spread varies sharply: public cloud deployments concentrate in hyperscale regions, while private and hybrid models track data sovereignty enforcement zones.
- Public Cloud:Centralized infrastructure pools serve latency-tolerant workloads across multiple jurisdictions. German automotive manufacturers and Japanese electronics assemblers dominate consumption for non-sensitive batch processing.
- Hybrid Cloud:Combines on-premises sovereignty with burst capacity to public substrates. French healthcare networks and US financial services deploy this architecture to satisfy HIPAA and GDPR Article 44 constraints without sacrificing elasticity.
- Multi-Cloud:Workload distribution across competing hyperscalers reduces vendor lock-in. Enterprise procurement teams in South Korea and Singapore specify multi-cloud mandates in RFPs.
- Private Cloud:Dedicated infrastructure for single-tenant residency requirements. Chinese state-owned enterprises and Saudi government agencies deploy private nodes to satisfy SAMR and domestic data-localization thresholds.
Public cloud commands the established base. The steepest expansion runs through hybrid configurations.
Service Offering:
Cost tiering separates infrastructure provisioning from value-added platform services, with network abstraction layers capturing premium margins.
- Infrastructure as a Service:Bare-metal compute and storage at edge points. Manufacturing facilities in Germany and India provision IaaS for sensor data processing without cloud round trips.
- Platform as a Service:Managed Kubernetes and serverless runtimes abstract infrastructure complexity. Automotive software teams in Japan and Germany adopt PaaS for over-the-air update pipelines.
- Network as a Service:Programmable connectivity fabrics with latency guarantees. Telecommunications operators in the US and South Korea deploy NaaS for 5G network slicing and V2X roadside units.
- Software as a Service:Application-layer delivery from distributed nodes. Media streaming services in Brazil and Australia edge-cache content to reduce transit costs.
Infrastructure as a Service commands the established base. Network as a Service is climbing the fastest.
Use Case:
Application maturity determines margin structure: edge computing captures scarcity premiums while content delivery compresses toward commodity economics.
- Edge Computing:Sub-50 millisecond processing for autonomous systems and industrial automation. German automotive plants and US connected vehicle corridors drive deployment density.
- Content Delivery:Caching and acceleration for media and software distribution. Mature pricing pools in North American and European markets limit expansion velocity.
- Data Sovereignty Management:Jurisdiction-specific residency controls with audit trails. French banking regulators and Chinese SAMR enforcement accelerate enterprise procurement.
- IoT Connectivity:Device ingestion and protocol translation at scale. Indian smart city initiatives and Japanese factory digitalization programs expand addressable volume.
Content delivery commands the established base. Edge computing is gaining share fastest.
End User Industry:
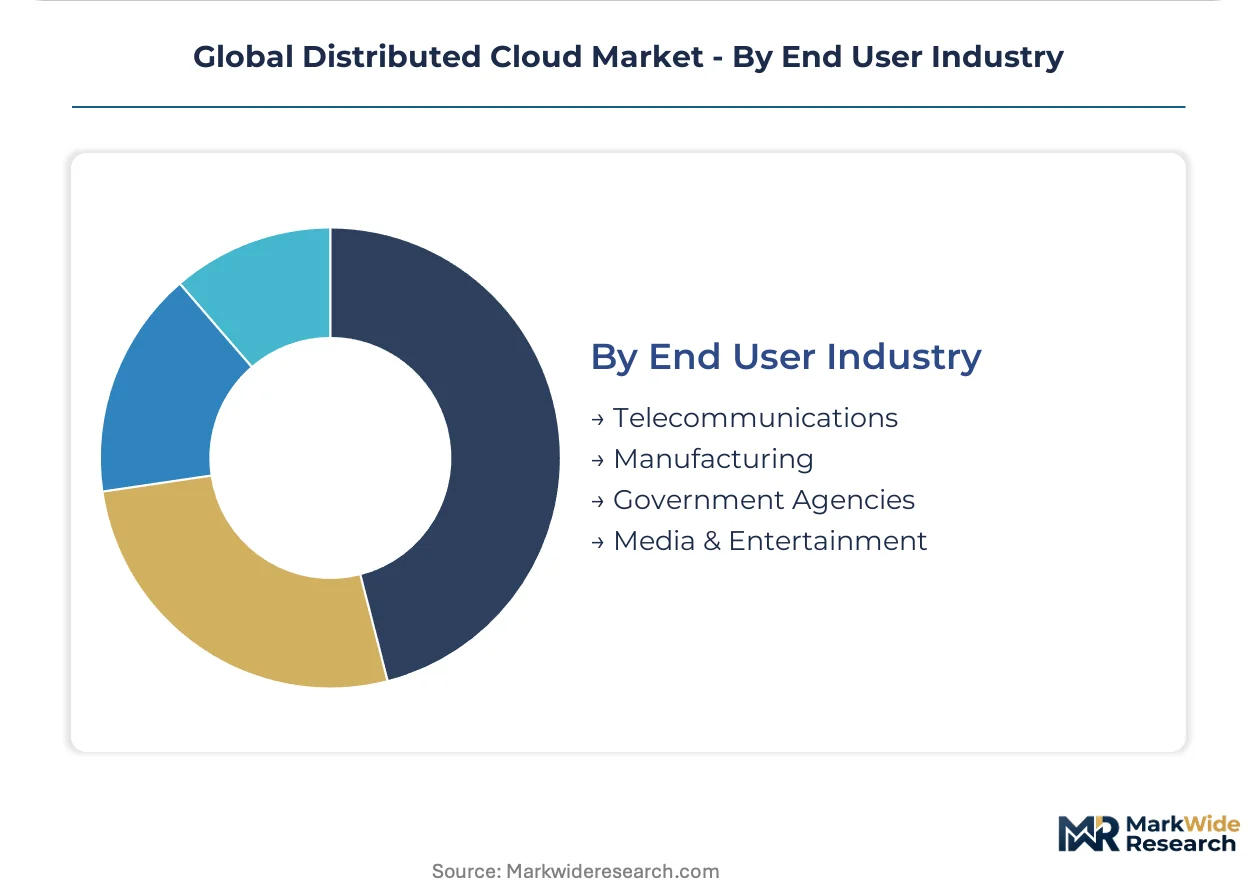
Customer type segmentation maps regulatory exposure against technical sophistication, with telecommunications and government agencies setting procurement specifications that cascade to manufacturing.
- Telecommunications:5G infrastructure operators deploying distributed nodes at base stations. Verizon, Deutsche Telekom, and SK Telecom drive standardization for sub-10 millisecond slicing.
- Manufacturing:Industrial automation clusters requiring OT-IT convergence. German Mittelstand firms and Japanese automotive suppliers specify edge-compliant infrastructure in supplier agreements.
- Government Agencies:Sovereign cloud mandates for classified and citizen data. EU member states, Saudi Arabia, and Australia procure country-specific substrate offerings.
- Media & Entertainment:Streaming and gaming platforms optimizing latency for user experience. Brazilian and South Korean broadcasters deploy regional nodes to reduce buffering.
Telecommunications commands the established base. Manufacturing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The DE-CIX internet exchange in Frankfurt anchors Germany's role as Europe's distributed cloud hub, processing traffic that feeds edge nodes across the continent. Submarine cables landing at Marseille and Bilbao interconnect Mediterranean and Atlantic routes. Cross-border fiber links between Singapore and Johor enable Southeast Asian latency arbitrage.
United States
Verizon and AT&T deploy Wavelength nodes at 5G base stations for sub-10 millisecond network slicing. FCC spectrum auctions for C-band and mmWave accelerate infrastructure densification. Connected vehicle corridors along I-75 in Michigan and I-95 in Virginia require roadside edge deployments for NHTSA V2X specifications.
Germany
Industrial automation clusters in Stuttgart and Munich demand edge-compliant infrastructure for sensor data processing without cloud round trips. GDPR Article 44 restrictions compel sovereign cloud instances within member state borders. Mittelstand automotive suppliers in Baden-Württemberg specify edge infrastructure in procurement contracts.
China
State-owned enterprises deploy private distributed nodes to satisfy SAMR data-localization thresholds. GB standards enforce domestic residency controls for AI training data. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou process industrial IoT workloads at substation-level compute facilities.
India
PLI scheme incentives for electronics production create demand for localized edge infrastructure in Tamil Nadu and Gujarat industrial zones. TRAI recommendations on data center localization guide carrier investments. Smart city initiatives in Bangalore and Hyderabad expand IoT connectivity deployments at municipal scale.
Japan
METI industrial digitalization subsidies accelerate outcome-based edge contracting across automotive assembly operations. Kansai region manufacturers negotiate uptime commitments tied to production line availability. Osaka and Nagoya industrial corridors deploy serverless edge computing for predictive maintenance analytics.
Global Distributed Cloud Market Competitive Landscape
Listed hyperscalers compete with private specialists across infrastructure scale and sovereign compliance capabilities. The vendor base concentrates around three tiers: hyperscale platforms with global fiber networks, telecommunications operators with last-mile real estate, and software-defined abstraction specialists. Strategic archetypes include edge-native challengers, carrier-captive integrators, and compliance-first regionalists. Competitive moves center on M&A for Kubernetes orchestration assets and strategic partnerships with semiconductor foundries.
Within the hyperscale tier, Amazon Web Services, Microsoft Corporation, and Google exemplify divergent architectural bets. AWS anchors carrier partnerships through Wavelength infrastructure co-location. Microsoft extends hybrid consistency via Azure Arc platform abstraction. Google differentiates through Anthos container portability. These three entities represent the dominant competitive anchors shaping procurement specifications across telecommunications and manufacturing verticals.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Alibaba Cloud |
| VMware |
| Teradata |
| F5 |
| Others |
Supply & Pricing Matrix
Capacity reservation agreements with Taiwan-based semiconductor foundries lock in GPU and FPGA supply for edge AI inference nodes while fixing hardware cost exposure across multi-year deployment cycles. German automotive manufacturers and US telecommunications carriers leverage these structures to secure sub-10 millisecond latency infrastructure without spot-market volatility.
Pricing Analysis
Volume-discount tiering structures separate hyperscale commitments above ten thousand nodes from mid-market batches and pilot deployments. Three-tier pricing stratifies across premium sovereign-cloud instances with full audit trails, standard edge nodes with regional residency controls, and economy tiers for latency-tolerant caching workloads. Cost compression in the economy tier intensifies as content delivery margins compress toward commodity levels. Manufacturing procurement teams in Japan exhibit lowest price sensitivity due to METI subsidy coverage, while Indian smart city initiatives negotiate aggressively on per-node economics.
Supply Chain Analysis
Strategic stockpile preferences dominate advanced node procurement as lead times for edge AI accelerators extend beyond standard planning horizons. Taiwan, South Korea, and the United States anchor semiconductor fabrication for distributed cloud hardware. Supply chains draw from specialized GPU foundries, high-bandwidth memory modules, and precision cooling systems. Single-source vulnerability concentrates in Taiwan-based advanced node production, with tariff exposure escalating on US-China technology trade restrictions. Distribution runs through telecommunications carrier partnerships and direct hyperscaler procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The distributed cloud market is recovering from infrastructure overbuild cyclicality as 5G network slicing deployments absorb excess edge node capacity. Capital expenditure normalization by Verizon, Deutsche Telekom, and SK Telecom signals demand stabilization.
For Market Incumbents: Fortify hybrid cloud consistency through Kubernetes orchestration layer investments that neutralize emerging container-native challengers. Deepen backward integration into semiconductor supply through strategic foundry partnerships, reducing exposure to Taiwan concentration risk. Prioritize ISO 27001 certification maintenance as competitive moats against regional compliance-first specialists. For New Entrants and Emerging Players: Anchor in Indian manufacturing corridors where PLI scheme subsidies reduce customer acquisition costs for localized edge infrastructure. Target substation-level compute for FERC Order 2222 grid optimization as the most penetrable utility vertical. Pursue outcome-based contracting models that bundle connectivity and compute guarantees, mirroring Japanese automotive procurement specifications. For Investors and Strategic Acquirers: Capital is best deployed toward sovereign-cloud regionalists with established GDPR Article 44 compliance architectures and existing government agency relationships. Long-term viability hinges on data residency enforcement durability across EU AI Act implementation phases. Watch for inflection when CNIL enforcement actions accelerate country-specific substrate procurement in France and Germany.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Partnership Expansion | AWS Wavelength and Azure Edge Zones co-location secures sub-10 millisecond 5G slicing real estate. |
| Kubernetes Orchestration Acquisition | Anthos and Azure Arc platform consolidation accelerates container portability across hybrid substrates. |
| Sovereign Cloud Substrate Launch | Country-specific instances satisfy GDPR Article 44 transfer restrictions for French banking regulators. |
| Serverless Edge Computing Deployment | Function-as-a-service models reduce infrastructure overhead for Japanese automotive predictive maintenance. |
| Semiconductor Foundry Partnership | Strategic alliances with Taiwan and South Korean fabricants secure GPU supply for AI inference nodes. |
Research Methodology
Operator-level perspectives from telecommunications infrastructure planners, cloud platform engineers, manufacturing IT directors, and regulatory compliance officers anchored the qualitative base. Primary interviews triangulated against hyperscaler capex disclosures, SEC filings, TRAI data center localization recommendations, and EU AI Act implementation guidance. Bottom-up node deployment estimates across Germany, the United States, China, India, and Japan reconciled with top-down market sizing from infrastructure investment tracking.
Sensitivity analysis tested forecast robustness across alternative 5G rollout trajectories and sovereign cloud enforcement intensities. Segmentation dimensions modeled include deployment topology, service layer, use case maturity, and end-user industry regulatory exposure. CAGRs derived from infrastructure investment run-rates, node provisioning timelines, and compliance-driven replacement cycles. Edge AI chip supply constraints and GDPR enforcement velocity served as key scenario variables.
Material uncertainties — semiconductor foundry capacity allocation, EU AI Act delegated act timing, and US-China technology trade restriction escalation — sit outside the modeled envelope. Forecasts reflect assumptions around sustained telecommunications carrier investment and stable data localization enforcement. Revision becomes warranted when edge AI chip lead time volatility crosses six-month thresholds or GDPR penalty precedents trigger sovereign cloud procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
GPU Virtualization Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Cloudifier Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud Management Market