
 Japan Cloud Computing Market | 2026-2036
Japan Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Cloud Computing Market Insights
The capital-intensity gap between hyperscale builders and domestic operators is bifurcating competitive dynamics in Japan's cloud sector. Amazon Web Services sustains unmatched global infrastructure scale, while NTT DATA leverages deep enterprise relationships and sovereign data center footprints across the archipelago. Fujitsu anchors public-sector and critical infrastructure verticals through its hybrid integration capabilities.
Cloud computing denotes networked delivery of on-demand computing resources—encompassing servers, storage, databases, networking, software, and analytics—over the internet, typically measured by service-level agreements guaranteeing uptime percentages and latency thresholds below 50 milliseconds for enterprise workloads. Its primary commercial purpose is to replace capital-heavy on-premises IT estates with elastic, usage-billed infrastructure. Public cloud deployments absorb the majority of new workload growth as Japanese enterprises prioritize scalability over asset ownership. SaaS within the service model dimension captures expanding margin pools by embedding vertical-specific compliance and workflow automation for finance and healthcare buyers.
METI's cloud security guidelines, Japan's Act on the Protection of Personal Information (APPI), and JIS standards for information security management collectively mandate data localization and audit transparency, compelling foreign hyperscalers to partner with domestic operators or build certified in-region facilities. PMDA's digital health governance further restricts where pharmaceutical and medical device data may reside, deepening hybrid cloud demand. Stakeholders must weigh sovereignty requirements against the cost and innovation velocity of global platforms when architecting multi-year IT roadmaps.
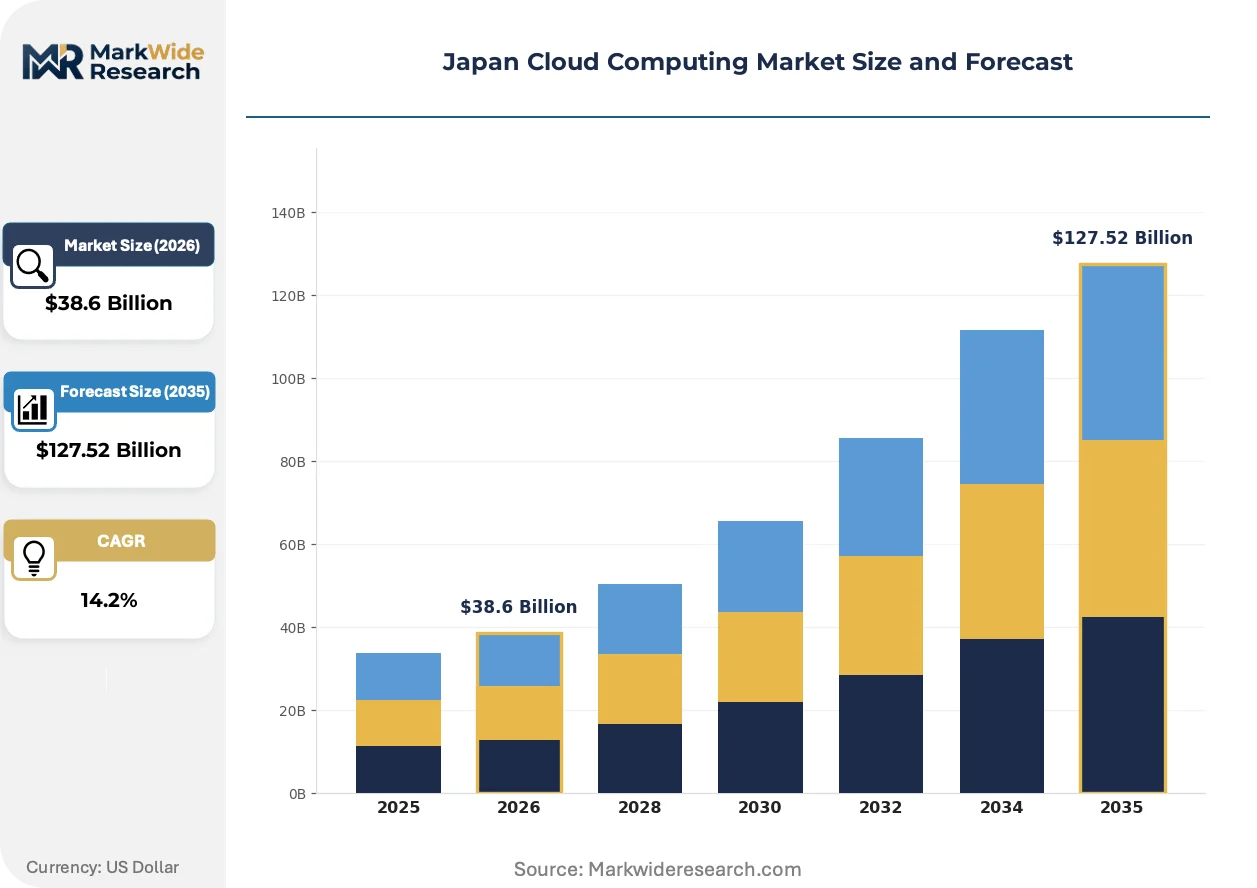
Market Dynamics
Japan's cloud sector is undergoing a structural pivot as METI's data sovereignty mandates and APPI revisions force domestic data residency requirements onto foreign hyperscalers, compelling hybrid architecture investments across automotive and financial verticals.
Growth Catalysts
- Connected Vehicle Platforms:Japanese automotive manufacturers are migrating manufacturing execution systems and telematics workloads to sovereign cloud environments to support software-defined vehicle roadmaps.
- APPI Compliance Mandates:The Act on the Protection of Personal Information revision imposes stricter cross-border transfer restrictions, accelerating procurement of JIS-certified domestic facilities.
- Financial Services Digitization:Tokyo's banking conglomerates are retiring legacy mainframe estates in favor of elastic infrastructure for real-time payments and open banking APIs.
Market Restraints
- Domestic Data Center Concentration:Certified facility supply clusters heavily in the Kanto corridor, creating geographic concentration risk for disaster resilience planning.
- Specialized Engineering Talent Scarcity:Multi-cloud architects with JIS Q 27001 audit experience command premium compensation, constraining mid-market provider expansion.
- Hybrid Integration Complexity:Technical debt in on-premises SAP and Oracle estates prolongs migration timelines and inflates professional services costs.
Strategic Opportunities
- Osaka-Kobe Manufacturing Belt:Underpenetrated industrial automation and IoT analytics demand in western Japan offers greenfield deployment potential for edge-computing nodes.
- PMDA Digital Health Pathway:Pharmaceutical and medical device data localization requirements are opening specialized healthcare cloud verticals with elevated compliance barriers.
- 5G Network Slicing Convergence:Integration between telco edge infrastructure and cloud orchestration layers enables ultra-low latency workloads for autonomous systems.
Industry Challenges
- Multi-Cloud Skill Fragmentation:Enterprise IT teams lack depth across AWS, Azure, and domestic platforms simultaneously, forcing reliance on systems integrator intermediaries.
- Certification Timeline Compression:JIS Q 27001 and ISMS certification cycles for new facilities routinely extend 18-24 months, delaying revenue recognition for capital-intensive builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Cloud Computing Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Model: IaaS, PaaS, SaaS, FaaS Industry Vertical: Healthcare, Finance, Retail, Education End User: SMEs, Large Enterprises, Government, Non-Profit |
| Companies Covered | NTT DATA, NEC Corporation, Amazon Web Services, KDDI Corporation, NTT Communications, Microsoft Azure, Fujitsu, Sakura Internet, Google Cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Cloud Computing Market Trends and Innovations
Container orchestration and serverless architectures are dissolving traditional infrastructure boundaries, while regulatory pressure on data residency is spawning new sovereign-cloud service tiers. These forces are compressing procurement cycles and reconfiguring vendor relationships across Japanese enterprise IT.
Edge computing infrastructure is fragmenting centralized cloud architectures by distributing compute to factory floors, retail branches, and cellular base stations. Automotive manufacturers and precision electronics assemblers are deploying Kubernetes clusters at production sites to process quality-control imagery locally. This topology is fragmenting the traditional hyperscale data center model into federated edge-core hierarchies with diverging hardware specifications.
METI's cloud security guidelines and APPI enforcement are mandating audit transparency and breach notification protocols that exceed baseline international standards. Foreign providers must now establish legally independent Japanese entities with local director accountability to maintain operating licenses. Financial services and healthcare buyers are prioritizing these certified sovereign offerings despite 15-30 percent cost premiums over global equivalents.
Consumption-based billing models are displacing reserved instance commitments as buyers demand granular cost visibility and workload portability. Mid-market enterprises in Osaka and Nagoya are negotiating month-to-month contracts with domestic operators rather than three-year hyperscale agreements. This behavioral shift is most pronounced in pharmaceutical and logistics verticals where demand volatility complicates capacity planning.
Japan Cloud Computing Market Segmentation
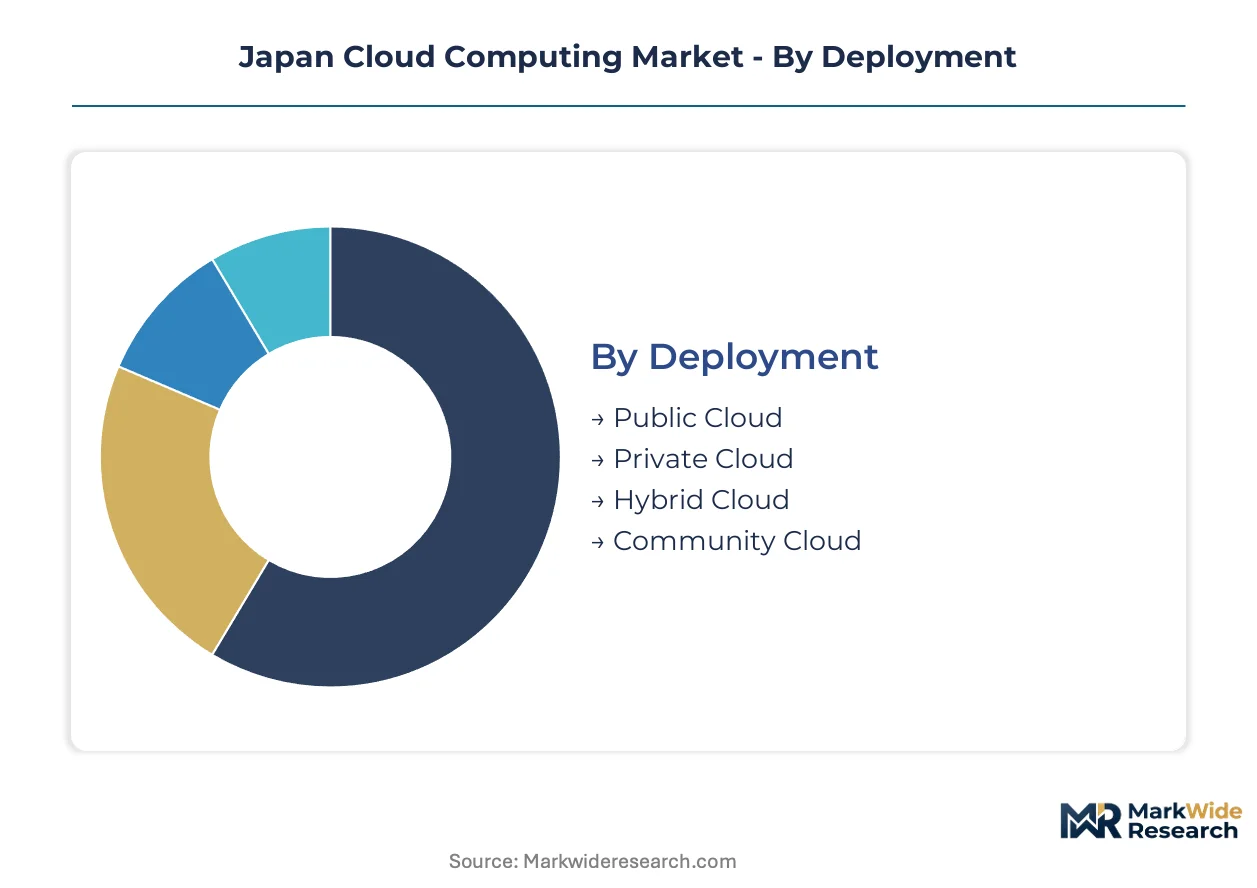
Japan's cloud computing market segments along four intersecting dimensions that determine procurement patterns and margin capture. Deployment architecture choices reflect METI's data sovereignty mandates, while service model selection tracks enterprise digital maturity and compliance burden.
Deployment:
Margin pools concentrate in hybrid configurations where domestic operators command sovereignty premiums and professional services attach rates.
- Public Cloud:Shared infrastructure delivered over the internet with metered resource consumption. Tokyo's financial services conglomerates are absorbing the majority of new public cloud workloads as they retire legacy mainframe estates for open banking APIs and real-time payment processing. Elastic scaling and consumption-based billing align with volatile transaction volumes.
- Hybrid Cloud:Federated architecture combining on-premises infrastructure with public cloud resources orchestrated through unified management planes. Japanese automotive manufacturers migrating connected vehicle platforms favor hybrid deployments to keep telematics data within sovereign boundaries while bursting compute to global regions. METI's cross-border transfer restrictions make hybrid the default architecture for regulated verticals.
- Private Cloud:Single-tenant infrastructure dedicated to one organization, deployed on-premises or at colocation facilities. Pharmaceutical manufacturers under PMDA digital health governance deploy private clouds for clinical trial data residency.
- Community Cloud:Shared infrastructure provisioned for exclusive use by a specific community of organizations with common compliance requirements. University research consortia and municipal healthcare alliances utilize community models for cost-pooled sovereignty.
Public Cloud holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Service Model:
Application complexity and internal IT capability determine where buyers land on the abstraction stack, with higher layers capturing expanding margin through embedded compliance automation.
- SaaS:Fully managed software applications delivered via subscription, with vendor responsibility for infrastructure, middleware, and application maintenance. Healthcare providers in Osaka and Nagoya are prioritizing SaaS for electronic medical records and claims processing to offload JIS Q 27001 audit burdens onto specialized vendors. Vertical-specific compliance modules command 15-30 percent pricing premiums over horizontal alternatives.
- IaaS:Fundamental compute, storage, and networking resources provisioned as virtualized services with customer-managed operating systems and applications. Large manufacturing enterprises in the Kanto corridor deploy IaaS for legacy ERP containerization, retaining control over patch cycles and security configurations that SAP and Oracle estates demand.
- PaaS:Development and deployment environments abstracting infrastructure management to accelerate application delivery. Fintech startups leverage PaaS for rapid API prototyping under sandbox regulatory frameworks.
- FaaS:Event-driven compute executing code in response to triggers without persistent server management. IoT analytics pipelines for precision electronics assemblers utilize FaaS for sporadic quality-control image processing.
SaaS commands the highest attach rates for professional services. PaaS is climbing fastest among developer-centric enterprises.
Industry Vertical:
Regulatory intensity and data sensitivity stratify cloud adoption timelines across sectors, with finance and healthcare setting the compliance pace that other verticals follow.
- Finance:Banking, insurance, and securities institutions subject to Financial Services Agency oversight and real-time payment system mandates. Tokyo's megabanks are driving the largest enterprise cloud migrations as they modernize core banking platforms for 24/7 settlement and open API ecosystems. APPI's cross-border restrictions and FSA operational resilience guidelines mandate domestic data residency with sub-50 millisecond latency to trading venues.
- Healthcare:Hospitals, clinics, pharmaceutical manufacturers, and medical device companies regulated under PMDA digital health pathways. Patient data localization requirements and clinical trial data sovereignty are opening specialized healthcare cloud verticals with elevated certification barriers that filter out generalist providers.
- Retail:Omnichannel merchants and e-commerce platforms processing consumer transactions and loyalty data. Osaka-based retail conglomerates are deploying edge computing nodes for in-store analytics while centralizing ERP in sovereign cloud facilities.
- Education:Universities, vocational institutes, and research organizations managing student records and collaborative research datasets. National university corporations balance cost constraints against METI research data governance requirements.
Finance holds the deepest committed spend. Healthcare is expanding most quickly as PMDA enforcement tightens.
End User:
Organizational scale determines procurement sophistication, with large enterprises negotiating sovereign service tiers and SMEs prioritizing standardized, rapidly deployable offerings.
- Large Enterprises:Organizations with complex IT estates, dedicated procurement functions, and multi-year transformation roadmaps. Japan's automotive and electronics conglomerates anchor demand for customized hybrid architectures with professional services integration. These buyers command dedicated account teams and influence vendor product roadmaps through co-development partnerships.
- SMEs:Mid-market enterprises with limited internal IT resources and compressed decision cycles. Manufacturing SMEs in the Nagoya industrial belt are negotiating month-to-month SaaS contracts rather than reserved instance commitments, prioritizing granular cost visibility over volume discounts. Domestic operators capture disproportionate SME share through localized support and JIS-certified default configurations.
- Government:National ministries, prefectural administrations, and municipal authorities subject to Government Cloud standards. METI and Digital Agency procurement guidelines favor domestic operators with security clearance and facility certification.
- Non-Profit:Social welfare organizations, international development agencies, and cultural institutions with constrained budgets and volunteer-dependent operations. Grant-funded cloud adoption proceeds through consortium purchasing to achieve scale economics.
Large Enterprises hold committed contract value. SMEs are gaining share fastest as self-service provisioning lowers adoption barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo commands 35-40 percent pricing premiums over Osaka for JIS-certified sovereign cloud capacity, concentrating procurement power in the Kanto corridor while western Japan offers arbitrage opportunities for cost-sensitive manufacturing workloads.
Kanto/Tokyo
Financial services digitization and connected vehicle R&D dominate demand, with megabanks retiring legacy mainframes for real-time payment infrastructure. METI's data sovereignty guidelines mandate domestic residency for cross-border data flows. The Tokyo-Yokohama technology corridor hosts the densest concentration of certified facilities, absorbing the majority of enterprise cloud commitments.
Kansai/Osaka
Precision manufacturing and pharmaceutical supply chains drive hybrid cloud adoption for industrial IoT analytics. PMDA's digital health pathway enforces strict localization for clinical trial data. The Osaka-Kobe manufacturing belt remains underpenetrated relative to Kanto, offering greenfield deployment potential for edge-computing nodes serving automotive subcontractors.
Chubu/Nagoya
Automotive OEMs and robotics manufacturers anchor demand for sovereign cloud platforms supporting software-defined vehicle roadmaps. APPI compliance mandates steer procurement toward domestic operators with JIS Q 27001 certification. The Nagoya industrial corridor concentrates Toyota and supplier ecosystem workloads requiring sub-50 millisecond latency to production systems.
Kyushu
Semiconductor fabrication and renewable energy projects create specialized high-performance computing demand. National university research consortia utilize community cloud models for cost-pooled sovereignty under METI research data governance. Fukuoka's startup ecosystem is attracting smaller domestic operators seeking lower facility costs than Tokyo.
Hokkaido
Agricultural technology and cold-chain logistics generate niche edge computing requirements for precision farming analytics. Cooler ambient temperatures reduce cooling costs for data center operators. Sapporo hosts emerging disaster-resilient backup facilities for Kanto-based financial institutions seeking geographic diversification.
Japan Cloud Computing Market Competitive Landscape
Concentration sits with hyperscale platforms and domestic telecommunications incumbents, creating a bifurcated structure where global infrastructure scale competes against sovereign data residency capabilities. Tier-one positions are held by entities with either unmatched global reach or deep enterprise relationships and certified facility footprints. Strategic moves center on hybrid partnership formations and JIS certification investments to satisfy METI compliance mandates.
Among Japan-based integrated IT services providers, NTT DATA, Fujitsu, and NEC Corporation exemplify the domestic archetype combining sovereign data center assets with systems integration expertise. These entities anchor the hybrid cloud segment where regulatory compliance and professional services attach rates command premium positioning. Foreign hyperscalers including Amazon Web Services, Microsoft Azure, and Google Cloud occupy the public cloud volume tier, partnering with domestic operators to satisfy data residency requirements while competing on innovation velocity and global platform breadth.
| Leading Market Players |
|---|
| NTT DATA |
| NEC Corporation |
| Amazon Web Services |
| KDDI Corporation |
| NTT Communications |
| Microsoft Azure |
| Fujitsu |
| Sakura Internet |
| Google Cloud |
| Others |
Pricing and Supply Chain Analysis
Consumption-based billing contracts lock in supply access through elastic capacity reservations while delivering granular price visibility to Japanese enterprises navigating volatile workload demands. These structures tether pricing predictability to sovereign data center availability, forcing buyers to weigh JIS-certified facility premiums against hyperscale cost efficiency.
Pricing Analysis
The customization-premium spread between configured-to-order sovereign cloud deployments and standardized hyperscale offerings runs 15-30 percent in Japan's market. Subscription-tiered SaaS models dominate, with vertical-specific compliance modules for finance and healthcare buyers commanding premiums over horizontal alternatives. Price differentiation rests on JIS Q 27001 certification grade and after-sales professional services bundling. Cost compression in public cloud tiers is intensifying as domestic operators expand certified capacity, though sovereign hybrid deployments show pricing resilience. SMEs in Osaka and Nagoya exhibit highest price sensitivity, negotiating month-to-month contracts, while Tokyo megabanks absorb premium sovereign tiers with minimal elasticity.
Supply Chain Analysis
Inbound logistics costs for server hardware and networking equipment face intermittent pressure from transpacific container availability constraints and Yokohama port congestion. Supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductors and specialized cloud infrastructure components. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and precision cooling systems. Single-source vulnerability in specialized ASIC fabrication creates structural risk for domestic operators scaling sovereign facilities. Distribution runs through systems integrator intermediaries who bundle hardware procurement with professional services, extending deployment timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Tokyo's financial services conglomerates as their procurement scale forces vendor roadmap concessions, fragmenting pricing leverage across smaller domestic operators.
For Market Incumbents: Consolidate hybrid cloud integration capabilities through deeper professional services attach rates and JIS Q 27001 certification investments. Defend against emerging domestic edge-computing specialists by anchoring automotive and pharmaceutical verticals with sovereign data residency guarantees. Capacity addition in the Osaka-Kobe corridor offers geographic diversification from Kanto concentration risk. For New Entrants and Emerging Players: Lead with specialized healthcare cloud verticals under PMDA digital health governance, where compliance barriers filter out generalist hyperscalers. The Nagoya industrial belt's automotive OEM ecosystem presents the most penetrable segment for sovereign edge-computing nodes. A direct-to-manufacturer go-to-market angle bypassing systems integrator intermediaries compresses sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap domestic operators with certified facility footprints and established enterprise relationships, positioned for sustained relevance across the analysis window. Acquisition targets should demonstrate JIS Q 27001 audit experience and hybrid integration capabilities. The signal to watch is METI enforcement intensity on cross-border data transfer restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Q 27001 Certification Investment | Unlocks sovereign cloud procurement eligibility under METI data residency mandates. |
| Hybrid Cloud Partnership Formation | Combines hyperscale innovation velocity with domestic operator compliance capabilities. |
| Edge Computing Node Deployment | Captures automotive and precision manufacturing demand in underpenetrated western Japan. |
| Vertical SaaS Compliance Module Development | Commands 15-30 percent pricing premiums from PMDA-regulated healthcare buyers. |
| Systems Integrator Channel Control | Secures professional services attach rates and prolongs customer retention cycles. |
Research Methodology
Initial hypotheses were tested against primary input from cloud procurement officers at financial services conglomerates, IT infrastructure directors at automotive OEMs, regulatory compliance leads at pharmaceutical manufacturers, and platform engineers at domestic operators, then refined through secondary validation. Secondary sources encompassed METI policy filings, JIS certification registries, hyperscaler capital expenditure disclosures, and hospital procurement databases. Bottom-up demand modeling triangulated against top-down market sizing across deployment architectures and service models.
Variance decomposition across the projection horizon isolated volume drivers from price-mix effects within each segmentation dimension. The analytical framework modeled deployment architecture, service model abstraction layer, industry vertical regulatory intensity, and organizational scale sophistication. CAGRs were derived from curve-fitting observed adoption patterns against infrastructure capacity buildout timelines, incorporating sovereign facility certification cycle durations and automotive connected vehicle platform migration schedules as industry-specific inputs.
Forecasts assume regulatory continuity in METI data sovereignty enforcement and APPI cross-border transfer regimes; material policy shifts would require re-modeling. Specific risk factors encompass JIS Q 27001 certification timeline compression, hyperscaler partnership restructuring, and sovereign facility disaster resilience events. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Global Cloud-Native Software Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Cloud Computing Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Virtual Machines Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
Telecom Cloud Market