
 Global Cloud Collaboration Market | 2026-2036
Global Cloud Collaboration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Collaboration Market Foresight
Multi-tenant serverless architectures with edge-node distribution is reshaping how collaboration platforms deliver sub-50ms latency for real-time editing and video synchronization. Microsoft Corporation leverages its Azure backbone to sustain deep integration between productivity suites and identity management layers. Cisco Systems Inc. anchors enterprise trust through hardware-certified encryption endpoints that differentiate its Webex stack in regulated industries.
Cloud collaboration encompasses software services that enable distributed teams to co-create, communicate, and coordinate through centralized platforms accessed via internet protocols, typically employing REST APIs, WebRTC for real-time media, and AES-256 encryption for data protection. The primary purpose is replacing on-premises productivity infrastructure with elastic, subscription-based alternatives that scale with workforce size. Hybrid cloud deployment captures the dominant margin pool as enterprises retain sensitive workloads on private nodes while bursting routine collaboration to public infrastructure. Video conferencing within solution types is displacing legacy telephony spend fastest, though team messaging generates stickier daily active usage patterns across IT and education verticals.
FDA 21 CFR Part 11 guidelines shape how pharmaceutical and healthcare adopters validate electronic records in cloud environments, while GDPR and the EU AI Act constrain cross-border data routing and automated decision-making features in European deployments. ISO 27001 certification has become a baseline procurement filter rather than a differentiator for platform selection. Stakeholders must weigh sovereign cloud requirements against interoperability costs as national data localization mandates proliferate.
Market Dynamics
Sovereign data residency mandates are fragmenting cloud infrastructure procurement as enterprises rebuild collaboration stacks around jurisdictional boundaries rather than cost optimization alone.
Growth Catalysts
- GDPR Article 44 cross-border transfer constraints:German financial services firms are procuring EU-sovereign cloud instances to maintain legal continuity for client data processing workflows.
- WebRTC edge-node distribution:Real-time video synchronization protocols now deploy within 50 milliseconds of end-users, eliminating latency barriers for distributed engineering teams.
- Healthcare digitization:FDA 21 CFR Part 11 validation requirements are pulling pharmaceutical quality assurance departments toward certified cloud document management platforms.
Market Restraints
- Encryption key escrow complexity:National data localization laws in France, Germany, and Saudi Arabia force redundant key management infrastructure, inflating operational overhead.
- Hyperscaler concentration risk:Three infrastructure providers control over 70 percent of underlying compute capacity, creating single-point-of-failure exposure for multi-tenant collaboration services.
- Legacy telephony sunk costs:Enterprises with depreciated PBX hardware face write-off penalties that delay full cloud migration timelines.
Strategic Opportunities
- India's PLI scheme for data centers:Domestic cloud infrastructure investment incentives are creating captive collaboration hosting capacity for multinational back-office operations.
- AI-assisted meeting transcription:Natural language processing convergence with real-time audio streams opens compliance documentation automation in regulated legal and medical verticals.
- Mobile-first channel expansion:Field service technicians in construction and energy sectors are adopting smartphone-native collaboration clients that bypass traditional desktop procurement cycles.
Industry Challenges
- Zero-trust architecture skill scarcity:Enterprise IT departments lack sufficient identity and access management engineers to configure micro-segmented collaboration environments.
- ISO 27001 certification timeline compression:Accelerated vendor onboarding demands are colliding with six-to-nine-month audit cycles, delaying contract executions.
- Interoperability protocol fragmentation:Proprietary real-time editing engines resist standardized API integration, forcing costly middleware development for multi-platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Collaboration Market |
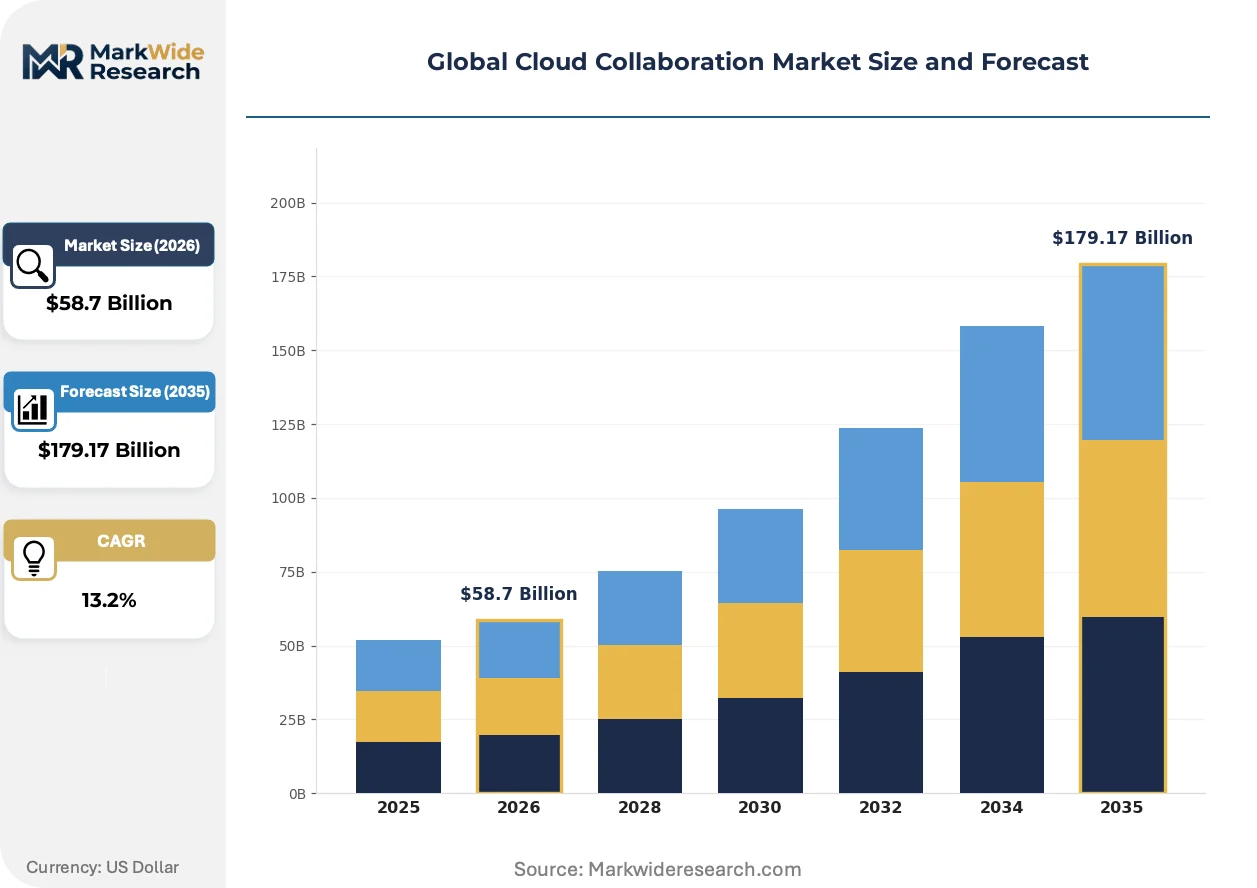
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $179.17 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Team Messaging, Document Sharing, Video Conferencing, Project Management, Workflow Automation Use Case: Remote Work, Client Collaboration, Internal Communication, Partner Management, Training & Development Industry Vertical: Information Technology, Education Services, Financial Services, Media & Entertainment, Legal Services |
| Companies Covered | Microsoft Corporation, Cisco Systems Inc., Google LLC, Oracle Corporation, IBM Corporation, Salesforce Inc., Zoom Video Communications Inc., Atlassian Corporation Plc, Box Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Collaboration Market Shifts & Advancements
Latency-sensitive synchronous collaboration is driving architectural bets toward edge-distributed compute, while regulatory fragmentation forces platform engineering teams to maintain parallel compliance codebases.
Serverless function deployment is hybridizing container orchestration with bare-metal edge nodes to sustain sub-50 millisecond response times for concurrent document editing. Manufacturing engineering teams in Germany and Japan are piloting these architectures for distributed CAD collaboration. The technology is hybridizing traditional three-tier application stacks into geographically sharded microservices that respect data residency perimeters.
The EU AI Act's risk classification framework is constraining automated decision-making features within European collaboration deployments. Platforms must now maintain human-in-the-loop audit trails for AI-generated meeting summaries and action item assignments. Healthcare and legal verticals in France and the Netherlands are prioritizing vendors with documented conformity assessment procedures.
Consumption-based licensing is displacing per-seat subscriptions as enterprise procurement teams demand usage-aligned cost structures. Mid-market technology firms in the United States and United Kingdom are negotiating burst-capacity clauses that accommodate seasonal workforce fluctuations. Finance departments prefer this model for cash flow predictability despite higher per-unit rates.
Global Cloud Collaboration Market Segmentation
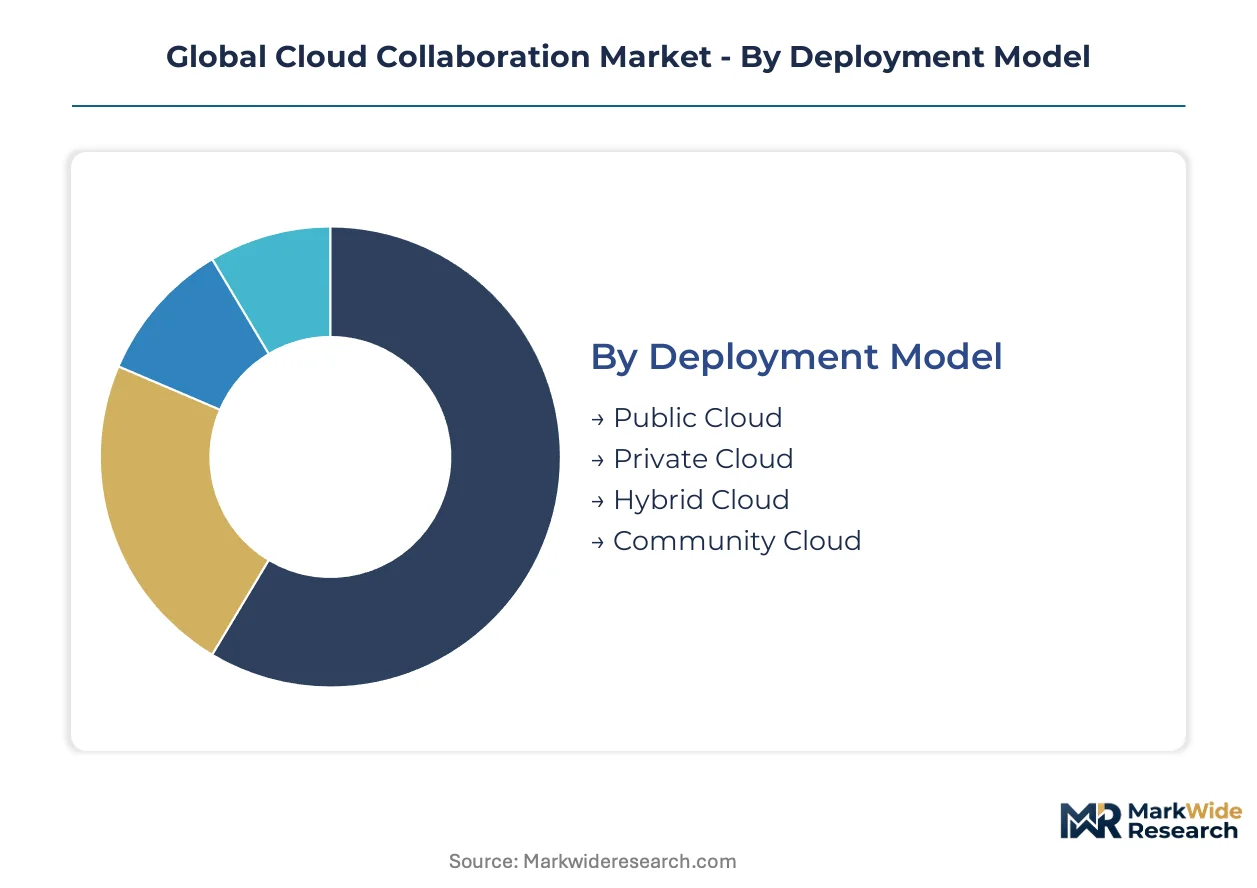
Cloud collaboration procurement patterns diverge sharply across deployment architectures and functional modules. Enterprise buyers segment their spending between latency-sensitive synchronous tools and asynchronous document workflows, with regulatory pressure reshaping infrastructure choices.
Deployment Model:
After-sales service intensity peaks with private cloud deployments requiring dedicated infrastructure support teams and compliance audit accompaniment.
- Public Cloud:Multi-tenant infrastructure delivers elastic compute scaling without capital expenditure. German financial services firms are migrating routine collaboration workloads to EU-sovereign public instances to satisfy GDPR Article 44 transfer constraints.
- Private Cloud:Single-tenant environments host dedicated hardware stacks with hardware-certified encryption endpoints. Pharmaceutical quality assurance departments in the United States deploy these for FDA 21 CFR Part 11 electronic record validation requirements.
- Hybrid Cloud:Bursting architectures retain sensitive data on private nodes while pushing routine traffic to public infrastructure. This model dominates margin pools as enterprises optimize cost against compliance.
- Community Cloud:Shared infrastructure serving specific industry cohorts with common regulatory requirements. Legal services consortia in the Netherlands utilize these for client confidentiality standardization.
Hybrid cloud holds the largest share; momentum sits with community cloud as sector-specific compliance frameworks proliferate.
Solution Type:
Cost tier differentiation separates premium real-time video stacks from commoditized messaging layers with freemium entry points.
- Video Conferencing:WebRTC-based synchronous media delivery with sub-50 millisecond edge-node distribution. Manufacturing engineering teams in Japan pilot these for distributed CAD collaboration requiring frame-precise synchronization.
- Document Sharing:Centralized repositories with version control and concurrent editing engines. Financial services firms expanding adoption drive procurement concentration here.
- Team Messaging:Persistent chat channels generating stickier daily active usage patterns across IT and education verticals than synchronous alternatives.
- Project Management:Task dependency mapping with resource allocation visualization. Construction sector field service technicians adopt smartphone-native clients.
- Workflow Automation:Trigger-based routing of approvals and notifications across distributed teams. Legal and medical verticals prioritize these for compliance documentation automation.
Document sharing captures the dominant revenue position; workflow automation is climbing the fastest as AI-assisted transcription converges with real-time audio streams.
Use Case:
Application maturity varies from established internal communication stacks to emerging partner ecosystem orchestration tools.
- Remote Work:Distributed workforce coordination with identity management layer integration. Microsoft Corporation leverages Azure backbone dominance here.
- Internal Communication:Departmental information dissemination with hierarchical access controls. Education services verticals standardize on these for campus-wide coordination.
- Client Collaboration:External stakeholder engagement with audit-trail documentation. Law firms in France require human-in-the-loop audit trails for AI-generated meeting summaries.
- Partner Management:Supply chain and channel coordination across organizational boundaries. Cisco Systems Inc. differentiates through hardware-certified endpoints in regulated industries.
- Training & Development:Structured learning delivery with progress tracking and certification workflows. Healthcare digitization pulls pharmaceutical departments toward certified platforms.
Internal communication holds the largest share; momentum sits with client collaboration as EU AI Act risk classification constrains automated decision-making features.
Industry Vertical:
Customer type concentration shapes feature roadmaps, with regulated industries demanding sovereign infrastructure and audit capabilities.
- Financial Services:Transaction documentation and client advisory workflows with encrypted archival. German enterprises prioritize data residency controls driving demand concentration.
- Information Technology:DevOps coordination and incident response with API-first integration requirements. This vertical generates the stickiest daily active usage patterns.
- Education Services:Campus collaboration and remote learning delivery with accessibility compliance. Mid-market technology firms in the United Kingdom negotiate burst-capacity clauses here.
- Legal Services:Privilege-protected communication and case file management with tamper-evident logging. France and Netherlands prioritize vendors with documented conformity assessment procedures.
- Media & Entertainment:Creative asset collaboration with high-resolution media streaming. Consumption-based licensing displaces per-seat subscriptions in this vertical.
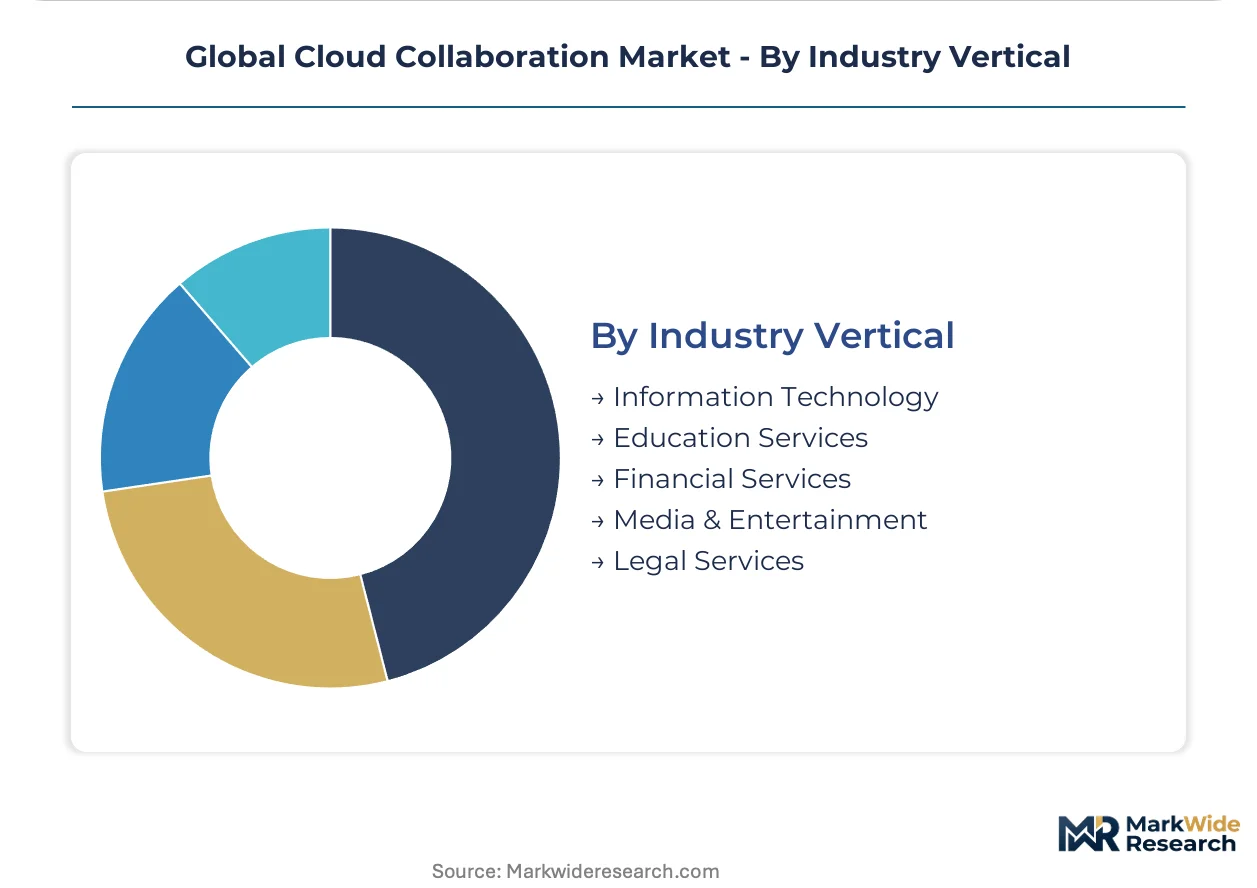
Information technology holds the largest share; financial services is gaining share fastest as EU sovereign cloud procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantial service exports in cloud collaboration software, while Germany and Japan represent net importers of productivity infrastructure as domestic enterprises accelerate sovereign cloud procurement. Trade balances diverge sharply between established SaaS exporters and jurisdictions prioritizing data localization mandates.
United States
Enterprise technology firms and mid-market software vendors drive domestic demand concentration. HIPAA compliance requirements shape healthcare sector procurement patterns for encrypted document management platforms. Silicon Valley clusters anchor development of WebRTC-based real-time media protocols for distributed engineering teams.
Germany
Financial services institutions and automotive manufacturers prioritize data residency controls for client advisory workflows. GDPR Article 44 cross-border transfer constraints accelerate EU-sovereign cloud instance procurement. Munich and Frankfurt banking clusters deploy hybrid architectures retaining sensitive records on private nodes.
Japan
Manufacturing engineering departments and pharmaceutical quality assurance teams pilot edge-distributed CAD collaboration systems. METI industrial digitization programs subsidize cloud infrastructure migration for precision machinery producers. Nagoya industrial corridor hosts sub-50 millisecond latency pilots for frame-precise synchronization requirements.
India
Multinational back-office operations and domestic IT services firms expand captive collaboration hosting capacity. PLI scheme incentives for data center infrastructure attract hyperscaler investment in Mumbai and Bengaluru clusters. Telangana and Karnataka technology parks negotiate burst-capacity licensing for seasonal workforce fluctuations.
United Kingdom
Legal services consortia and education technology providers standardize on compliance-documented platforms. Mid-market technology firms in London and Southeast England negotiate consumption-based contracts displacing per-seat subscriptions. Financial services verticals maintain audit-trail documentation for external stakeholder engagement workflows.
Global Cloud Collaboration Market Competitive Landscape
On the supply side, the industry is consolidating around hyperscaler-backed productivity suites while specialist vendors occupy defended niches in regulated verticals. Tiered competitive dynamics separate infrastructure-integrated platforms from point-solution providers. Three strategic archetypes dominate: hyperscaler-anchored ecosystems, hardware-certified security specialists, and vertical-focused workflow automation vendors. Dominant competitive moves include strategic partnerships with identity management providers and geographic expansion through EU-sovereign data center deployments.
Within the hyperscaler-anchored tier, Microsoft Corporation and Google LLC exemplify platform ecosystems leveraging cloud infrastructure dominance to integrate productivity suites with identity layers. Cisco Systems Inc. occupies a position among hardware-certified security specialists, anchoring enterprise trust through encryption endpoints in regulated industries. These three entities represent the structural fault lines between infrastructure-integrated and security-differentiated competitive strategies.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems Inc. |
| Google LLC |
| Oracle Corporation |
| IBM Corporation |
| Salesforce Inc. |
| Zoom Video Communications Inc. |
| Atlassian Corporation Plc |
| Box Inc. |
| Others |
Supply & Pricing Matrix
Mumbai and Bengaluru hyperscaler clusters anchor capacity expansion for multinational back-office operations, with PLI scheme subsidies compressing infrastructure costs and transmitting downstream pricing power to SaaS vendors negotiating burst-capacity contracts. EU-sovereign data center investments in Frankfurt and Amsterdam inflate operational overhead through redundant key management infrastructure, forcing tiered cost pass-through to enterprise procurement teams.
Pricing Analysis
Current-generation serverless edge architectures command premium positioning against prior-generation centralized three-tier stacks, while next-generation AI-native transcription bundles reshape value perception. Consumption-based licensing displaces per-seat subscriptions as the dominant model, with price differentiation driven by ISO 27001 certification tier and after-sales service intensity. Cost compression in mid-market segments intensifies as hyperscaler-backed productivity suites leverage infrastructure scale. Financial services buyers in Germany exhibit lowest price sensitivity due to regulatory compliance mandates, while education technology providers in the United Kingdom negotiate aggressively on per-unit rates.
Supply Chain Analysis
Extended payment terms from hyperscaler infrastructure providers and supply-chain finance facilities from cloud distribution partners stabilize working capital for platform engineering teams. Compute capacity concentrates in the United States, Ireland, and Singapore, with specialized encryption hardware sourcing from Taiwan and Japan. Raw material dependencies span silicon wafers, rare earth elements for magnetic storage, and lithium-ion battery systems for edge-node power resilience. Single-source vulnerability in WebRTC protocol licensing creates concentration exposure. Distribution runs through direct enterprise sales organizations and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise software investment cycles are recovering from prior-period compression as deferred digital transformation budgets release into sovereign cloud procurement. GDPR Article 44 enforcement and EU AI Act risk classification timelines provide cyclical justification for compliance-driven spending.
For Market Incumbents: Insulate margin position through hardware-certified encryption endpoint differentiation and EU-sovereign data center capacity expansion in Frankfurt and Amsterdam. Microsoft Corporation and Cisco Systems Inc. anchor defensive positioning against emerging vertical-focused workflow automation vendors by deepening Azure backbone integration and Webex stack certification investments. Threat from AI-native meeting transcription specialists demands accelerated natural language processing R&D allocation. For New Entrants and Emerging Players: Mid-market construction and energy sector field service technicians in India and Southeast Asia represent the most penetrable entry point, with smartphone-native collaboration clients bypassing traditional desktop procurement cycles. Legal services consortia in the Netherlands seeking client confidentiality standardization offer second white-space target. Go-to-market angle should emphasize consumption-based licensing with burst-capacity clauses for seasonal workforce fluctuations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical-focused workflow automation vendors with documented EU AI Act conformity assessment procedures. Long-term viability rests on sustained regulatory fragmentation creating persistent demand for parallel compliance codebases. Acquisition target archetype: specialist firms in healthcare and legal verticals with FDA 21 CFR Part 11 or tamper-evident logging certifications. Signal to watch is ISO 27001 certification timeline compression accelerating vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU-Sovereign Data Center Expansion | Frankfurt and Amsterdam deployments satisfy GDPR Article 44 transfer constraints for German financial services procurement. |
| AI-Assisted Meeting Transcription Integration | Natural language processing convergence opens compliance documentation automation in French legal and Dutch medical verticals. |
| Hardware-Certified Encryption Endpoint Development | Taiwan-sourced specialized components differentiate Webex stack in FDA-regulated pharmaceutical quality assurance departments. |
| Consumption-Based Licensing Transition | Usage-aligned cost structures accommodate seasonal workforce fluctuations in United Kingdom mid-market technology firms. |
| Edge-Node Distribution Architecture | Sub-50 millisecond latency pilots in Nagoya industrial corridor sustain frame-precise CAD synchronization for Japanese manufacturing engineering teams. |
Research Methodology
A standing panel of CTOs, IT procurement officers, platform engineers, and channel partners provided ongoing calibration across primary interview rounds, with secondary validation drawing from SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU regulatory filings. Bottom-up deployment model sizing triangulated against top-down enterprise spending surveys to converge on segment-level estimates.
Scenario-bracketing framed analytical approach across the projection horizon, modeling deployment architecture, organization size, vertical regulatory intensity, integration complexity, and regional data residency pattern as core segmentation dimensions. CAGRs derived from historical elasticity analysis applied to sovereign cloud procurement acceleration and healthcare digitization pull-through. Forecast inputs incorporated FDA 21 CFR Part 11 validation timeline assumptions and METI industrial digitization subsidy disbursement patterns.
Practitioners should monitor GDPR enforcement variance, EU AI Act risk classification implementation delays, and hyperscaler concentration risk events for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Cloud Management Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
Private Cloud Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Cloud Management for the Openstack Market
Cloud Computing
Containers As a Service (Caas) Market