
 Healthcare Cloud Infrastructure Market | 2026-2036
Healthcare Cloud Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Cloud Infrastructure Market Intelligence
Hospital procurement channels is reconfiguring around cloud-native vendor ecosystems as health systems abandon legacy data center leases. Microsoft Corporation leverages its Azure stack to anchor hybrid deployments across large integrated delivery networks. Amazon Web Services, Inc. competes through specialized healthcare compliance tooling and direct connectivity to clinical research pipelines. Google LLC differentiates with AI-optimized infrastructure layers that appeal to precision medicine workloads.
Healthcare cloud infrastructure comprises server, storage, and networking resources delivered through virtualized, on-demand platforms to medical organizations, typically supporting workloads requiring sub-50-millisecond latency for real-time diagnostic imaging and 99.99% uptime for continuous patient monitoring. Public cloud deployments lead volume among telehealth providers seeking elastic capacity, while private cloud retains margin concentration among hospitals governed by strict data residency protocols. Hybrid architectures represent the fastest-expanding segment as laboratories balance cost efficiency against genomic data sovereignty requirements.
FDA oversight of software-as-medical-device and HIPAA security rule enforcement shape infrastructure design requirements for US-based deployments, while GDPR data localization mandates constrain European cloud architectures and create compliance-driven demand for region-specific hosting. HITECH breach notification standards accelerate investment in encrypted storage and access logging across all deployment models. Stakeholders must monitor evolving FDA guidance on AI-enabled diagnostics to anticipate infrastructure specifications for training and inference workloads.
Market Dynamics
Hospital procurement channels are reconfiguring around cloud-native vendor ecosystems as health systems abandon legacy data center leases. Microsoft Corporation leverages its Azure stack to anchor hybrid deployments across large integrated delivery networks. Amazon Web Services, Inc. competes through specialized healthcare compliance tooling and direct connectivity to clinical research pipelines. Google LLC differentiates with AI-optimized infrastructure layers that appeal to precision medicine workloads.
Growth Catalysts
- HIPAA Security Rule Enforcement:Breach notification mandates under HITECH accelerate encrypted storage investment across all deployment models, compelling hospitals to modernize infrastructure.
- Genomic Data Sovereignty Requirements:Laboratories balancing cost efficiency against data residency protocols are expanding hybrid cloud architectures fastest among all segments.
- Sub-50-Millisecond Latency Demands:Real-time diagnostic imaging workloads require edge-proximate infrastructure, pulling compute resources closer to clinical settings.
Market Restraints
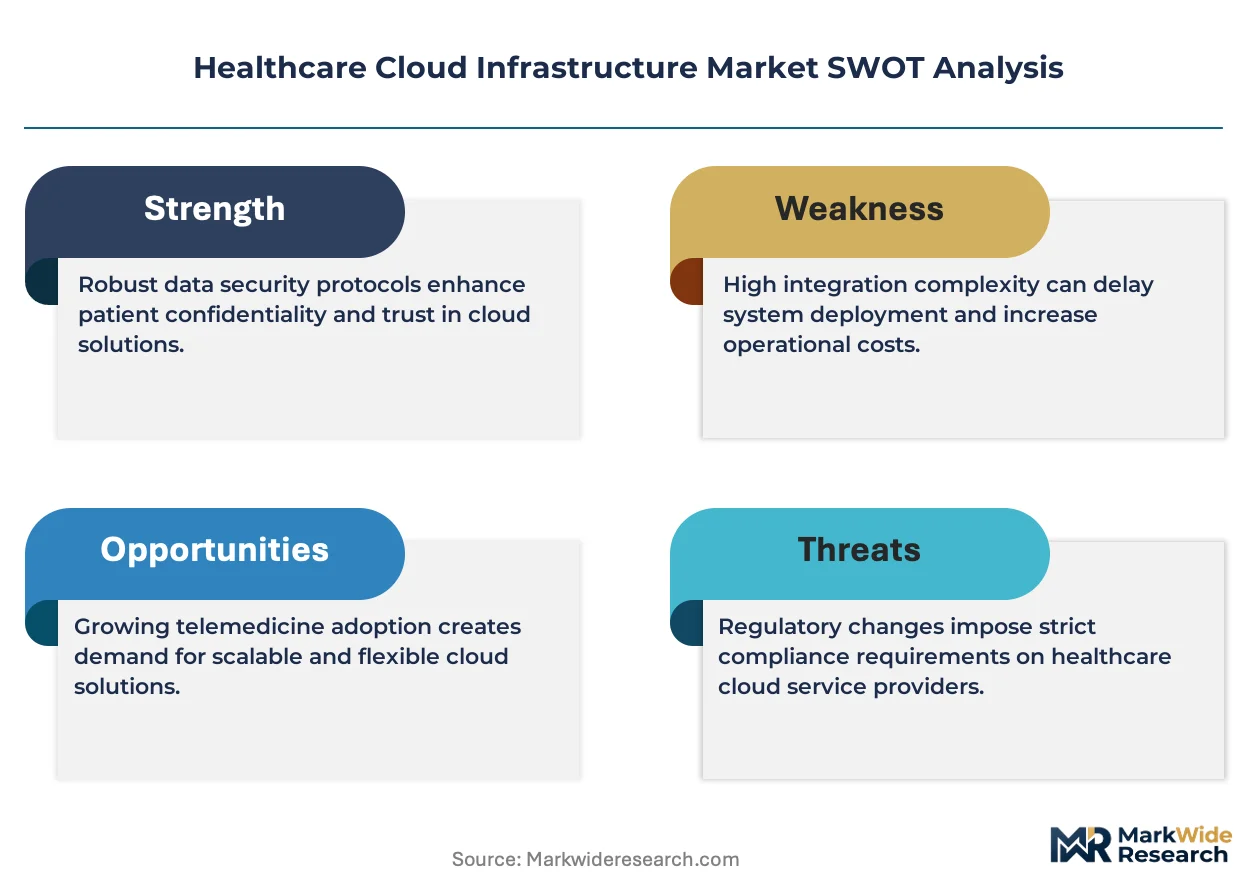
- GDPR Data Localization Mandates:European cloud architectures face compliance-driven constraints that fragment hosting strategies and increase operational complexity.
- Specialized Healthcare Compliance Tooling Costs:Custom security frameworks and audit-ready configurations inflate total cost of ownership versus generic cloud deployments.
- Strict Data Residency Protocols:Government hospitals and military medical facilities require on-premise or sovereign cloud options that limit vendor pool and scale economics.
Strategic Opportunities
- FDA AI-Enabled Diagnostics Guidance:Evolving oversight on software-as-medical-device creates infrastructure specification demand for training and inference workloads.
- Telehealth Elastic Capacity Models:Public cloud deployments among virtual care providers remain underpenetrated relative to inpatient settings, offering volume expansion potential.
- Precision Medicine Workload Convergence:Integration of AI-optimized infrastructure with clinical research pipelines opens new service tiers for academic medical centers.
Industry Challenges
- Hybrid Architecture Integration Complexity:Laboratories struggle to orchestrate workload portability between on-premise genomic data stores and public cloud burst capacity.
- Cloud-Native Talent Scarcity:Health systems lack sufficient DevOps and healthcare cybersecurity specialists to operate distributed infrastructure at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Cloud Infrastructure Market |
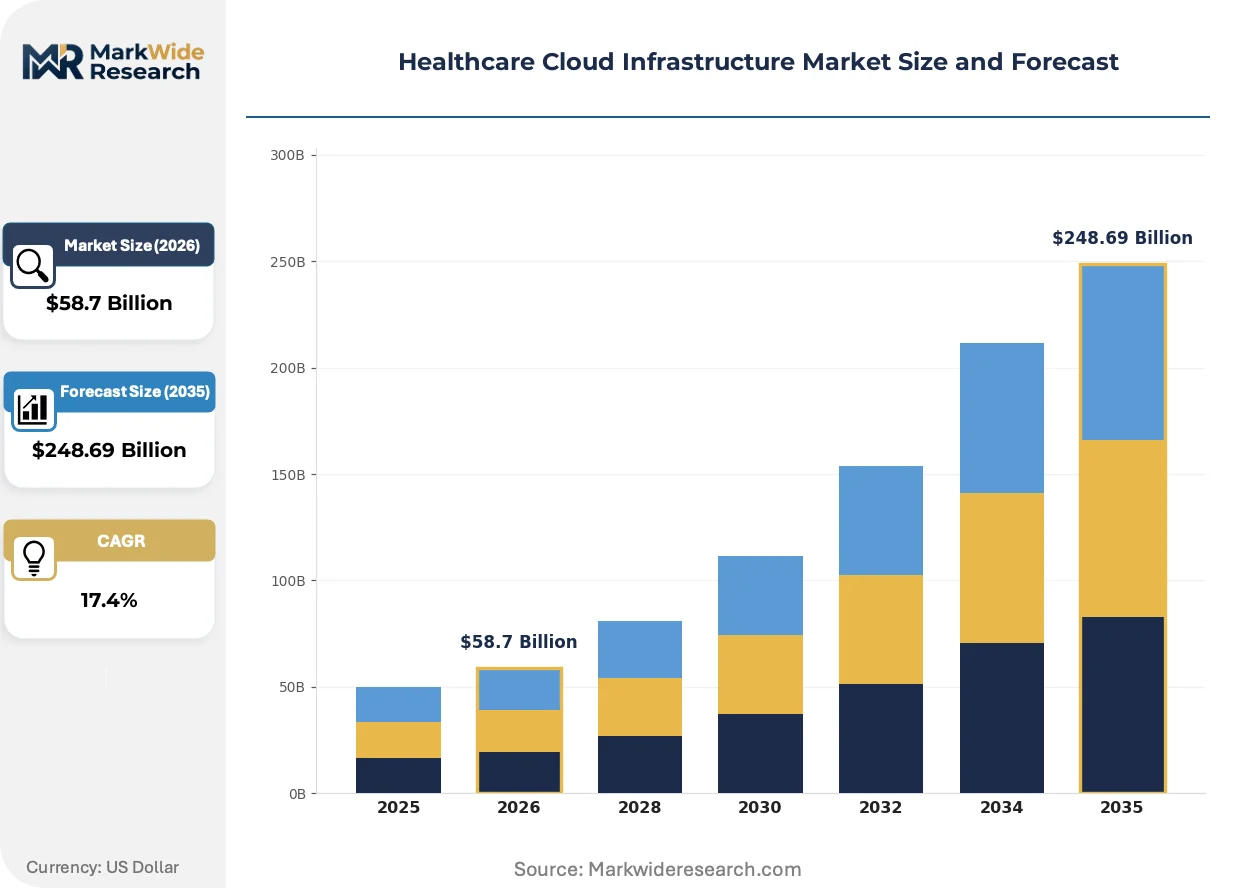
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $248.69 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Deployment Model: On-Premises, Cloud-Based, Managed Services, SaaS End User: Hospitals, Clinics, Laboratories, Telehealth Providers Compliance Standard: HIPAA, GDPR, HITECH, SOC 2 |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, IBM, Oracle Corporation, Dell Inc., Hewlett Packard Enterprise Development LP, Google LLC, Cisco Systems, Inc., Salesforce, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Cloud Infrastructure Market Strategic Shifts & Innovations
Healthcare cloud infrastructure is migrating from capital-intensive ownership models toward consumption-based platforms. This shift compresses procurement cycles and reconfigures vendor relationships around continuous service delivery rather than discrete hardware refresh programs.
Containerized workloads are migrating from virtual machine-based hosting to Kubernetes-orchestrated platforms. Telehealth providers adopt this architecture fastest to achieve elastic scaling during demand surges. The technology is migrating from infrastructure abstraction layers toward application-centric deployment models that reduce operational overhead.
EU AI Act risk classification rules are reshaping infrastructure design for clinical decision support systems. High-risk AI applications now require auditable training data pipelines and explainable inference logging. European academic medical centers are responding by segmenting workloads across compliant and non-compliant cloud regions.
Buying committees are consolidating vendor relationships around integrated platform stacks rather than best-of-breed point solutions. Integrated delivery networks now prioritize single-vendor accountability for uptime and security compliance. United States hospital systems demonstrate this pattern most clearly, with procurement teams reducing approved vendor lists by half.
Healthcare Cloud Infrastructure Market Segmentation
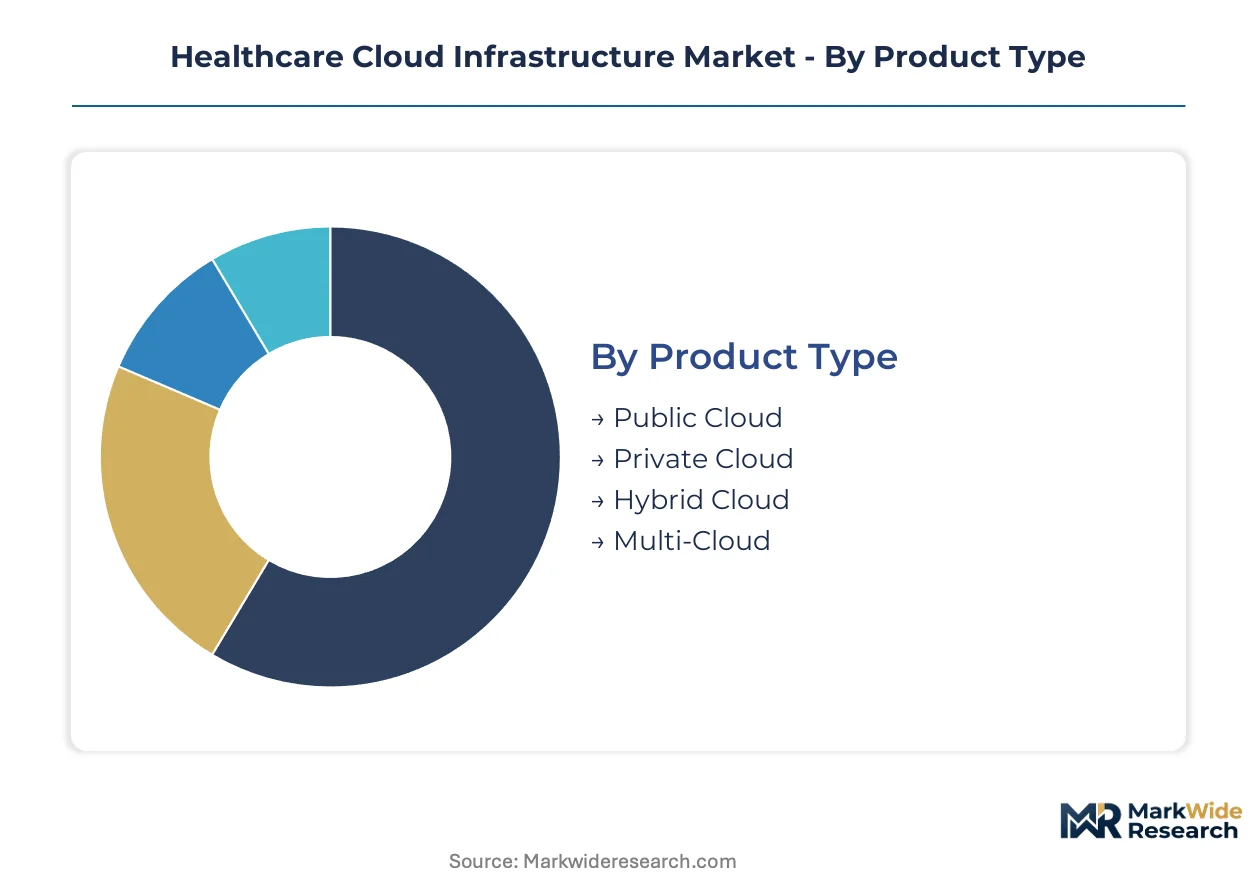
Healthcare cloud infrastructure procurement varies sharply across workload types, data sensitivity tiers, and regulatory exposure levels. Understanding these segment boundaries reveals where margin concentrates and which architectures health systems prioritize for specific clinical applications.
Product Type:
Deployment architectures span a spectrum from fully outsourced public capacity to sovereign-controlled private environments, with hybrid configurations dominating complex clinical workflows.
- Public Cloud:Shared infrastructure delivers elastic compute and storage through virtualized resource pools accessible over public internet. Telehealth providers in the United States concentrate demand here for burst capacity during seasonal patient volume spikes, driven by minimal capital requirements and sub-hour provisioning.
- Private Cloud:Dedicated single-tenant infrastructure deployed within hospital data centers or exclusive third-party facilities. Academic medical centers in the United States anchor demand for genomic data sovereignty, constrained by strict data residency protocols and HIPAA audit requirements.
- Hybrid Cloud:Orchestrated workload portability between on-premise and off-premise environments. Laboratories balancing cost efficiency against data sovereignty requirements are expanding this architecture fastest among all segments.
- Multi-Cloud:Distributed workloads across two or more independent cloud providers. Large integrated delivery networks deploy this model to mitigate vendor lock-in and satisfy disaster recovery mandates.
The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest.
Deployment Model:
Operational responsibility distribution shapes total cost of ownership and internal capability requirements for health systems.
- On-Premises:Hospital-owned hardware housed in dedicated facilities with full internal operational control. Military medical facilities and government hospitals in the United States mandate this model for classified or sensitive patient data, constrained by federal procurement regulations.
- Cloud-Based:Third-party hosted infrastructure with customer-managed applications and security configurations. Community health centers across the United States favor this approach for electronic health record hosting, balancing operational flexibility against limited IT staffing.
- Managed Services:Outsourced operational responsibility including patching, monitoring, and compliance reporting. Small rural hospitals in the United States concentrate demand here, driven by cybersecurity talent scarcity and 24/7 uptime requirements.
- SaaS:Fully vendor-operated clinical applications delivered through browser interfaces. Specialty clinics in the United States adopt this fastest for revenue cycle management and patient engagement tools.
Managed Services captures the steepest expansion trajectory as health systems confront cloud-native talent gaps.
End User:
Institutional scale and clinical mission dictate infrastructure performance specifications and compliance rigor.
- Hospitals:Large inpatient facilities requiring 99.99% uptime for continuous patient monitoring systems. Integrated delivery networks in the United States drive procurement volume, constrained by legacy electronic health record integration complexity.
- Clinics:Outpatient facilities with intermittent connectivity needs and lower data throughput requirements. Federally qualified health centers in the United States concentrate demand for cost-optimized SaaS diagnostic tools.
- Laboratories:High-performance computing environments processing genomic sequencing and molecular diagnostics. Precision medicine institutes in the United States anchor demand for GPU-optimized inference infrastructure.
- Telehealth Providers:Virtual care platforms requiring elastic scaling for video consultation workloads. Regional telehealth networks in the United States expand capacity here fastest, driven by rural access mandates and post-pandemic reimbursement permanence.
Hospitals retain dominant procurement volume, though Telehealth Providers are gaining share fastest.
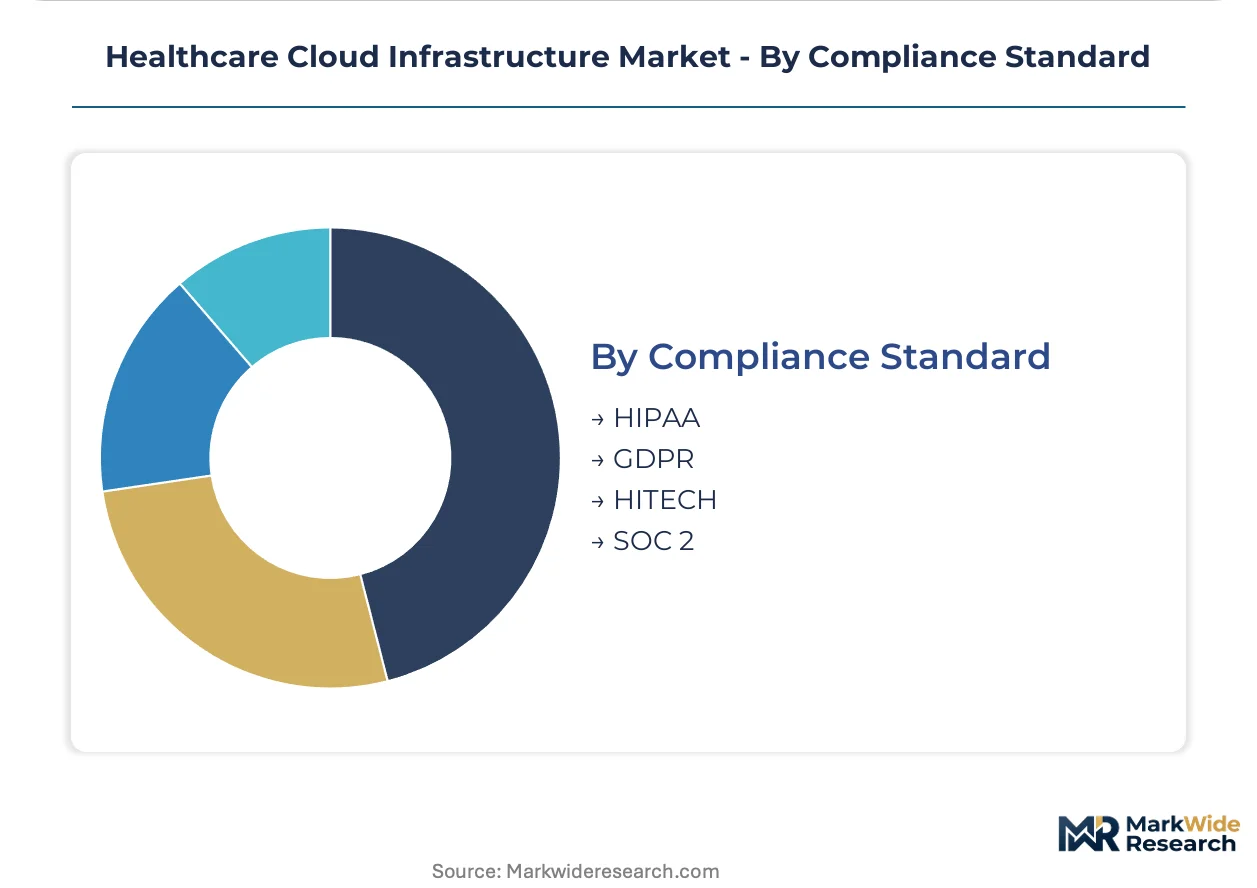
Compliance Standard:
Regulatory frameworks enforce specific technical controls that filter vendor eligibility and architecture design.
- HIPAA:US federal security and privacy rules governing protected health information. All domestic hospital procurement decisions incorporate HIPAA Business Associate Agreement requirements as a threshold qualification.
- GDPR:European Union data protection mandates with extraterritorial reach. Multinational health systems serving EU patients must segment infrastructure across compliant regions, fragmenting hosting strategies.
- HITECH:US breach notification and enforcement provisions strengthening HIPAA penalties. Breach notification mandates accelerate encrypted storage investment across all deployment models.
- SOC 2:AICPA trust services criteria for security, availability, and confidentiality. Health technology vendors seeking enterprise hospital contracts pursue this certification to demonstrate audit-ready controls.
HIPAA governs the largest addressable market, while GDPR compliance investments are climbing fastest among multinational deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ashburn-Loudoun County data center corridor in Virginia anchors North American cloud capacity for healthcare workloads, with direct fiber links to major hospital networks along the Eastern Seaboard.
United States
Integrated delivery networks in Massachusetts and California drive demand for hybrid cloud architectures balancing genomic data sovereignty against burst compute needs. HIPAA Security Rule enforcement and HITECH breach notification mandates compel encrypted storage investment across all deployment models. The Research Triangle Park cluster in North Carolina concentrates precision medicine infrastructure development for academic medical centers.
Germany
University hospitals in Bavaria and Baden-Württemberg anchor demand for GDPR-compliant private cloud environments with strict data localization protocols. The EU AI Act risk classification rules reshape infrastructure design for clinical decision support systems requiring auditable training pipelines. Frankfurt's financial district proximity creates specialized hosting zones for health insurance data processing workloads.
United Kingdom
NHS trusts in London and Greater Manchester expand managed services adoption to address cloud-native talent scarcity and 24/7 uptime requirements. SOC 2 certification serves as threshold qualification for vendors seeking enterprise hospital contracts. The Cambridge-Oxford-London life sciences triangle concentrates AI-optimized infrastructure for clinical research pipeline integration.
Japan
Metropolitan Tokyo hospitals require sub-50-millisecond latency infrastructure for real-time diagnostic imaging workloads. METI guidelines on medical data security influence procurement specifications for domestic cloud providers. The Osaka-Kobe biotech corridor develops sovereign cloud options for pharmaceutical supply chain data residency compliance.
India
Telehealth networks in Karnataka and Telangana leverage public cloud elasticity for rural access mandates and post-pandemic reimbursement permanence. The country's national pharmaceutical regulator shapes data localization requirements for clinical trial management systems. Hyderabad's Health City cluster anchors GPU-optimized inference infrastructure for molecular diagnostics laboratories.
Healthcare Cloud Infrastructure Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform stacks rather than best-of-breed point solutions. Hyperscale cloud providers anchor hybrid deployment architectures while specialized healthcare IT vendors retain positions in compliance tooling and clinical workflow integration. Three archetypes dominate: infrastructure-as-a-service hyperscalers, healthcare-exclusive cloud specialists, and legacy hardware vendors pivoting to managed services. Competitive moves center on M&A for compliance certification portfolios and strategic partnerships with electronic health record vendors.
Among hyperscale infrastructure providers, Microsoft Corporation exemplifies the platform-integrated archetype through Azure stack deployments, Amazon Web Services, Inc. occupies a position emphasizing specialized healthcare compliance tooling, and Google LLC represents the AI-optimized infrastructure tier targeting precision medicine workloads. These three entities anchor the vendor ecosystem as hospital procurement committees consolidate approved supplier lists and prioritize single-vendor accountability for uptime and security compliance.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| IBM |
| Oracle Corporation |
| Dell Inc. |
| Hewlett Packard Enterprise Development LP |
| Google LLC |
| Cisco Systems, Inc. |
| Salesforce, Inc. |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud capacity concentration in the Ashburn-Loudoun County corridor concentrates pricing power among three dominant infrastructure providers, pushing margin capture downstream toward specialized compliance tooling and managed service layers where hospital procurement committees negotiate.
Pricing Analysis
Volume-discount tiering structures separate enterprise integrated delivery networks from mid-tier community hospitals and small rural facilities. Pricing stratifies across premium managed services with full HIPAA audit support, standard self-managed configurations, and economy-tier burst capacity for telehealth workloads. Cost compression in the standard tier intensifies as hyperscalers compete for academic medical center contracts. Small rural hospitals exhibit highest price sensitivity due to constrained capital budgets, while large IDNs leverage scale for customized service-level agreements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for specialized healthcare compliance hardware and encrypted storage components. Taiwan, South Korea, and the United States anchor semiconductor fabrication for GPU-optimized inference infrastructure. Raw material dependencies include advanced memory modules, specialized networking silicon, and sovereign cloud certification modules. Single-source vulnerability concentrates in custom security framework development. Distribution runs through direct hyperscaler sales teams and specialized healthcare IT value-added resellers serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent infrastructure providers face substitution pressure from sovereign cloud alternatives as government hospitals and military medical facilities mandate data residency compliance, requiring defensive positioning around hybrid architecture integration capabilities.
For Market Incumbents: Build switching-cost moats through deep electronic health record vendor integrations and exclusive managed services partnerships. Anchor hybrid deployment expertise across large integrated delivery networks to resist displacement by specialized healthcare cloud specialists. Invest in HIPAA Business Associate Agreement automation tooling to accelerate procurement cycles. Prioritize certification portfolio expansion into EU AI Act compliance for European academic medical center expansion.
For New Entrants and Emerging Players: Geographic underpenetration in India telehealth networks and Japan metropolitan hospital edge computing creates immediate addressable white space. Target small rural hospitals in the United States with fully outsourced managed services addressing cloud-native talent scarcity. Pursue precision medicine institute partnerships for GPU-optimized inference workload specialization. Deploy through channel partnerships with regional health information exchanges to bypass direct hyperscaler competition.
For Investors and Strategic Acquirers: Capital is best deployed toward healthcare-exclusive cloud specialists with established HIPAA audit-ready configurations and existing electronic health record vendor integrations. Long-term viability hinges on regulatory compliance automation capabilities rather than raw infrastructure scale. Monitor FDA guidance publication velocity on AI-enabled diagnostics as the critical inflection signal for training and inference infrastructure demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA Business Associate Agreement Automation | Accelerates hospital procurement cycles by reducing legal review bottlenecks at integrated delivery networks. |
| EU AI Act Compliance Certification | Opens European academic medical center contracts requiring auditable training data pipeline infrastructure. |
| Electronic Health Record Platform Integration | Creates switching-cost moats through deep workflow embedding in Epic and Cerner environments. |
| Edge Computing Infrastructure Deployment | Addresses sub-50-millisecond latency requirements for real-time diagnostic imaging in metropolitan Tokyo hospitals. |
| Genomic Data Sovereignty Architecture | Captures hybrid cloud expansion among laboratories balancing cost efficiency against data residency protocols. |
Research Approach
Initial hypotheses were tested against primary input from hospital chief information officers, cloud procurement managers at integrated delivery networks, biomedical informatics directors, and healthcare cybersecurity specialists and refined through secondary validation against hospital procurement databases, GPO contracts, CMS Medicare reimbursement data, and hyperscaler healthcare vertical revenue disclosures. Bottom-up demand modeling across deployment architectures triangulated with top-down market sizing from infrastructure capacity expansion announcements.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation by deployment model, end-user institution scale, compliance standard tier, and workload type. CAGRs derived from elasticity-adjusted adoption curves and infrastructure capacity buildout timelines. Forecast inputs incorporated HIPAA enforcement intensity indices and precision medicine research funding trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign cloud providers or specialized healthcare compliance vendors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Web Scale IT Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Public Cloud Market
Cloud Computing
Cloud API and Management Platforms and Middleware Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
Data Virtualization Cloud Market
Cloud Computing
Cloud Services Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
South Korea Cloud Computing Market