
 Spain Cloud Computing Market | 2026-2036
Spain Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Cloud Computing Market Insights
Mid-sized enterprise demand in Spain is pivoting from fragmented departmental cloud pilots toward consolidated platform contracts governed by central IT procurement. Microsoft Corporation anchors its position through deep integration with existing enterprise productivity stacks across Spanish banking and retail verticals. Amazon Web Services, Inc competes by extending its Madrid and Barcelona infrastructure regions with sovereign cloud capabilities for regulated workloads. Google LLC differentiates through AI-optimized compute instances that attract Spanish research institutions and pharmaceutical developers.
Cloud computing encompasses the on-demand delivery of IT resources—compute power, storage, databases, networking, and software—over the internet through self-service provisioning and measured service models, typically employing virtualization, container orchestration, and software-defined networking to achieve elastic scalability. Its primary commercial purpose is to replace capital-intensive on-premises infrastructure with operational expenditure models that accelerate application deployment and disaster recovery. Public Cloud deployments capture the dominant revenue share as Spanish SMEs abandon server ownership entirely, while Hybrid Cloud architectures grow fastest among large enterprises managing legacy system interdependencies. SaaS applications within the Service Type dimension command the widest user base, though IaaS retains the deepest per-customer revenue concentration.
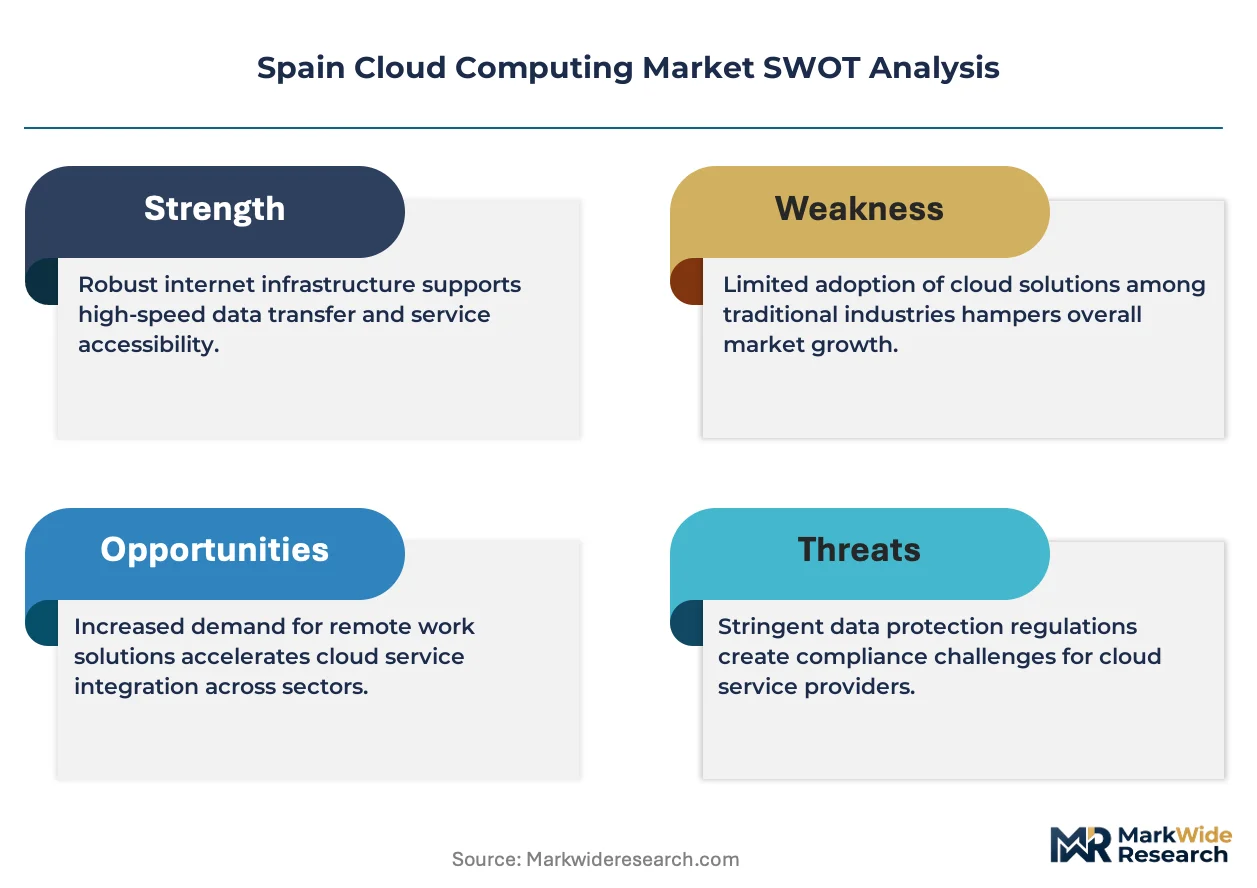
Spain's cloud market operates under the layered oversight of the Spanish Data Protection Agency enforcing GDPR mandates, the National Cryptologic Centre setting cybersecurity certification standards for public sector procurement, and EU-level CSRD disclosures pressuring sustainability transparency from cloud providers. These frameworks shape demand by requiring data residency guarantees, encryption standards, and carbon reporting that favor providers with certified Spanish facilities. Stakeholders must monitor how pending EU AI Act implementation will reclassify machine-learning workloads and redirect procurement toward compliant infrastructure tiers.
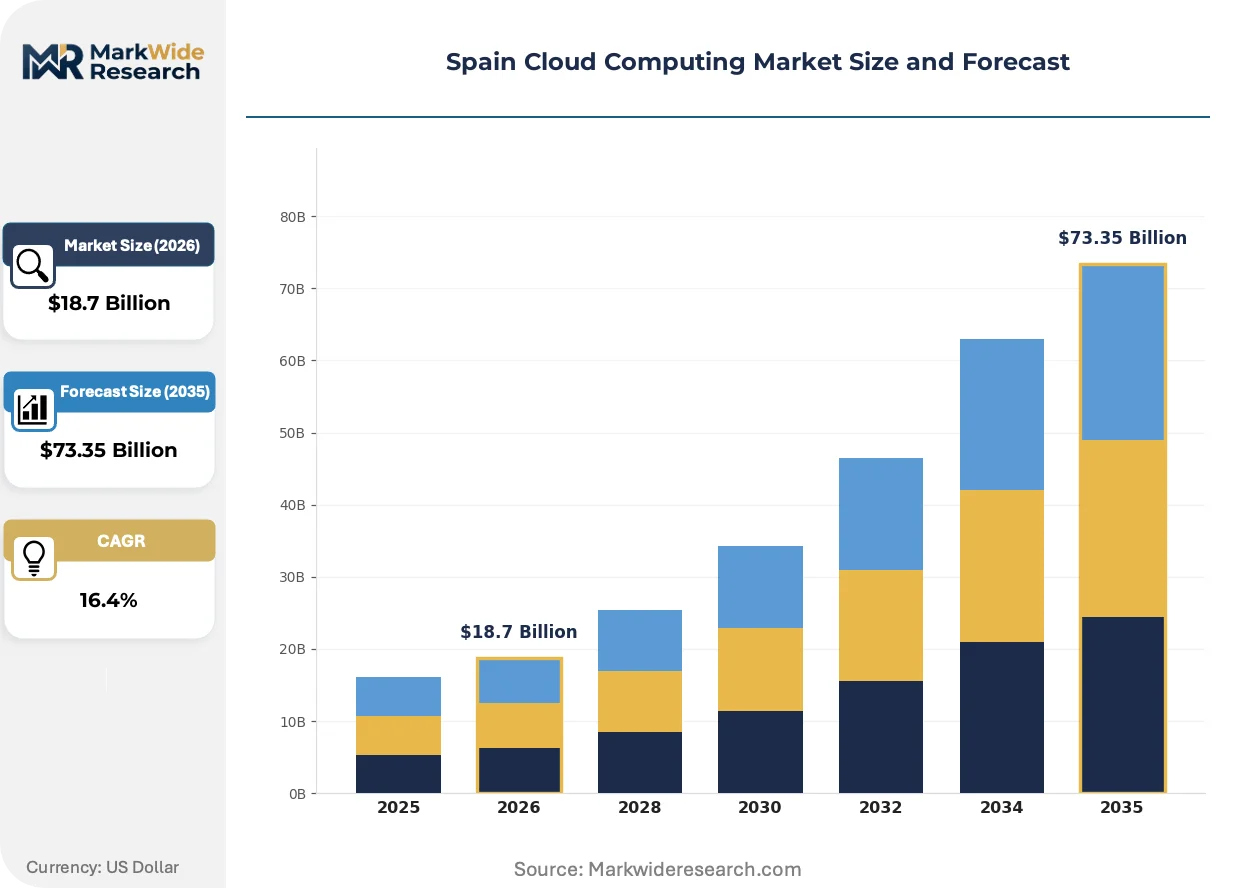
Market Dynamics
Spanish financial services firms are consolidating fragmented cloud pilots into centralized platform contracts governed by procurement teams, compressing vendor selection cycles and elevating data residency requirements as the decisive procurement criterion.
Growth Catalysts
- EU GDPR Data Residency Mandates:The Spanish Data Protection Agency enforces strict data localization rules that redirect enterprise workloads toward certified domestic facilities, creating captive demand for Madrid and Barcelona data center zones.
- Real-Time Transaction Processing:Spanish banking and retail verticals are migrating core payment systems to cloud-native architectures that enable sub-second settlement and 24/7 availability.
- Container Orchestration Adoption:Kubernetes-based deployment models are displacing monolithic legacy applications across mid-sized enterprises, accelerating workload portability and multi-cloud strategies.
Market Restraints
- Certification Timeline Friction:The National Cryptologic Centre's security clearance process for public sector cloud procurement extends vendor onboarding by 12-18 months, freezing competitive entry.
- Legacy System Interdependencies:Large Spanish enterprises maintain decades-old mainframe architectures that resist API-based integration, forcing expensive middleware layers.
- Specialized Cloud Architecture Skills:Domestic talent pools lack sufficient certified professionals in FinOps, SRE, and cloud security engineering, inflating implementation costs.
Strategic Opportunities
- AI-Optimized Compute Demand:Spanish pharmaceutical developers and research institutions are procuring GPU-intensive instances for molecular simulation and generative model training, opening premium service tiers.
- Andalusia and Valencia Expansion:Secondary metropolitan zones outside Madrid and Barcelona present underpenetrated markets where localized cloud zones could capture public sector and manufacturing demand.
- EU AI Act Compliance Infrastructure:Pending classification of machine-learning workloads will redirect procurement toward compliant infrastructure tiers, favoring providers with pre-certified risk management frameworks.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Spanish enterprises struggle to maintain consistent security postures and cost governance across heterogeneous AWS, Azure, and Google Cloud environments.
- Carbon Reporting Integration:CSRD-mandated sustainability disclosures require granular carbon accounting that most cloud consumption models currently cannot provide at workload level.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Cloud Computing Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DRaaS Customer Type: SMEs, Large Enterprises, Startups, Government Application: Data Storage, Web Hosting, Development, Backup |
| Companies Covered | Amazon Web Services, Inc, Microsoft Corporation, Google LLC, Oracle Corporation, IBM Corporation, Arsys Internet SLU, OVH Groupe SA, A3Sec Group, SAP SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Cloud Computing Market Trends and Innovations
Spanish cloud consumption patterns are pivoting from infrastructure migration toward workload optimization, with FinOps discipline and sovereign cloud capabilities emerging as the primary axes of vendor differentiation.
Confidential computing architectures using hardware-based trusted execution environments are integrating encryption-in-use capabilities that satisfy Spanish financial regulators' most stringent data protection requirements. Major domestic banks are piloting these technologies for cross-border payment validation and fraud detection pipelines. The technology is integrating compliance automation directly into infrastructure provisioning workflows, collapsing the traditional security review cycle.
The EU AI Act's risk-based classification system is redefining procurement specifications for machine-learning infrastructure across Spanish healthcare and public administration buyers. High-risk AI deployments now require documented training data lineage and model interpretability guarantees that reshape vendor qualification criteria. Pharmaceutical developers in Barcelona are restructuring cloud contracts to isolate training environments from inference workloads, creating demand for segmented infrastructure tiers with differentiated certification levels.
Centralized IT procurement teams at Spanish enterprises are displacing departmental shadow IT through enforced cloud cost allocation and reserved instance standardization. Manufacturing and logistics buyers in the Basque Country and Catalonia are consolidating fragmented SaaS subscriptions into platform negotiations with single vendors. This concentration is compressing vendor margins while elevating professional services and managed support to primary profit centers.
Spain Cloud Computing Market Segmentation
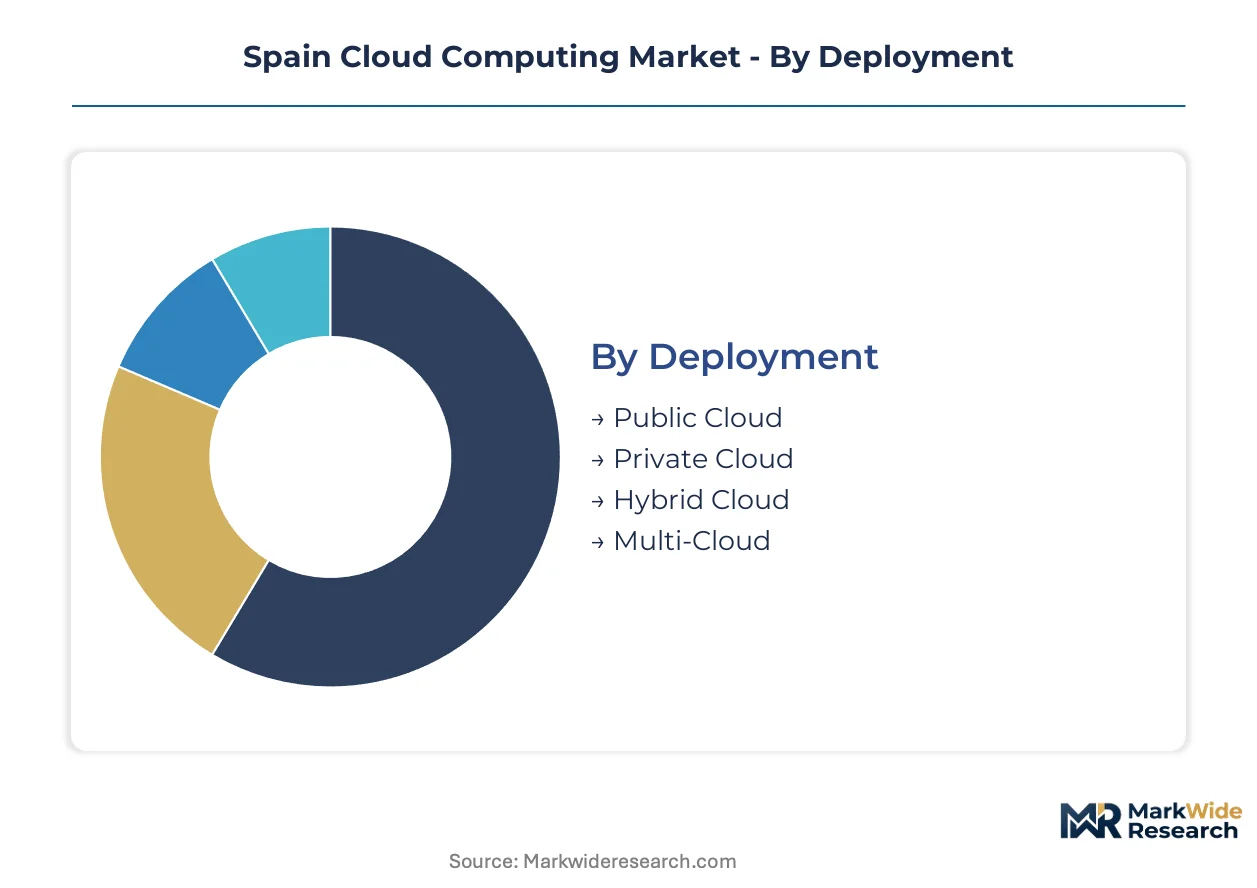
Cloud segmentation in Spain reflects distinct procurement maturity across customer archetypes, with regulatory pressure and legacy system constraints fragmenting deployment strategies. Understanding these divisions reveals where vendor differentiation commands premium pricing versus where standardization dominates.
Deployment:
Architectural choices in Spanish cloud infrastructure cluster around data sovereignty requirements and existing capital investments.
- Public Cloud:Delivers compute, storage, and networking resources through shared infrastructure with metered consumption. Spanish SMEs in retail and professional services are abandoning server ownership entirely, driven by operational expenditure preferences and GDPR-compliant Madrid zones from hyperscalers.
- Hybrid Cloud:Orchestrates workloads across on-premises infrastructure and public cloud resources through unified management planes. Large Spanish banks and manufacturers in Catalonia maintain this architecture to preserve mainframe integrations while bursting transactional peaks to cloud.
- Private Cloud:Dedicated infrastructure deployed within enterprise data centers or single-tenant hosted facilities. Defense contractors and critical infrastructure operators in Spain select this model for National Cryptologic Centre certification requirements.
- Multi-Cloud:Distributes applications across two or more public cloud providers to avoid vendor lock-in. Mid-sized enterprises with containerized workloads adopt this strategy, though complexity inflates FinOps staffing costs.
Mature deployment sits with Public Cloud. Newer deployment is concentrated in Multi-Cloud.
Service Type:
Service abstraction layers in Spain stratify by customer technical sophistication and speed-to-market imperatives.
- SaaS:Delivers fully managed applications through web browsers with zero infrastructure management. Spanish government agencies and healthcare providers procure SaaS for rapid digitization, constrained by AEPD data residency audits and integration with legacy record systems.
- IaaS:Provides virtualized compute, storage, and networking resources with customer-managed operating systems. Madrid-based fintechs and Barcelona pharmaceutical developers favor IaaS for GPU-intensive molecular simulation and real-time fraud detection pipelines.
- PaaS:Abstracts infrastructure management to enable application deployment through managed runtime environments. Software startups in Valencia and Bilbao leverage PaaS for accelerated product iteration without DevOps specialization.
- DRaaS:Replicates production workloads to secondary sites for disaster recovery orchestration. Financial services firms in the Basque Country contract DRaaS to satisfy Bank of Spain operational resilience mandates.
Volume concentrates in SaaS. Value capture concentrates in IaaS.
Customer Type:
Procurement authority and compliance exposure create four distinct buying behaviors in Spanish cloud markets.
- Large Enterprises:Organizations with centralized IT governance and multi-year vendor relationships. These buyers negotiate platform-wide contracts with professional services attachments, consolidating fragmented departmental pilots under procurement team oversight.
- SMEs:Mid-sized firms with limited technical staff and high price sensitivity. Spanish manufacturing SMEs in Andalusia and Galicia favor pay-as-you-grow models, migrating from on-premises ERP to SaaS financial suites.
- Government:Public sector entities subject to National Cryptologic Centre security clearance and EU procurement directives. Extended vendor onboarding timelines of 12-18 months freeze competitive entry for uncertified providers.
- Startups:Venture-backed technology firms prioritizing speed over long-term cost optimization. Barcelona and Madrid startup clusters consume credits-based programs, though churn rises when promotional pricing expires.
Contract complexity sits with Government. Expansion velocity sits with Startups.
Application:
Workload purpose determines infrastructure specifications and residency requirements across Spanish deployments.
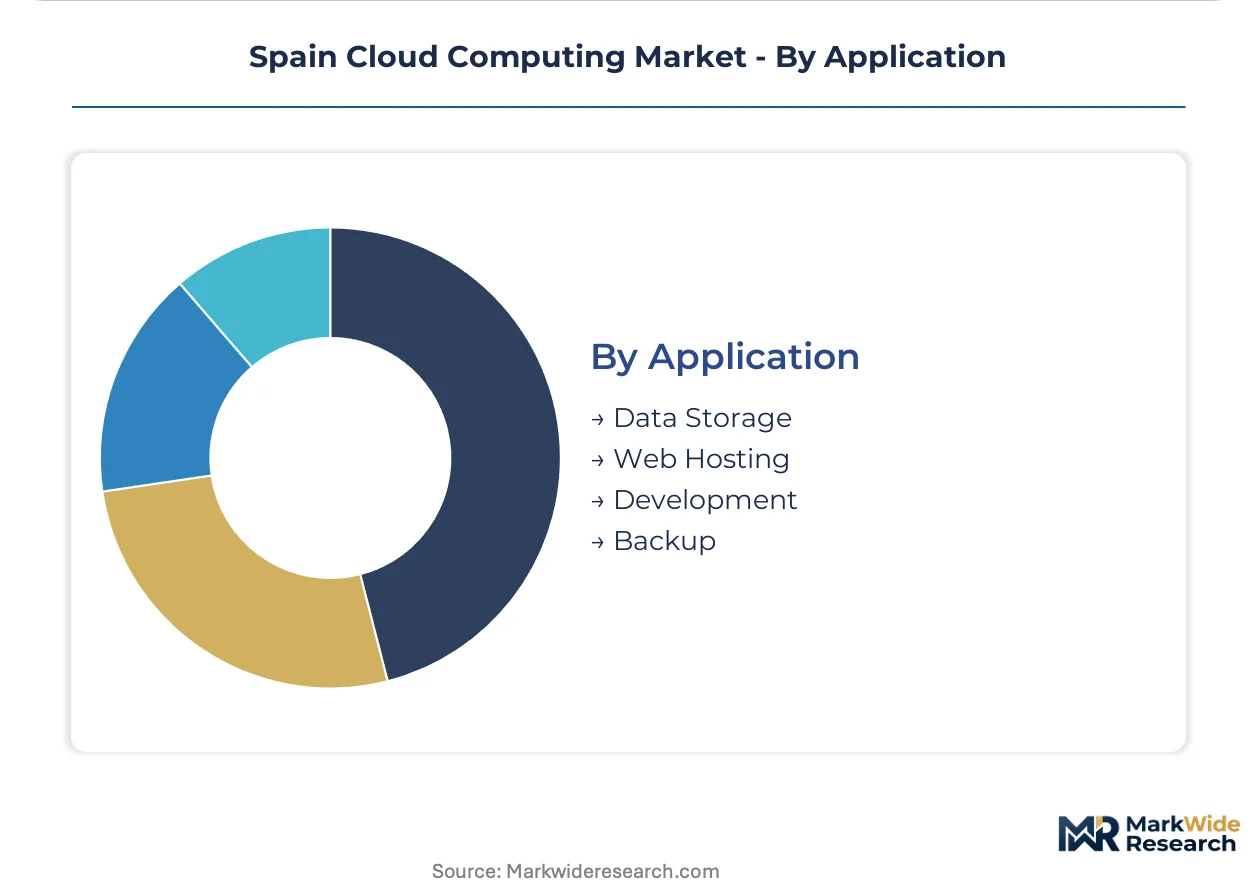
- Data Storage:Object, block, and file storage services for structured and unstructured datasets. Spanish media companies and research institutions in Barcelona store petabyte-scale archives, with tiering policies driven by CSRD-mandated carbon accounting.
- Development:Environments for application coding, testing, and continuous integration. Software vendors in Madrid and Valencia provision ephemeral compute for agile pipelines, integrating compliance automation into infrastructure workflows.
- Web Hosting:Scalable serving of websites and web applications with global content delivery. E-commerce retailers in Catalonia and the Basque Country deploy auto-scaling architectures for seasonal demand spikes.
- Backup:Scheduled replication of production data to geographically separated facilities. Healthcare providers across Spain's autonomous communities contract backup services to satisfy AEPD availability requirements for patient records.
Regulatory scrutiny sits with Backup. Margin expansion sits with Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in the Madrid metropolitan zone anchors Spain's cloud infrastructure buildout, with hyperscaler data centers clustering around the capital's power grid and fiber interconnection nodes.
Madrid
Financial services concentration drives hyperscaler investment in dedicated cloud zones. The Spanish Data Protection Agency enforces GDPR data residency audits for banking workloads. Madrid's Pozuelo de Alarcón corridor hosts certified facilities processing real-time payment settlements for BBVA and Santander.
Catalonia
Pharmaceutical developers and research institutions demand GPU-intensive compute for molecular simulation. Barcelona Supercomputing Center partnerships accelerate AI-optimized infrastructure procurement. The 22@ innovation district clusters cloud-native startups consuming container orchestration services.
Basque Country
Advanced manufacturing and automotive suppliers adopt hybrid architectures for legacy ERP integration. Basque cybersecurity agencies collaborate with the National Cryptologic Centre on industrial control system certifications. Bilbao's Zorrozaurre technology park hosts edge computing nodes for predictive maintenance workloads.
Andalusia
Public sector digitization and tourism technology platforms expand cloud consumption beyond traditional hubs. Regional government procurement follows EU procurement directives with extended vendor qualification timelines. Málaga's Technology Park attracts SaaS providers serving southern European markets.
Valencia
Software development clusters and maritime logistics operators drive platform-as-a-service adoption. The Valencian Community's startup ecosystem consumes credits-based cloud programs for rapid product iteration. The Port of Valencia deploys containerized analytics for supply chain optimization.
Spain Cloud Computing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sovereign cloud specialization and AI-optimized compute instances. The vendor base stratifies across three tiers: hyperscalers with Madrid and Barcelona infrastructure regions, European providers with GDPR-certified domestic facilities, and domestic specialists in public sector security clearance. Competitive moves concentrate on sovereign cloud capability expansion and FinOps professional services attachment.
Among US-based hyperscalers, Amazon Web Services, Inc and Microsoft Corporation exemplify the infrastructure-scale archetype with deep enterprise productivity integration. Google LLC occupies a differentiated position targeting research and pharmaceutical AI workloads. European providers including OVH Groupe SA represent the data sovereignty tier with EU-based facility networks. Spanish specialists such as Arsys Internet SLU and A3Sec Group anchor the domestic compliance segment, serving National Cryptologic Centre certification requirements for public sector procurement.
| Leading Market Players |
|---|
| Amazon Web Services, Inc |
| Microsoft Corporation |
| Google LLC |
| Oracle Corporation |
| IBM Corporation |
| Arsys Internet SLU |
| OVH Groupe SA |
| A3Sec Group |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
Vertical integration into sovereign cloud infrastructure anchors both supply positioning and pricing power for hyperscalers operating Madrid and Barcelona facilities. These providers capture premium tiers by bundling National Cryptologic Centre certification and GDPR data residency guarantees that domestic competitors cannot replicate without multi-year facility investments.
Pricing Analysis
Managed security services and professional support bundling separate premium hyperscaler tiers from unbundled commodity compute offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and data residency guarantees. Cost compression in standard IaaS tiers is intensifying because Spanish SMEs are consolidating vendor relationships under centralized procurement. Manufacturing SMEs in Andalusia exhibit highest price sensitivity, while financial services firms in Madrid demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for dedicated infrastructure, while distributor networks serve fragmented SME segments through managed service provider intermediation. Silicon wafer fabrication concentrates in Taiwan, South Korea, and the USA, with server assembly clustering in China and Mexico. GPU accelerators and high-bandwidth memory modules constitute critical component dependencies. Single-source vulnerability in advanced node semiconductor manufacturing threatens infrastructure expansion timelines. Distribution runs through systems integrators and certified managed service providers for public sector procurement compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's cloud market sits in a containerization transition phase, with Kubernetes-native architectures displacing monolithic legacy applications that resist API-based integration across banking and manufacturing verticals.
For Market Incumbents: Lock in enterprise relationships through sovereign cloud certification investments that freeze competitive entry for 12-18 months under National Cryptologic Centre timelines. Deepen FinOps professional services attachment to capture margin as infrastructure pricing compresses. The threat of AI-optimized compute specialization from Google LLC demands defensive GPU capacity expansion in Barcelona research corridors. For New Entrants and Emerging Players: Edge computing nodes for predictive maintenance workloads offer a technology-first wedge into Basque Country manufacturing zones underserved by hyperscaler presence. Secondary metropolitan markets in Andalusia and Valencia present underpenetrated public sector demand. A channel partnership strategy with regional systems integrators accelerates National Cryptologic Centre certification navigation. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of domestic compliance specialists with existing security clearance. Long-term viability favors providers with certified sovereign infrastructure and AI workload isolation capabilities. The signal to watch is EU AI Act implementation timelines that will reclassify machine-learning procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | National Cryptologic Centre clearance creates 12-18 month competitive moats for public sector contracts. |
| GPU Infrastructure Expansion | Barcelona pharmaceutical developers drive premium compute demand for molecular simulation workloads. |
| FinOps Professional Services | Centralized procurement teams prioritize cost governance expertise over raw infrastructure pricing. |
| Edge Computing Deployment | Bilbao manufacturing corridors require low-latency nodes for predictive maintenance applications. |
| AI Compliance Infrastructure | EU AI Act risk classifications redirect procurement toward pre-certified training environment isolation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cloud platform engineers, IT procurement officers at Spanish financial institutions, National Cryptologic Centre certification auditors, and managed service provider executives. Secondary sources encompassed AEPD enforcement disclosures, EU procurement directive databases, hyperscaler capex reports, and Spanish Data Protection Agency audit findings. Bottom-up workload sizing across Madrid and Barcelona zones triangulated against top-down enterprise IT spend surveys.
Data-stream reconciliation across deployment models, service types, customer segments, and regional adoption patterns generated volume and value outputs throughout the forecast period. CAGRs derived from segment-level growth rate interpolation weighted by procurement maturity indicators. Modeled inputs included container orchestration adoption curves, sovereign cloud certification pipeline timelines, and GPU instance provisioning ratios for pharmaceutical and research workloads.
Several conditions sit outside the modeled scope, including pending EU AI Act regulatory finalization, unannounced hyperscaler facility investments, and macroeconomic shocks to Spanish SME IT budgets. Forecasts reflect assumptions about certification timeline stability and legacy system API integration feasibility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
SME Cloud Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
Cloudifier Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Public Cloud Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Application Hosting Market