
 Europe Cloud Computing Market | 2026-2036
Europe Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cloud Computing Market Analysis
ISO 27001 and SOC 2 Type II certification tiers is redrawing competitive hierarchy across European cloud procurement. Microsoft Azure leverages its extensive EU data center footprint to anchor enterprise loyalty in regulated sectors. OVHcloud differentiates through strict data sovereignty guarantees and French government cloud qualification. Google Cloud sustains aggressive expansion via custom silicon and carbon-neutral operations pledges.
Europe Cloud Computing denotes the delivery of on-demand compute, storage, networking, and platform resources over IP-based networks from data centers located within European jurisdictions, typically governed by latency thresholds under 20 milliseconds and data residency constraints. Its primary purpose enables enterprises to replace capital-intensive on-premises infrastructure with elastic operational expenditure models while meeting jurisdictional compliance. Hybrid Cloud deployments now capture the largest revenue pool as enterprises stricter legacy system retention with cloud-native development. SaaS delivery leads service type adoption among end users seeking minimal management overhead. Government and financial services verticals within the End User segment command premium pricing due to enhanced security and audit requirements.
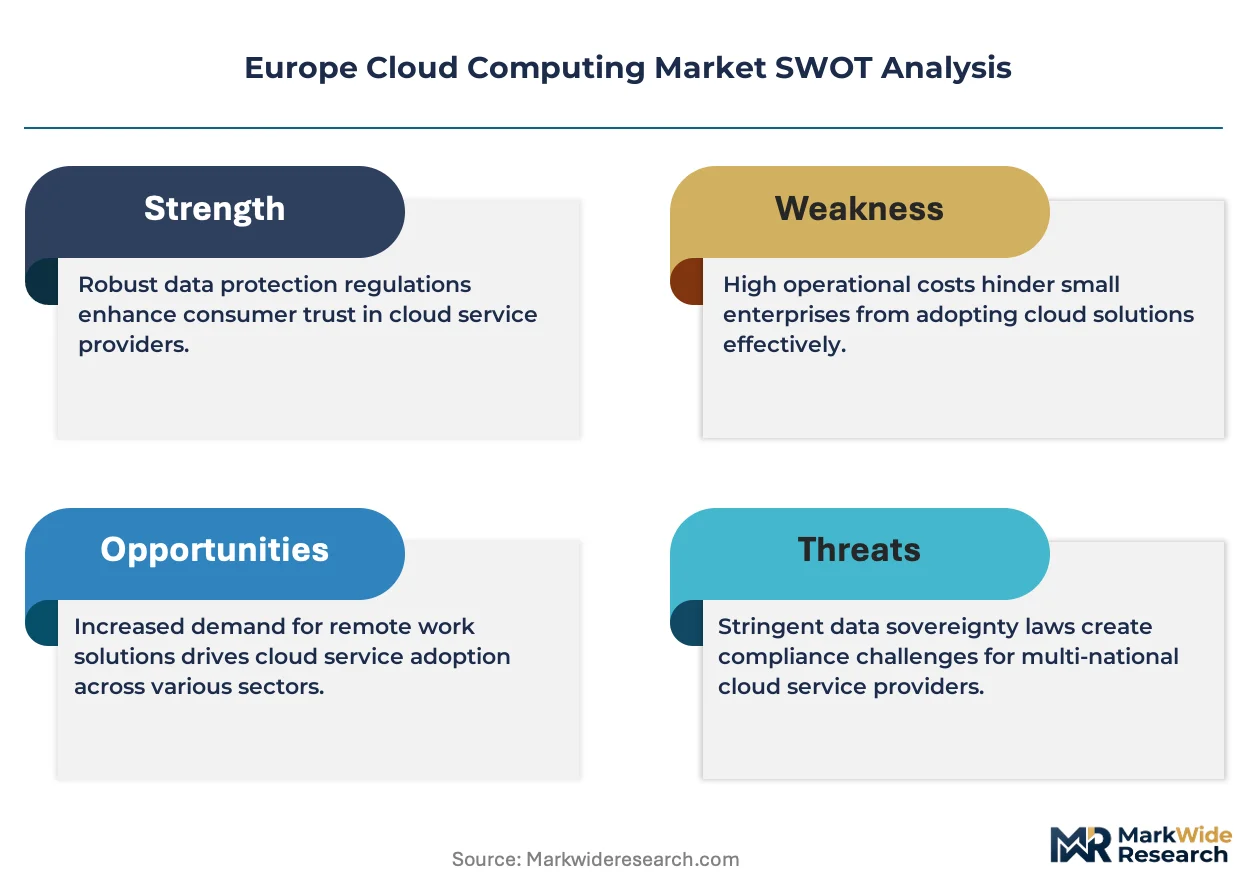
GDPR, the EU AI Act, and national implementations of the NIS2 Directive collectively reshape provider architectures, mandating encryption standards, incident reporting protocols, and algorithmic transparency for AI-integrated cloud workloads. EMA guidelines for pharmaceutical data integrity and ECB oversight of cloud outsourcing by systemic banks add sector-specific compliance layers. Stakeholders must weigh sovereign cloud investments against interoperability costs as fragmentation between national certification schemes deepens.
Market Dynamics
The EU AI Act and GDPR compliance requirements are compressing procurement timelines while fragmenting vendor qualification standards across member states. Financial institutions and pharmaceutical companies now demand sovereign cloud architectures with localized encryption key management, forcing providers to rebuild infrastructure around jurisdictional boundaries rather than latency optimization alone.
Growth Catalysts
- NIS2 Directive implementation:The directive mandates stricter incident reporting and supply chain security for critical infrastructure operators, accelerating replacement of legacy on-premises systems with certified cloud platforms.
- Financial services migration:Systemic banks under ECB oversight are outsourcing core payment processing to EU-qualified cloud environments to reduce capital reserves tied to physical data centers.
- Edge computing integration:Manufacturing facilities in Germany and the Netherlands are deploying 5G-connected edge nodes for real-time quality control, creating hybrid demand that pure hyperscale models cannot satisfy.
Market Restraints
- Energy cost volatility:Data center power purchase agreements in Ireland and Sweden face renegotiation pressure as Nordic electricity markets experience price spikes, compressing provider margins.
- Semiconductor supply concentration:Custom AI accelerators and high-bandwidth memory modules depend on single-source foundry capacity in East Asia, creating 18-24 month procurement queues for European cloud builders.
- Cross-border data friction:Schrems II rulings invalidate Privacy Shield successor mechanisms, forcing redundant infrastructure investments for US-headquartered providers serving EU clients.
Strategic Opportunities
- Gaia-X federation expansion:The French-German data infrastructure initiative creates procurement preference for interoperable sovereign cloud providers, opening public sector contracts previously captured by non-EU hyperscalers.
- Carbon accounting integration:The CSRD mandates granular Scope 3 emissions disclosure, positioning carbon-neutral data center operators to capture sustainability-linked procurement from listed enterprises.
- Confidential computing:Hardware-based trusted execution environments enable processing of encrypted data without decryption, unlocking healthcare and government workloads previously excluded from cloud migration.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Enterprise IT departments lack personnel fluent in Kubernetes, Terraform, and sovereign compliance frameworks simultaneously, extending deployment timelines.
- ISO 27001 certification backlog:Accredited audit bodies in Southern Europe operate 6-9 month queues, delaying market entry for new providers targeting regulated verticals.
- Legacy mainframe interconnection:Core banking systems running COBOL require specialized gateway infrastructure that cloud-native architectures do not natively support, inflating integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cloud Computing Market |
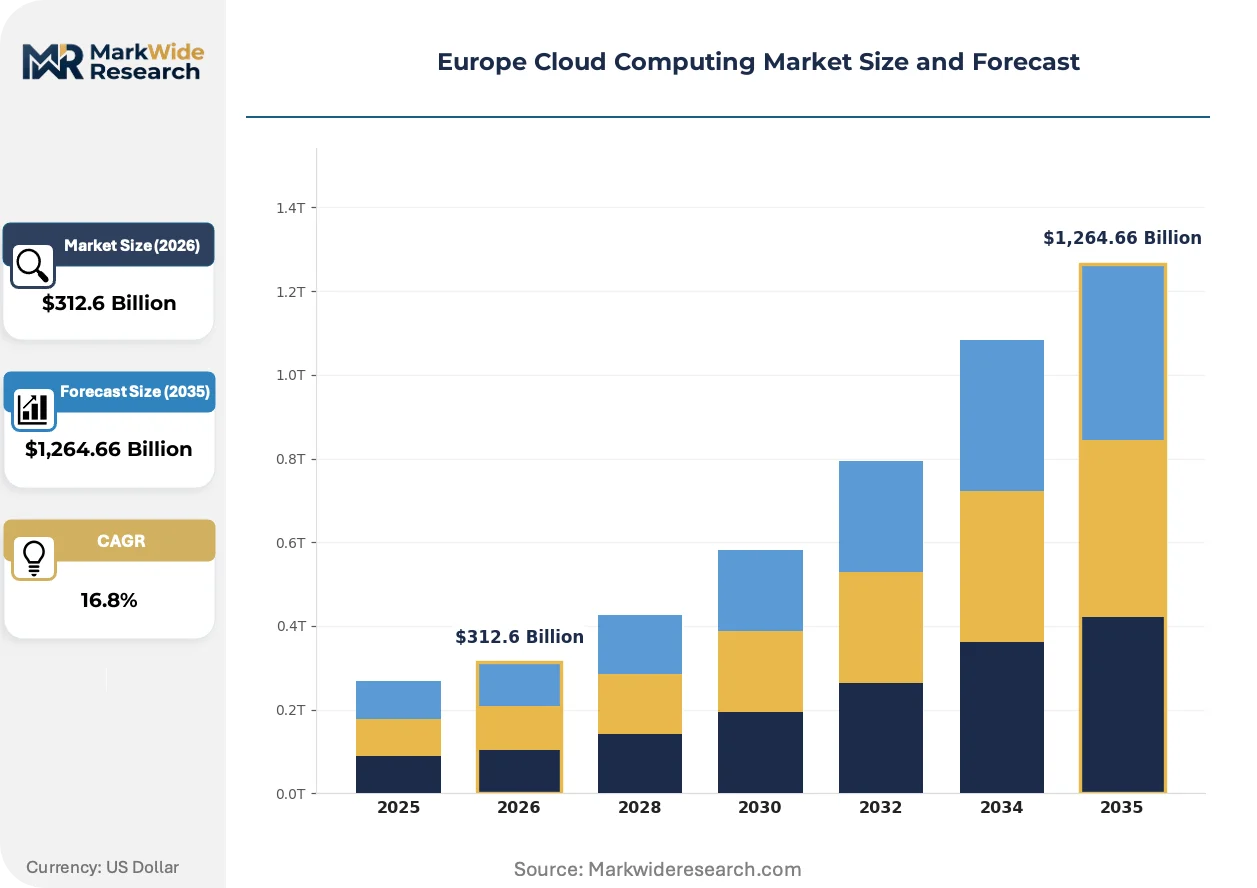
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,264.66 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, FaaS End User: SMEs, Large Enterprises, Government, Educational Institutions Solution: Data Backup, Disaster Recovery, Cloud Storage, Application Hosting |
| Companies Covered | OVHcloud, IONOS Cloud, Microsoft Azure, UpCloud, Hetzner, Amazon Web Services (AWS), Oracle Cloud Infrastructure, Serverspace, Google Cloud, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cloud Computing Market Emerging Trajectories
European cloud infrastructure is fragmenting along sovereignty lines while converging around carbon performance metrics and AI workload specialization. Providers must now architect for compliance-first rather than performance-first deployment patterns.
Confidential computing hardware from Intel and AMD is bifurcating the security architecture landscape. Pharmaceutical companies conducting multi-party clinical trials are adopting these chips to process patient data without exposing raw records to cloud administrators. This capability is compressing the addressable market for traditional encryption-at-rest solutions while expanding total cloud spend in life sciences verticals previously blocked by data residency concerns.
The EU AI Act risk classification framework is reshaping provider liability structures. High-risk AI systems deployed on cloud infrastructure must maintain audit logs and human oversight capabilities, forcing platform operators to build compliance tooling as core services. Financial services firms in Frankfurt and Paris are selecting providers based on pre-certified AI governance modules rather than raw compute pricing.
Enterprise buying committees are consolidating vendor relationships to reduce interoperability overhead. Mid-cap manufacturers in Bavaria and Lombardy are replacing best-of-breed point solutions with integrated platform contracts spanning IaaS, PaaS, and SaaS layers. This concentration is most visible in automotive supply chains, where tier-one suppliers demand single-pane visibility across design, simulation, and production workloads.
Europe Cloud Computing Market Segmentation
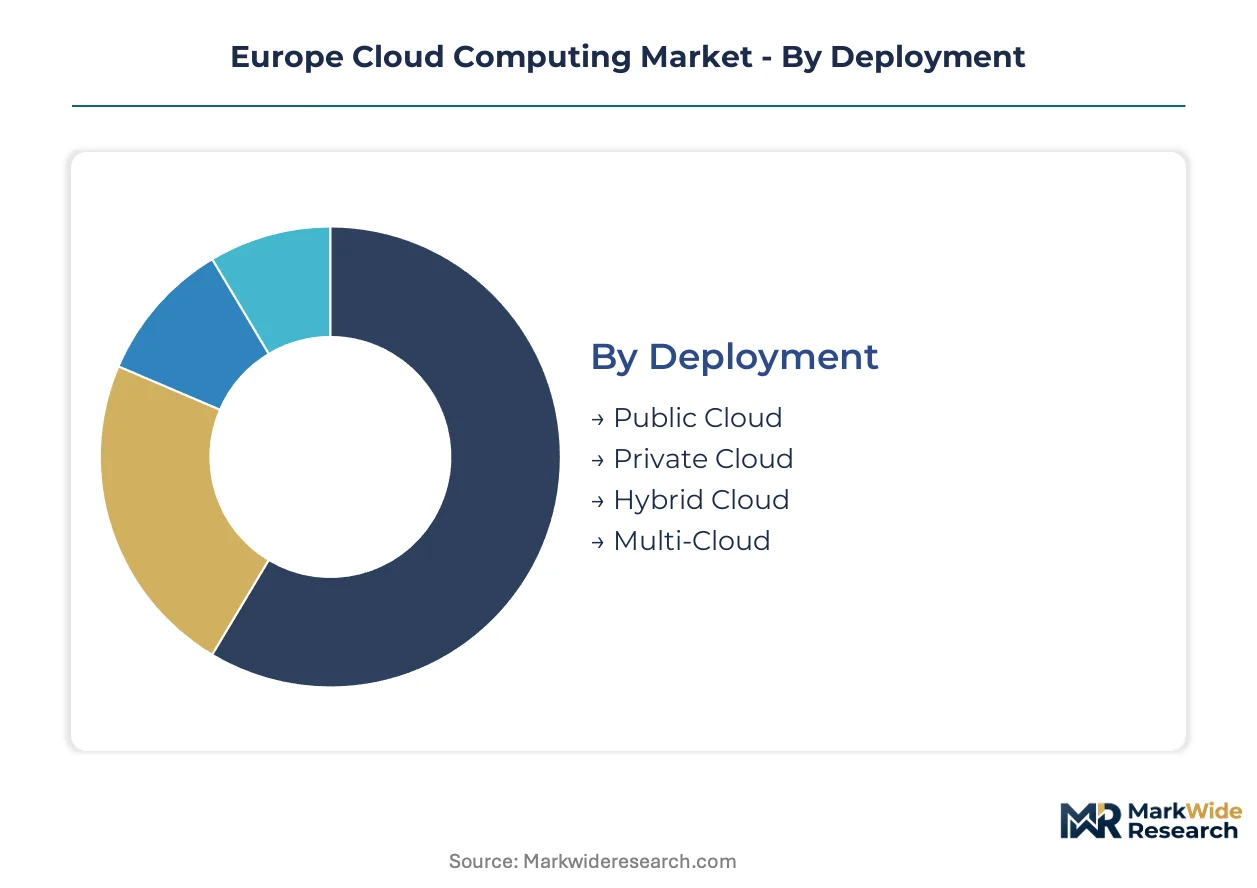
Cloud procurement patterns in Europe diverge sharply across deployment architectures and compliance tiers. Buyers segment infrastructure choices by data sovereignty exposure, latency sensitivity, and regulatory audit depth rather than raw compute economics alone.
Deployment:
Substitution pressure from sovereign cloud alternatives and edge-native architectures is fragmenting traditional deployment hierarchies.
- Public Cloud:Shared infrastructure delivers elastic compute pools through hyperscale data centers in Frankfurt, Amsterdam, and Dublin. German automotive suppliers and Dutch logistics operators dominate consumption, driven by burst capacity needs for simulation workloads and seasonal demand spikes.
- Hybrid Cloud:Orchestrated environments bridge on-premises assets with off-premise elasticity through unified management planes. French systemic banks under ECB oversight anchor demand, compelled by capital reserve rules that penalize fully-outsourced core systems while permitting cloud-adjacent processing.
- Private Cloud:Dedicated single-tenant infrastructure serves classified government workloads and pharmaceutical trial data under EMA guidelines.
- Multi-Cloud:Distributed architectures spanning two or more hyperscale providers reduce vendor lock-in for mission-critical applications.
Hybrid Cloud retains volume leadership; Multi-Cloud holds the steepest expansion curve.
Service Type:
Margin compression in commoditized compute layers is pushing providers toward higher-abstraction services with embedded compliance tooling.
- SaaS:Application-layer delivery eliminates infrastructure management overhead through browser-accessible software licensed by seat or transaction volume. Nordic professional services firms and Benelux mid-market manufacturers drive procurement, prioritizing GDPR-compliant HR and finance modules over custom development.
- IaaS:Raw compute, storage, and networking resources provisioned through APIs enable lift-and-shift migration of legacy workloads. Italian public sector bodies and Spanish regional health authorities concentrate demand, constrained by NIS2 procurement timelines and ISO 27001 certification requirements.
- PaaS:Developer-centric environments abstract runtime management while preserving deployment flexibility.
- FaaS:Event-driven serverless execution charges per invocation rather than provisioned capacity.
SaaS captures the widest enterprise penetration; PaaS is climbing the fastest as container-native development standardizes.
End User:
Customer-type segmentation reflects diverging risk appetites for data residency and audit trail granularity.
- Government:National and supranational agencies mandate in-country encryption key custody and personnel security clearance for cloud administrators. Gaia-X qualification requirements in France and Germany, plus CSRD-aligned procurement rules, channel spending toward certified sovereign providers.
- Large Enterprises:Multinational corporations with EU headquarters in London, Paris, and Munich balance global operational consistency against Schrems II-driven data localization. Pharmaceutical multinationals conducting EMA-regulated trials anchor demand for confidential computing-enabled environments.
- SMEs:Resource-constrained organizations prioritize per-seat pricing and minimal IT overhead.
- Educational Institutions:Research universities and technical colleges leverage cloud for compute-intensive simulation and collaboration platforms.
Large Enterprises retain volume leadership; Government holds the steepest expansion curve.
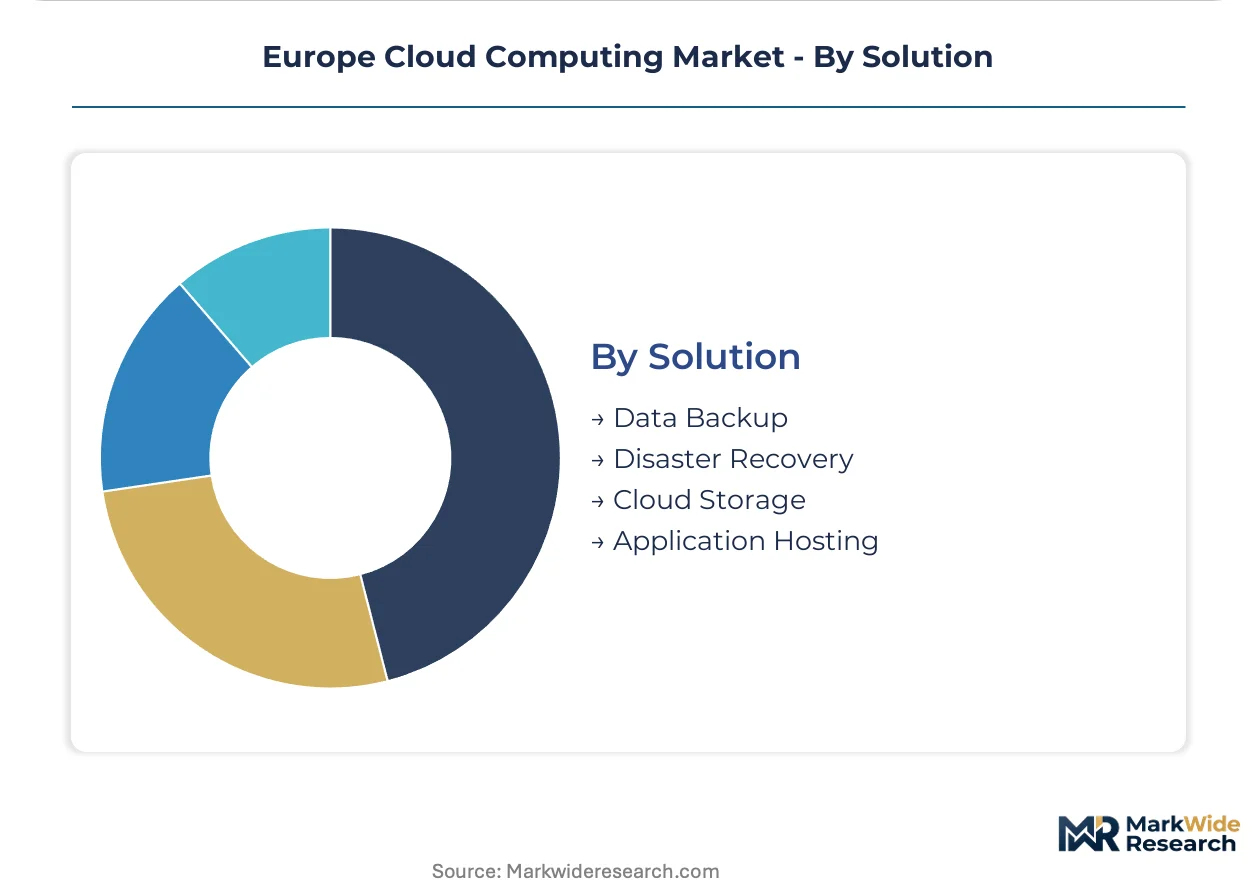
Solution:
Application maturity determines which workload categories face displacement by cloud-native alternatives versus persistent on-premises retention.
- Cloud Storage:Object and block storage services replace tape libraries and NAS appliances through pay-per-gigabyte consumption models. German industrial IoT deployments and French media archives concentrate demand, driven by exponential sensor data growth and 4K/8K content retention requirements.
- Disaster Recovery:Automated failover and point-in-time recovery capabilities replace secondary data center investments. Dutch financial services firms and Irish pharmaceutical operations anchor procurement, compelled by ECB and EMA business continuity mandates.
- Data Backup:Immutable snapshot services protect against ransomware and operational deletion.
- Application Hosting:Managed runtime environments for legacy ERP and custom business applications.
Cloud Storage retains volume leadership; Disaster Recovery holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cloud infrastructure exports flow into French and Dutch enterprise buyers, creating a north-south corridor where sovereign compliance requirements shape procurement patterns across the continent.
Germany
Automotive suppliers in Bavaria and financial institutions in Frankfurt drive sovereign cloud demand for AI training workloads and core banking systems. The BSI's C5 certification framework mandates strict encryption standards for federal contractors. Hetzner and IONOS Cloud anchor domestic capacity in Frankfurt and Berlin-Brandenburg, serving mid-market manufacturers with GDPR-compliant hosting.
France
Public sector digitization and pharmaceutical R&D in Île-de-France concentrate demand for Gaia-X qualified infrastructure. ANSSI's SecNumCloud certification creates procurement preference for providers meeting personnel security clearance requirements. OVHcloud operates hyperscale facilities in Roubaix and Strasbourg, capturing defense and healthcare contracts previously awarded to non-EU operators.
Netherlands
Amsterdam's AMS-IX internet exchange attracts financial services and logistics firms requiring sub-10 millisecond latency to London and Frankfurt. The Digital Government Act mandates in-country data storage for citizen registries and tax systems. Microsoft Azure and Google Cloud have expanded region presence to capture Dutch maritime and flower auction platform workloads.
United Kingdom
London's fintech cluster and Edinburgh's banking sector sustain demand despite post-Brexit regulatory divergence from EU frameworks. The UK National Cyber Security Centre's Cloud Security Principles guide procurement for critical national infrastructure operators. AWS and Oracle Cloud maintain substantial Thames Valley and London data center footprints to serve insurance and asset management verticals.
Italy
Regional health authorities in Lombardy and Lazio accelerate migration of patient record systems to certified cloud platforms under NIS2 implementation timelines. The AgID's Cloud PA framework establishes technical and organizational standards for public administration outsourcing. UpCloud and local system integrators capture mid-market manufacturing demand in Emilia-Romagna's industrial belt.
Europe Cloud Computing Market Vendor Landscape
Listed hyperscale platforms compete with private European specialists across certification depth and data sovereignty guarantees. Market structure divides into three tiers: global incumbents with extensive region builds, national champions leveraging government qualification, and niche operators targeting latency-sensitive edge workloads. Strategic moves center on Gaia-X federation membership and carbon-neutral data center expansion to meet CSRD procurement criteria.
Within the sovereign cloud tier, OVHcloud exemplifies the French government-qualified archetype through its SecNumCloud and Gaia-X certifications. Among German mid-market specialists, Hetzner occupies a position emphasizing price-performance for developer-centric workloads. Microsoft Azure anchors the multinational incumbent category, representing the compliance-heavy approach required by ECB-supervised financial institutions. These three archetypes illustrate how vendor selection now prioritizes jurisdictional certification over raw compute economics.
| Leading Market Players |
|---|
| OVHcloud |
| IONOS Cloud |
| Microsoft Azure |
| UpCloud |
| Hetzner |
| Amazon Web Services (AWS) |
| Oracle Cloud Infrastructure |
| Serverspace |
| Google Cloud |
| Others |
Supply Flow & Price Mechanics
Hyperscale data center utilization rates above 75% in Frankfurt and Amsterdam create nonlinear cost advantages that compress price floors for mid-tier providers while elevating entry barriers for sovereign cloud specialists. This scale concentration forces European challengers to compete on certification depth rather than raw compute economics, embedding compliance premiums into contract structures.
Pricing Analysis
Next-generation confidential computing instances command 40-60% premiums over standard virtual machines, while prior-generation x86 instances face accelerating price erosion from surplus capacity. Three-tier pricing structure across premium sovereign-certified, standard enterprise-grade, and economy developer tiers dominates procurement. Price differentiation hinges on ISO 27001 audit depth and in-country encryption key custody. Cost compression in the economy tier intensifies because hyperscalers are absorbing idle capacity through spot-instance discounting. SMEs in Southern Europe exhibit highest price sensitivity, while ECB-supervised banks accept substantial premiums for pre-certified compliance modules.
Supply Chain Analysis
Eighteen-to-twenty-four month lead times for custom AI accelerators and high-bandwidth memory modules constrain European cloud builders' expansion timelines. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced silicon fabrication. European infrastructure draws from Chinese rare earth processing for magnet components in cooling systems and Japanese precision optics for photonic interconnects. Single-source foundry vulnerability in East Asia exposes providers to geopolitical disruption. Distribution runs through direct hyperscaler procurement for large enterprises and regional systems integrators for mid-market sovereign cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's cloud market operates as a regulatory-moat architecture where GDPR, EU AI Act, and national certification schemes create switching costs that protect incumbent positions. This entrenchment rewards early movers with sovereign qualifications and punishes late entrants with 12-18 month compliance timelines.
For Market Incumbents: Shield market position by accelerating Gaia-X federation membership to capture public sector procurement preferences and deepening vertical integration into confidential computing hardware partnerships. Threat substitution from edge-native architectures demands pre-emptive 5G node deployment in German manufacturing corridors. Certification investment in SecNumCloud and C5 frameworks anchors the priority lever against price-based challengers. For New Entrants and Emerging Players: ANSSI fast-track certification pathways for healthcare and defense verticals open white-space entry before hyperscalers complete personnel security clearance adaptations. Mid-market pharmaceutical R&D in Île-de-France represents the most penetrable segment, with EMA-regulated trial data creating demand for sovereign alternatives. Go-to-market execution should center on carbon-neutral data center positioning to capture CSRD-mandated procurement from listed enterprises. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sovereign cloud providers with multi-year public sector contracts and automatic renewal clauses. Long-term viability across the projection horizon favors specialists with Gaia-X interoperability and national government cloud qualifications over undifferentiated infrastructure resellers. Acquisition targets should demonstrate ISO 27001 certification backlog clearance and existing SecNumCloud or C5 credentials. The signal to watch is NIS2 procurement timeline acceleration in Southern European health authorities.| Strategic Initiative | Industry Significance |
|---|---|
| Gaia-X Federation Membership | Unlocks French and German public sector contracts previously captured by non-EU hyperscalers. |
| Confidential Computing Hardware Integration | Enables processing of encrypted patient data for pharmaceutical clinical trials under EMA guidelines. |
| Carbon-Neutral Data Center Expansion | Positions operators to capture CSRD-mandated sustainability-linked procurement from listed enterprises. |
| ISO 27001 Certification Fast-Track | Accelerates market entry for regulated verticals facing 6-9 month audit body queues in Southern Europe. |
| Edge Node Deployment in Manufacturing Corridors | Captures 5G-connected quality control workloads that pure hyperscale models cannot satisfy. |
Methodological Framework
Initial hypotheses were tested against primary input from cloud procurement officers at systemic banks, sovereign cloud platform engineers, data center infrastructure planners, and regulatory compliance leads at pharmaceutical multinationals and refined through secondary validation. Sources included hyperscaler capex disclosures, EU regulatory filings under GDPR and NIS2, Gaia-X federation technical specifications, and national cloud framework documentation from BSI and ANSSI. Bottom-up demand modeling triangulated against top-down market sizing across deployment architectures.
Variance decomposition across the projection horizon isolates growth contributions from regulatory compliance mandates, AI workload migration, and sovereign cloud substitution. Segmentation dimensions modeled encompass deployment model, service type abstraction layer, end-user risk tier, and national certification jurisdiction. CAGRs derive from cohort-based adoption curves calibrated to NIS2 implementation timelines and ECB outsourcing guidance evolution. Forecast inputs incorporate confidential computing hardware availability constraints and Nordic electricity market price volatility assumptions.
Decision-makers should treat outputs as directional under sustained GDPR enforcement and NIS2 procurement acceleration assumptions; material deviation in Schrems II successor mechanisms or semiconductor supply normalization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Global Hybrid and Community Cloud As a Service Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Automotive Cloud Based Solutions Market