
 Cloud Based Contact Center Market | 2026-2036
Cloud Based Contact Center Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Based Contact Center Market Analysis
India's contact center capacity build-out is fragmenting as domestic BPO operators migrate voice infrastructure to cloud-native stacks. NICE leverages predictive behavioral routing to sustain premium positioning in workforce optimization suites. Genesys anchors enterprise accounts through deep CRM integration capabilities across Salesforce and Microsoft ecosystems. Five9 competes aggressively in the mid-market with AI-powered agent assist tools that reduce average handle times.
A cloud based contact center delivers customer interaction management through virtualized automatic call distribution, interactive voice response, and omnichannel queuing hosted on remote server infrastructure rather than on-premises PBX hardware. These platforms process voice, chat, email, and social messaging through unified agent desktops with sub-150 millisecond latency requirements for real-time transcription. Public cloud deployments dominate volume adoption due to elastic scaling during seasonal demand spikes, while hybrid cloud configurations capture margin pools from financial institutions with data residency constraints. AI-powered solutions within the technology segment are displacing rules-based routing as natural language processing accuracy crosses commercial thresholds for sentiment analysis and intent classification.
The Federal Communications Commission enforces STIR/SHAKEN caller ID authentication mandates that cloud contact center providers must embed to prevent illegal robocall origination from VoIP trunk lines. The EU AI Act classifies emotion recognition systems in customer service contexts as high-risk, requiring conformity assessments before deployment in European member states. Enterprises must evaluate whether their vendor's architecture supports regional data sovereignty requirements without sacrificing real-time analytics performance.
Market Dynamics
Hyperscaler partnerships with legacy telecom carriers are compressing vendor margins while accelerating platform consolidation among enterprise buyers seeking unified infrastructure stacks.
Growth Catalysts
- EU AI Act compliance frameworks:The high-risk classification for emotion recognition systems is forcing vendors to invest in explainable AI architectures, creating differentiation for early movers with certified conformity assessments.
- BFSI omnichannel demand:Financial institutions require seamless voice-to-digital handoffs with audit trails, pulling cloud-native replacements for aging on-premises ACD systems.
- Elastic scaling architectures:Public cloud deployments enable seasonal capacity spikes without stranded capital, particularly for retail and travel verticals with predictable demand cycles.
Market Restraints
- Data residency mandates:Financial institutions in Germany and France require sovereign cloud configurations that fragment vendor R&D resources across incompatible infrastructure footprints.
- STIR/SHAKEN implementation costs:FCC mandates for caller ID authentication impose fixed compliance burdens that disproportionately squeeze mid-market providers lacking carrier-grade signaling expertise.
- Hybrid integration complexity:Enterprises maintaining legacy CRM investments face API latency penalties when bridging on-premises customer data lakes with cloud agent desktops.
Strategic Opportunities
- India domestic BPO migration:Voice infrastructure modernization among tier-two operators creates whitespace for cloud-native workforce optimization suites with vernacular language support.
- Real-time transcription convergence:Sub-150 millisecond NLP pipelines are unlocking sentiment-driven routing decisions that command premium pricing in high-churn subscription verticals.
- API-first distribution channels:System integrators and CRM marketplaces are emerging as primary procurement paths, displacing direct enterprise sales cycles for sub-500 seat deployments.
Industry Challenges
- Conversational AI talent scarcity:Shortages of linguists with domain-specific training data curation skills are extending model deployment timelines for intent classification systems.
- Legacy PBX decommissioning friction:Enterprises with sunk capital in Cisco and Avaya investments face organizational resistance and change management costs that stall migration decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Based Contact Center Market |
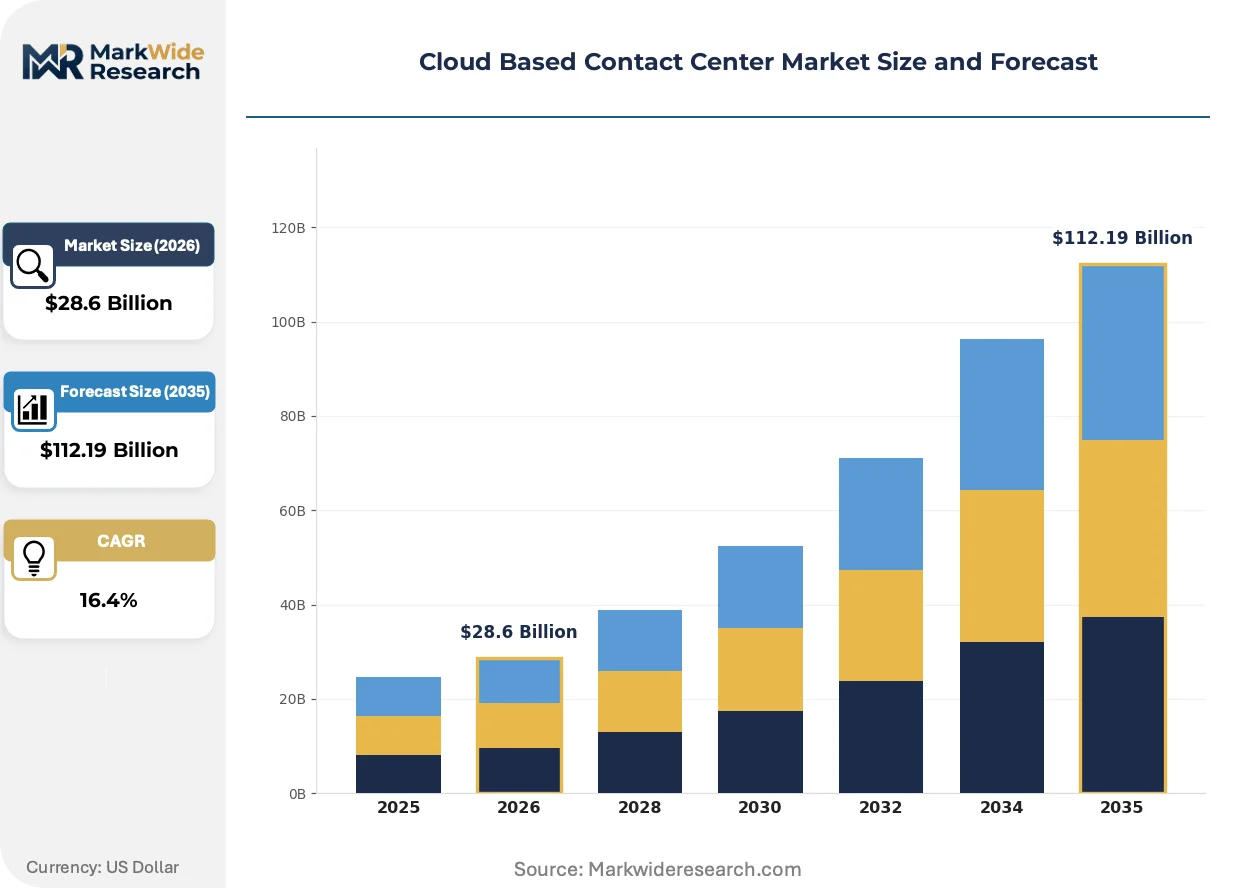
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Inbound Services, Outbound Services, Blended Services, IVR Solutions Technology: AI-Powered Solutions, VoIP, CRM Integration, Omnichannel Routing End User: BFSI, Retail, Healthcare, Telecommunications |
| Companies Covered | NICE, Genesys, Five9, AWS, Talkdesk, Cisco, Avaya, RingCentral, 8x8, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Based Contact Center Market Emerging Trajectories
Agent assist architectures are converging with real-time coaching systems, compressing the boundary between workforce optimization and quality management functions.
Large language model copilots are hybridizing with rules-based knowledge bases to surface contextual responses during live interactions. Mid-market contact centers with 50-300 agents are adopting these tools fastest, reducing average handle times without proportional headcount expansion. The structural consequence is margin compression for standalone quality monitoring vendors as coaching automation becomes table stakes.
The EU AI Act's high-risk classification for automated decision-making in customer service contexts is mandating human-in-the-loop overrides for emotion detection outputs. Vendors must now maintain dual audit trails for algorithmic recommendations and agent overrides, increasing engineering overhead. European financial services and healthcare deployments are requiring these conformity assessments before contract execution, slowing sales cycles but creating compliance moats for certified providers.
Outcome-based pricing for contact center seats is displacing per-agent subscription models in enterprise renewals. Buyers in telecommunications and utilities verticals are negotiating contracts tied to first-contact resolution rates rather than licensed capacity. This shift is most visible in United States enterprise accounts above 1,000 seats, where procurement teams possess the data infrastructure to measure operational outcomes against contracted baselines.
Cloud Based Contact Center Market Segmentation
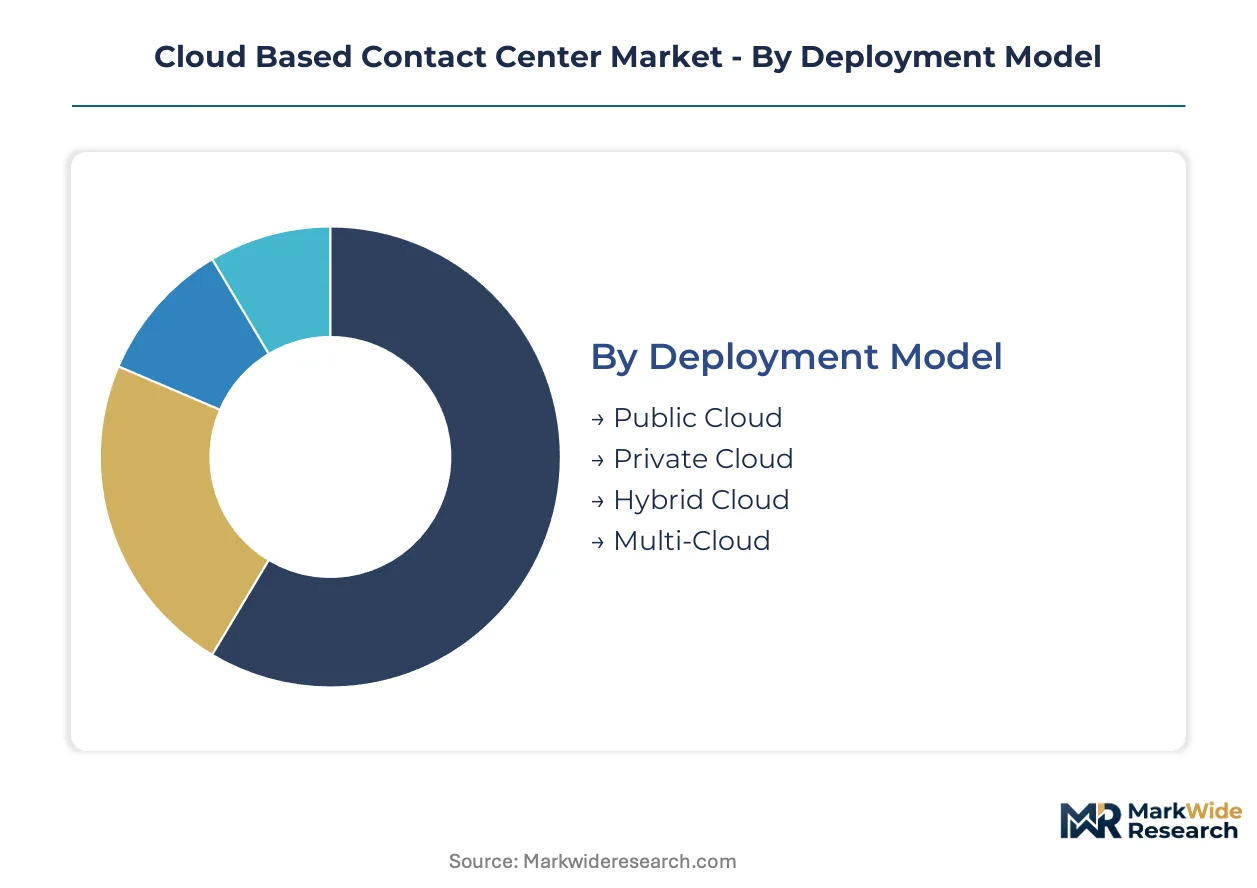
Deployment architecture, service delivery modes, underlying technology stacks, and vertical-specific requirements create distinct competitive arenas within cloud contact center procurement. Buyers prioritize different capability bundles based on regulatory exposure, integration complexity, and seasonal demand volatility.
Deployment Model:
Cost tier determines infrastructure ownership trade-offs between operational flexibility and compliance overhead across enterprise segments.
- Public Cloud:Elastic compute pools shared across tenants enable instantaneous scaling during retail peak seasons without capital commitment. United States e-commerce operators and travel aggregators dominate consumption, driven by unpredictable inquiry volumes and tolerance for multi-tenant data architectures.
- Private Cloud:Dedicated single-tenant environments isolate voice and interaction data on sovereign infrastructure, satisfying German and French financial institutions under national data residency statutes. Premium pricing reflects bespoke hardware provisioning and localized disaster recovery replication.
- Hybrid Cloud:Split workloads route sensitive customer records through on-premises nodes while bursting transactional traffic to public edge locations. Healthcare networks in the United States leverage this bifurcation to maintain HIPAA-controlled data lakes alongside cloud-native agent desktops.
- Multi-Cloud:Orchestration layers distribute workloads across AWS, Azure, and Google Cloud simultaneously to mitigate vendor lock-in and regional outage risks. Telecommunications providers with 99.999% uptime SLAs are adopting these architectures fastest.
Public Cloud holds installed capacity. Multi-Cloud is rotating up the share rankings.
Service Type:
Application orientation separates voice-centric legacy migrations from digital-first engagement platforms.
- Inbound Services:Intelligent queuing and skills-based routing manage customer-initiated voice, chat, and email inquiries through unified agent desktops. BFSI institutions in the United States concentrate demand here, requiring audit trails for regulatory examinations and dispute resolution.
- Outbound Services:Predictive dialers and campaign management tools automate proactive customer contact for collections, sales, and appointment scheduling. FCC STIR/SHAKEN compliance mandates are reshaping vendor roadmaps for authenticated caller ID transmission.
- Blended Services:Dynamic agent state switching between inbound response and outbound campaign execution maximizes seat utilization rates. Domestic BPO operators in India are migrating to these cloud-native stacks to serve multiple client verticals from shared infrastructure.
- IVR Solutions:Speech-enabled self-service trees resolve routine inquiries without agent intervention, reducing cost per contact. Natural language processing accuracy improvements are displacing touch-tone menu hierarchies in enterprise renewals.
Inbound Services holds installed capacity. Blended Services is rotating up the share rankings.
Technology:
Maturity gradients separate proven infrastructure components from emerging AI layers commanding premium pricing.
- AI-Powered Solutions:Real-time sentiment analysis, predictive behavioral routing, and agent assist copilots process sub-150 millisecond transcription pipelines. EU AI Act high-risk classification for emotion recognition systems is mandating explainable architectures and human-in-the-loop overrides in European deployments.
- VoIP:Packet-switched voice transport over internet protocol replaces legacy TDM circuits, enabling geographic agent distribution without physical trunk provisioning. Quality-of-service guarantees and jitter buffering differentiate carrier-grade implementations from commodity offerings.
- CRM Integration:Pre-built connectors to Salesforce, Microsoft Dynamics, and ServiceNow synchronize customer context across voice and digital channels. Deep API integration capabilities anchor enterprise account retention for platform vendors.
- Omnichannel Routing:Unified queuing engines prioritize interactions across voice, chat, email, SMS, and social messaging based on customer value and urgency. Retailers with subscription churn exposure are investing fastest in sentiment-driven routing decisions.
VoIP holds installed capacity. AI-Powered Solutions is expanding most quickly.
End User:
Vertical-specific compliance regimes and customer interaction patterns fragment vendor go-to-market strategies.
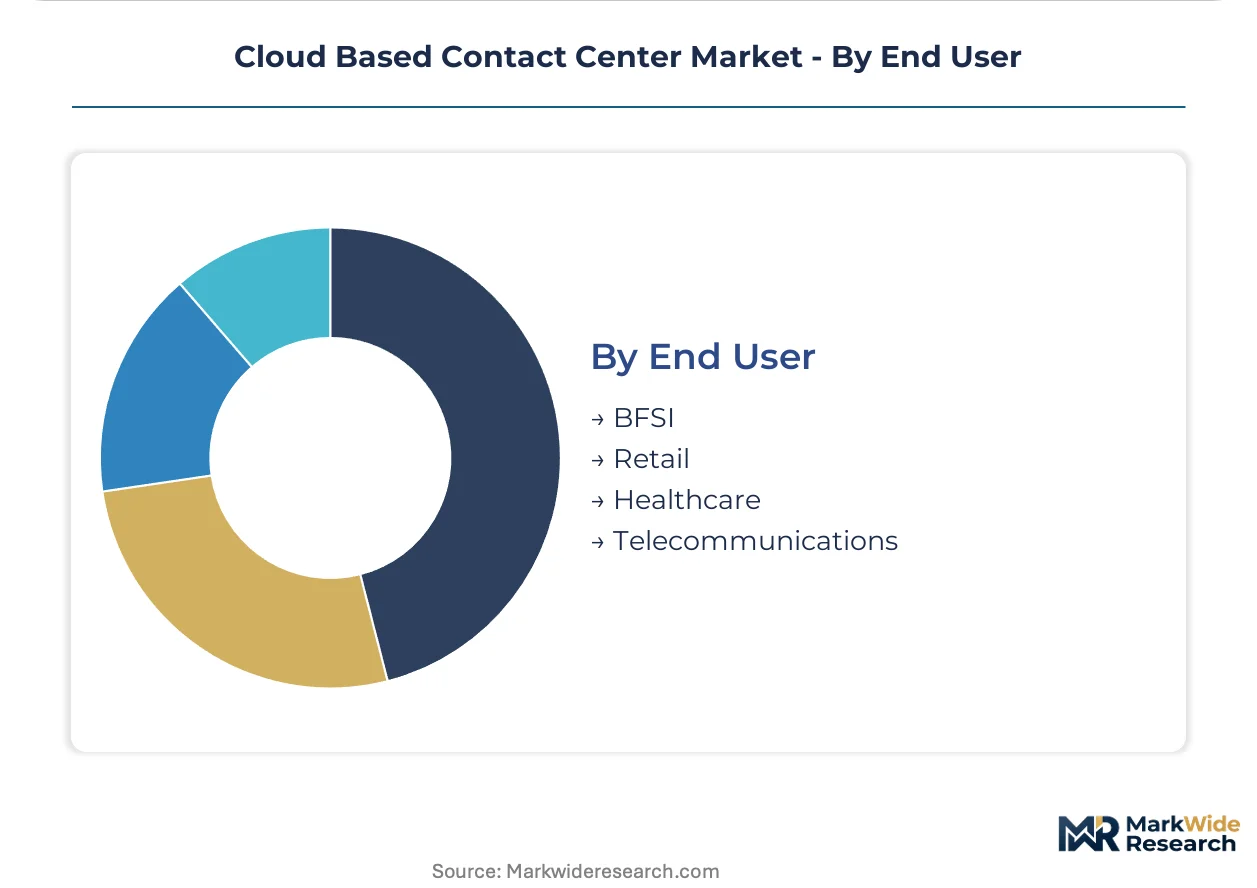
- BFSI:Omnichannel platforms with immutable audit logs support voice-to-digital handoffs for wealth management and insurance claims. German BaFin and French ACPR data localization requirements are pulling hybrid cloud configurations.
- Retail:Seasonal elasticity demands and high transaction volumes drive public cloud adoption with API-first commerce integrations. Black Friday and holiday surge capacity planning shapes procurement specifications.
- Healthcare:HIPAA-compliant interaction recording and encrypted patient data handling constrain vendor selection to HITRUST-certified providers. United States hospital systems prioritize business associate agreement standardization.
- Telecommunications:Outcome-based pricing tied to first-contact resolution rates is displacing per-agent subscriptions in carrier renewals above 1,000 seats. Network operations center integration requirements add complexity.
BFSI holds installed capacity. Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber cable systems landing at Virginia Beach and Bude anchor North American and European cloud contact center traffic flows. These submarine links enable sub-150 millisecond latency for real-time transcription pipelines across both continents.
United States
Hyperscaler partnerships with legacy telecom carriers are compressing vendor margins while accelerating platform consolidation among enterprise buyers. FCC STIR/SHAKEN mandates for caller ID authentication impose fixed compliance burdens that reshape vendor roadmaps for VoIP trunk lines. Dallas-Fort Worth and Phoenix data center clusters host the densest concentrations of cloud contact center infrastructure.
Germany
BaFin data localization requirements pull hybrid cloud configurations from financial institutions requiring sovereign infrastructure for customer interaction records. The EU AI Act's high-risk classification for emotion recognition systems mandates conformity assessments before deployment in German-speaking markets. Frankfurt's financial district anchors BFSI demand for omnichannel platforms with immutable audit logs.
India
Domestic BPO operators are migrating voice infrastructure to cloud-native stacks, fragmenting traditional capacity concentration. TRAI regulations on VoIP interconnection and data localization create compliance complexity for multinational platform deployments. Bengaluru and Hyderabad host the fastest-growing clusters of tier-two operators modernizing workforce optimization suites with vernacular language support.
United Kingdom
API-first distribution channels through CRM marketplaces are displacing direct enterprise sales cycles for sub-500 seat deployments. GDPR interaction recording requirements constrain vendor selection to providers with EU-based data processing capabilities. London's insurance and wealth management corridor drives demand for voice-to-digital handoffs with regulatory audit trails.
Japan
Telecommunications providers with 99.999% uptime SLAs are adopting multi-cloud orchestration layers to mitigate vendor lock-in. METI guidelines on AI governance in customer-facing systems create compliance overhead for emotion detection deployments. Tokyo-Osaka corridor enterprises prioritize deep CRM integration capabilities across Salesforce and Microsoft ecosystems.
Cloud Based Contact Center Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the routing, analytics, and workforce optimization layers. The vendor base separates into three strategic archetypes: full-stack platform vendors with hyperscaler partnerships, point-solution specialists in AI-powered agent assist, and legacy PBX incumbents defending installed base through hybrid cloud transitions. Competitive moves concentrate on M&A for NLP talent acquisition and strategic partnerships with CRM ecosystems to anchor enterprise account retention.
Within the full-stack platform tier, NICE and Genesys exemplify vendors sustaining premium positioning through predictive behavioral routing and deep CRM integration capabilities. Five9 occupies a position in the mid-market segment competing with AI-powered agent assist tools. These three companies represent the dominant competitive archetypes: workforce optimization suites, enterprise platform consolidation plays, and mid-market AI-native challengers.
| Leading Market Players |
|---|
| NICE |
| Genesys |
| Five9 |
| AWS |
| Talkdesk |
| Cisco |
| Avaya |
| RingCentral |
| 8x8 |
| Others |
Supply Flow & Price Mechanics
Dallas-Fort Worth data center clusters anchor North American cloud contact center infrastructure capacity, concentrating hyperscaler compute pools that translate elastic scaling advantages into pricing leverage for enterprise buyers negotiating outcome-based contracts.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on seat count thresholds and SLA guarantees. Price differentiation hinges on AI-powered feature depth and data residency certification status. Pricing pressure stems from hyperscaler partnerships compressing vendor margins while accelerating platform consolidation. Mid-market buyers with 50-300 seats exhibit highest price sensitivity; telecommunications carriers above 1,000 seats prioritize outcome-based metrics over per-agent rates.
Supply Chain Analysis
Upstream feedstock for cloud contact center infrastructure draws from Taiwan semiconductor foundries, South Korean memory fabrication, and United States hyperscaler data center buildouts. Critical components include GPU accelerators for NLP pipelines, optical transceivers for sub-150 millisecond latency, and sovereign cloud hardware for EU compliance. Single-source vulnerability concentrates in advanced AI chip supply. Distribution runs through direct enterprise sales for large accounts and CRM marketplace channels for sub-500 seat deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud contact center procurement represents a service-attach opportunity where AI-powered agent assist and real-time coaching subscriptions expand faster than core platform licensing, embedding vendors deeper into operational workflows.
For Market Incumbents: Build compliance moats through EU AI Act conformity assessments for emotion recognition systems. Invest in explainable AI architectures with dual audit trails. Deepen vertical integration into carrier-grade VoIP infrastructure to defend against hyperscaler margin compression. Prioritize workforce optimization suite consolidation to capture quality management automation.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-two BPO operator segment migrating voice infrastructure to cloud-native stacks. Target vernacular language support gaps left by multinational platforms. Pursue API-first distribution through Salesforce and Microsoft CRM marketplaces to bypass direct sales cycle disadvantages.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with embedded AI copilot subscriptions and outcome-based pricing contracts. Long-term viability favors platforms with certified EU deployments and hybrid cloud orchestration capabilities. Monitor STIR/SHAKEN compliance completion rates as an inflection indicator for mid-market provider consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification | Conformity assessments for emotion recognition systems unlock European BFSI procurement pipelines. |
| Hyperscaler Partnership | AWS, Azure, and Google Cloud alliances compress infrastructure costs while accelerating enterprise consolidation. |
| CRM Marketplace Integration | Salesforce AppExchange and Microsoft AppSource channels displace direct sales for sub-500 seat deployments. |
| Outcome-Based Pricing Transition | First-contact resolution rate contracts align vendor incentives with telecommunications carrier operational metrics. |
| Vernacular Language AI Development | Indic language NLP capabilities capture India's domestic BPO modernization wave. |
Methodological Framework
A standing panel of cloud contact center CTOs, IT procurement officers, platform integration specialists, and workforce optimization directors provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, FCC STIR/SHAKEN implementation databases, and EU AI Act regulatory guidance. Bottom-up seat deployment estimates triangulated against top-down addressable market sizing.
Scenario-bracketing framed demand projections across the analysis window, modeling deployment architecture shifts from on-premises PBX to public cloud and hybrid configurations. Segmentation dimensions included organization size tiers, vertical regulatory exposure, integration complexity levels, and regional data sovereignty requirements. CAGRs derived from elasticity-adjusted seat growth curves and AI feature attach rate assumptions.
Stress conditions across hyperscaler pricing volatility, EU AI Act enforcement timelines, and legacy PBX decommissioning friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about seasonal demand patterns and carrier consolidation trajectories. Cross-checking against FCC robocall mitigation compliance benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market