
 Android CRM Software Market | 2026-2036
Android CRM Software Market Size, Share, and Industry Trends Forecast 2026-2036
Android CRM Software Market Insights
Freemium-to-premium bundling is repositioning how small and mid-sized buyers evaluate total cost of ownership against feature depth. Salesforce leverages its AppExchange ecosystem to sustain platform stickiness across enterprise accounts. Zoho CRM anchors its competitive stance through integrated finance and HR modules that reduce third-party dependency. HubSpot differentiates via inbound marketing tools tightly coupled to its mobile CRM interface.
Android CRM software comprises customer relationship management applications natively engineered for the Android operating system, typically supporting offline synchronization, GPS-based activity logging, and REST API connectivity to backend cloud services. These systems enable field personnel to execute pipeline updates, service ticket resolution, and campaign tracking without continuous network availability. Sales automation dominates revenue contribution among product type segments, while marketing automation registers the fastest expansion as B2B buyers demand closed-loop attribution from mobile touchpoints. Cloud-based deployment captures the largest installed base, though hybrid configurations attract regulated industries requiring local data residency alongside remote accessibility.
FDA guidelines on promotional materials and customer interaction records shape CRM data retention protocols for pharmaceutical field forces, while GDPR and the EU AI Act impose algorithmic transparency requirements on automated lead-scoring modules deployed through European Android instances. India's Digital Personal Data Protection Act adds consent-layer complexity for vendors serving its SME segment. Stakeholders must weigh jurisdictional compliance fragmentation against the cost of maintaining region-specific code branches as mobile CRM becomes indispensable to distributed revenue operations.
Market Dynamics
Offline-first architecture is compressing vendor differentiation as field sales teams demand seamless synchronization between Android devices and cloud backends without latency penalties.
Growth Catalysts
- GDPR and state-level US privacy laws:Pharmaceutical distributors in Europe and the United States now mandate consent-auditable CRM systems, forcing upgrades from legacy mobile databases.
- Healthcare field force digitization:Medical device representatives across India, Brazil, and Indonesia require GPS-logged customer interaction records for compliance with national pharmaceutical regulators.
- Edge computing integration:On-device AI inference for lead scoring is reducing cloud dependency for sales teams operating in bandwidth-constrained rural territories.
Market Restraints
- API rate limiting costs:Third-party mapping and telephony integrations now consume 15-25% of total platform operating budgets for mid-market vendors.
- Data residency fragmentation:India's Digital Personal Data Protection Act and Indonesia's pending data localization rules force code branch maintenance across Southeast Asian deployments.
- Substitution by unified workspace suites:Microsoft and Google bundle lightweight CRM modules with enterprise productivity licenses, capturing price-sensitive SME accounts.
Strategic Opportunities
- Indonesia SME digitization gap:Less than 12% of Indonesian distributors currently deploy mobile CRM, creating whitespace for verticalized field service solutions.
- EU AI Act algorithmic transparency:Automated lead-scoring vendors can differentiate by pre-certifying explainability modules for European pharmaceutical field forces.
- 5G standalone network slicing:Guaranteed quality-of-service lanes for CRM data sync are enabling premium service tiers among German automotive field sales teams.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle backend synchronization requires 6-9 month implementation timelines, delaying mobile rollout ROI realization.
- Cross-platform security certification:FedRAMP and ISO 27001 audit backlogs now extend 14-18 months, freezing public sector Android CRM procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Android CRM Software Market |
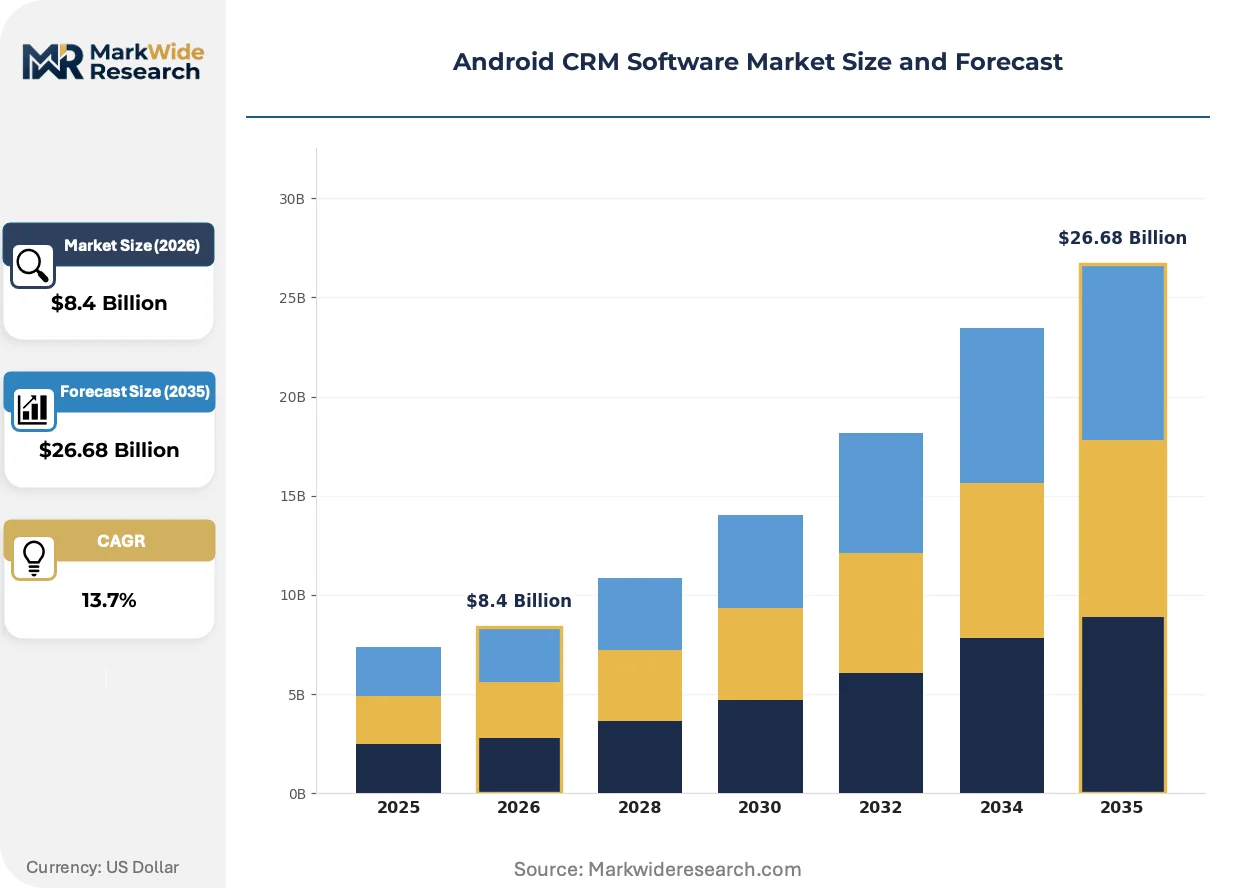
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sales Automation, Customer Support, Marketing Automation, Analytics Deployment: Cloud-Based, On-Premise, Hybrid, Managed Service End User: SMEs, Large Enterprises, Freelancers, Non-Profits Pricing Model: Subscription, One-Time Purchase, Freemium, Pay-As-You-Go |
| Companies Covered | Salesforce, Zoho CRM, HubSpot, Pipedrive, SugarCRM, Microsoft Dynamics 365, Insightly, Freshsales, Agile CRM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Android CRM Software Market Trends and Innovations
Three forces are restructuring how Android CRM platforms capture value: compute migration toward devices, regulatory algorithmic accountability, and procurement model fragmentation favoring modular subscription tiers.
On-device machine learning inference for predictive opportunity scoring is decentralizing data processing from centralized cloud architectures to Android handsets. Pharmaceutical field representatives in bandwidth-variable territories adopt these capabilities fastest, compressing vendor reliance on continuous connectivity and reducing latency-sensitive churn in competitive evaluations.
GDPR's Article 22 on automated decision-making and the EU AI Act's risk classification framework now mandate explainability logs for AI-driven lead prioritization. European pharmaceutical CRM deployments must implement interpretable model outputs, adding 20-30% to compliance engineering costs while creating defensible moats for vendors with pre-built transparency modules.
Subscription unbundling now dominates mid-market procurement, with buyers assembling CRM functionality from specialized point solutions rather than monolithic suites. German automotive distributors and Indian pharmaceutical wholesalers increasingly procure offline sync, GPS logging, and marketing automation as separate microservices, fragmenting vendor wallet share and compressing platform stickiness metrics.
Android CRM Software Market Segmentation
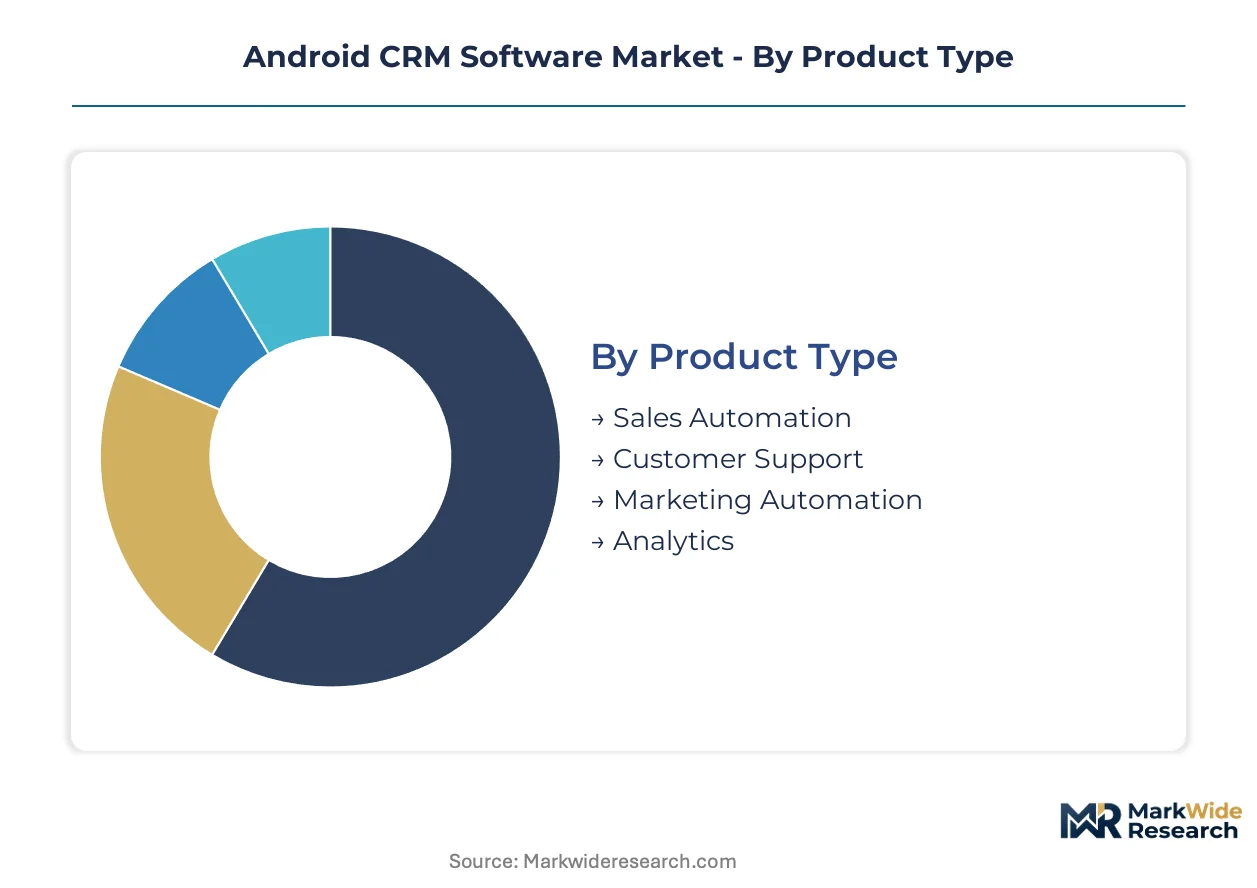
Android CRM segmentation reveals how vendor engineering priorities diverge across field deployment contexts. Product architecture, infrastructure choices, and procurement models each reshape competitive positioning for pharmaceutical field forces and distributed sales teams.
Product Type:
Volume concentration sits with pipeline management tools, while premium pricing attaches to predictive modules requiring on-device inference.
- Sales Automation:Pipeline tracking, quote generation, and order capture modules dominate revenue contribution. Pharmaceutical distributors in Germany and India deploy these capabilities for field force compliance logging under national pharmaceutical regulator requirements.
- Customer Support:Ticket routing, knowledge base access, and SLA monitoring for service teams. Demand concentrates among Brazilian medical device wholesalers requiring GPS-tagged resolution records for ANVISA audit trails.
- Marketing Automation:Campaign orchestration and lead nurturing workflows.
- Analytics:Dashboard visualization and predictive forecasting tools.
Mature deployment sits with Sales Automation. Newer deployment is concentrated in Marketing Automation.
Deployment:
Cost tiering separates fully managed offerings from self-operated infrastructure, with hybrid configurations commanding mid-market positioning.
- Cloud-Based:Multi-tenant SaaS delivery with automatic updates and elastic scaling. Indonesian pharmaceutical distributors favor this model for rapid rollout without capital expenditure, though data residency concerns under pending localization rules create procurement friction.
- Hybrid:Local data storage with cloud synchronization for specific workflows. European pharmaceutical field forces adopt this architecture to satisfy GDPR Article 44 cross-border transfer restrictions while maintaining remote accessibility.
- On-Premise:Self-managed server infrastructure behind corporate firewalls.
- Managed Service:Vendor-operated dedicated instances with custom SLAs.
Volume leadership belongs to Cloud-Based deployment. Steepest expansion trajectory is occurring in Hybrid configurations.
End User:
Customer scale determines feature complexity, with mid-sized buyers driving unbundled procurement patterns.
- SMEs:Organizations with under 500 employees requiring rapid deployment. Indian pharmaceutical wholesalers in Gujarat and Maharashtra states represent concentrated demand as PLI scheme incentives accelerate digitization.
- Large Enterprises:Global organizations with complex integration requirements. German automotive field sales teams demand FedRAMP-equivalent certifications and SAP backend synchronization, extending implementation timelines.
- Freelancers:Individual contractors managing personal client relationships.
- Non-Profits:Donor management and volunteer coordination use cases.
Established adoption centers on Large Enterprises. Emerging demand is clustering among SMEs.
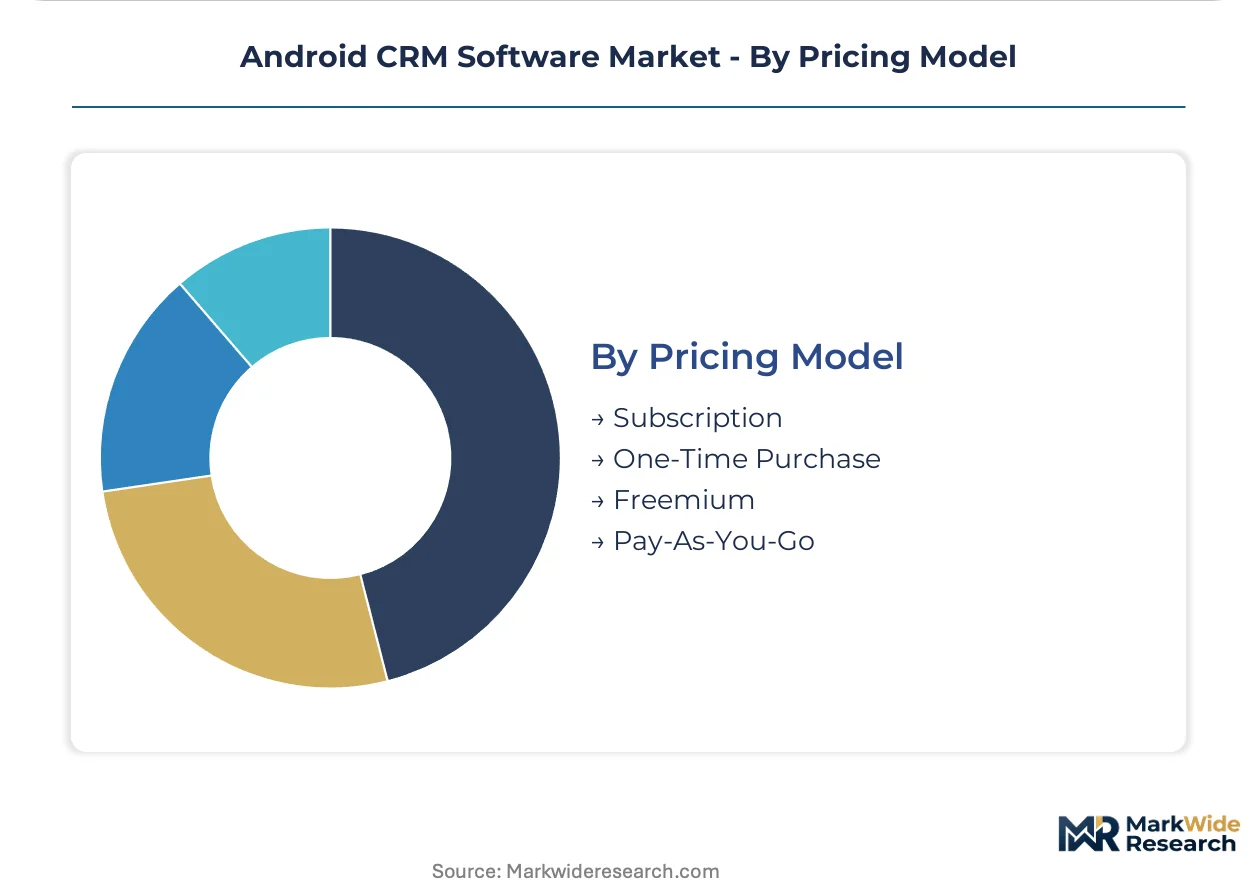
Pricing Model:
Procurement flexibility separates commitment-averse buyers from those seeking long-term cost predictability.
- Subscription:Recurring monthly or annual licenses with tiered feature access. Brazilian and Indonesian distributors prefer this structure for cash flow alignment with seasonal pharmaceutical sales cycles.
- Freemium:Base functionality at no cost with premium upgrades. Indian SME pharmaceutical wholesalers leverage free tiers for initial field force trials before committing to paid synchronization features.
- One-Time Purchase:Perpetual licenses with maintenance contracts.
- Pay-As-You-Go:Usage-based billing tied to API calls or storage consumption.
Revenue concentration rests with Subscription models. Fastest share gains are occurring in Freemium structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering concentrates in the United States and Germany where enterprise SaaS platforms originate, while consumption clusters in India, Brazil, and Indonesia where field sales digitization accelerates fastest. This production-consumption divide shapes localization requirements and compliance engineering priorities.
United States
Enterprise pharmaceutical distributors and medical device field forces drive demand for consent-auditable CRM systems. State-level data privacy laws in California and Virginia reshape product requirements for cross-border data handling. Boston and San Francisco metropolitan areas host the highest concentration of vendor R&D operations serving healthcare verticals.
Germany
Automotive field sales teams and industrial equipment distributors require FedRAMP-equivalent certifications and SAP backend synchronization. The EU AI Act and GDPR Article 22 impose algorithmic transparency mandates on automated lead-scoring modules. Stuttgart and Munich industrial clusters lead adoption of hybrid deployment architectures for local data residency compliance.
India
Pharmaceutical wholesalers in Gujarat and Maharashtra states represent concentrated SME demand as PLI scheme incentives accelerate digitization. The Digital Personal Data Protection Act adds consent-layer complexity for vendors serving this segment. Bangalore and Hyderabad technology corridors host regional development centers customizing offline-first architectures for bandwidth-variable territories.
Brazil
Medical device distributors require GPS-tagged customer interaction records for ANVISA audit compliance. Seasonal pharmaceutical sales cycles align procurement preferences with subscription pricing models for cash flow management. São Paulo and Rio de Janeiro metropolitan areas concentrate field force deployment and vendor implementation partnerships.
Indonesia
Less than 12% of pharmaceutical distributors currently deploy mobile CRM, creating whitespace for verticalized field service solutions. Pending data localization rules under national privacy frameworks create procurement friction for cloud-based deployments. Jakarta and Surabaya distribution hubs drive pilot adoption of freemium-tier products before enterprise commitment.
Android CRM Software Market Competitive Landscape
The competitive structure tilts toward platform ecosystems with deep integration capabilities. Consolidation pressure intensifies as mid-market buyers fragment procurement across specialized point solutions. Three archetypes dominate: enterprise suite vendors with AppExchange marketplaces, integrated business software providers bundling finance and HR modules, and inbound marketing specialists with mobile-native interfaces. M&A activity targets offline-sync technology assets, while strategic partnerships with ERP vendors compress implementation timelines.
Within the enterprise platform tier, Salesforce and Microsoft anchor ecosystem-centric positioning through marketplace strategies and productivity suite bundling. Zoho exemplifies the integrated business software archetype with cross-functional module expansion. HubSpot occupies the marketing-automation-native position with mobile interface specialization. These three patterns represent the dominant competitive vectors reshaping vendor wallet share and platform stickiness metrics.
| Leading Market Players |
|---|
| Salesforce |
| Zoho CRM |
| HubSpot |
| Pipedrive |
| SugarCRM |
| Microsoft Dynamics 365 |
| Insightly |
| Freshsales |
| Agile CRM |
| Others |
Pricing and Supply Chain Analysis
Android CRM engineering talent pools in Bangalore and Hyderabad generate labor-cost differentials that widen pricing-tier spreads between premium enterprise suites and freemium entry points for Indian SME pharmaceutical distributors.
Pricing Analysis
Margin tightening in mid-market tiers reflects API rate limiting costs consuming 15-25% of platform operating budgets for vendors integrating third-party mapping and telephony services. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-certified enterprise deployments from self-serve cloud subscriptions and freemium trials with paywalled offline sync. Price differentiation hinges on certification grade and after-sales implementation support. Indian pharmaceutical wholesalers exhibit highest price sensitivity, while German automotive field sales teams prioritize compliance-grade premiums over cost.
Supply Chain Analysis
Freight cost escalation for edge computing hardware shipments from Taiwan and South Korea is compressing margins for vendors deploying on-device AI inference modules to bandwidth-constrained territories. Software development centers concentrate in the United States, Germany, and India, with cloud infrastructure provisioning anchored in AWS, Azure, and Google Cloud regional zones. Raw material dependencies span semiconductor chips, GPS modules, and encryption processors. Single-source vulnerability sits with Qualcomm Snapdragon dominance in Android handset chipsets. Distribution runs through direct vendor sales teams, systems integrators, and mobile device management partners serving pharmaceutical field forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue backward integration into offline-sync technology assets to compress implementation timelines and reduce third-party API dependency.
For Market Incumbents: Deepen ERP vendor partnerships with SAP and Oracle to collapse 6-9 month integration timelines that currently freeze mobile rollout ROI realization. Fortify algorithmic transparency modules for EU AI Act compliance to defend against emerging point-solution challengers in European pharmaceutical field forces. Prioritize certification investment in FedRAMP and ISO 27001 to unblock public sector procurement cycles extending 14-18 months. For New Entrants and Emerging Players: Begin with Indonesia's pharmaceutical distribution whitespace where less than 12% penetration creates immediate addressable market for verticalized field service solutions. Target Brazilian medical device distributors requiring GPS-tagged resolution records for ANVISA audit compliance as the most penetrable segment. Lead with freemium-to-premium conversion mechanics proven in Indian SME trials. For Investors and Strategic Acquirers: Re-rating potential sits with offline-sync technology specialists given edge computing integration accelerating across bandwidth-variable pharmaceutical territories. Long-term viability favors vendors with pre-built GDPR and EU AI Act compliance architectures over pure feature-play competitors. Watch 5G standalone network slicing adoption among German automotive field sales teams as inflection signal for premium service tier willingness-to-pay.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens SAP and Oracle backend synchronization to collapse implementation timelines for enterprise pharmaceutical distributors. |
| Acquisition of Specialist Firm | Captures offline-sync technology assets that reduce cloud dependency for sales teams in rural Indian territories. |
| Strategic Partnership | Aligns with 5G network operators to deliver guaranteed quality-of-service lanes for CRM data sync in German automotive. |
| Geographic Expansion | Targets Indonesian pharmaceutical distributors with verticalized field service solutions in underpenetrated distribution hubs. |
| Product Launch | Deploys explainable AI lead-scoring modules pre-certified for EU AI Act algorithmic transparency mandates. |
Research Methodology
Document review covered SEC filings of publicly traded CRM vendors, hyperscaler capex disclosures, and pharmaceutical regulatory guidance documents, complemented by interviews with CTOs at mid-market SaaS providers, IT procurement officers at German automotive distributors, and integration specialists serving Indian pharmaceutical wholesalers. Secondary validation drew from App Annie mobile adoption metrics, GPO contracts for healthcare technology procurement, and CMS Medicare data on field force digitization incentives. Bottom-up sizing of vendor revenue streams and top-down macroeconomic calibration ensured triangulation integrity.
Cross-referencing historical adoption curves against panel input from platform engineers and channel partners anchored projections across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs were derived from slope analysis of mobile-first adoption inflection points and pharmaceutical compliance mandate timelines. Industry-specific inputs encompassed FDA promotional material retention protocols and India's Digital Personal Data Protection Act consent-layer requirements.
Underlying measurement precision varies by segment; cloud-based deployment figures carry tighter precision than hybrid configurations where data residency fragmentation complicates vendor reporting. Forecasts reflect assumptions around 5G rollout pace, regulatory enforcement intensity, and ERP vendor partnership expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
CRM Analytics Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Customer Communication Management Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Online CRM Software Market