
 Loyalty Management Solutions Market | 2026-2036
Loyalty Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Loyalty Management Solutions Market Analytics
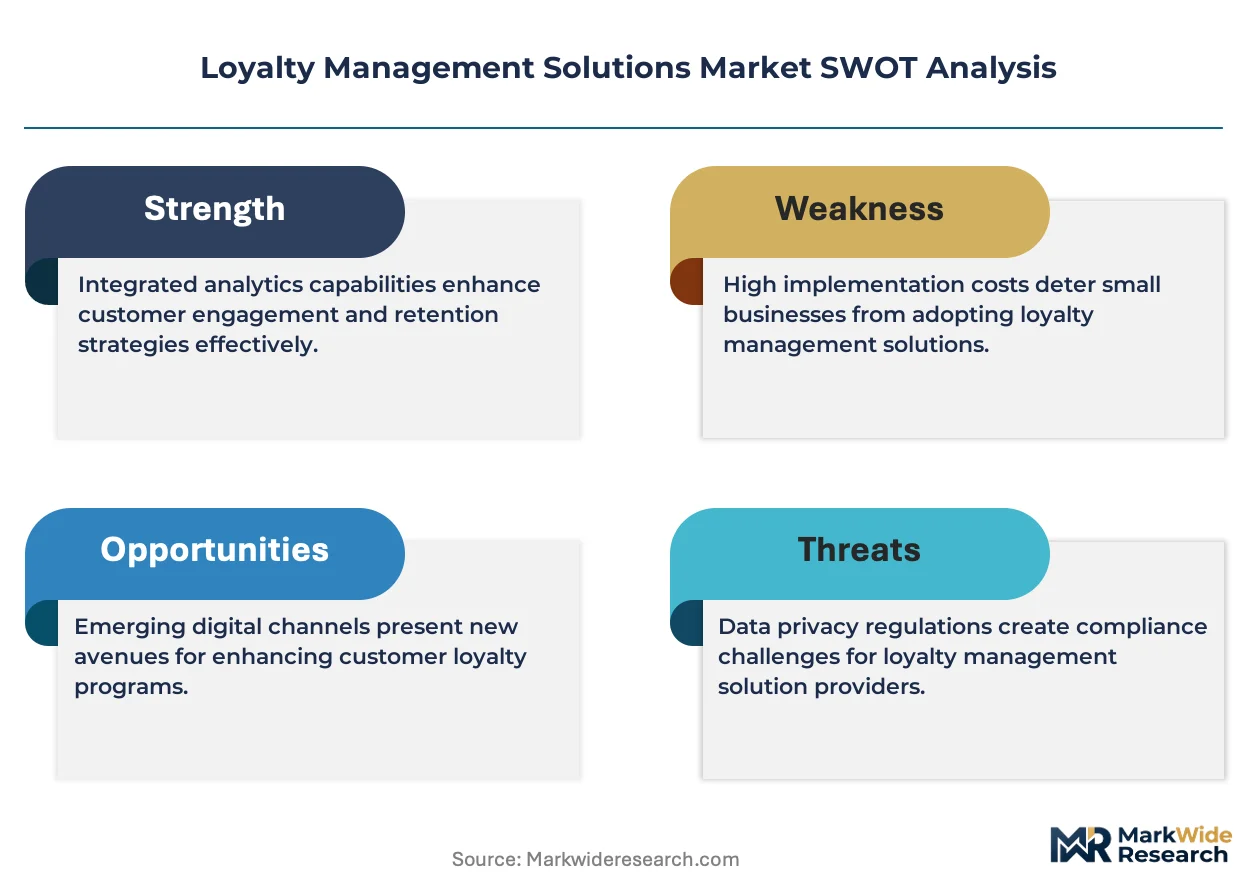
ISO 27001 certification is unwinding the competitive landscape for loyalty platform vendors, forcing mid-tier providers to absorb compliance costs or exit enterprise procurement cycles. Salesforce, Inc. leverages its CRM data fabric to embed loyalty logic directly into commerce workflows. Oracle Corporation anchors its position through database-tier integration that reduces latency for real-time points reconciliation. SAP SE competes by extending ERP-native loyalty modules that minimize custom integration overhead for manufacturing conglomerates.
Loyalty management solutions constitute software platforms that orchestrate customer retention programs through programmable rules engines, real-time points ledgers, and omnichannel redemption APIs, typically processing sub-second transaction validation across POS, mobile, and web endpoints. Cloud-based deployments capture the fastest expansion as retailers abandon on-premise hardware commitments in favor of elastic consumption models. Enterprise-grade B2C implementations dominate margin pools, while SMB-oriented tiered systems encounter price compression from self-service entrants.
GDPR in Europe, the CCPA in California, and PCI-DSS globally impose data residency and encryption mandates that inflate platform architecture costs while disqualifying non-compliant vendors from regulated sectors. India's Digital Personal Data Protection Act and Brazil's LGPD are replicating this pattern, fragmenting vendor certification requirements across jurisdictions. Stakeholders must evaluate whether regional compliance investments justify market entry against the revenue yield from localized program deployments.
Market Dynamics
API-first architectures are dismantling legacy monolithic loyalty stacks, forcing vendors to rearchitect around real-time data fabrics or lose enterprise procurement cycles to cloud-native competitors.
Growth Catalysts
- GDPR Article 17 (Right to Erasure):European retailers are investing in compliant loyalty data architectures, expanding addressable market for certified platform vendors.
- POS-mobile-web convergence:Unified redemption APIs enable seamless points validation across physical and digital touchpoints, accelerating retailer platform upgrades.
- United States enterprise SaaS procurement:Fortune 500 customer engagement budgets are climbing, pulling loyalty management spend into consolidated martech stacks.
Market Restraints
- ISO 27001 certification costs:Mid-tier vendors absorb six-figure compliance investments or exit regulated verticals, compressing competitive field.
- Cloud infrastructure concentration:AWS, Azure, and GCP dominance creates vendor lock-in risk and inflates ongoing platform operating costs.
- Real-time latency requirements:Sub-second points reconciliation across distributed ledgers strains legacy database architectures, forcing expensive rewrites.
Strategic Opportunities
- India's Digital Personal Data Protection Act:Localized data residency mandates create first-mover advantage for vendors building India-specific compliance frameworks.
- Embedded finance convergence:Loyalty points linked to payment rails and BNPL services unlock new monetization streams for platform operators.
- SMB self-service tier:Low-code program builders address price-sensitive merchants underserved by enterprise-focused implementations.
Industry Challenges
- API integration complexity:Legacy ERP and POS systems require custom middleware development, extending deployment timelines and inflating professional services costs.
- Cross-border data fragmentation:Brazil's LGPD, India's DPDPA, and California's CCPA impose conflicting residency rules, multiplying architecture complexity for multinational deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loyalty Management Solutions Market |
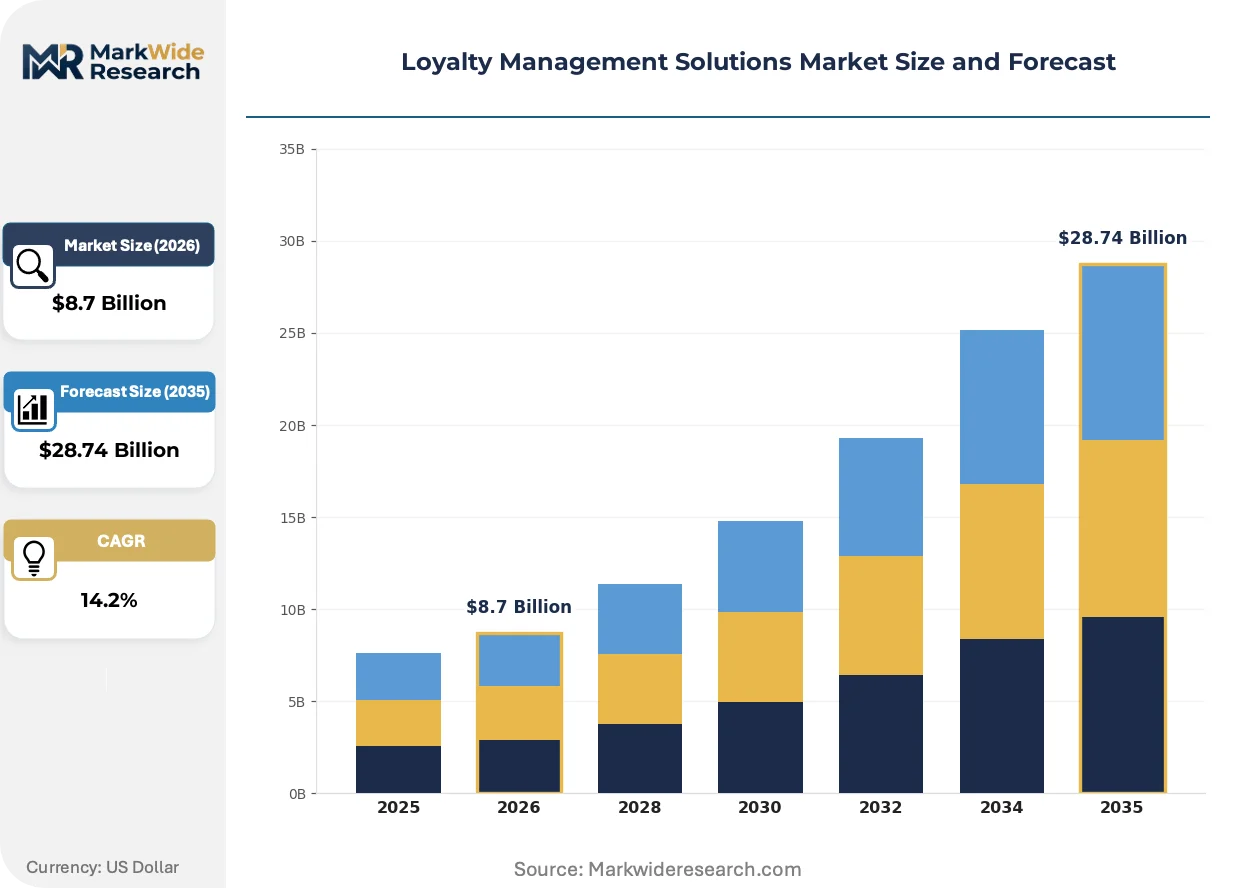
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Points-Based, Tiered Systems, Cashback, Coupons Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Retail, Hospitality, E-Commerce, Entertainment Customer Type: B2C, B2B, SMBs, Enterprises |
| Companies Covered | Salesforce, Inc., Oracle Corporation, SAP SE, Capillary Technologies, Comarch SA, Fiserv, Inc., Kobie Marketing, LLC, Bond Brand Loyalty, L.P., Antavo Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loyalty Management Solutions Market Evolving Landscape
Real-time personalization engines and blockchain-anchored points ledgers are redefining how retailers orchestrate retention economics, compressing the gap between transaction and reward recognition.
Edge computing nodes deployed at retail locations are miniaturizing loyalty validation logic, pushing sub-second points reconciliation closer to the point of sale. Grocery and convenience chains in Germany and Japan are piloting these distributed architectures to reduce cloud round-trip latency. The technology is miniaturizing the traditional centralized loyalty stack into localized processing units that operate independently during connectivity outages.
California's CCPA amendments tightening data broker definitions are forcing loyalty platforms to reclassify points-as-currency transactions under stricter disclosure regimes. Retailers operating cross-border programs must now segment California resident data flows or face per-violation penalties. Beauty and wellness brands with subscription loyalty tiers are responding by building state-specific consent management layers.
Buyer procurement committees are consolidating martech vendor relationships, folding standalone loyalty contracts into broader customer data platform agreements. Mid-market retailers are displacing point-solution vendors with suite players offering bundled CDP-plus-loyalty pricing. This concentration is most visible in United States retail chains undergoing post-pandemic vendor base rationalization.
Loyalty Management Solutions Market Segmentation
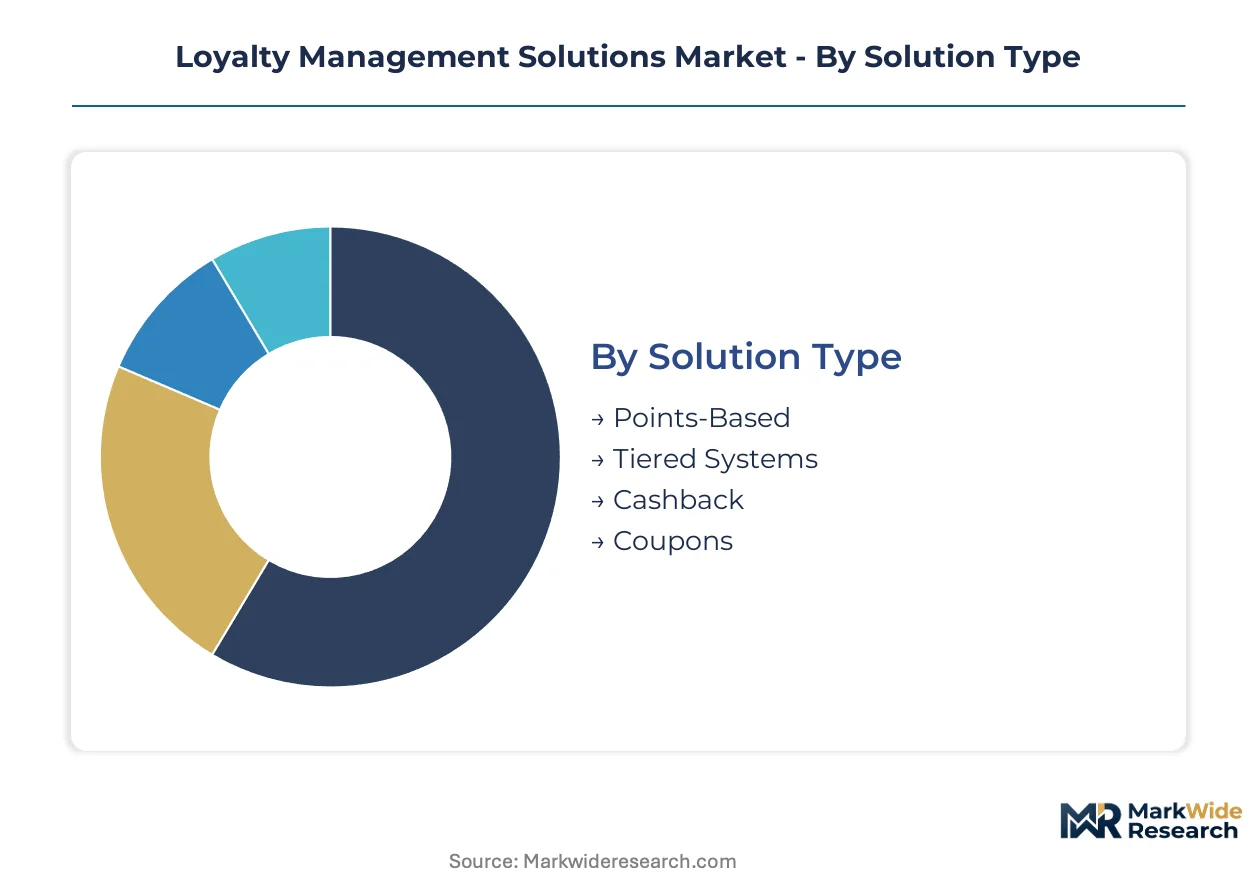
Loyalty management solutions fragment across four structural dimensions that determine procurement patterns and margin capture. Solution type dictates program mechanics, deployment model shapes total cost of ownership, end user verticals impose compliance and integration requirements, and customer type governs pricing elasticity and sales cycle length.
Solution Type:
Channel mix varies sharply by solution type, with points-based and tiered systems flowing through enterprise SaaS marketplaces while cashback and coupon modules distribute via payment processor integrations and affiliate networks.
- Points-Based:Programmable rules engines assign redeemable credits per transaction value, with ledgers reconciling across POS, mobile, and web endpoints in sub-second validation cycles. Demand concentrates in United States grocery and pharmacy chains where frequency-based accumulation drives repeat visits, though GDPR Article 17 erasure mandates inflate data architecture costs for European deployments.
- Tiered Systems:Status hierarchies unlock escalating benefits based on cumulative spend or engagement thresholds, requiring real-time progression tracking and dynamic entitlement management. Hospitality brands in Dubai and Singapore deploy these to capture high-net-worth traveler wallets, with property management system integrations representing the primary procurement constraint.
- Cashback:Direct monetary rebates settle to payment instruments or statement credits, minimizing consumer cognitive load but compressing merchant margins. Fintech-issued cards in Brazil and Mexico embed these natively.
- Coupons:Single-use or limited-duration discounts distributed through SMS, email, or app push notifications, with redemption validation against purchase receipts. Quick-service restaurants in India leverage these for demand smoothing.
Points-based solutions dominate installed base across legacy retail footprints. Tiered systems are where expansion concentrates as hospitality and luxury verticals prioritize status differentiation over transactional discounts.
Deployment Model:
Cost tier stratification governs deployment selection, with on-premise carrying capital intensity and cloud-based shifting to operational expenditure with elastic scaling.
- On-Premise:Hardware and software licenses deployed within client data centers, delivering data sovereignty and sub-millisecond latency for high-transaction-volume retailers. Japanese convenience chains and German automotive dealerships retain these for legacy ERP co-location.
- Cloud-Based:Multi-tenant SaaS architectures with API-first integration patterns, capturing the steepest expansion trajectory as North American and European retailers abandon depreciation schedules for consumption-based pricing. AWS, Azure, and GCP concentration creates vendor lock-in risk.
- Hybrid:Sensitive data resides on-premise while engagement layers operate in cloud, addressing India's DPDPA and Brazil's LGPD residency mandates without full infrastructure replication.
- Managed Services:Third-party operations of loyalty infrastructure, including program design, member support, and fraud monitoring. French luxury houses outsource tier management to preserve brand focus.
On-premise retains share in regulated verticals requiring air-gapped data. Cloud-based deployments are climbing the fastest as procurement committees consolidate martech vendor relationships.
End User:
Application-specific requirements fragment vendor selection, with retail prioritizing POS convergence, hospitality demanding property management integration, e-commerce requiring real-time personalization, and entertainment seeking ticket-linked redemption.
- Retail:Unified commerce platforms spanning brick-and-mortar, mobile app, and web storefronts, with inventory-aware redemption and returns handling. United States department stores and European grocery cooperatives represent the largest addressable spend pools.
- Hospitality:Guest recognition systems interfacing with property management, spa booking, and food and beverage outlets, with folio-based earning and burning. Maldives resort operators and Dubai hotel groups drive premium pricing.
- E-Commerce:Browser and app-based programs with machine learning-driven offer personalization, A/B testing infrastructure, and cart abandonment triggers. Direct-to-consumer beauty brands in California build state-specific consent layers under CCPA amendments.
- Entertainment:Venue-access and merchandise-linked benefits, with season ticket holder retention and dynamic pricing integration. Sports franchises in the United Kingdom and cinema chains in South Korea deploy these.
Retail commands the largest current spend. E-commerce is gaining share fastest as digital-native merchants displace point-solution vendors with bundled CDP-plus-loyalty procurement.
Customer Type:
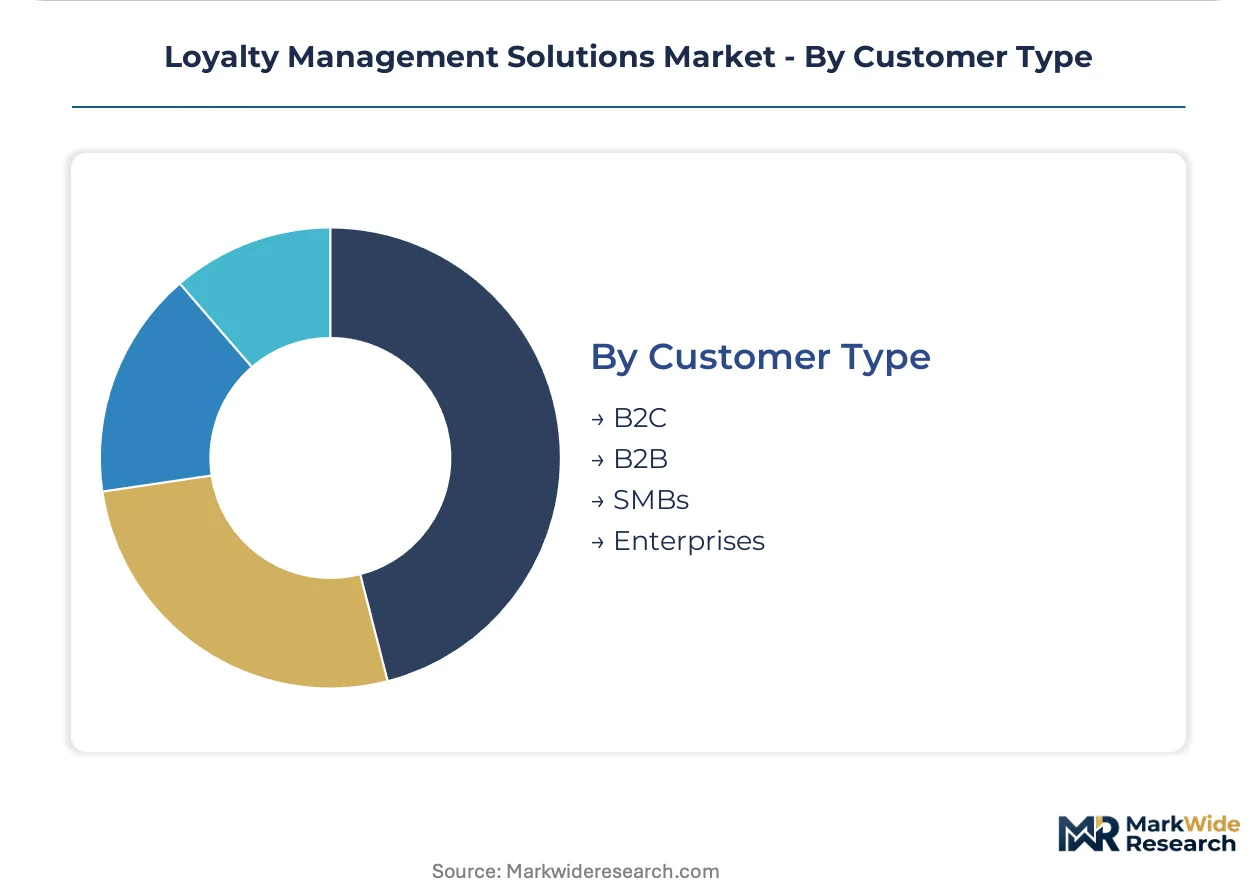
Volume and margin profiles diverge by customer scale, with enterprises demanding customization and professional services while SMBs accept standardized self-service tiers.
- B2C:Mass-market programs targeting individual consumers with demographic and behavioral segmentation, representing the deepest margin pools due to scale economics. Fortune 500 customer engagement budgets in the United States pull loyalty spend into consolidated stacks.
- B2B:Channel partner and procurement officer incentives with account-based progression, contract-value-linked rewards, and sales enablement tool integration. Industrial distributors in Germany and software marketplaces in the United States adopt these.
- SMBs:Low-code program builders with template-based rules configuration and limited integration depth, encountering price compression from self-service entrants. Indian kirana stores and Mexican corner shops represent underpenetrated demand.
- Enterprises:Custom-developed modules with dedicated account management, SLA guarantees, and multi-region compliance certification. ISO 27001 mandates force mid-tier vendors to absorb six-figure investments or exit these procurement cycles.
B2C programs dominate current revenue. SMB self-service tiers are where expansion concentrates as price-sensitive merchants seek alternatives to enterprise-focused implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise SaaS procurement committees in the United States, Germany, and India are accelerating loyalty platform deployments to retain digitally native consumers. Cloud infrastructure migration and API-first architectures are dismantling legacy monolithic systems across these markets. Regulatory fragmentation around data residency is forcing vendors to build jurisdiction-specific compliance frameworks.
United States
Fortune 500 customer engagement budgets are climbing, pulling loyalty management spend into consolidated martech stacks. The FTC and state-level CCPA amendments tighten data broker definitions, forcing platforms to reclassify points-as-currency transactions. California beauty brands build state-specific consent management layers for subscription loyalty tiers.
Germany
Grocery and convenience chains are piloting edge computing nodes to miniaturize loyalty validation logic at retail locations. GDPR Article 17 erasure mandates inflate data architecture costs for European deployments. Automotive dealerships in Bavaria retain on-premise systems for legacy ERP co-location and sub-millisecond latency.
India
Quick-service restaurants leverage coupon-based programs for demand smoothing across price-sensitive merchant segments. The Digital Personal Data Protection Act imposes localized data residency mandates, creating first-mover advantage for vendors building India-specific compliance frameworks. Kirana stores in Maharashtra represent underpenetrated SMB demand for low-code program builders.
Brazil
Fintech-issued cards embed native cashback programs, minimizing consumer cognitive load while compressing merchant margins. LGPD data residency rules multiply architecture complexity for multinational deployments. Industrial distributors in São Paulo adopt B2B channel partner incentives with account-based progression systems.
United Arab Emirates
Hospitality brands in Dubai deploy tiered status hierarchies to capture high-net-worth traveler wallets, with property management system integrations representing the primary procurement constraint. MOHAP data governance frameworks influence platform selection in healthcare-adjacent retail. Luxury houses outsource tier management to preserve brand focus.
Loyalty Management Solutions Market Competitive Landscape
Player mix skews toward enterprise software conglomerates with adjacent CRM and ERP data fabrics. Mid-tier specialists face compression from self-service entrants and compliance cost absorption. Three archetypes dominate: cloud-native platform vendors, legacy database-integrated suite players, and vertical-focused loyalty pure-plays. Consolidation pressures are forcing M&A activity and API-first rearchitecture investments.
Within the enterprise suite tier, Salesforce, Inc., Oracle Corporation, and SAP SE anchor competitive positioning through embedded loyalty logic. Salesforce leverages CRM data fabric integration, Oracle anchors through database-tier latency reduction, and SAP extends ERP-native modules for manufacturing conglomerates. These three exemplify how adjacent platform dominance translates into loyalty market leverage without standalone point-solution dependency.
| Leading Market Players |
|---|
| Salesforce, Inc. |
| Oracle Corporation |
| SAP SE |
| Capillary Technologies |
| Comarch SA |
| Fiserv, Inc. |
| Kobie Marketing, LLC |
| Bond Brand Loyalty, L.P. |
| Antavo Limited |
| Others |
Value Network & Pricing Analysis
Elastic cloud consumption models concentrate procurement power among hyperscaler-aligned vendors, compressing price floors for mid-tier loyalty platform providers while elevating margins for ISO 27001-certified incumbents with enterprise SaaS marketplace presence. Scale economies in API-first architecture development simultaneously reward concentrated R&D investment and punish fragmented point-solution vendors.
Pricing Analysis
Cost-plus contracts with AWS Reserved Instance indexation anchor enterprise deployments, though consumption-based SaaS tiers increasingly displace fixed licensing. Price differentiation rests on ISO 27001 certification tier and real-time personalization engine depth. Cost compression in SMB self-service tiers intensifies because low-code entrants undercut professional services bundles. Fortune 500 procurement committees exhibit lowest price sensitivity; Indian kirana stores and Mexican corner shops represent highest.
Supply Chain Analysis
Strait of Malacca fiber cable transit underwrites sub-second latency guarantees for Asia-Pacific loyalty validation nodes. Platform development concentrates in the United States, Germany, and India. Raw material dependencies span GPU clusters for machine learning personalization, blockchain node infrastructure for points ledger integrity, and edge computing hardware for retail location deployment. Single-source vulnerability concentrates in AWS, Azure, and GCP compute allocation. Distribution runs through enterprise SaaS marketplaces and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architecture expertise scarcity defines competitive moats in this market, with vendors possessing real-time data fabric engineering capabilities commanding premium positioning against legacy rearchitecture laggards.
For Market Incumbents: Fortify database-tier integration advantages through ERP-native module deepening, particularly for SAP SE's manufacturing conglomerate footprint. Absorb ISO 27001 certification costs to disqualify mid-tier competitors from regulated vertical procurement cycles. Cloud-native platform vendors with CRM data fabric integration represent the primary substitution threat. For New Entrants and Emerging Players: India's DPDPA certification fast-track offers first-mover positioning in localized data residency compliance. Target underpenetrated SMB self-service demand in Maharashtra kirana stores and São Paulo industrial distributor segments. Embed loyalty logic directly into payment processor integrations as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical-focused loyalty pure-plays with hospitality or retail sector depth over horizontal suite players. Long-term viability hinges on embedded finance convergence readiness. Watch for CCPA amendment enforcement patterns as the signal indicating regulatory-driven vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Investment | Unlocks Fortune 500 procurement cycles previously closed to non-compliant vendors. |
| Edge Computing Node Deployment | Reduces cloud round-trip latency for German grocery and Japanese convenience chains. |
| Payment Rail Integration | Captures cashback monetization streams from Brazil and Mexico fintech-issued cards. |
| India-Specific Compliance Framework | Addresses DPDPA data residency mandates before multinational competitors localize. |
| CDP-Plus-Loyalty Bundle Launch | Displaces point-solution vendors in United States post-pandemic vendor rationalization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with loyalty platform CTOs, enterprise IT procurement officers, retail systems integrators, and hospitality property management system vendors. Secondary validation drew from SEC 10-K SaaS revenue disclosures, hyperscaler capex reports, GDPR enforcement action databases, and ISO certification registries. Bottom-up deployment estimates and top-down enterprise SaaS spend allocation were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled solution type, deployment model, end-user vertical, and customer type segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves and professional services revenue mix trajectories. Real-time personalization engine penetration rates and embedded finance partnership velocity served as industry-specific forecast inputs.
Underlying assumptions cover sustained cloud migration momentum and regulatory fragmentation persistence, with deviation risk concentrated in GDPR Article 17 enforcement intensity and CCPA amendment interpretation shifts. Practitioners should keep alternative scenarios live as data residency mandate proliferation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Online CRM Software Market
Customer Relationship Management (CRM)
US Customer Relationship Management Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market