
 Healthcare CRM Market | 2026-2036
Healthcare CRM Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare CRM Market Intelligence
Healthcare IT talent scarcity is bifurcating the competitive landscape into vendors with captive engineering depth and those dependent on contracted implementation partners. Salesforce leverages its native cloud architecture to sustain dominance in enterprise health system deployments. Oracle anchors its position through deep electronic health record integration and database infrastructure control. SAP competes on workflow automation breadth that extends across payer and provider operations.
Healthcare CRM denotes software systems engineered to manage patient relationships, clinical communications, and care coordination workflows through centralized data repositories with HL7 FHIR interoperability protocols. These platforms orchestrate appointment scheduling, population health outreach, and revenue cycle touchpoints across ambulatory and acute settings. Cloud-based solutions lead deployment preferences as hospitals prioritize elastic infrastructure over capital-intensive on-premise installations. Artificial Intelligence segments within technology architecture show the fastest expansion trajectory, though workflow automation retains the deepest installed base and recurring revenue pools. Mobile solutions remain nascent outside physician practices, where point-of-care access drives differentiated utility.
US FDA interoperability mandates under the 21st Century Cures Act compel CRM vendors to certify FHIR-compliant data exchange, while HIPAA privacy frameworks constrain cross-platform patient data orchestration. The EU AI Act imposes risk-classification requirements on clinical decision-support algorithms embedded within European deployments. Stakeholders must weigh regulatory certification timelines against the pace of AI feature rollouts when selecting vendor roadmaps.
Market Dynamics
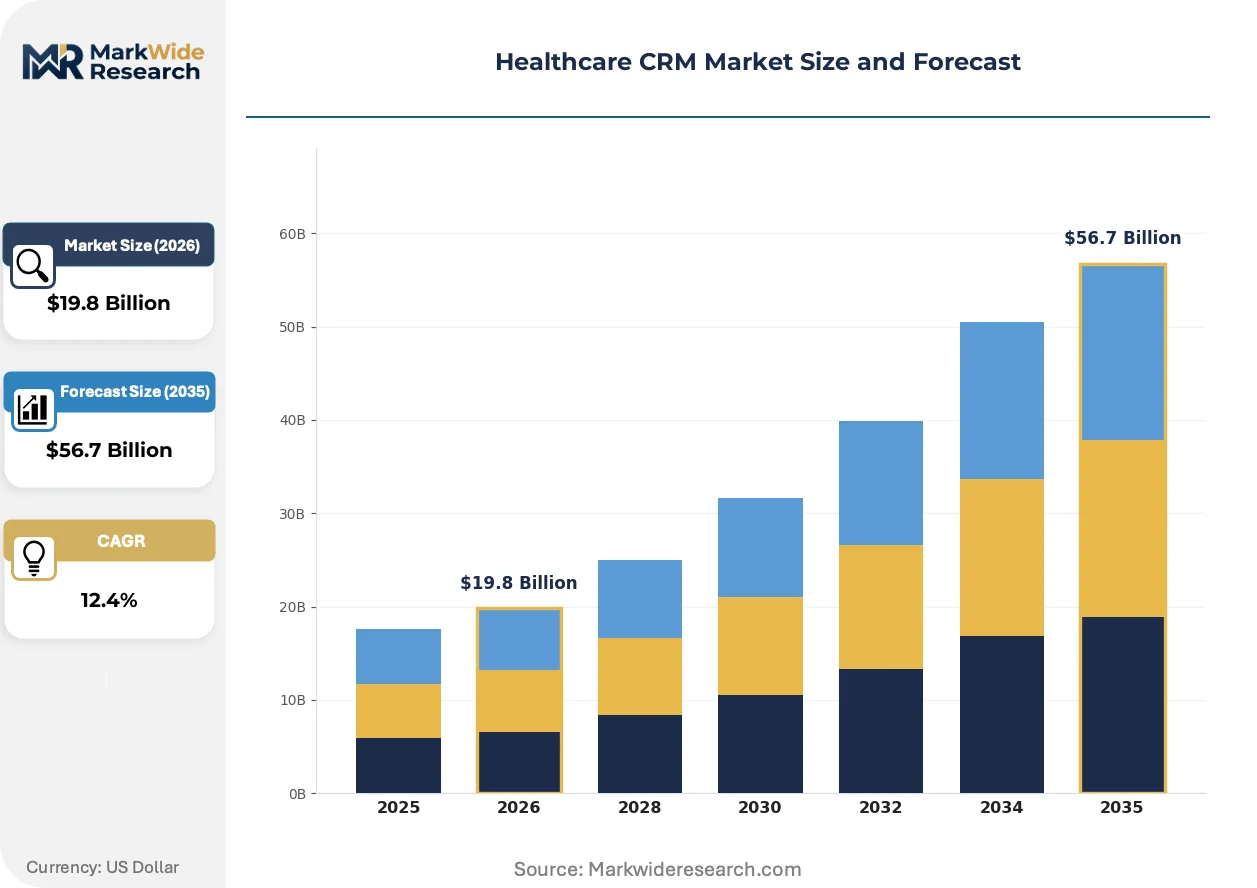
The US FDA's 21st Century Cures Act interoperability mandates are compressing vendor certification timelines while cloud migration accelerates across acute care settings. This regulatory-technological convergence is restructuring competitive advantage around FHIR-compliant data architectures.
Growth Catalysts
- Interoperability Mandates:The US FDA's 21st Century Cures Act compels health systems to deploy FHIR-certified platforms, forcing replacement cycles for legacy patient management infrastructure.
- Cloud Elasticity:Hospitals prioritize subscription-based deployment models that eliminate capital-intensive on-premise server maintenance and enable rapid scaling during patient volume surges.
- Population Health Management:Accountable care organizations require integrated outreach tools for chronic disease cohorts, driving demand for centralized engagement platforms.
Market Restraints
- HIPAA Compliance Friction:Privacy framework constraints on cross-platform patient data orchestration limit vendor ability to offer seamless multi-system integrations.
- Engineering Talent Scarcity:Healthcare IT specialization gaps bifurcate the vendor landscape between those with captive development teams and implementation-dependent competitors.
- Legacy System Entrenchment:Deep electronic health record integration requirements create switching costs that slow replacement cycles in established health systems.
Strategic Opportunities
- AI-Enabled Clinical Decision Support:The EU AI Act's risk-classification framework creates first-mover advantage for vendors certifying algorithmic care coordination tools in European deployments.
- Mobile Point-of-Care Access:Physician practices outside hospital systems represent underpenetrated territory where smartphone-based engagement tools deliver differentiated workflow utility.
- Revenue Cycle Integration:Payer-provider convergence creates whitespace for platforms unifying patient financial touchpoints with clinical communication workflows.
Industry Challenges
- FHIR Certification Complexity:Vendors face compressed development cycles to achieve interoperability compliance while maintaining feature parity with non-certified competitors.
- Data Migration Execution:Health system consolidation creates massive patient record transfer requirements that strain implementation bandwidth and prolong deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare CRM Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $56.7 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-premise Solutions, Cloud-based Solutions, Hybrid Solutions, Mobile Solutions End User: Hospitals, Clinics, Physician Practices, Nursing Homes Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-premise Technology: Artificial Intelligence, Machine Learning, Data Analytics, Workflow Automation |
| Companies Covered | Salesforce, Oracle, IBM, SAP, Microsoft, Veeva Systems, Accenture, Zoho Corporation, hc1, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare CRM Market Strategic Shifts & Innovations
Artificial intelligence architectures are penetrating care coordination workflows while regulatory pressure intensifies around algorithmic transparency. These forces are compressing vendor roadmaps and reshaping buyer evaluation criteria.
Generative AI is supplanting rule-based patient outreach automation in enterprise health system deployments. Large language models now power appointment scheduling, medication adherence prompts, and post-discharge follow-up sequences. Academic medical centers in the United States are piloting these tools at accelerated procurement cycles, compressing traditional eighteen-month vendor selection processes.
The EU AI Act imposes risk-classification requirements on clinical decision-support algorithms embedded within European CRM deployments. High-risk designations trigger conformity assessment obligations that extend certification timelines by twelve to eighteen months. Vendors targeting German and French health systems are restructuring product architectures to segregate algorithmic components from core workflow automation.
Health system procurement teams are consolidating vendor relationships around platforms offering unified patient engagement, revenue cycle, and population health modules. Standalone point solutions face displacement as integrated suites capture expanded share of IT budgets. This concentration is most visible in United States metropolitan markets where large delivery networks centralize purchasing authority.
Healthcare CRM Market Segmentation
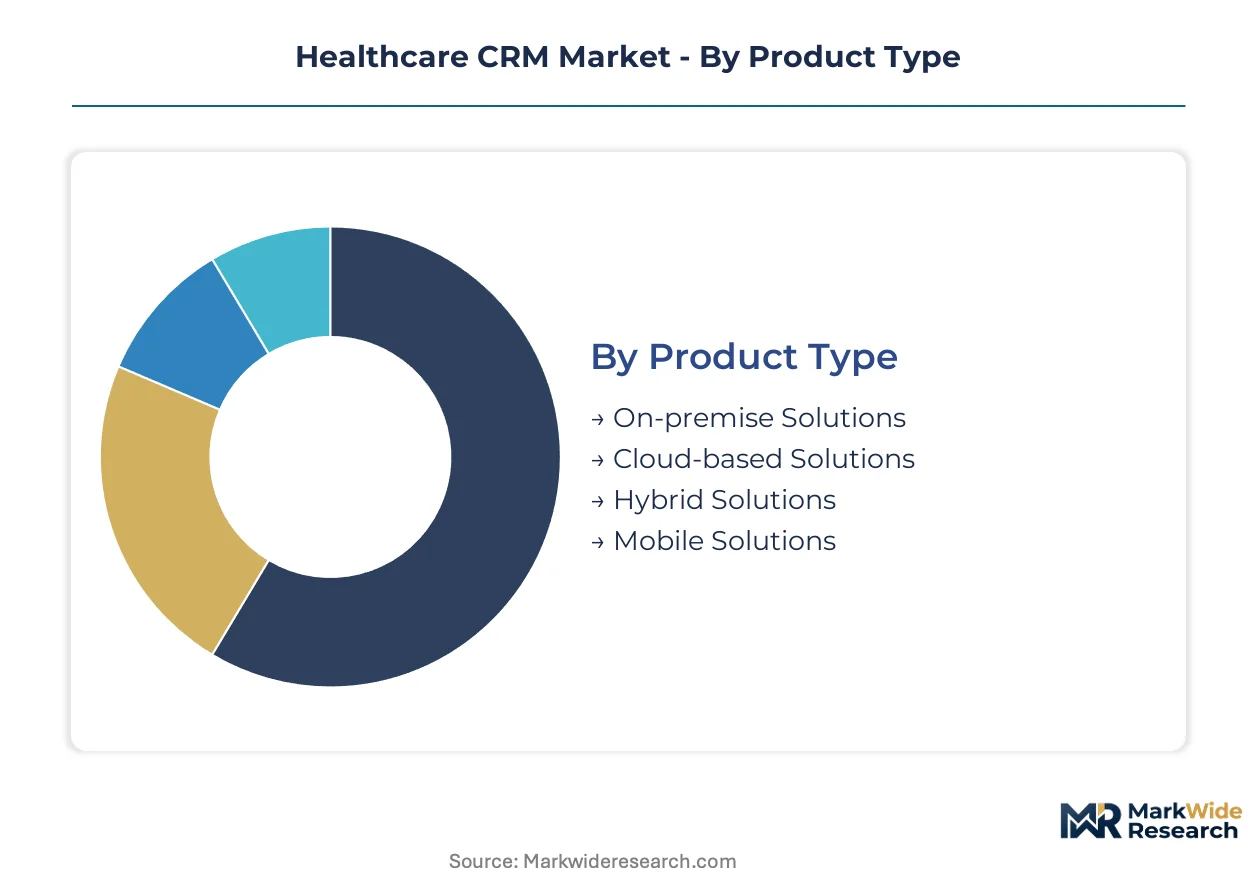
Healthcare CRM segmentation reveals how regulatory mandates and infrastructure preferences reshape procurement patterns across health systems. Vendors must align certification timelines with specific deployment architectures to capture replacement cycles triggered by interoperability requirements.
Product Type:
FDA's 21st Century Cures Act certification requirements differentiate vendor positioning across deployment models, with FHIR compliance timelines varying by infrastructure architecture.
- Cloud-based Solutions:Subscription architectures eliminate capital-intensive server maintenance while enabling elastic scaling during patient volume surges. United States health systems prioritize these platforms as cloud migration outpaces other markets, driven by consolidated purchasing power among large delivery networks.
- On-premise Solutions:Legacy installations retain presence in security-sensitive environments requiring localized data sovereignty controls. Deep electronic health record integration requirements create switching costs that slow replacement cycles in established health systems, constraining vendor displacement efforts.
- Hybrid Solutions:Architectures blending cloud elasticity with on-premise data residency address HIPAA privacy constraints on cross-platform patient data orchestration.
- Mobile Solutions:Smartphone-based platforms remain nascent outside physician practices, where point-of-care access drives differentiated workflow utility.
Established volume favors On-premise Solutions; emerging adoption favors Cloud-based Solutions.
End User:
Customer scale determines feature complexity requirements and implementation bandwidth allocation across the care continuum.
- Hospitals:Enterprise platforms orchestrate appointment scheduling, population health outreach, and revenue cycle touchpoints across ambulatory and acute settings. Academic medical centers in the United States are piloting generative AI tools at accelerated procurement cycles, compressing traditional vendor selection processes.
- Physician Practices:Point solutions prioritize smartphone-based engagement tools and streamlined workflow automation. These settings represent underpenetrated territory where mobile access delivers differentiated utility compared to hospital-centric platforms.
- Clinics:Mid-scale facilities require modular architectures that balance population health management capabilities with constrained IT staffing resources.
- Nursing Homes:Long-term care settings demand specialized care coordination workflows for chronic disease cohorts with extended patient relationship horizons.
Procurement concentration tilts toward Hospitals; Physician Practices offer whitespace for specialized point solutions.
Deployment:
Infrastructure ownership models segment by data control requirements and operational expenditure preferences.
- Public Cloud:Shared infrastructure delivers lowest total cost of ownership for health systems prioritizing rapid deployment over customization depth. Elastic capacity accommodates seasonal patient volume fluctuations without capital reservation.
- Private Cloud:Dedicated tenant environments satisfy HIPAA constraints on cross-platform patient data orchestration while retaining cloud operational benefits. German and French health systems favor these architectures under EU AI Act risk-classification frameworks.
- Hybrid Cloud:Segregated workloads place sensitive patient records in controlled environments while leveraging public infrastructure for non-clinical applications.
- On-premise:Captive infrastructure persists where legacy system entrenchment creates prohibitive data migration execution challenges.
Public Cloud captures expanding share of new deployments; Private Cloud anchors European compliance-sensitive procurements.
Technology:
Algorithmic capabilities differentiate vendor roadmaps against regulatory certification timelines and workflow integration depth.
- Workflow Automation:Rule-based engines retain the deepest installed base and recurring revenue pools across enterprise health system deployments. These platforms anchor current vendor profitability while AI architectures penetrate adjacent workflows.
- Artificial Intelligence:Large language models now power appointment scheduling, medication adherence prompts, and post-discharge follow-up sequences. EU AI Act risk-classification requirements trigger conformity assessment obligations that extend certification timelines for high-risk algorithmic components.
- Machine Learning:Predictive cohort identification tools enable accountable care organizations to target chronic disease interventions with resource-optimized precision.
- Data Analytics:Population health visualization and reporting modules support quality metric reporting for value-based reimbursement contracts.
Workflow Automation sustains current revenue concentration; Artificial Intelligence represents the steepest expansion trajectory across vendor roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems deploy cloud-native patient engagement platforms at accelerated procurement cycles, while European facilities navigate risk-classification frameworks that elongate vendor certification timelines. German and French providers prioritize private cloud architectures for algorithmic care coordination tools. Emerging markets concentrate purchasing among metropolitan hospital networks with constrained IT staffing resources.
United States
Academic medical centers in Boston and the San Francisco Bay Area pilot generative AI appointment scheduling and post-discharge follow-up sequences. The FDA's 21st Century Cures Act interoperability mandates compel FHIR-certified platform replacements across consolidated health systems. Large delivery networks in Texas and the Midwest centralize purchasing authority around unified patient engagement and revenue cycle modules.
Germany
University hospitals in Baden-Württemberg and North Rhine-Westphalia demand segregated algorithmic architectures under EU AI Act high-risk designations. The country's national pharmaceutical regulator requires extended conformity assessments for clinical decision-support tools. Berlin-based health IT clusters restructure product roadmaps to separate AI components from core workflow automation.
France
Public hospital groups in Île-de-France and Auvergne-Rhône-Alpes favor dedicated tenant environments satisfying cross-border data residency requirements. ANSM and CNIL oversight triggers twelve-to-eighteen-month certification extensions for algorithmic care coordination. Lyon and Marseille metropolitan networks concentrate procurement of modular platforms balancing population health capabilities with limited technical staff.
United Kingdom
NHS trusts in London and the Greater Manchester region consolidate vendor relationships around integrated suites capturing expanded IT budget shares. GDPR constraints on patient data orchestration limit multi-system integration offerings from international vendors. Cambridge and Oxford academic medical centers accelerate pilot programs for large language model-powered medication adherence prompts.
India
Corporate hospital chains in Maharashtra and Karnataka prioritize subscription-based deployment models eliminating capital-intensive server maintenance. CDSCO guidance on software-as-medical-device classification creates uncertainty for AI-enabled clinical tools. Hyderabad and Bengaluru health IT clusters attract implementation partners addressing engineering talent scarcity in healthcare specialization.
Healthcare CRM Market Key Industry Players
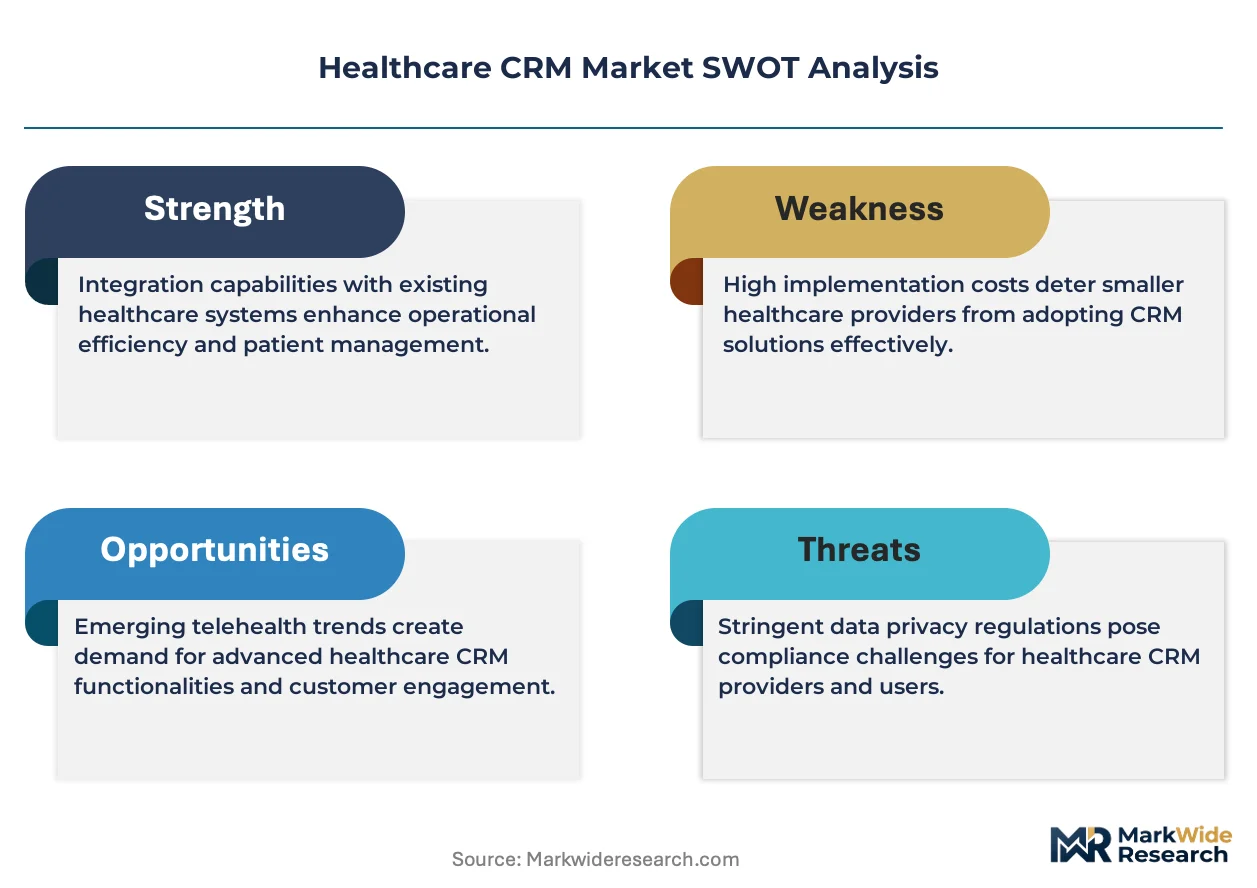
A small set of integrated leaders sits above a broader specialist tier, with native cloud architects and database infrastructure controllers commanding enterprise health system deployments. The vendor landscape bifurcates between those with captive engineering depth and competitors dependent on contracted implementation partners. Two strategic archetypes dominate: platform consolidators unifying patient engagement with revenue cycle modules, and workflow automation specialists with deep electronic health record integration. Competitive moves center on FHIR certification acceleration and AI feature rollout pacing against regulatory timelines.
Within the integrated platform tier, Salesforce and Oracle exemplify contrasting architectural approaches, with the former leveraging cloud-native elasticity and the latter anchoring through database infrastructure control. SAP occupies a position emphasizing workflow automation breadth across payer and provider operations. These three represent the dominant competitive anchors as health system procurement teams consolidate around unified suites and certification-compliant roadmaps.
| Leading Market Players |
|---|
| Salesforce |
| Oracle |
| IBM |
| SAP |
| Microsoft |
| Veeva Systems |
| Accenture |
| Zoho Corporation |
| hc1 |
| Others |
Cost & Logistics Intelligence
Eighteen-month FHIR certification timelines compress vendor cash conversion cycles while amplifying pricing power for pre-certified incumbents. United States health systems leverage consolidated purchasing authority to negotiate subscription discounts against implementation complexity premiums.
Pricing Analysis
Long-term enterprise SaaS contracts dominate procurement, with annual recurring revenue tiers scaling by patient volume band and AI feature depth. Price differentiation hinges on FHIR certification status and native cloud architecture versus hybrid deployment requirements. Cost compression in mid-market segments intensifies as implementation partners absorb margin pressure from talent scarcity. Academic medical centers exhibit lowest price sensitivity due to grant-funded innovation budgets; physician practices face acute budget constraints.
Supply Chain Analysis
India and the United States anchor healthcare IT engineering talent pools, with Hyderabad and Bengaluru clusters feeding implementation partner networks. Cloud infrastructure draws from hyperscaler data centers in Virginia, Frankfurt, and Singapore; specialized FHIR middleware components source from Boston and Berlin health IT clusters. Single-source vulnerability concentrates in AI/ML engineering talent pipelines. Distribution runs through systems integrators and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare CRM platform economics reach an inflection as FHIR interoperability mandates collapse vendor fragmentation into consolidated suite architectures. The FDA's 21st Century Cures Act ecosystem reshapes competitive moats around certification velocity and captive engineering depth.
For Market Incumbents: Secure FHIR certification acceleration as primary defensive priority against cloud-native challengers. Deepen vertical integration into implementation services to offset partner talent scarcity. Anchor renewal pricing through EHR integration switching costs. For New Entrants and Emerging Players: Lead with mobile-first point solutions targeting physician practice whitespace outside hospital system procurement concentration. Emphasize smartphone-native workflows and rapid deployment timelines against enterprise suite complexity. Pursue channel partnerships with regional health IT distributors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement centralization favors scaled platforms with regulatory certification depth. Target acquisition archetypes: workflow automation specialists with captive FHIR engineering teams and established hospital system relationships. Watch AI feature rollout pacing against EU AI Act certification timelines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Acceleration | FDA 21st Century Cures Act compliance compresses vendor replacement cycles toward certified platforms. |
| AI Component Segregation | EU AI Act risk-classification requirements force architectural restructuring for European market access. |
| Implementation Partner Captivation | Talent scarcity drives vertical integration into professional services to control deployment quality. |
| Revenue Cycle Module Integration | Payer-provider convergence creates whitespace for unified patient financial and clinical touchpoints. |
| Mobile-First Platform Development | Physician practice underpenetration offers expansion avenue outside hospital-centric competitive intensity. |
Research Approach
Operator-level perspectives from hospital CIOs, health system procurement directors, EHR integration specialists, and FHIR certification consultants anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital GPO contract disclosures, and hyperscaler healthcare vertical revenue segments. Bottom-up deployment counts triangulated against top-down health system IT spending surveys.
Sensitivity analysis tested forecast robustness across interoperability mandate acceleration scenarios and cloud migration pace variations. Segmentation dimensions modeled include deployment architecture, end-user scale, technology sophistication tier, and regional regulatory cluster. CAGRs derived from patient volume growth projections, replacement cycle timing, and AI feature penetration curves. Inputs incorporated health system consolidation patterns and EU AI Act implementation timelines.
Forecasts assume regulatory continuity in FDA and EMA regimes; material policy shifts would require re-modeling. Specific risks include HIPAA enforcement intensity variations, FHIR standard version updates, and AI algorithm liability framework evolution. Recalibration cycles align with material shifts in interoperability mandate compliance deadlines and health system M&A activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
US Customer Relationship Management Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market
Customer Relationship Management (CRM)
Contact Center Software Market