
 Customer Experience Management (CEM) in Telecommunication Market | 2026-2036
Customer Experience Management (CEM) in Telecommunication Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Experience Management (CEM) in Telecommunication Market Outlook
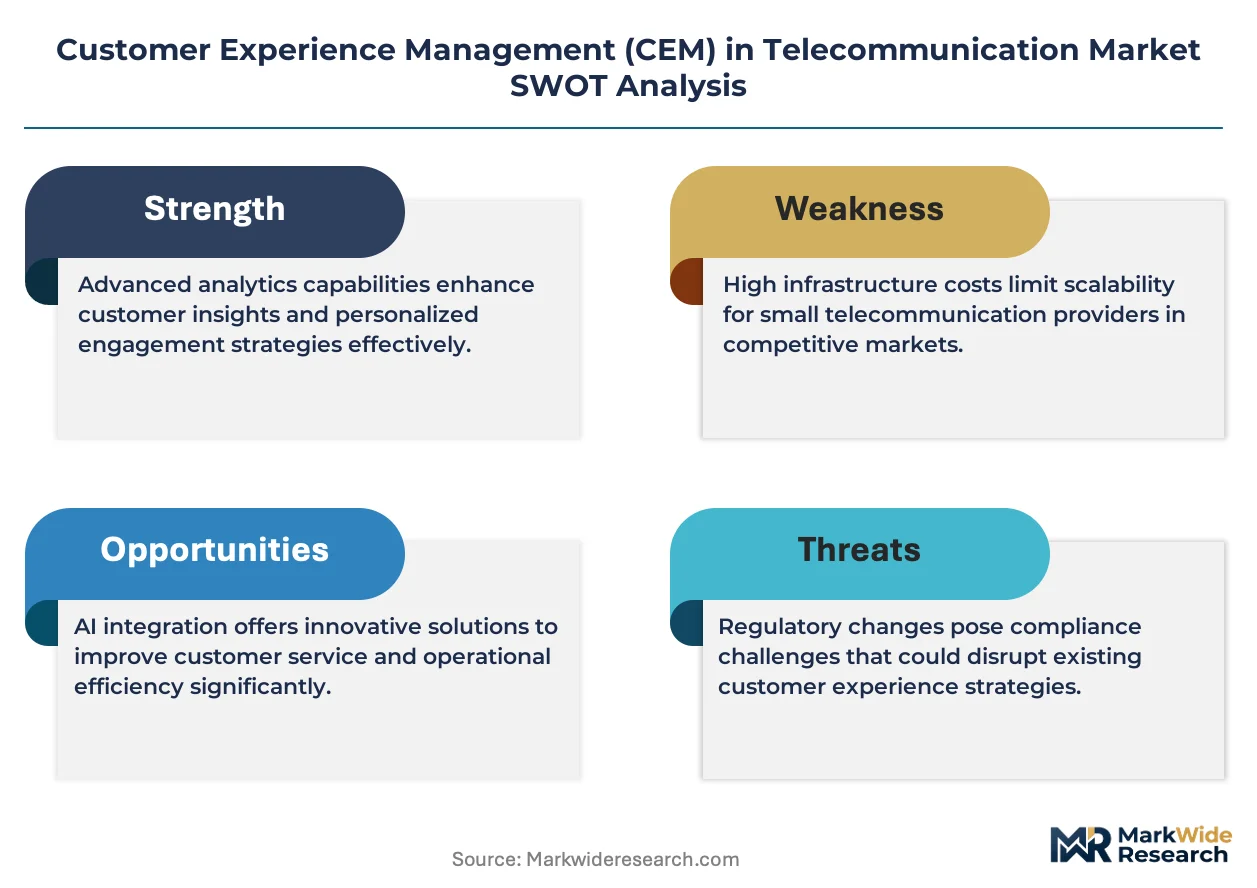
The gap between premium omnichannel orchestration and basic ticketing systems is consolidating around AI-native architectures. NICE Ltd leverages real-time interaction analytics to anchor its position in enterprise telecom deployments. Ericsson competes through network-integrated CEM suites that extend from radio access to customer touchpoints. Huawei Technologies Co., Ltd. dominates in emerging markets where it controls end-to-end infrastructure and overlays experience management natively.
Customer Experience Management in Telecommunication encompasses software platforms, analytics engines, and service workflows that aggregate subscriber interactions across voice, digital, and network channels into unified operational dashboards. These systems apply natural language processing and predictive scoring to anticipate churn, optimize quality of service, and automate resolution pathways for carriers managing millions of accounts. Cloud Solutions within the Technology dimension leads current deployment velocity as carriers migrate from legacy on-premise call center stacks to elastic infrastructure. AI Analytics represents the fastest-expanding margin pool, with carriers paying premium licensing for real-time sentiment models that integrate directly with billing and network operations centers. Enterprise Customers within the End User category sustains the highest contract values, though Small Businesses shows accelerating uptake through bundled SaaS offerings from major platforms.
FCC guidelines on consumer data privacy and complaint transparency shape how US carriers architect their CEM data retention and disclosure workflows. EUs GDPR and proposed AI Act impose cross-border constraints on automated decision-making in subscriber-facing systems, forcing vendors to engineer region-specific compliance modules. Stakeholders must monitor how diverging regulatory timelines for algorithmic accountability will fragment platform development roadmaps and localize vendor procurement criteria.
Market Dynamics
Real-time AI inference at the network edge is compressing subscriber issue resolution from hours to seconds, forcing carriers to rebuild CEM architectures around low-latency data pipelines rather than batch-processed analytics warehouses.
Growth Catalysts
- FCC Net-Neutrality Enforcement:US carriers must maintain transparent traffic management, driving investment in unified monitoring dashboards that correlate network performance with individual subscriber journeys.
- 5G Standalone Core Deployments:Network slicing capabilities enable carriers to offer differentiated service tiers with guaranteed latency, requiring CEM platforms to track quality-of-experience per slice.
- Churn Prediction Algorithms:Machine learning models processing call detail records and social sentiment now flag at-risk accounts before cancellation requests, reducing subscriber acquisition costs.
Market Restraints
- Cloud Infrastructure Concentration:Hyperscaler dependency for elastic CEM workloads creates vendor lock-in and data sovereignty complications for European carriers under GDPR.
- Legacy BSS/OSS Integration:Decades-old billing and provisioning systems resist API modernization, delaying unified customer view deployments by 18-24 months in major operators.
- Specialized Talent Scarcity:Shortage of engineers fluent in both telecommunications protocols and MLOps pipelines restricts in-house platform development at mid-tier carriers.
Strategic Opportunities
- Small Business SaaS Bundles:Tier-2 carriers in Germany and France are white-labeling modular CEM toolkits to SMB resellers, capturing underserved segments below enterprise scale.
- EU AI Act Compliance Services:Automated decision-making disclosure requirements create demand for explainable AI modules that document how churn scores and routing logic are derived.
- Edge-Native Analytics Convergence:Integration of 5G MEC infrastructure with real-time sentiment processing enables sub-50ms intervention triggers during live support calls.
Industry Challenges
- Cross-Functional Data Silos:Network operations, billing, and care teams maintain separate data lakes with incompatible schemas, fragmenting the subscriber 360-degree view.
- Algorithmic Bias Auditing:Carriers deploying automated credit and service tiering face regulatory pressure to document fairness across demographic segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Experience Management (CEM) in Telecommunication Market |
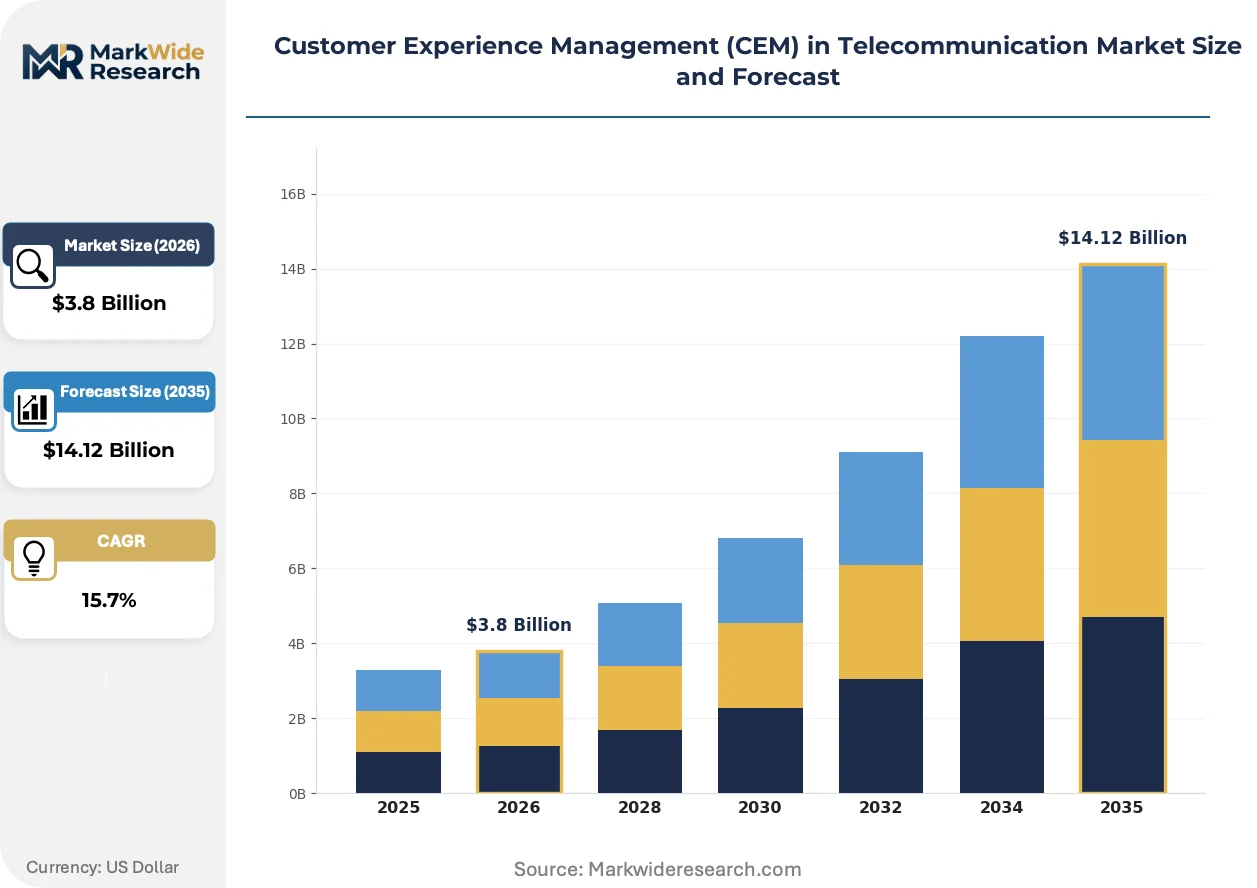
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.12 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Services, Data Services, Managed Services, Value-Added Services Technology: Cloud Solutions, AI Analytics, Customer Feedback Tools, Omnichannel Platforms End User: Enterprise Customers, Small Businesses, Residential Users, Corporates Delivery Model: On-Premise, Cloud-Based, Hybrid, Outsourced Solutions |
| Companies Covered | NICE Ltd, Avaya LLC, Accenture plc, Ericsson, Huawei Technologies Co., Ltd., Amdocs Limited, IBM, Salesforce, Inc., Genesys Cloud Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Experience Management (CEM) in Telecommunication Market Strategic Shifts
Generative AI is collapsing the traditional trade-off between personalization scale and operational cost, enabling carriers to deploy individualized retention scripts across millions of accounts without proportional headcount expansion.
Multimodal large language models trained on voice transcripts, chat logs, and network telemetry are rewriting how carriers identify service degradation patterns. Tier-1 operators in Japan and South Korea are deploying these systems to correlate dropped call clusters with tower maintenance schedules. The technology is compressing mean-time-to-resolution by synthesizing disparate signal sources into unified diagnostic narratives.
The EU AI Act's risk classification framework for automated decision-making systems is forcing carriers to engineer granular consent mechanisms and human-in-the-loop overrides for high-stakes subscriber interactions. Vendors serving European markets must now document model provenance and training data lineage as contractual deliverables. This regulatory pressure is fragmenting product roadmaps between compliant and non-compliant feature branches.
Enterprise procurement teams at multinational carriers are consolidating vendor relationships around platforms offering outcome-based pricing tied to measurable churn reduction. Traditional seat-based licensing is losing ground to contracts where fees scale with retained revenue. This shift is most visible in North American and Australian markets where procurement functions have matured analytics capabilities to validate performance claims.
Customer Experience Management (CEM) in Telecommunication Market Segmentation
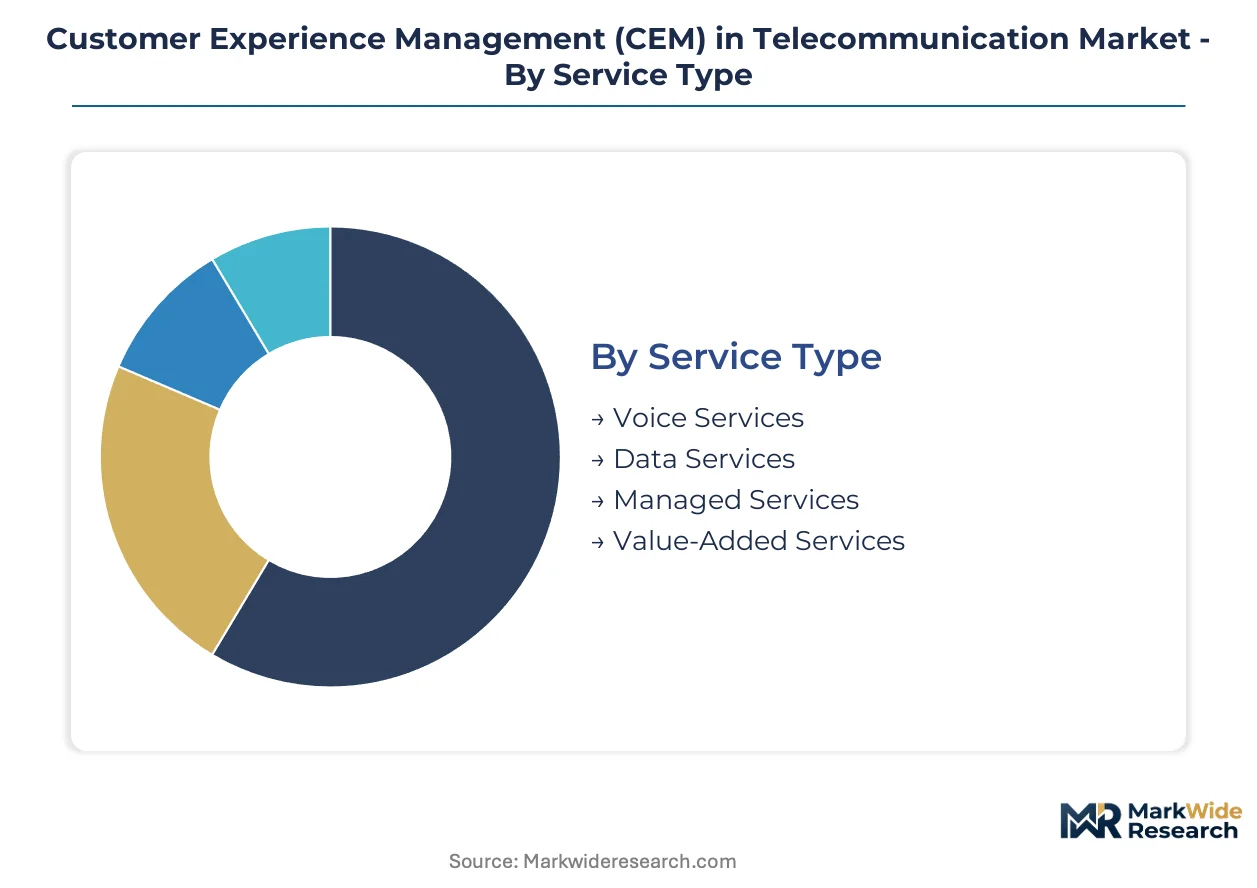
Segmentation in telecommunication CEM reveals how carriers prioritize investments across service tiers and infrastructure models. Distinct operational requirements between mass-market residential subscribers and complex enterprise accounts drive divergent platform architectures and vendor selection criteria.
Service Type:
Standardization dominates voice and data service deployments, while managed and value-added services demand extensive customization to carrier-specific network topologies and regulatory environments.
- Voice Services:Legacy call center quality monitoring systems process circuit-switched and VoIP traffic to detect audio degradation, echo, and dropped connections. US carriers facing FCC complaint transparency mandates concentrate investment here to document service levels for regulatory filings.
- Data Services:Broadband and mobile data experience platforms correlate throughput metrics with subscriber satisfaction scores to identify congestion-induced churn risks. European operators under GDPR constraints prioritize these tools for granular consent management around usage analytics.
- Managed Services:Third-party CEM operations covering platform hosting, model training, and escalation handling.
- Value-Added Services:Premium offerings including proactive outreach, loyalty program integration, and personalized retention campaigns.
Most installed capacity flows through Voice Services. Expansion is steepest in Managed Services.
Technology:
Cloud-native deployments scale efficiently for millions of subscribers, while AI analytics commands premium pricing for real-time inference capabilities that legacy architectures cannot replicate.
- Cloud Solutions:Elastic infrastructure replaces fixed-capacity call center stacks, enabling carriers to absorb traffic spikes during network outages without service degradation. Tier-1 operators in Germany and France accelerate migration to reduce data center capital intensity.
- AI Analytics:Machine learning models process natural language from voice transcripts, chat logs, and social media to predict subscriber intent and automate routing decisions. Japanese carriers deploy multimodal systems correlating network telemetry with sentiment signals for sub-minute issue resolution.
- Customer Feedback Tools:Survey engines and Net Promoter Score trackers capturing post-interaction satisfaction metrics.
- Omnichannel Platforms:Unified interfaces consolidating voice, digital, and in-store touchpoints into single subscriber profiles.
Cloud Solutions absorb the majority of current deployment spend. AI Analytics is climbing the fastest as carriers compete on predictive intervention capabilities.
End User:
Enterprise contracts sustain the highest absolute values, though small business segments show accelerating uptake through standardized SaaS bundles that reduce implementation friction.
- Enterprise Customers:Multi-year agreements covering unified communications, SLA monitoring, and dedicated support tiers for corporate accounts with thousands of lines. Australian carriers report these contracts increasingly include outcome-based pricing tied to measurable churn reduction.
- Small Businesses:Modular toolkits delivered through white-label reseller channels enable tier-2 operators to serve sub-enterprise segments without dedicated sales forces. French regional carriers bundle these with connectivity services to improve account stickiness.
- Residential Users:Mass-market deployments serving individual subscribers through automated self-service and community forums.
- Corporates:Mid-market accounts with hybrid needs between standardized small business tools and full enterprise customization.
Enterprise Customers retain the largest contract values. Small Businesses are gaining share fastest through bundled distribution models.
Delivery Model:
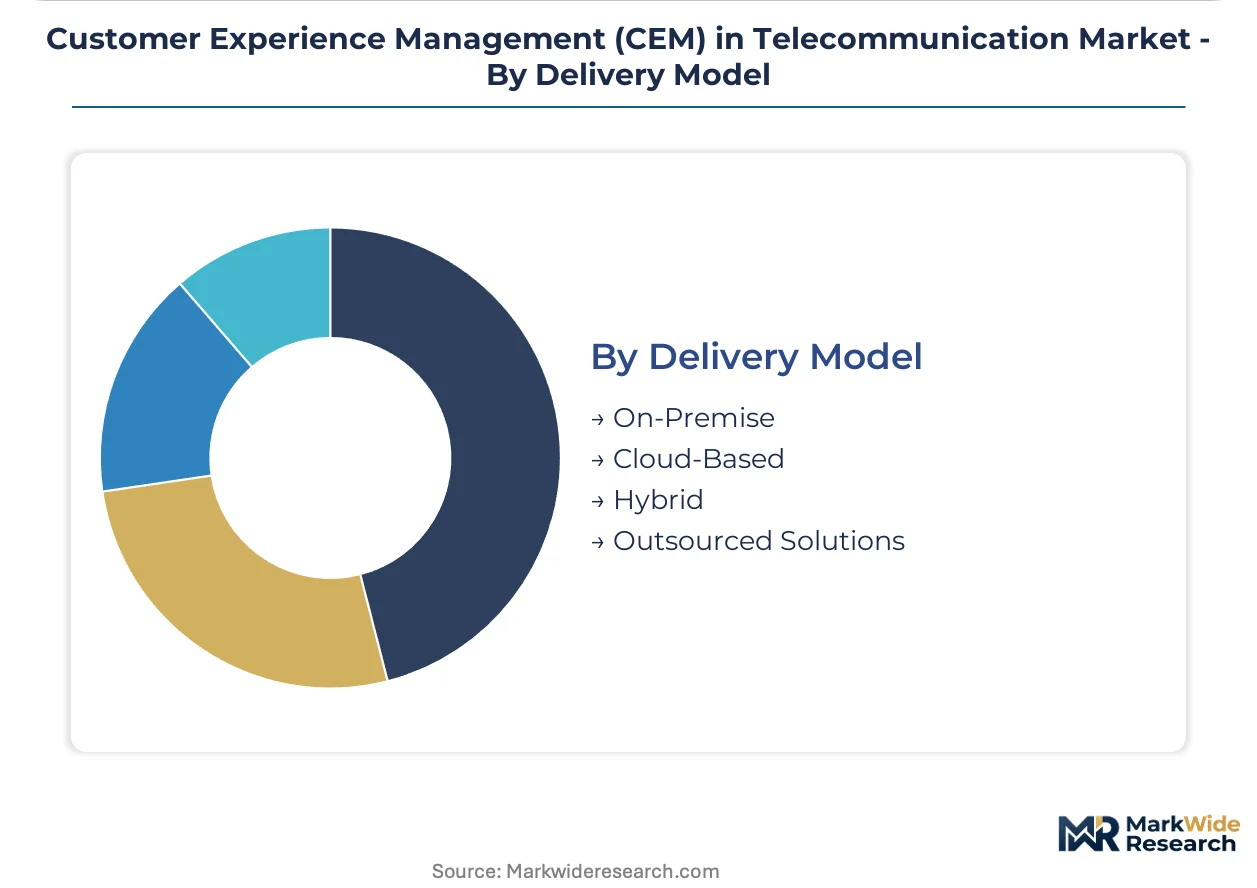
On-premise installations persist where data sovereignty requirements block cloud migration, while hybrid architectures dominate among carriers navigating phased modernization of legacy billing and operations support systems.
- On-Premise:Dedicated hardware deployments within carrier-owned facilities satisfying strict data residency requirements. South Korean operators maintain these configurations for government and defense sector subscribers subject to national security classifications.
- Cloud-Based:Fully managed SaaS platforms eliminating infrastructure ownership and enabling rapid feature updates. Brazilian carriers adopt these to bypass capital constraints and accelerate time-to-market for digital experience capabilities.
- Hybrid:Split architectures retaining sensitive subscriber data on-premise while leveraging cloud elasticity for analytics workloads.
- Outsourced Solutions:Complete CEM function delegation to specialized managed service providers.
Hybrid deployments represent the dominant current configuration. Cloud-Based models are expanding most quickly as API modernization unlocks unified data pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States carriers outpace German operators in AI-native CEM deployment velocity, while Japanese and South Korean markets lead in multimodal sentiment analytics integration with network operations.
United States
FCC net-neutrality enforcement and 5G standalone core rollouts compel carriers to invest in unified journey orchestration dashboards. The FCC mandates transparent traffic management documentation, driving demand for real-time network-to-subscriber correlation tools. Silicon Valley and Dallas-Fort Worth clusters host the densest concentrations of CEM platform engineering talent.
Germany
Tier-2 carriers in Bavaria and North Rhine-Westphalia white-label modular CEM toolkits to SMB resellers, capturing underserved segments below enterprise scale. The EU AI Act imposes cross-border constraints on automated decision-making, forcing vendors to engineer region-specific compliance modules. Frankfurt's financial services corridor demands explainable AI modules for high-stakes subscriber interactions.
Japan
Multimodal large language models trained on voice transcripts and network telemetry compress mean-time-to-resolution by synthesizing disparate signal sources. METI guidelines on digital transformation accelerate carrier investment in edge-native analytics. Tokyo and Osaka metropolitan areas anchor Tier-1 operator deployments correlating dropped call clusters with tower maintenance schedules.
South Korea
Government and defense sector subscribers subject to national security classifications sustain on-premise CEM configurations despite cloud migration pressure. The MFDS and national cybersecurity frameworks restrict data residency for sensitive accounts. Seoul Capital Area carriers deploy sub-50ms intervention triggers during live support calls through 5G MEC integration.
Brazil
Capital constraints drive carriers toward fully managed SaaS platforms that bypass infrastructure ownership and accelerate time-to-market. ANVISA and national data protection regulations shape cloud architecture decisions for subscriber-facing systems. São Paulo's telecommunications corridor concentrates vendor implementation partnerships for Latin American market entry.
Customer Experience Management (CEM) in Telecommunication Market Competitive Environment
Top-tier vendors anchor enterprise telecom deployments through network-integrated suites, while mid-tier specialists compete on modular SaaS bundles for regional carriers. The vendor base stratifies across three tiers: full-stack infrastructure providers, cloud-native platform specialists, and verticalized managed service operators. Two dominant competitive moves define current positioning: outcome-based pricing contracts tied to measurable churn reduction, and strategic partnerships hyperscalers for elastic workload infrastructure.
Within the full-stack infrastructure tier, Ericsson and Huawei Technologies Co., Ltd. exemplify divergent geographic positioning strategies. NICE Ltd occupies a position among real-time interaction analytics specialists serving enterprise-scale deployments. Amdocs Limited represents the billing-integrated CEM archetype, anchoring solutions that bridge legacy BSS/OSS modernization with predictive subscriber intelligence. These three companies illustrate how vendor selection increasingly correlates with carrier infrastructure maturity and regulatory jurisdiction rather than feature parity alone.
| Leading Market Players |
|---|
| NICE Ltd |
| Avaya LLC |
| Accenture plc |
| Ericsson |
| Huawei Technologies Co., Ltd. |
| Amdocs Limited |
| IBM |
| Salesforce, Inc. |
| Genesys Cloud Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive cloud infrastructure integration by hyperscalers anchors supply positioning for CEM platforms while simultaneously compressing pricing power for independent software vendors competing against bundled offerings. Carriers in Germany and France face this structural condition as AWS, Azure, and GCP embed analytics modules into connectivity contracts, forcing standalone vendors toward outcome-based pricing to defend margin.
Pricing Analysis
Capacity additions in Ireland and Singapore are reshaping price floors for cloud-hosted CEM workloads, pressuring legacy on-premise licensing models. Three-tier pricing structure across premium AI-analytics, standard omnichannel, and economy self-service tiers dominates procurement frameworks. Price differentiation rests on real-time inference latency and GDPR compliance certification. Cost compression in the economy tier intensifies because Brazilian and Indian carriers prioritize rapid deployment over customization. Small business resellers exhibit highest price sensitivity, while enterprise accounts in Australia and Japan accept premium tiers for SLA guarantees.
Supply Chain Analysis
Returns and refurbishment flows for legacy call center hardware concentrate in Malaysia and Mexico, where third-party logistics providers remanufacture retired switchgear for secondary markets. Component sourcing draws from Taiwan for GPU acceleration modules, South Korea for memory subsystems, and the United States for specialized NLP chipsets. Single-source vulnerability in NVIDIA AI training silicon creates procurement risk for European vendors under export control scrutiny. Distribution runs through direct enterprise sales teams for Tier-1 carriers, supplemented by systems integrator channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in CEM platforms stems from cloud infrastructure cost-down curves and carrier willingness to pay premiums for real-time churn prediction accuracy.
For Market Incumbents: To counter hyperscaler bundled analytics, Ericsson and NICE Ltd should deepen API integration with legacy BSS/OSS stacks in North American Tier-1 carriers, anchoring switching costs. Certification investment in EU AI Act explainability modules creates regulatory moats against cloud-native challengers. For New Entrants and Emerging Players: Begin with white-label SaaS bundles for Tier-2 carriers in Bavaria and São Paulo, where capital constraints block full-platform procurement. The most penetrable segment combines SMB resellers with modular sentiment analytics. A channel-first go-to-market through regional systems integrators accelerates carrier trust acquisition. For Investors and Strategic Acquirers: Roll-up economics work for verticalized managed service operators because carrier outsourcing trends fragment CEM execution across multiple vendors. Long-term viability favors platforms with proprietary training data from ten-million-plus subscriber interactions. Monitor FCC complaint transparency enforcement intensity as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies voice, chat, and network telemetry into single subscriber profiles for Japanese Tier-1 operators. |
| Strategic Partnership | Hyperscaler alliances provide elastic GPU capacity for real-time sentiment model training at German carriers. |
| Acquisition of Specialist Firm | Captures proprietary NLP training data from ten-million-plus subscriber interaction archives. |
| Geographic Expansion | Establishes EU AI Act compliance engineering centers in Frankfurt for continental carrier procurement. |
| Product Launch | Deploys edge-native analytics converging 5G MEC with sub-50ms intervention triggers in Seoul. |
Study Parameters
Bottom-up carrier deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with CEM platform product managers, telecommunications procurement officers, network operations executives, and systems integration specialists informed demand-side assumptions. Secondary validation drew from FCC complaint databases, EU AI Act regulatory filings, hyperscaler capex disclosures, and carrier annual reports. Triangulation between subscriber churn correlation studies and platform licensing data anchored market sizing.
Historical trendline analysis of CEM adoption velocity across cloud migration waves established baseline growth parameters. The projection framework segments by service type, technology layer, end-user scale, and delivery model, with additional granularity for regulatory jurisdiction clusters. CAGRs derive from fitted adoption curves calibrated against 5G standalone core deployment timelines and AI inference cost decline trajectories. Forecast inputs include carrier capital expenditure patterns and hyperscaler infrastructure expansion announcements.
Several conditions sit outside the modeled scope, including sovereign cloud mandates that could nationalize data residency requirements and generative AI capability jumps that might collapse current pricing architectures. Forecasts reflect documented assumptions about carrier outsourcing propensity and API modernization velocity. Practitioners should monitor EU AI Act enforcement consistency and FCC net-neutrality rule stability for early signals of demand trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market
Customer Relationship Management (CRM)
CRM Analytics Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Customer Communication Management Market
Customer Relationship Management (CRM)
Contact Center Software Market