
 Customer Experience Platforms Market | 2026-2036
Customer Experience Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Experience Platforms Market Outlook
Subscription-based pricing for AI-powered services is restructuring how enterprises procure customer experience capabilities. Zendesk leverages its multi-product ecosystem to anchor recurring revenue streams across mid-market accounts. Qualtrics XM differentiates through deep integration with enterprise resource planning systems, while Medallia specializes in real-time feedback loops for hospitality and financial services clients.
Customer experience platforms encompass software systems that collect, analyze, and act upon customer interaction data across touchpoints, typically processing structured survey responses, unstructured social sentiment, and behavioral telemetry through machine learning pipelines to optimize retention and lifetime value. Feedback management and journey mapping represent mature segments with established vendor bases, whereas AI-powered services and personalization tools capture expanding margin pools as enterprises prioritize predictive engagement over reactive support. Cloud-based and multi-cloud deployment options are gaining preference as organizations seek elastic infrastructure for seasonal demand spikes in retail and telecommunications.
GDPR and the EU AI Act impose strict constraints on automated decision-making in customer profiling, compelling platform vendors to build explainability layers into their analytics engines. The Federal Trade Commission in the United States scrutinizes data brokerage practices that feed into CX personalization engines, affecting how vendors source third-party behavioral signals. Stakeholders must weigh regulatory compliance investments against the competitive advantage of deeper customer intelligence orchestration.
Market Dynamics
Subscription-based pricing for AI-powered services is restructuring how enterprises procure customer experience capabilities, compressing traditional perpetual license models and forcing vendors to build recurring revenue through integrated product ecosystems rather than standalone point solutions.
Growth Catalysts
- GDPR and EU AI Act:Privacy-by-design mandates are compelling enterprises to replace legacy analytics stacks with compliant platforms, creating replacement demand across European retail and financial services sectors.
- Real-time feedback loops:Hospitality chains and wealth management firms are deploying sentiment analysis pipelines that process unstructured voice and text data to intercept churn before ticket escalation.
- Cloud elasticity:Telecommunications providers in India and Brazil are adopting multi-cloud deployments to handle seasonal traffic spikes without capital-intensive infrastructure builds.
Market Restraints
- Data brokerage scrutiny:FTC enforcement actions against third-party behavioral signal sourcing are constraining how vendors enrich customer profiles, limiting personalization depth in US deployments.
- GPU compute costs:Training and inference for large language models in journey analytics is concentrating platform economics among hyperscaler-backed vendors with captive silicon supply.
- Legacy system entrenchment:Mainframe-dependent insurance and banking IT stacks in Japan and Germany resist API-native CX orchestration, extending sales cycles by 18-24 months.
Strategic Opportunities
- Explainability layers:Vendors embedding interpretable machine learning for automated decision-making can capture compliance-burdened European financial services accounts fleeing black-box competitors.
- Voice-of-customer convergence:Platforms integrating contact center transcription, social listening, and IoT telemetry into unified signal streams are creating new pricing power in industrial equipment aftermarket services.
- India's DPI infrastructure:The country's digital public goods stack enables low-cost identity-verified feedback collection at population scale, opening CX platform adoption for public sector and rural banking use cases.
Industry Challenges
- MLOps talent scarcity:Pipeline engineering for real-time feature stores and model drift monitoring requires specialized skill sets that command premium compensation, squeezing mid-market vendor margins.
- Cross-border data localization:Divergent sovereignty requirements between China's PIPL, Russia's data localization laws, and EU GDPR are fragmenting platform architectures and multiplying engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Experience Platforms Market |
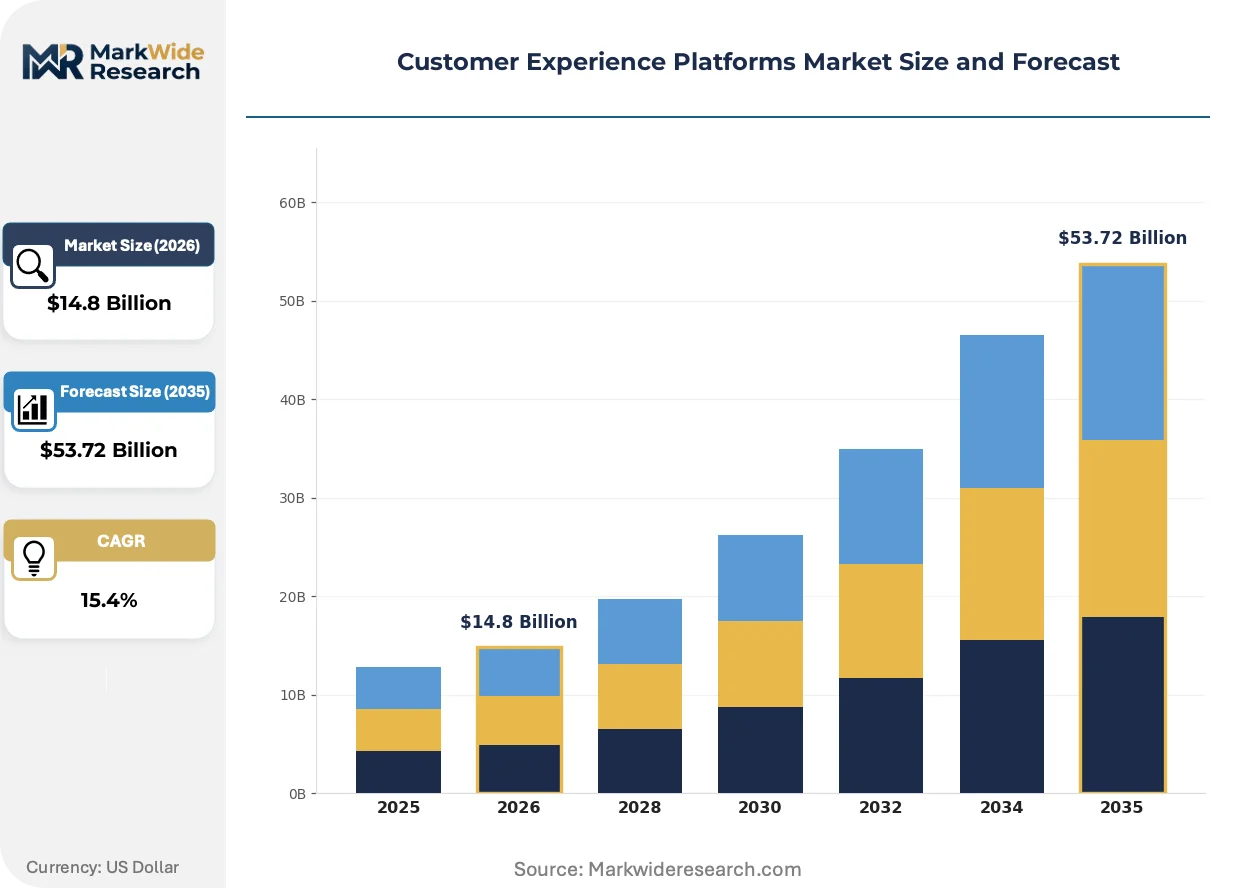
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $53.72 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feedback Management, Journey Mapping, Personalization, Analytics Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Cloud End User: Retail, Hospitality, Financial Services, Telecommunications Solution: Desktop Applications, Mobile Applications, Self-Service Portals, AI-Powered Services |
| Companies Covered | Zendesk, Freshdesk, Qualtrics XM, Sprinklr, Contentsquare, Medallia, HubSpot Service Hub, Intercom, SogoCX by Sogolytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Experience Platforms Market Strategic Shifts
Federated learning architectures and edge-deployed inference engines are redistributing computational load away from centralized cloud warehouses, enabling privacy-preserving analytics that comply with data residency constraints without sacrificing model performance.
Edge-based natural language processing is decentralizing sentiment analysis from hyperscaler data centers to retail point-of-sale terminals and automotive infotainment systems. Quick-service restaurant chains and connected vehicle manufacturers are piloting on-device inference to reduce latency below 50 milliseconds for real-time service recovery. This topology is compressing the addressable market for centralized batch-processing analytics vendors while expanding margin pools for semiconductor-integrated software stacks.
The EU AI Act's risk-based classification system for automated decision-making is forcing platform vendors to reengineer scoring algorithms for credit, insurance, and employment use cases. Systems deemed high-risk must maintain human oversight interfaces and audit trails, adding 15-20% to development costs. Financial services deployments across Germany, France, and the Netherlands are prioritizing vendors with pre-certified explainability modules, creating a two-tier competitive landscape between compliance-ready and legacy architectures.
Enterprise buyers are unbundling monolithic CX suites and procuring point solutions through marketplaces integrated with existing cloud contracts. Mid-market technology and professional services firms in the United States are consolidating vendor relationships under Microsoft, Salesforce, and ServiceNow ecosystems, displacing standalone best-of-breed procurement. This concentration is compressing pricing power for independent platforms while expanding attach rates for native ecosystem players.
Customer Experience Platforms Market Segmentation
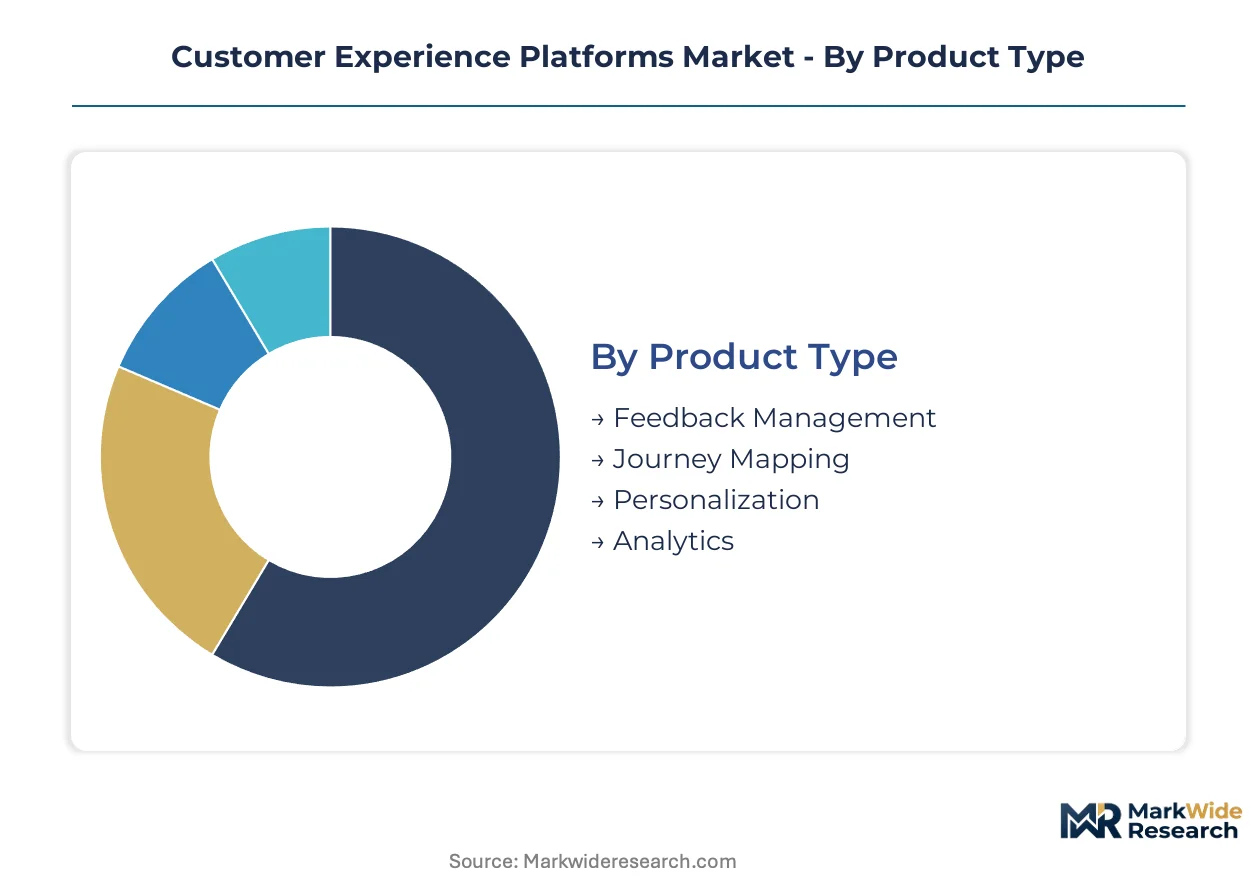
Customer experience platforms fragment across four intersecting axes that determine procurement priorities. Technical architecture choices lock enterprises into multi-year infrastructure commitments, while end-user verticals impose distinct compliance and latency requirements that reshape feature roadmaps.
Product Type:
Technical sophistication distinguishes mature tooling from emerging capabilities that capture expanding margin pools.
- Feedback Management:Structured survey engines and Net Promoter Score tracking dominate installed bases across Fortune 500 accounts. Banking consortia in Germany and France prioritize these tools for regulatory reporting under GDPR Article 30 documentation requirements.
- Journey Mapping:Visual workflow designers connect touchpoint telemetry into unified lifecycle views. Omnichannel retail chains in the United States deploy these systems to unify online browsing patterns with in-store purchase behavior, compressing attribution windows from weeks to minutes.
- Personalization:Real-time content adaptation engines process behavioral signals to customize offers.
- Analytics:Descriptive and predictive dashboards aggregate cross-channel metrics for executive consumption.
Feedback Management leads on scale; Personalization leads on momentum.
Deployment:
Infrastructure topology decisions reflect data sovereignty constraints and workload elasticity requirements.
- Cloud-Based:Single-tenant or multi-tenant SaaS configurations deliver automatic updates and elastic scaling. Mid-market professional services firms across India consolidate here to avoid capital expenditure while accessing GPU-accelerated inference.
- Multi-Cloud:Distributed architectures span AWS, Azure, and Google Cloud simultaneously for redundancy. Telecommunications providers in Brazil and India adopt this pattern to route traffic through lowest-latency availability zones during seasonal demand spikes.
- Hybrid:Sensitive data remains on-premises while compute-intensive processing shifts to cloud.
- On-Premises:Air-gapped installations serve defense contractors and classified government facilities.
Cloud-Based dominates current procurement volumes; Multi-Cloud climbs the fastest as sovereignty requirements multiply.
End User:
Vertical-specific compliance regimes and customer interaction patterns dictate platform configuration priorities.
- Financial Services:Wealth management and retail banking deploy explainable AI for credit scoring and churn prediction. EU AI Act high-risk system classifications force German and Dutch institutions to maintain human oversight interfaces and algorithmic audit trails.
- Retail:Unified commerce platforms integrate point-of-sale, e-commerce, and mobile app telemetry. North American department store chains expand deployment to synchronize inventory visibility with real-time personalization.
- Hospitality:Guest sentiment analysis intercepts service failures before review platform escalation.
- Telecommunications:Subscriber lifecycle management reduces churn through predictive intervention.
Financial Services commands premium pricing; Retail expands most quickly across mid-market accounts.
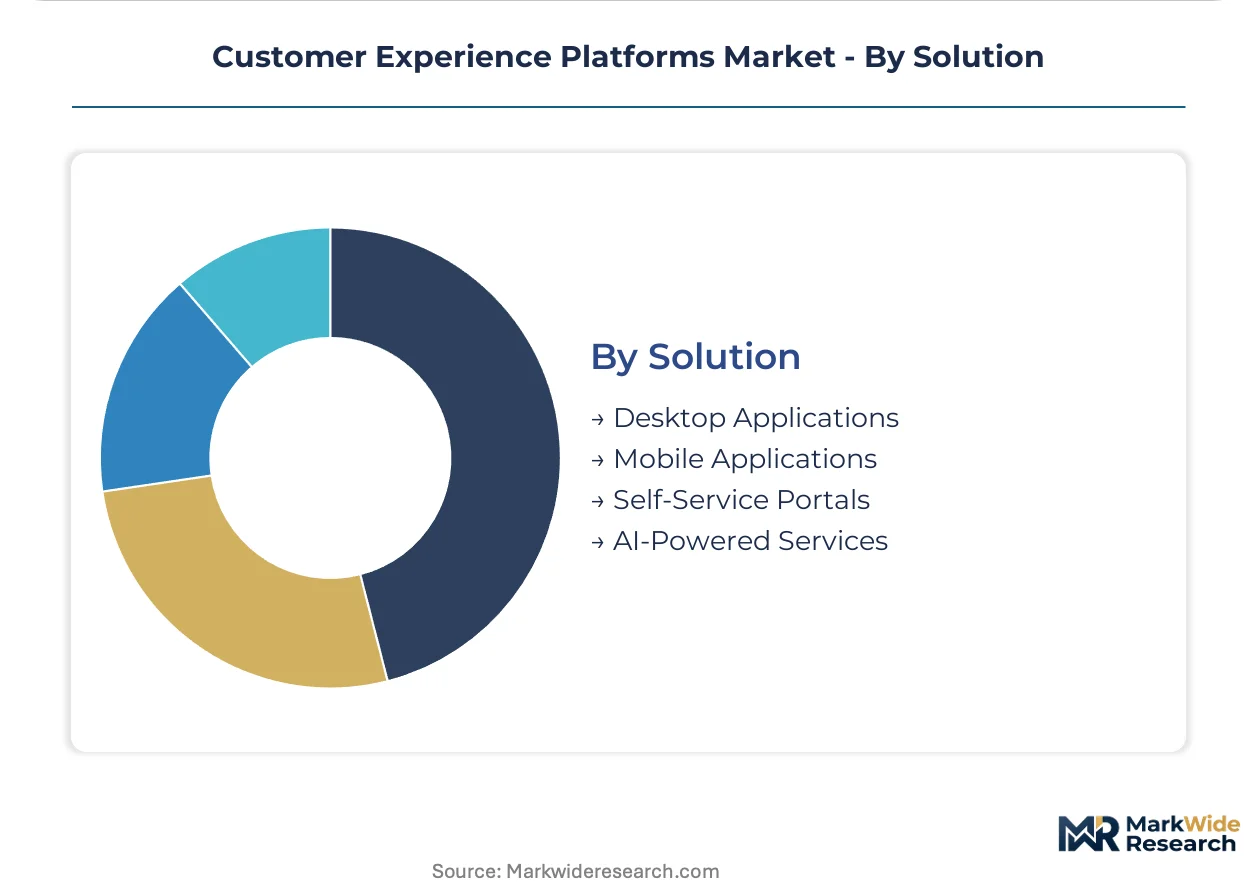
Solution:
Interface modality and intelligence layer integration determine user adoption curves and operational transformation depth.
- AI-Powered Services:Large language models and predictive engines automate response generation and next-best-action recommendations. Hospitality chains and wealth managers deploy these for real-time sentiment analysis that processes unstructured voice and text data.
- Mobile Applications:Native iOS and Android experiences extend platform functionality to field service teams and executive dashboards. Quick-service restaurant operators in the United States prioritize these for frontline manager access to real-time customer feedback.
- Desktop Applications:Full-featured client software remains standard for power users and administrators.
- Self-Service Portals:Configurable interfaces enable business users to build workflows without engineering support.
Desktop Applications retains the largest installed base; AI-Powered Services gains share fastest as GPU economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Germany in enterprise IT allocation for customer intelligence software, while India trails both in absolute spend yet accelerates faster through cloud-native procurement patterns.
United States
Enterprise technology and professional services firms drive platform adoption through consolidated vendor relationships under major cloud ecosystems. FTC enforcement actions against third-party data brokerage constrain personalization depth, forcing vendors to reengineer signal sourcing. The San Francisco Bay Area and Greater Boston anchor hyperscaler-backed platform development, concentrating MLOps talent and GPU compute access.
Germany
Automotive manufacturers and industrial equipment suppliers deploy journey analytics for aftermarket service optimization. EU AI Act high-risk system classifications mandate human oversight interfaces for credit and insurance scoring algorithms. The Stuttgart and Munich metropolitan regions concentrate platform engineering teams serving GDPR-compliant financial services deployments.
United Kingdom
Wealth management and retail banking sectors prioritize explainable AI modules for churn prediction and client segmentation. FCA conduct rules intersect with GDPR requirements to shape vendor procurement criteria. London's fintech corridor dominates regional headquarters placement for North American platform vendors seeking European market entry.
India
Telecommunications providers and quick-service restaurant chains adopt multi-cloud deployments to manage seasonal demand elasticity without capital-intensive infrastructure. TRAI data localization guidelines and the Digital Personal Data Protection Act reshape platform architecture decisions. Bengaluru and Hyderabad host captive development centers for global vendors seeking cost-engineered feature delivery.
Brazil
Retail chains and telecommunications operators leverage cloud elasticity to handle traffic spikes during promotional periods and sporting events. ANVISA and central bank regulations impose sector-specific data handling requirements on customer-facing systems. São Paulo anchors regional platform deployment decisions, with Rio de Janeiro secondary for hospitality and tourism-focused sentiment analysis.
Customer Experience Platforms Market Competitive Environment
Top-tier vendors anchor the integrated-suite segment, while point-solution specialists compete on vertical depth and deployment speed. The market exhibits tiered consolidation around three strategic archetypes: ecosystem-integrated platforms, vertical-specialized feedback engines, and AI-native personalization stacks. M&A activity concentrates on acquiring real-time analytics capabilities and geographic expansion through regional system integrators. Portfolio diversification into adjacent revenue operations and customer success management tools represents the dominant competitive vector.
Within the ecosystem-integrated tier, Zendesk and HubSpot Service Hub exemplify multi-product anchoring strategies that compress standalone vendor pricing power. Qualtrics XM occupies a position bridging enterprise resource planning connectivity with experience management depth. Medallia represents the vertical-specialist archetype, with its naming convention signaling hospitality and financial services concentration. These three companies collectively illustrate how vendor selection criteria diverge between mid-market consolidation preferences and enterprise best-of-breed procurement.
| Leading Market Players |
|---|
| Zendesk |
| Freshdesk |
| Qualtrics XM |
| Sprinklr |
| Contentsquare |
| Medallia |
| HubSpot Service Hub |
| Intercom |
| SogoCX by Sogolytics |
| Others |
Value Chain & Pricing Dynamics
Mid-market procurement consolidation under hyperscaler ecosystems is compressing standalone vendor pricing power and forcing supply reconfiguration toward API-native, cloud-elastic architectures that can deliver subscription economics at scale.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for cloud-native CX deployments as regional data center buildouts reduce latency premiums previously commanded by US-based infrastructure. Three-tier pricing structure across premium, standard, and economy levels dominates SaaS procurement, with differentiation anchored in AI inference volume, GDPR compliance certification, and multi-cloud redundancy. Pricing pressure stems from hyperscaler marketplace bundling that displaces best-of-breed point solutions. Mid-market professional services firms exhibit highest price sensitivity; financial services institutions in Germany and the Netherlands show lowest sensitivity due to compliance-driven vendor stickiness.
Supply Chain Analysis
Customer data ingestion hardware refurbishment flows from retail point-of-sale terminals and automotive infotainment systems back to semiconductor-integrated software vendors for edge inference chip reprogramming. Supply concentration centers on Taiwan for GPU silicon, Ireland and Singapore for cloud infrastructure orchestration, and India for feature engineering talent pipelines. Raw material dependencies include NVIDIA/AMD accelerator chips, high-bandwidth memory modules, and specialized optical transceivers for data center interconnect. Single-source vulnerability around TSMC's advanced node production creates systemic concentration risk. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with regional system integrator overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in CX platforms rests on GPU cost curves flattening through hyperscaler volume commitments and premium-tier pricing power accruing to explainable AI modules under EU AI Act compliance mandates.
For Market Incumbents: Anticipate hyperscaler marketplace unbundling by embedding native explainability layers that preempt regulatory displacement, and anchor recurring revenue through vertical-specific workflow automation that resists ecosystem commoditization. Threat vectors include edge-deployed inference engines that circumvent centralized platform telemetry capture. Vertical integration into MLOps talent pipelines in Bengaluru and Hyderabad defends engineering cost position. For New Entrants and Emerging Players: Federated learning architectures offer technology-first wedge into privacy-constrained European financial services accounts fleeing black-box incumbents. White-space targets include industrial equipment aftermarket voice-of-customer convergence and India's DPI-enabled rural banking feedback collection. Most penetrable segment: mid-market hospitality chains seeking real-time sentiment analysis without legacy mainframe integration burdens. Go-to-market angle: pre-certified compliance modules that compress procurement cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native personalization stacks possessing captive GPU supply agreements and pre-built explainability modules for EU AI Act high-risk system classifications. Long-term viability favors vendors with vertical depth in wealth management and hospitality rather than horizontal suite breadth. Acquisition target archetype: real-time analytics specialists with edge inference IP. Signal to watch: hyperscaler capex allocation shifts toward sovereign cloud regions indicating regulatory-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding within Microsoft, Salesforce, and ServiceNow ecosystems displaces standalone procurement for mid-market accounts. |
| Acquisition of Specialist Firm | Real-time analytics capabilities in hospitality and financial services verticals command premium multiples due to compliance moats. |
| Product Launch | Explainable AI modules pre-certified for EU AI Act high-risk classifications unlock German and Dutch banking procurement. |
| Strategic Partnership | Regional system integrator alliances in São Paulo and Bengaluru accelerate deployment velocity without direct sales overhead. |
| Geographic Expansion | Sovereign cloud deployments in India and Brazil capture seasonal elasticity demand from telecommunications and retail verticals. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners across North America, Europe, and Asia-Pacific with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile telemetry data, and EU regulatory certification databases. Bottom-up deployment tracking across cloud regions and top-down enterprise IT budget surveys were triangulated against vendor-reported subscription metrics.
Historical reference periods anchored the forecast window through backward-looking analysis of cloud migration velocity and AI adoption curves across the projection horizon. Segmentation dimensions modeled include deployment topology, organization size tier, vertical industry, integration complexity, and regional regulatory framework cluster. CAGRs were derived through logistic diffusion modeling of enterprise software procurement cycles, with industry-specific inputs incorporating GPU cost trajectories and GDPR enforcement intensity indices.
The model holds under stable hyperscaler pricing and continued EU AI Act enforcement; deviation in semiconductor supply shocks or data localization law proliferation would shift deployment elasticity assumptions. Practitioners should monitor hyperscaler sovereign cloud region announcements and EU AI Act high-risk system certification timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Customer Experience Management Software Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market