
 Global Customer Relationship Management Market | 2026-2036
Global Customer Relationship Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Relationship Management Market Foresight
North American software vendors is consolidating around subscription platforms that embed artificial intelligence natively. Salesforce leverages its AppExchange ecosystem to extend developer loyalty across enterprise accounts. Microsoft Dynamics anchors its position through tight integration with Office 365 and Azure infrastructure. Oracle competes by specializing in industry-specific vertical editions for financial services and telecommunications.
Customer relationship management denotes the systematic practice of acquiring, organizing, and analyzing customer interaction data across sales, marketing, and service channels, typically delivered through cloud-native software architectures with API-first connectivity and real-time analytics engines. Its primary commercial purpose is to improve customer lifetime value and reduce churn through predictive engagement. Cloud-based deployment now captures the dominant margin pool as enterprises abandon capital-intensive on-premises infrastructure. Marketing automation and analytics segments lead solution type growth, while large enterprises remain the most contested customer type due to multi-year contract values.
US HIPAA and SEC disclosure rules shape how CRM platforms handle sensitive customer records, while EU GDPR and the EU AI Act impose strict limits on automated profiling and cross-border data transfers. India's BIS cloud standards and China's NMPA data localization requirements add further compliance layers for multinational deployments. Stakeholders must monitor how fragmented sovereignty rules alter platform architecture decisions and vendor selection criteria across jurisdictions.
Market Dynamics
Cloud-native architectures are consolidating control over enterprise customer data pipelines, displacing fragmented on-premises installations as GDPR and HIPAA enforcement hardens requirements for real-time compliance telemetry.
Growth Catalysts
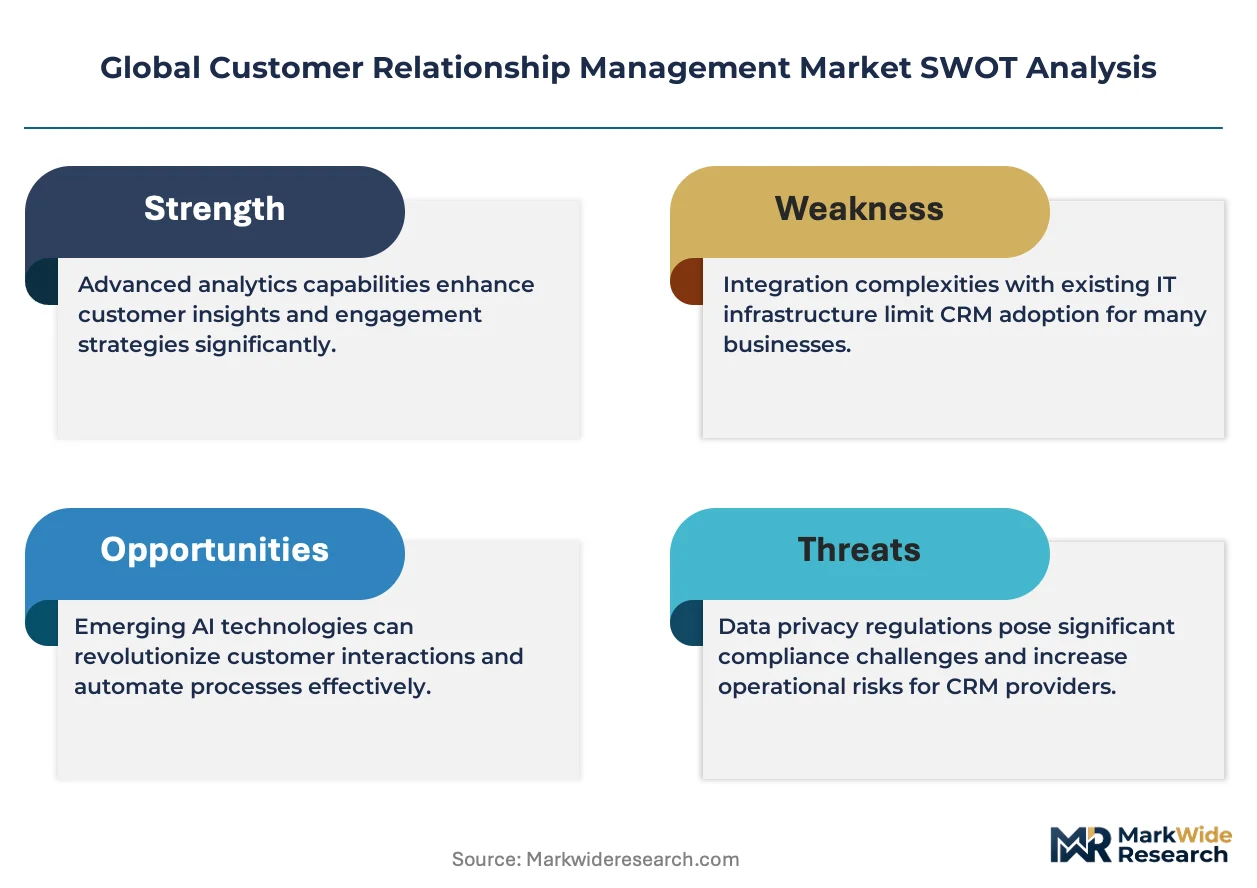
- EU AI Act compliance automation:Financial services firms in Germany and France are deploying predictive engagement engines that embed automated audit trails for algorithmic decision documentation.
- India PLI scheme incentives:Software development centers in Bangalore and Hyderabad are attracting foreign CRM platform investment through production-linked incentive structures for cloud infrastructure.
- API-first connectivity standards:Retail banking networks across Singapore, Australia, and Canada are mandating open banking interfaces that require real-time customer data synchronization.
Market Restraints
- Cross-border data localization mandates:China's NMPA requirements and Russia's data sovereignty rules fragment cloud architecture strategies for multinational deployments.
- Specialized data engineering talent scarcity:Pipeline construction for real-time analytics engines faces recruitment bottlenecks in secondary European technology markets.
- Legacy system integration technical debt:Mainframe-era customer databases in established financial institutions resist API abstraction without expensive middleware layers.
Strategic Opportunities
- Indonesia's unpenetrated SME segment:Mid-market manufacturers in Jakarta and Surabaya lack deployed CRM infrastructure despite accelerating digital payment adoption.
- Convergence of generative AI with voice analytics:Contact center operators are piloting real-time sentiment synthesis for service escalation prediction.
- Brazil's open banking regulatory tailwind:Central bank mandates for customer data portability are creating first-mover advantages for cloud-native platform entrants.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous GDPR, HIPAA, and BIS compliance timelines stretch quality assurance resources across product release cycles.
- Real-time data pipeline capex intensity:Sub-100-millisecond latency requirements for predictive engagement engines demand specialized stream processing infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Relationship Management Market |
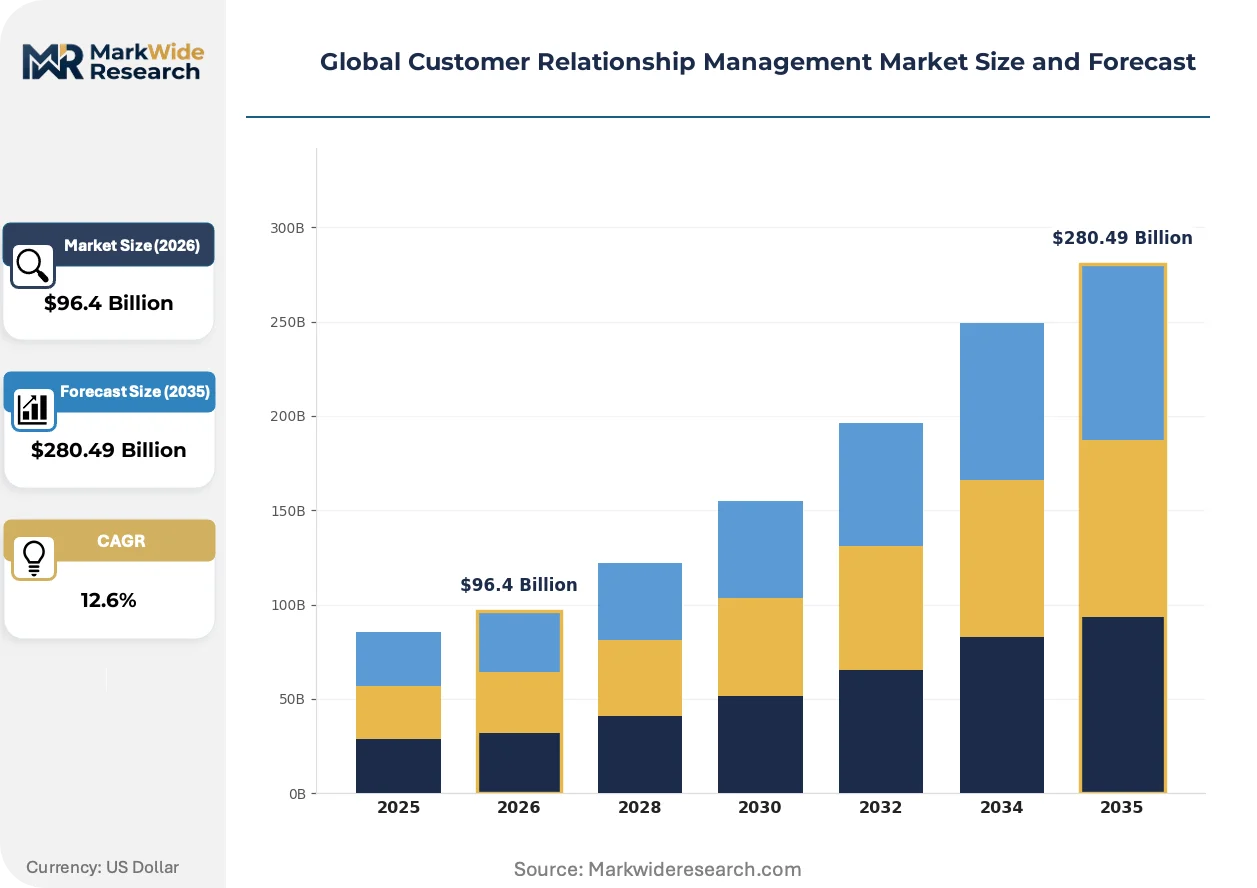
| Market Size in 2026 | $96.4 Billion |
| Market Size in 2035 | $280.49 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Private Cloud Solution Type: Sales Force Automation, Marketing Automation, Customer Support, Analytics, Social CRM Application: Lead Management, Campaign Management, Customer Retention, Contact Management, Customer Segmentation Customer Type: Small & Medium Businesses, Large Enterprises, Startups, Nonprofit Organizations |
| Companies Covered | Salesforce, Microsoft Dynamics, Oracle, SAP, Adobe, HubSpot, Zoho, Zendesk, Freshworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Relationship Management Market Shifts & Advancements
Artificial intelligence integration is consolidating formerly separate marketing automation, sales forecasting, and service ticketing workflows into unified data fabrics. Platform vendors are racing to embed predictive capabilities natively rather than through bolt-on acquisitions.
Embedded machine learning inference engines are consolidating customer lifetime value prediction directly within operational databases. Retail banking and telecommunications operators in the United States and United Kingdom are deploying these capabilities at scale. The technology is consolidating competitive advantage around data gravity rather than feature breadth.
EU GDPR Article 22 enforcement against fully automated profiling is forcing CRM vendors to architect human-in-the-loop decision interfaces. Financial services deployments across Italy, Spain, and the Netherlands are redesigning lead-scoring workflows to accommodate intervention requirements. Marketing automation segments targeting credit-sensitive products face the steepest compliance redesign cycles.
Subscription pricing for core platform access is compressing as buyers demand consumption-based billing for AI inference and data storage. Mid-market enterprises in South Korea and Mexico are piloting usage-metered contracts that unbundle predictive analytics from base licensing. Procurement teams in technology and professional services verticals are driving this renegotiation most aggressively.
Global Customer Relationship Management Market Segmentation
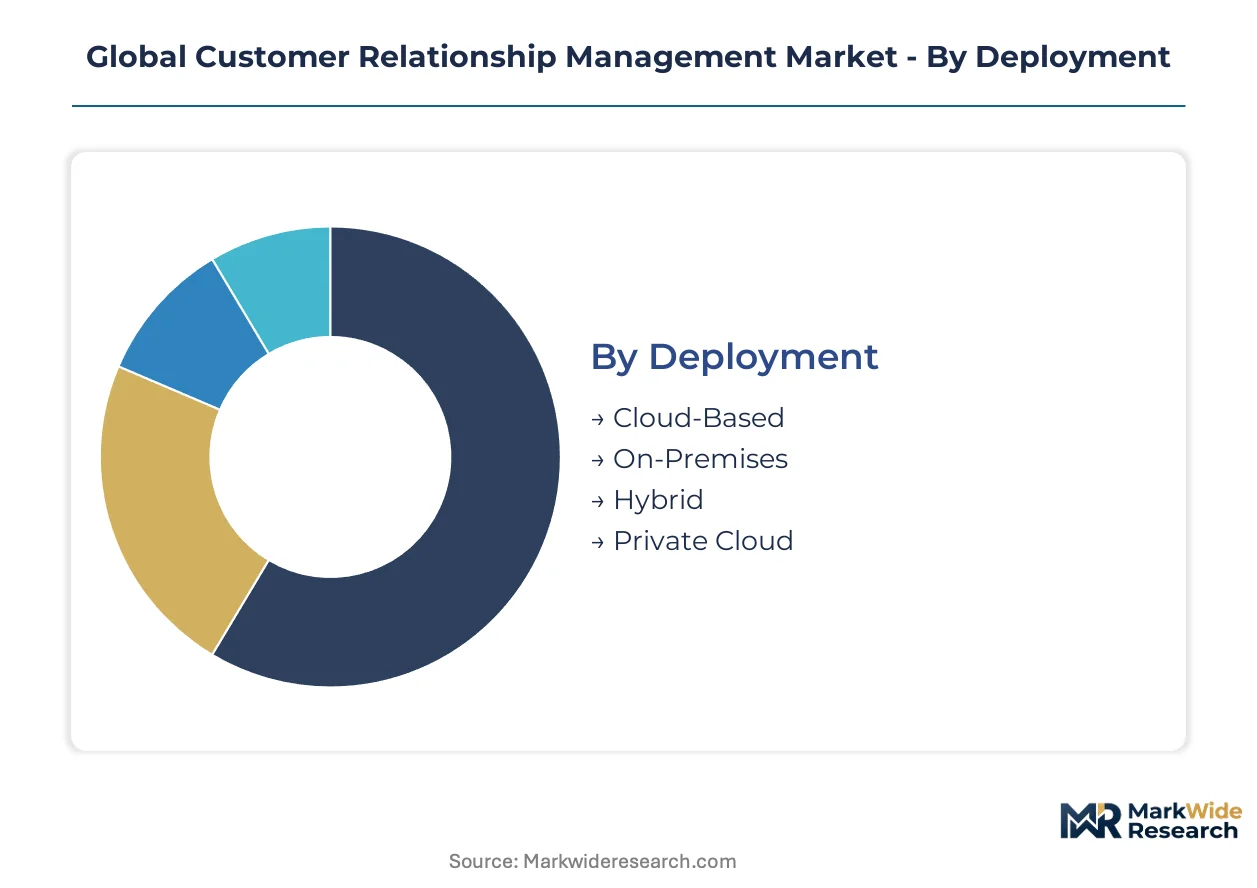
CRM segmentation reveals how deployment economics, solution specialization, and buyer scale create distinct competitive battlegrounds. Vendors must align architecture investments with the compliance requirements and integration complexity that each segment demands.
Deployment:
Buyers in this category differ by capital intensity tolerance and data sovereignty obligations.
- Cloud-Based:Multi-tenant architectures with automatic compliance telemetry now dominate enterprise procurement in Germany and France. EU AI Act documentation requirements and HIPAA audit mandates accelerate displacement of self-managed infrastructure.
- On-Premises:Legacy mainframe-era financial institutions in the United States and United Kingdom retain these deployments where sub-100-millisecond latency for predictive scoring is non-negotiable. Capital expenditure constraints and talent scarcity erode this base.
- Hybrid:Split configurations separate customer PII in private nodes from analytics workloads in public cloud. Retail banking networks across Singapore and Australia favor this model for open banking API compliance.
- Private Cloud:Single-tenant dedicated instances serve defense contractors and government health systems with NIST 800-171 or FedRAMP authorization requirements.
Volume sits with Cloud-Based; growth tilts toward Hybrid as sovereignty rules fragment.
Solution Type:
Margin concentration follows the depth of AI integration and data pipeline complexity.
- Marketing Automation:Real-time journey orchestration engines with embedded GDPR Article 22 human-in-the-loop interfaces command premium pricing. Italian and Spanish financial services firms are redesigning credit-sensitive lead scoring around these compliance features.
- Analytics:Customer lifetime value prediction with stream processing infrastructure is consolidating competitive advantage around data gravity. Telecommunications operators in the United States deploy these capabilities at scale.
- Sales Force Automation:Pipeline management with predictive forecasting and mobile-first field interfaces.
- Customer Support:Omnichannel ticketing with voice analytics and real-time sentiment synthesis for escalation prediction.
- Social CRM:Public listening and engagement tools with influencer identification and crisis response workflows.
Revenue concentrates in Marketing Automation; Analytics is expanding most quickly as inference workloads unbundle from base licensing.
Application:
Use case maturity separates buyers with established data foundations from those building first-party asset pipelines.
- Lead Management:Prospecting workflows with automated scoring and routing dominate technology and professional services verticals. Procurement teams in South Korea and Mexico are piloting usage-metered contracts for these capabilities.
- Customer Retention:Churn prediction with intervention triggering is deepening penetration in subscription-heavy telecommunications and software sectors. Brazil's open banking portability mandates create first-mover advantages for cloud-native entrants here.
- Campaign Management:Cross-channel execution with budget optimization and attribution modeling.
- Contact Management:Unified customer profiles with interaction history and preference centers.
- Customer Segmentation:Clustering engines for personalization and product development targeting.
Adoption is deepest in Lead Management; Customer Retention is gaining share fastest as recurring revenue models spread.
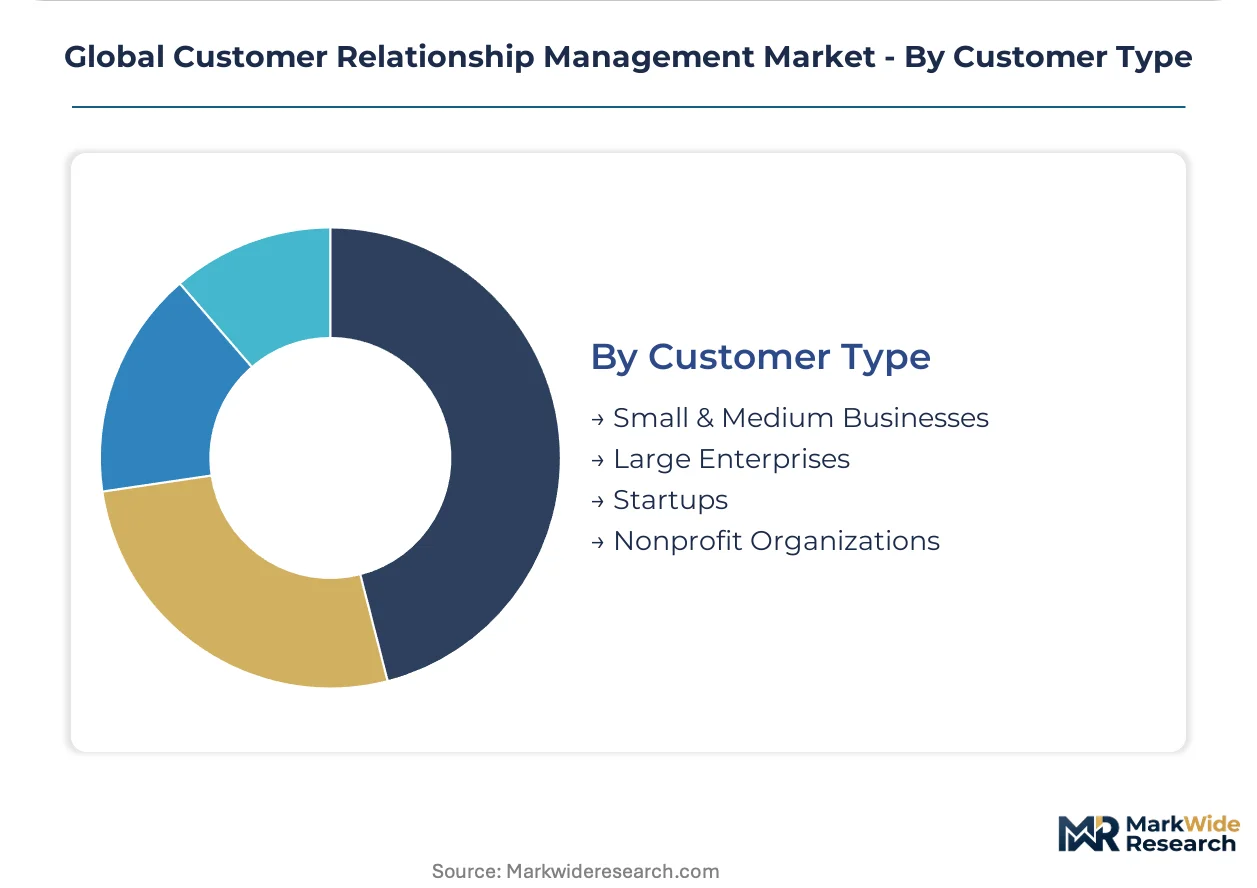
Customer Type:
Contract structure and sales motion complexity divide this category.
- Large Enterprises:Multi-year agreements with custom integration and dedicated success resources attract platform consolidation plays. Salesforce and Microsoft compete through ecosystem breadth and Office 365 anchoring respectively.
- Small & Medium Businesses:Standardized configurations with self-service onboarding and tiered feature access. Indonesia's unpenetrated manufacturing segment in Jakarta and Surabaya represents expansion opportunity despite accelerating digital payment adoption.
- Startups:Freemium entry points with growth-stage pricing escalation and API-first scalability.
- Nonprofit Organizations:Discounted licensing with donor management specialization and grant compliance reporting.
Contract value peaks with Large Enterprises; Small & Medium Businesses show the steepest expansion trajectory as vertical solutions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment concentrates in jurisdictions with clear data sovereignty frameworks. Regulatory divergence across major economies fragments deployment architectures and vendor selection criteria.
United States
HIPAA audit mandates and SEC disclosure rules drive demand for compliance-telemetry-embedded platforms. Healthcare systems and financial services firms prioritize real-time audit trail capabilities. Silicon Valley and Seattle clusters host primary development centers for predictive engagement engines.
Germany
EU AI Act documentation requirements reshape algorithmic decision workflows in banking and insurance. GDPR Article 22 enforcement necessitates human-in-the-loop interfaces for credit-sensitive lead scoring. Frankfurt and Munich financial hubs deploy these compliance-integrated systems at scale.
India
BIS cloud standards and PLI scheme incentives attract foreign platform investment into domestic infrastructure. Software development centers in Bangalore and Hyderabad expand capacity for regional service delivery. Manufacturing SMEs in Gujarat and Maharashtra represent underpenetrated mid-market opportunity.
China
NMPA data localization mandates fragment multinational cloud strategies into sovereign-compliant architectures. Domestic operators build captive infrastructure to isolate customer PII from cross-border analytics workloads. Beijing and Shanghai clusters lead deployment of state-authorized platform alternatives.
Brazil
Central bank open banking mandates create first-mover advantages for cloud-native entrants in customer retention segments. Data portability requirements accelerate displacement of legacy on-premises installations. São Paulo and Rio de Janeiro financial networks pilot real-time synchronization for predictive churn intervention.
Global Customer Relationship Management Market Competitive Landscape
Global majors compete with regional champions across ecosystem breadth versus localization depth. The vendor base stratifies into three tiers: full-suite platforms with native AI, vertical specialists with industry compliance expertise, and API-first challengers with consumption-based pricing. Consolidation pressure intensifies as buyers demand unified data fabrics over point solutions. Strategic moves center on embedding machine learning inference directly within operational databases and acquiring middleware capabilities for legacy system abstraction.
Within the full-suite platform tier, Salesforce and Microsoft Dynamics occupy positions defined by ecosystem anchoring and infrastructure integration respectively. Oracle exemplifies vertical specialization through industry-specific editions targeting regulated sectors. These three entities represent distinct competitive vectors: ecosystem breadth, productivity-suite anchoring, and compliance-native verticalization.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft Dynamics |
| Oracle |
| SAP |
| Adobe |
| HubSpot |
| Zoho |
| Zendesk |
| Freshworks |
| Others |
Supply & Pricing Matrix
Mid-market procurement teams in South Korea and Mexico are demanding usage-metered contracts that unbundle AI inference from base platform licensing, forcing vendors to restructure cost allocation across cloud infrastructure tiers and compress margin capture at the entry level.
Pricing Analysis
Service-level guarantees with compliance telemetry bundling separate premium tiers from standard offerings. Pricing stratifies across enterprise, mid-market, and entry tiers based on data residency certification, AI inference volume, and dedicated success resources. Cost compression in the mid-market tier is intensifying because hyperscaler infrastructure commoditizes core platform access. Small and medium businesses exhibit the highest price sensitivity, while large enterprises with multi-year contracts show the least.
Supply Chain Analysis
Regional distribution centers in Ireland, Singapore, and Virginia anchor hub-and-spoke delivery for cloud infrastructure serving European, Asia-Pacific, and North American demand nodes. Platform development draws from engineering talent pools in India, Poland, and Vietnam, with specialized ML operations concentrated in the United States and United Kingdom. Single-source vulnerability in GPU allocation for training workloads creates supply risk. Distribution runs through direct enterprise sales with partner-led implementation for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time data pipeline infrastructure faces capacity constraints from specialized stream processing hardware scarcity, propping pricing power for vendors with captive cloud capacity.
For Market Incumbents: Lock in ecosystem loyalty by embedding machine learning inference directly within operational databases before challengers consolidate around API-first alternatives. Acquire middleware capabilities for legacy system abstraction to defend against vertical specialists with compliance-native positioning. Prioritize FedRAMP and NIST 800-171 certification investment to capture defense and government health system demand. For New Entrants and Emerging Players: Cloud-native channel partnerships with systems integrators in Jakarta and Surabaya offer the most penetrable route into Indonesia's unpenetrated SME manufacturing segment. Pilot consumption-based pricing with usage-metered AI inference to differentiate from incumbent subscription bundles. Target Brazil's open banking regulatory tailwind for customer retention solution entry. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing industry-specific compliance expertise given EU AI Act enforcement accelerating algorithmic decision documentation requirements. Long-term viability favors platforms with data gravity advantages in telecommunications and retail banking. Watch for inflection when mid-market procurement teams in technology and professional services verticals achieve critical mass in usage-metered contract renegotiation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies marketing automation, sales forecasting, and service ticketing into single data fabric for GDPR Article 22 compliance. |
| Acquisition of Specialist Firm | Adds middleware capabilities for mainframe-era customer database abstraction in United States and United Kingdom financial institutions. |
| Geographic Expansion | Establishes software development centers in Bangalore and Hyderabad to capture PLI scheme incentives for regional service delivery. |
| Strategic Partnership | Aligns with hyperscaler infrastructure to secure GPU allocation for sub-100-millisecond predictive engagement engine deployment. |
| Product Launch | Introduces human-in-the-loop decision interfaces for credit-sensitive lead scoring in Italian and Spanish financial services markets. |
Research Methodology
Document review covered SEC filings, hyperscaler capex disclosures, and EU regulatory enforcement records, complemented by interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across retail banking, telecommunications, and healthcare verticals. Secondary validation drew from GDPR enforcement actions, HIPAA audit findings, BIS cloud standard documentation, and open banking regulatory filings. Bottom-up deployment estimates and top-down market sizing were triangulated for consistency.
Output projections reflect segment-level modeling across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern throughout the forecast period. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points and infrastructure investment cycles. Forecast inputs incorporated cloud infrastructure capacity expansion timelines and compliance certification pipeline durations.
The model holds under steady regulatory enforcement intensity and stable hyperscaler pricing; deviation in data localization mandate expansion or GPU supply disruption would shift trajectory. Forecasts reflect documented assumptions about buyer procurement behavior evolution and vendor consolidation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market
Customer Relationship Management (CRM)
Pharmaceutical Customer Relationship Management (CRM) Software Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market