
 Call Center Market | 2026-2036
Call Center Market Size, Share, and Industry Trends Forecast 2026-2036
Call Center Market Analysis
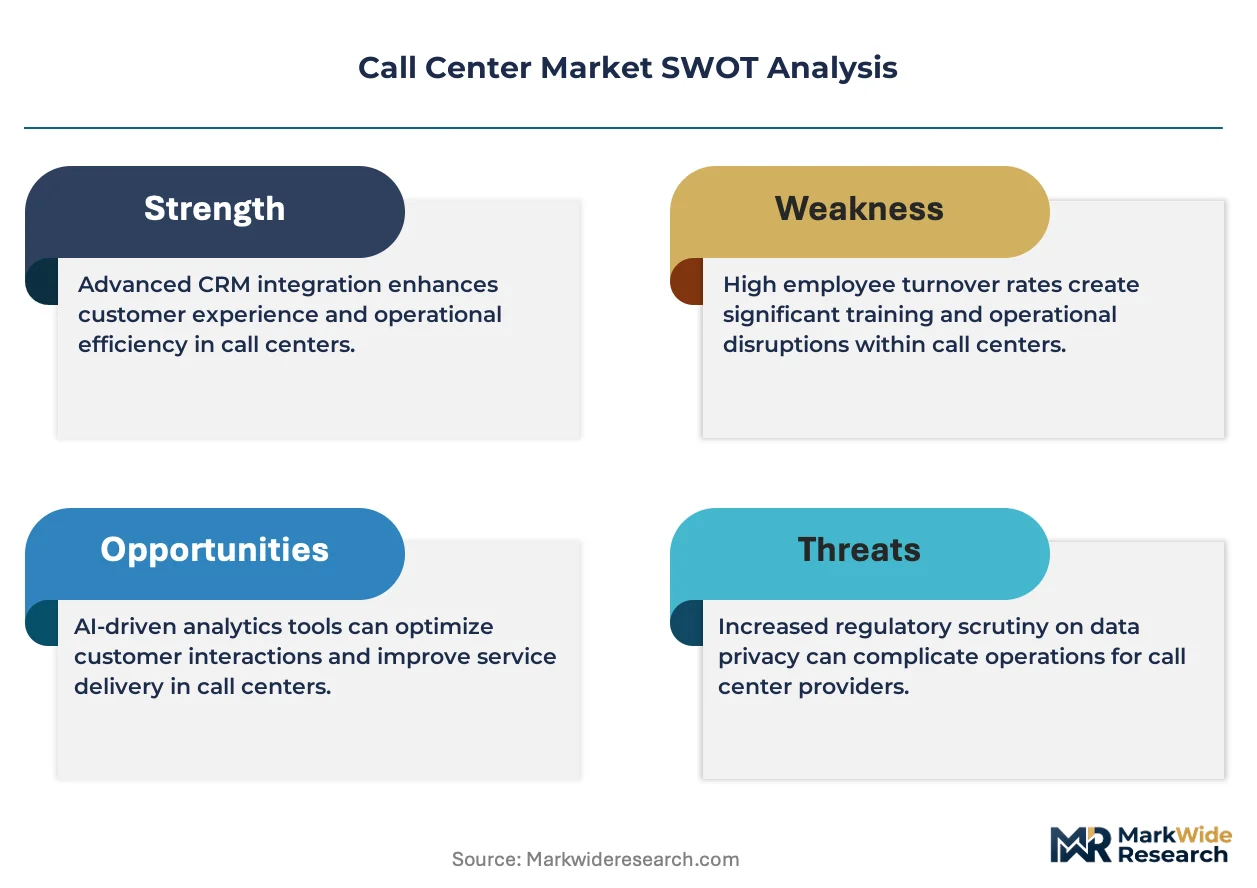
The capability gap between cloud-native and premise-bound infrastructure is collapsing as enterprise buyers demand elastic capacity and real-time analytics. Teleperformance sustains one of the largest global agent networks across six continents, while Concentrix leverages vertical specialization in healthcare and retail to command premium contract terms. Tata Consultancy Services anchors its call center portfolio within broader IT transformation deals, competing on integrated delivery rather than standalone voice services.
A call center constitutes a centralized facility or distributed virtual environment designed to manage high-volume customer interactions through voice, digital, and automated channels, typically incorporating automatic call distribution systems with sub-second routing algorithms and interactive voice response menus handling sixty to eighty percent of initial queries without human intervention. Its primary commercial purpose centers on resolving customer issues, driving sales conversions, and capturing structured feedback data for operational intelligence. Inbound service types now dominate contract value as subscription businesses prioritize retention over acquisition, while automated segments grow fastest as natural language processing reduces per-contact costs. Enterprise customer types generate the deepest margin pools due to multi-year outsourcing agreements with custom SLA tiers, whereas SMB demand fragments across pay-per-use platforms.
The Federal Communications Commission enforces strict telemarketing consent frameworks under the Telephone Consumer Protection Act, while the Health Insurance Portability and Accountability Act imposes encryption and access-log mandates on healthcare call centers handling protected health information. India's Telecom Regulatory Authority governs outbound dialing permissions and Do-Not-Disturb registry compliance for offshore delivery centers serving North American clients. Stakeholders must monitor evolving AI disclosure requirements as regulators in multiple jurisdictions draft rules mandating bot-to-human handoff transparency and algorithmic audit trails.
Market Dynamics
Cloud migration and AI-powered routing systems are collapsing the capability gap between elastic infrastructure and premise-bound legacy stacks, forcing buyers to renegotiate contract terms around real-time analytics and automated quality assurance.
Growth Catalysts
- HIPAA Encryption Mandates:Healthcare providers expand call center investments to manage patient scheduling and triage workflows under strict access-log requirements, creating durable demand for compliant outsourcing partners.
- Natural Language Processing:Automated voice systems now resolve sixty to eighty percent of initial queries without human intervention, compressing per-contact costs and accelerating self-service adoption.
- Labor Arbitrage in South Asia:India and the Philippines sustain large-scale delivery footprints through English-language proficiency and timezone coverage, anchoring offshore contract growth.
Market Restraints
- Agent Attrition Volatility:Wage inflation in Manila and Bangalore delivery clusters erodes margin structures that depend on stable workforce economics.
- Telemarketing Consent Friction:The FCC's Telephone Consumer Protection Act imposes strict dialing permissions and penalty frameworks, constraining outbound revenue streams.
- Legacy System Entrenchment:Premise-based automatic call distribution hardware in enterprise accounts resists cloud displacement due to capital recovery timelines.
Strategic Opportunities
- AI Disclosure Rulemaking:Multiple jurisdictions draft bot-to-human handoff transparency mandates, creating first-mover advantage for vendors with auditable algorithmic trails.
- Vertical Specialization:Healthcare and retail segments command premium contract terms through custom SLA tiers and domain-specific agent training protocols.
- Subscription Retention Economics:Inbound service types now dominate contract value as recurring-revenue businesses prioritize churn reduction over acquisition spend.
Industry Challenges
- Bilingual Technical Talent Scarcity:Complex troubleshooting across voice and digital channels demands agents with both language fluency and systems integration literacy.
- Multi-Cloud Orchestration Complexity:Enterprise buyers demand elastic capacity across AWS, Azure, and Google Cloud environments, straining vendor operational consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Call Center Market |
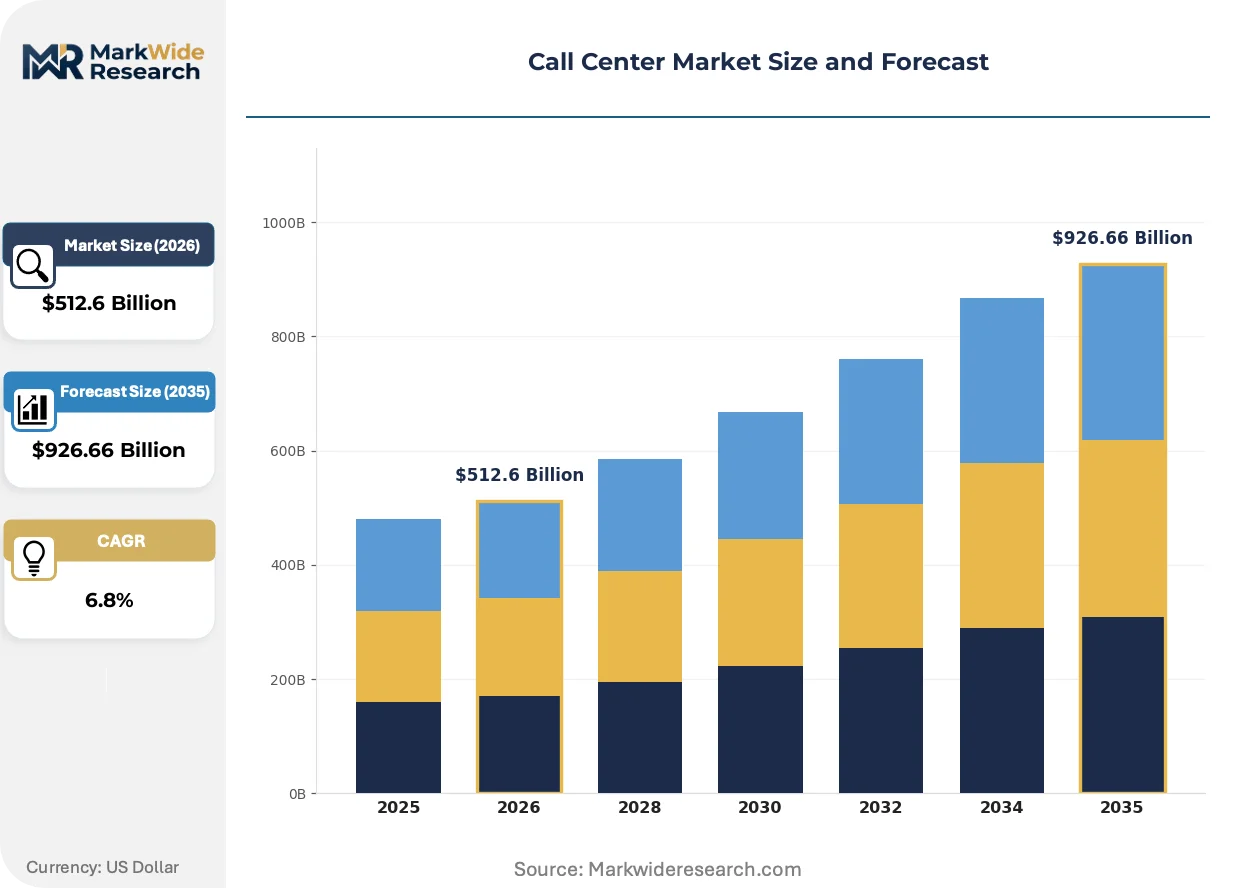
| Market Size in 2026 | $512.6 Billion |
| Market Size in 2035 | $926.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inbound, Outbound, Blended, Automated Technology: VoIP, ACD, IVR, CRM Customer Type: Enterprise, SMB, Government, Non-profit Industry Vertical: Telecommunications, Healthcare, Retail, Financial Services |
| Companies Covered | Alorica, Tata Consultancy Services, Teleperformance, iQor, TaskUs, Concentrix, TTEC, Five9, Foundever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Call Center Market Emerging Trajectories
Conversational AI and real-time sentiment analysis are reconfiguring workforce deployment models, compressing the interval between customer intent detection and resolution routing.
Edge-deployed speech recognition is miniaturizing latency requirements for voice biometrics and emotion detection, enabling sub-second authentication in financial services call flows. Retail banks and insurance underwriters pilot these capabilities at scale. The technology is miniaturizing hardware footprints in branch-adjacent micro-contact centers.
India's Telecom Regulatory Authority enforces Do-Not-Disturb registry compliance and outbound dialing permissions for offshore delivery centers serving North American clients. TRAI's 2023 framework amendments tightened consent documentation requirements. Healthcare and financial services verticals face the steepest compliance recalibration.
Enterprise procurement teams unbundle after-sales support from long-term outsourcing agreements, preferring pay-per-resolution models with transparent quality scoring. Tier-one technology vendors resist this shift while mid-market platforms capture fragmented demand. The pattern concentrates in United States subscription software and telecommunications accounts.
Call Center Market Segmentation
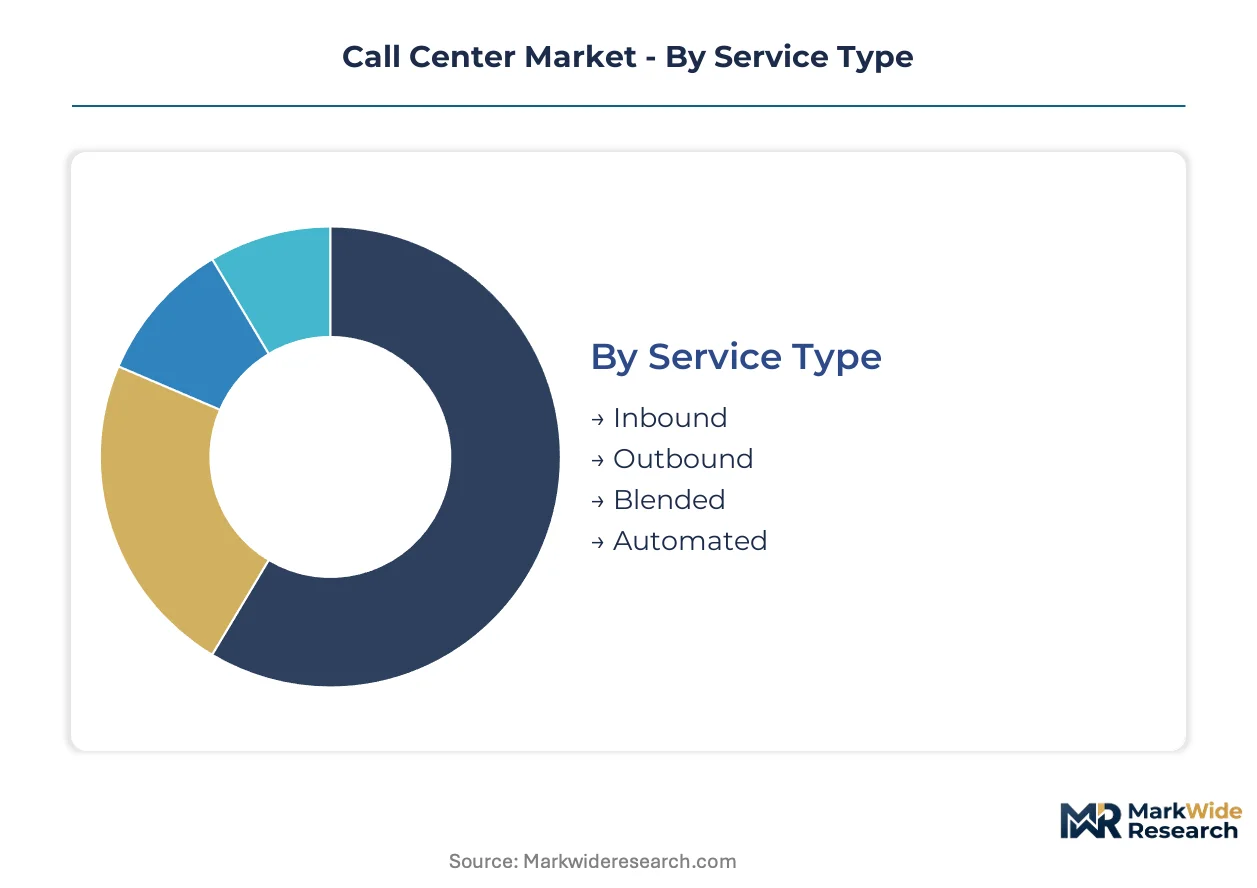
Call center procurement teams segment contracts around channel-mix requirements, balancing voice traffic volumes against digital integration complexity. Each segmentation dimension reveals distinct margin structures and vendor selection criteria that reshape competitive positioning.
Service Type:
Channel-mix dynamics determine which service types flow through voice-dominant infrastructure versus automated self-service portals versus blended human-digital workflows.
- Inbound:Subscription businesses prioritize retention-focused support desks handling billing disputes and technical troubleshooting through live agent channels. Enterprise software and telecommunications providers in the United States concentrate contract value here as churn reduction economics outweigh acquisition spend.
- Automated:Natural language processing engines now resolve sixty to eighty percent of initial queries without human handoff, compressing per-contact costs for high-volume, low-complexity interactions. Healthcare appointment scheduling and retail order status checks drive adoption.
- Outbound:FCC telemarketing consent frameworks constrain dialing permissions, limiting revenue streams to compliant lead generation and customer satisfaction surveys.
- Blended:Agents rotate between inbound queues and proactive outreach campaigns, maximizing seat utilization during demand troughs.
By volume, Inbound leads. By growth pace, Automated is expanding most quickly.
Technology:
Cost tier separation distinguishes premium real-time analytics stacks from baseline connectivity infrastructure, with integration depth determining contract pricing bands.
- ACD:Automatic call distribution systems route interactions through sub-second algorithms matching customer intent to agent skill profiles. Financial services fraud prevention queues in India and the Philippines demand this capability.
- CRM:Customer relationship management integration captures structured feedback data for operational intelligence, commanding premium terms in healthcare and retail verticals with custom SLA requirements.
- IVR:Interactive voice response menus handle initial query triage before human escalation.
- VoIP:Voice over Internet Protocol enables elastic capacity scaling across distributed agent pools.
By deployment scale, VoIP dominates. By margin contribution, CRM integration delivers the steepest expansion trajectory.
Customer Type:
Application complexity varies sharply between multi-year outsourcing agreements with custom infrastructure and pay-per-use platform consumption.
- Enterprise:Multi-year agreements with dedicated infrastructure and custom SLA tiers generate the deepest margin pools. Tier-one technology vendors anchor delivery through integrated IT transformation deals rather than standalone voice services.
- SMB:Fragmented demand concentrates across pay-per-resolution platforms with transparent quality scoring, capturing subscription software and telecommunications accounts in the United States.
- Government:Procurement emphasizes compliance documentation and security clearance requirements.
- Non-profit:Donor management and volunteer coordination drive seasonal capacity spikes.
By contract value concentration, Enterprise leads. By platform adoption velocity, SMB is gaining share fastest.
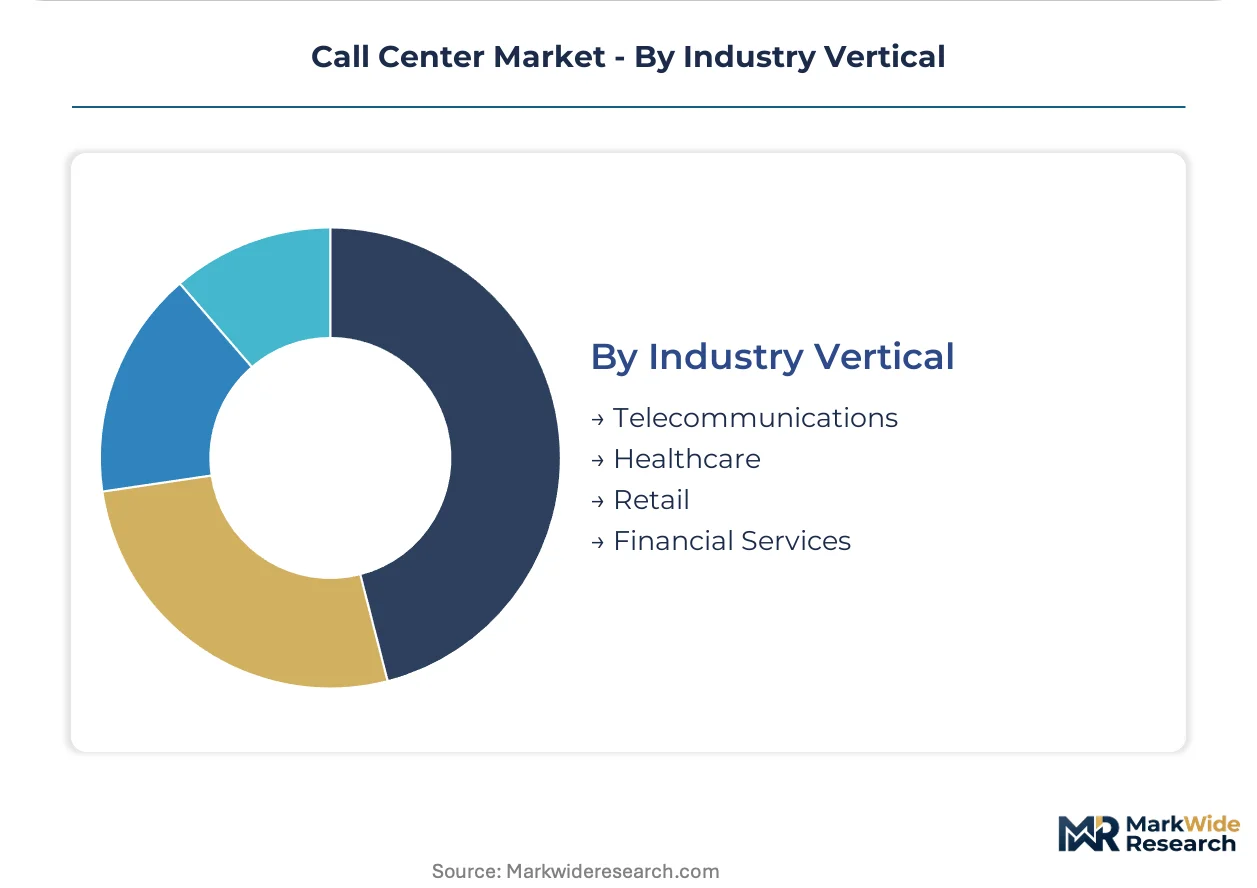
Industry Vertical:
Volume distribution reflects sector-specific regulatory burdens and customer interaction frequencies, with HIPAA encryption mandates and FCC consent frameworks reshaping vendor qualification criteria.
- Healthcare:Patient scheduling and triage workflows require HIPAA-compliant access-log systems and encrypted data handling, creating durable demand for specialized outsourcing partners. Providers expand investments to manage appointment logistics and nurse advice lines.
- Financial Services:Edge-deployed speech recognition enables sub-second voice biometric authentication for fraud prevention, with retail banks and insurance underwriters piloting these capabilities at scale.
- Telecommunications:Subscription retention economics prioritize inbound service desks handling billing and technical support.
- Retail:Order status checks and returns processing drive automated self-service adoption.
By outsourcing penetration depth, Telecommunications leads. By compliance-driven investment growth, Healthcare is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Western Europe demonstrate low price elasticity for HIPAA-compliant healthcare outsourcing, while procurement teams in emerging markets prioritize labor arbitrage over premium service tiers.
United States
Healthcare providers and subscription software vendors drive demand for retention-focused inbound desks with custom SLA tiers. The FCC's Telephone Consumer Protection Act imposes strict telemarketing consent frameworks and penalty structures. Dallas-Fort Worth and Phoenix anchor major delivery clusters where cloud-native infrastructure displaces legacy premise-based systems.
India
English-language proficiency and timezone coverage sustain large-scale offshore delivery for North American healthcare and financial services clients. TRAI's Do-Not-Disturb registry compliance and 2023 consent documentation amendments tighten operational requirements. Bangalore and Manila delivery clusters face wage inflation pressures that erode traditional margin structures.
Philippines
Voice-centric customer service and technical support workflows dominate contract volumes for US telecommunications and retail accounts. The national telecom regulator enforces outbound dialing permissions and consumer protection standards for offshore delivery centers. Metro Manila and Cebu City concentrate agent workforce pools experiencing attrition volatility.
Germany
Automotive and industrial machinery verticals demand multilingual technical support with embedded CRM integration. GDPR and the EU AI Act impose algorithmic audit trail and bot-to-human handoff transparency requirements. Frankfurt and Munich host specialized delivery centers serving DAX-listed enterprise accounts.
United Kingdom
Financial services fraud prevention and retail banking voice biometrics pilot programs accelerate technology investment. The Financial Conduct Authority and Information Commissioner's Office enforce data handling and AI disclosure standards. London and Manchester clusters focus on high-value compliance-heavy outsourcing relationships.
Call Center Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the top stratum anchoring delivery through multi-year IT transformation bundles rather than standalone voice contracts. The middle tier competes on vertical specialization in healthcare and retail, commanding premium terms through domain-specific agent training protocols. Two strategic archetypes dominate: scale-driven global networks optimizing seat utilization across time zones, and technology-forward platforms embedding conversational AI into core routing infrastructure. Competitive moves concentrate on cloud migration partnerships and automated quality assurance capabilities.
Among integrated outsourcing leaders, Teleperformance exemplifies the scale-driven archetype with six-continent agent network coverage, while Concentrix occupies a position within the vertical specialization tier. Tata Consultancy Services anchors the IT-integrated delivery model, competing on bundled transformation services rather than isolated call center contracts.
| Leading Market Players |
|---|
| Alorica |
| Tata Consultancy Services |
| Teleperformance |
| iQor |
| TaskUs |
| Concentrix |
| TTEC |
| Five9 |
| Foundever |
| Others |
Supply Flow & Price Mechanics
FCC telemarketing consent frameworks under the Telephone Consumer Protection Act gate both vendor qualification and price differentiation simultaneously, forcing offshore delivery centers to absorb compliance documentation costs that separate premium HIPAA-certified providers from commodity voice operators. Healthcare and financial services buyers in the United States pay elasticity premiums for encrypted access-log systems while SMB procurement teams fragment across pay-per-resolution platforms.
Pricing Analysis
Extended service contracts and multi-year outsourcing agreements drive lifetime value for enterprise customer types. Pricing stratifies across premium, standard, and economy tiers based on custom SLA requirements and vertical specialization depth. Cost compression in offshore delivery clusters is intensifying because wage inflation in Manila and Bangalore erodes traditional labor arbitrage margins. Enterprise buyers demonstrate low price sensitivity for compliant healthcare outsourcing, while SMB segments concentrate on transparent pay-per-use platforms.
Supply Chain Analysis
Inventory and lead-time requirements for cloud-native infrastructure have collapsed as elastic capacity scales across distributed agent pools. Supply concentration rests in the United States, India, and the Philippines, where English-language proficiency and timezone coverage sustain large-scale delivery footprints. Agent workforce pools, sub-second routing algorithms, and encrypted data handling systems constitute critical input dependencies. Single-source vulnerability concentrates in Metro Manila delivery clusters experiencing attrition volatility. Distribution runs through multi-year outsourcing agreements with tier-one technology vendors and fragmented pay-per-use platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Call center procurement is approaching a platform-economics inflection as enterprise buyers unbundle after-sales support from long-term agreements and demand API-first interoperability with CRM and workforce management systems.
For Market Incumbents: Consolidate cloud migration partnerships and automated quality assurance capabilities to defend against mid-market platforms capturing fragmented SMB demand. Vertical specialization in healthcare and retail commands premium contract terms through domain-specific agent training protocols. Capacity consolidation in India and the Philippines offsets wage inflation pressures eroding traditional margin structures.
For New Entrants and Emerging Players: HIPAA compliance fast-track programs create white-space entry points for healthcare call center outsourcing. Target pay-per-resolution platform segments in United States subscription software and telecommunications accounts where tier-one vendors resist unbundling shifts. Lead with transparent quality scoring and real-time analytics integration as primary go-to-market positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated self-service infrastructure as natural language processing compresses per-contact costs. Long-term viability favors technology-forward platforms embedding conversational AI over scale-driven seat-utilization models. Acquisition targets should demonstrate auditable algorithmic trails for impending AI disclosure mandates. Monitor bot-to-human handoff transparency rulemaking across multiple jurisdictions as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Migration Partnership | Elastic capacity scaling displaces legacy premise-based automatic call distribution hardware in Dallas-Fort Worth clusters. |
| Vertical Specialization Program | Healthcare and retail domain-specific agent training protocols command premium contract terms through custom SLA tiers. |
| AI Disclosure Compliance Investment | Auditable algorithmic trails create first-mover advantage as regulators draft bot-to-human handoff transparency mandates. |
| Automated Quality Assurance Deployment | Real-time sentiment analysis compresses the interval between customer intent detection and resolution routing. |
| Geographic Workforce Consolidation | Bangalore and Manila delivery cluster optimization offsets wage inflation pressures eroding traditional margin structures. |
Methodological Framework
A spread of perspectives from call center operations directors, healthcare compliance officers, IT procurement managers, and offshore delivery center executives converged on the working assumptions driving this analysis. Primary interviews with workforce management vendors and enterprise outsourcing buyers combined with secondary validation from FCC regulatory filings, TRAI framework amendments, SEC 10-K disclosures from tier-one vendors, and healthcare GPO contract databases. Bottom-up agent seat capacity estimates and top-down contract value aggregation triangulated market sizing.
Segmentation dimensions modeled include service type, technology deployment, customer scale tier, and industry vertical across the projection horizon. Inbound-automated-outbound-blended channel mix, ACD-CRM-IVR-VoIP technology stack penetration, and HIPAA-FCC-TRAI regulatory compliance clusters shaped analytical frameworks. CAGRs derived from elasticity-adjusted demand curves and labor cost trajectory modeling. Forecast inputs incorporated cloud migration velocity and natural language processing adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable regulatory enforcement intensity and continued cloud infrastructure cost decline; material deviation in AI disclosure rulemaking timelines or offshore wage inflation spikes would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Online CRM Software Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Customer Communication Management Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
US Customer Relationship Management Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Global CRM197 Market