
 Lead Management Market | 2026-2036
Lead Management Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Management Market Foresight
Mid-market B2B enterprises is redrawing the demand map for lead management solutions as these buyers replace legacy spreadsheet workflows with integrated CRM platforms. Salesforce leverages its AppExchange ecosystem to extend platform stickiness across verticals. HubSpot anchors the SMB segment through freemium-to-paid conversion funnels. Oracle competes at the enterprise tier with database-native integration capabilities that reduce implementation friction.
Lead management encompasses the systematic capture, qualification, distribution, and nurturing of prospective customer contacts through automated workflows and scoring algorithms, typically operating within CRM architectures that enforce data hygiene protocols and consent tracking. Cloud-based deployment models command the largest revenue pool due to lower total cost of ownership and faster implementation cycles, while SaaS delivery is gaining share fastest among startups and marketing agencies that prioritize subscription flexibility over capital expenditure. CRM integration solutions sit at the core of most technology stacks, though analytics modules are emerging as the highest-margin attach category as buyers demand predictive lead scoring and attribution modeling.
GDPR enforcement by European data protection authorities and state-level privacy statutes in the United States are mandating granular consent logging and right-to-deletion capabilities within lead databases, forcing vendors to embed compliance tooling natively rather than bolt on after deployment. The EU AI Act adds algorithmic transparency requirements for automated lead scoring systems that deploy machine learning models. Stakeholders must evaluate whether their current platforms can absorb emerging regulatory layers without custom development overhead.
Market Dynamics
Cloud-native architectures are displacing on-premise lead management deployments as mid-market B2B buyers prioritize subscription flexibility over capital-intensive infrastructure ownership. This infrastructure shift compresses vendor switching costs while elevating API interoperability as a procurement criterion.
Growth Catalysts
- GDPR Enforcement:European data protection authorities mandate granular consent logging and right-to-deletion capabilities, forcing database hygiene investments that expand platform attach rates for compliance modules.
- Marketing Agencies:These buyers prioritize SaaS delivery models that eliminate server maintenance overhead and accelerate campaign deployment cycles without IT dependency.
- Predictive Scoring Algorithms:Machine learning models embedded within CRM architectures automate lead qualification workflows, reducing manual sales development representative hours per qualified opportunity.
Market Restraints
- Integration Complexity:Legacy ERP systems in manufacturing and financial services require custom API development that extends implementation timelines and inflates professional services costs.
- Talent Scarcity:The shortage of data engineers capable of configuring attribution models and maintaining ETL pipelines constrains platform utilization rates among mid-market adopters.
- EU AI Act:Algorithmic transparency requirements for automated lead scoring systems impose documentation burdens that increase compliance overhead for vendors deploying machine learning models.
Strategic Opportunities
- India:The country's PLI scheme for IT hardware and expanding SaaS startup ecosystem creates demand for localized lead management platforms with vernacular language support and domestic data residency.
- Account-Based Marketing Convergence:The integration of intent data platforms with lead management workflows enables precision targeting at named accounts, compressing sales cycles for enterprise technology vendors.
- Revenue Operations Function:The emergence of RevOps as a dedicated organizational role creates demand for unified platforms that consolidate marketing automation, sales engagement, and customer success data.
Industry Challenges
- Data Stewardship Expertise:Organizations lack personnel capable of enforcing governance protocols across distributed marketing technology stacks, resulting in duplicate records and degraded scoring accuracy.
- Multi-Touch Attribution Complexity:Buyers struggle to validate return on ad spend when customer journeys span paid social, programmatic display, and organic search touchpoints with divergent tracking methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Management Market |
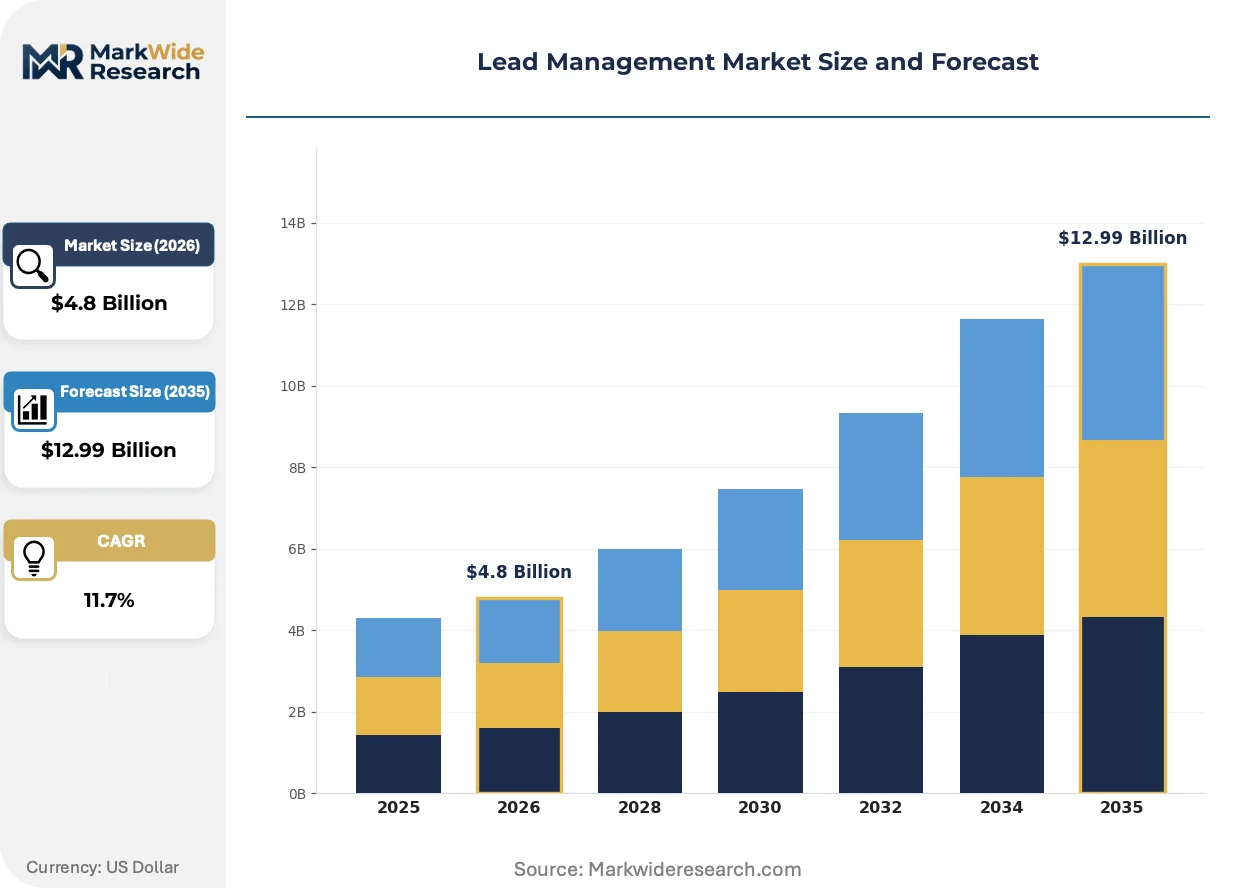
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS Solution Type: CRM Integration, Marketing Automation, Data Management, Analytics End User: B2B Enterprises, SMBs, Marketing Agencies, Telemarketers Customer Segment: Small Businesses, Large Corporations, Startups, Others |
| Companies Covered | Salesforce, HubSpot, Oracle, IBM, Microsoft, Zoho Corporation, SAP, Adobe, Pipedrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Management Market Shifts & Advancements
Artificial intelligence capabilities are redistributing competitive advantage from data volume holders to algorithmic sophistication providers. Vendors now differentiate through model interpretability rather than database scale.
Natural language processing engines for conversational lead qualification are fragmenting the sales development representative function. These systems interpret email responses and chat transcripts to schedule meetings without human intervention. Technology vendors and B2B SaaS providers deploy these tools fastest. The technology is fragmenting traditional inside sales team structures into specialized creative and technical roles.
The EU AI Act imposes explainability requirements on automated decision systems used for lead scoring and prioritization. Vendors must document training data provenance and model performance metrics for audit trails. European financial services and healthcare technology buyers now require algorithmic transparency documentation before procurement authorization.
Revenue operations teams now mandate native integration between lead management platforms and business intelligence tools rather than accepting CSV export workflows. This expectation compresses vendor evaluation cycles around API depth rather than feature breadth. The shift is most visible among Series C and later-stage software companies in the United States consolidating their marketing technology stacks.
Lead Management Market Segmentation
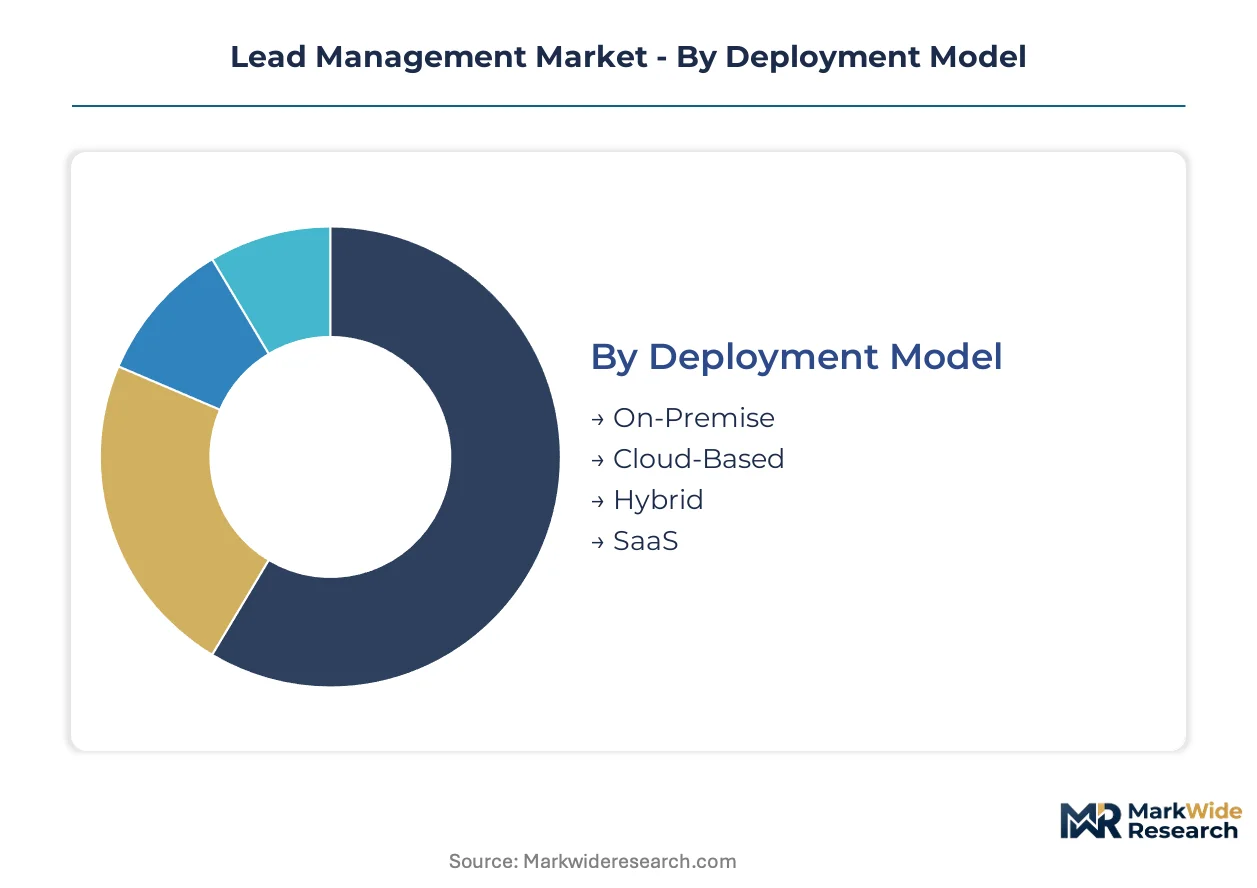
Lead management segmentation reveals how deployment choices, solution architectures, and buyer profiles reshape competitive dynamics. Vendors must align platform capabilities with specific compliance burdens and integration requirements across buyer tiers.
Deployment Model:
GDPR enforcement and the EU AI Act impose divergent infrastructure requirements across deployment architectures, with data residency mandates and algorithmic audit trails driving procurement decisions.
- Cloud-Based:Multi-tenant architectures with automatic scaling and regional data centers satisfy GDPR residency requirements without capital expenditure. Mid-market B2B enterprises in Germany and France favor this model for rapid deployment and built-in consent logging capabilities.
- SaaS:Subscription billing eliminates server maintenance overhead while embedding compliance updates through centralized vendor management. Marketing agencies across the United States and United Kingdom prioritize this model for campaign velocity and IT independence.
- On-Premise:Air-gapped installations serve financial services and healthcare buyers with strict data sovereignty requirements.
- Hybrid:Split architectures allow sensitive lead data on-premise while offloading analytics workloads to cloud infrastructure.
Established volume favors Cloud-Based; emerging adoption favors SaaS.
Solution Type:
Margin concentration varies sharply across solution categories, with predictive capabilities commanding premium pricing against commoditized integration tooling.
- Analytics:Machine learning models for lead scoring and attribution modeling deliver the highest attach rates and renewal premiums. B2B technology vendors in California and Massachusetts demand predictive forecasting and multi-touch attribution as standard procurement requirements.
- CRM Integration:API-native connectors to Salesforce, HubSpot, and Oracle databases reduce implementation friction and professional services overhead. Large corporations across Texas and Illinois prioritize pre-built integrations over custom development.
- Marketing Automation:Workflow engines for email sequencing and nurture campaigns serve high-volume lead generation operations.
- Data Management:Hygiene tools for deduplication, enrichment, and consent tracking address GDPR deletion mandates.
Revenue concentration sits with Analytics; deployment velocity sits with CRM Integration.
End User:
Customer sophistication determines feature requirements, with enterprise buyers demanding API depth and compliance documentation that smaller buyers overlook.
- B2B Enterprises:Complex sales cycles with multiple stakeholders require account-based routing and territory management. Manufacturing and industrial technology buyers in Ohio and Michigan invest heavily in lead-to-revenue tracking across field sales organizations.
- Marketing Agencies:Multi-client architectures with white-label reporting and cross-account benchmarking differentiate vendor selection. Boutique agencies in New York and London prioritize rapid campaign deployment without technical implementation.
- SMBs:Simplified interfaces and out-of-box templates reduce onboarding friction for resource-constrained buyers.
- Telemarketers:Dialer integration and real-time lead distribution optimize call center productivity metrics.
Contract value concentrates with B2B Enterprises; seat expansion concentrates with Marketing Agencies.
Customer Segment:
Organizational maturity shapes platform selection criteria, with funding stage determining acceptable implementation timelines and customization depth.
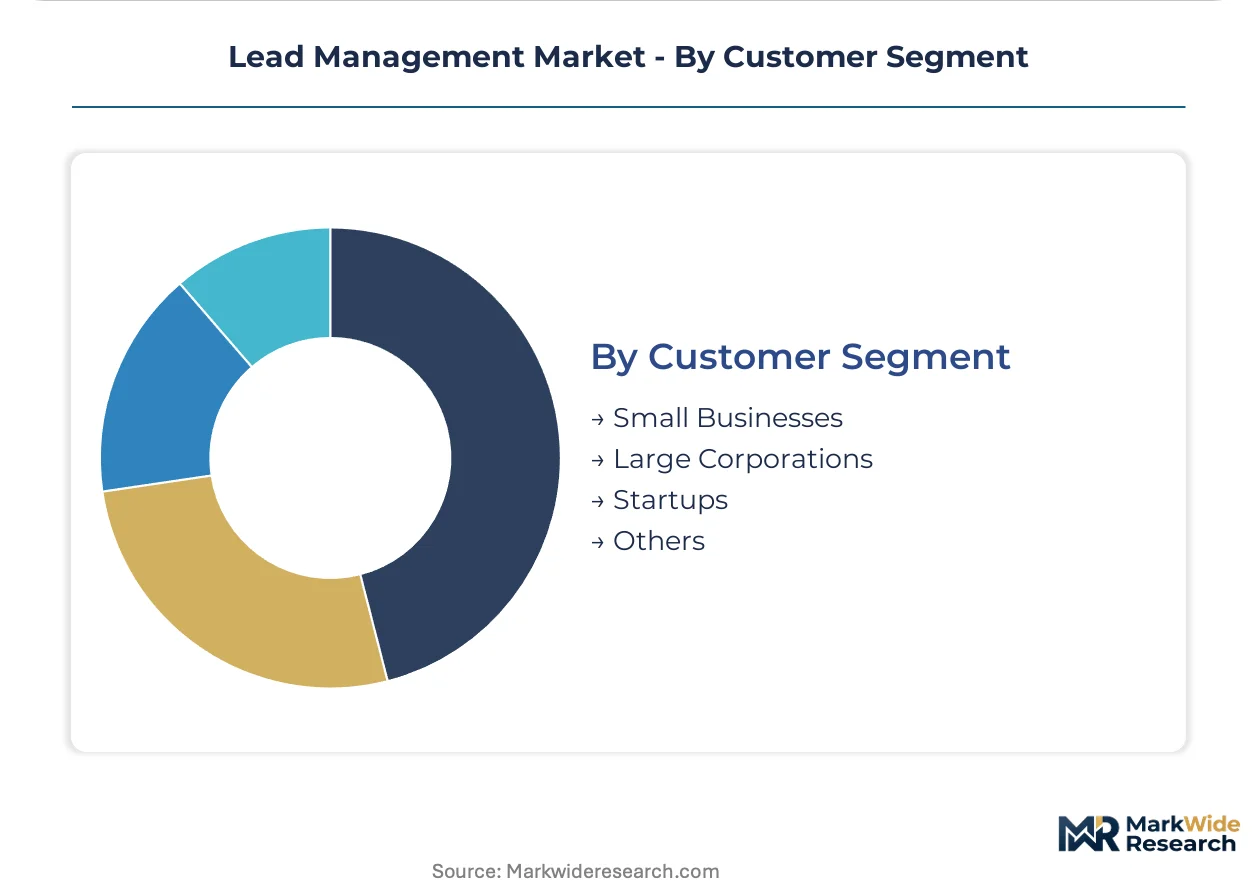
- Large Corporations:Procurement committees mandate SOC 2 certification, single sign-on, and dedicated customer success coverage. Fortune 500 technology divisions in Washington and New Jersey require vendor financial stability and enterprise liability coverage.
- Startups:Venture-backed companies prioritize speed-to-value and product-led growth tooling over comprehensive feature sets. SaaS founders in Austin and Berlin favor platforms with generous free tiers and rapid time-to-first-campaign.
- Small Businesses:Owner-operator buyers select based on monthly cost and minimal training requirements.
- Others:Nonprofit and educational institutions access discounted licensing with restricted feature scopes.
Retention economics favor Large Corporations; growth velocity favors Startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based SaaS vendors export cloud-native lead management platforms to mid-market buyers across Germany, United Kingdom, and India, with GDPR compliance modules bundled as standard for European deployments.
United States
Enterprise technology buyers in California and Massachusetts prioritize predictive analytics and multi-touch attribution as procurement requirements. HIPAA and state-level privacy statutes mandate granular consent logging for healthcare-adjacent lead databases. Austin and San Francisco host venture-backed SaaS startups favoring platforms with rapid time-to-first-campaign capabilities.
Germany
Industrial manufacturing buyers in Bavaria and North Rhine-Westphalia invest heavily in lead-to-revenue tracking across field sales organizations. GDPR enforcement by the country's federal data protection authority requires right-to-deletion capabilities and algorithmic transparency documentation. Frankfurt's financial services cluster demands SOC 2 certification and dedicated customer success coverage from vendors.
United Kingdom
Marketing agencies in London prioritize rapid campaign deployment without technical implementation overhead. The Information Commissioner's Office enforces consent logging mandates that expand platform attach rates for compliance modules. Manchester's expanding B2B technology sector drives demand for account-based routing and territory management features.
India
The country's PLI scheme for IT hardware and expanding SaaS startup ecosystem creates demand for localized platforms with vernacular language support. RBI data localization guidelines influence procurement decisions for financial services buyers. Bangalore and Hyderabad host marketing technology adopters prioritizing subscription flexibility over capital expenditure.
Japan
Enterprise buyers in Tokyo and Osaka demand API depth and integration with legacy ERP systems. METI guidelines on data governance shape vendor selection criteria for large corporations. Nagoya's automotive technology cluster invests in lead management platforms supporting complex, multi-stakeholder sales cycles.
Lead Management Market Competitive Landscape
Listed leaders compete with private specialists across platform breadth and vertical integration depth. The vendor base organizes into three tiers: cloud-native challengers with freemium conversion funnels, database-native incumbents with enterprise integration capabilities, and vertical specialists with industry-specific compliance tooling. Dominant competitive moves include strategic partnerships to embed compliance modules natively and geographic expansion through regional data center deployments.
Within the cloud-native tier, Salesforce and HubSpot occupy positions defined by ecosystem breadth and SMB conversion mechanics respectively. Oracle anchors the database-native segment with enterprise integration capabilities that reduce implementation friction. Zoho Corporation exemplifies the private specialist archetype competing on price-accessible subscription tiers for resource-constrained buyers.
| Leading Market Players |
|---|
| Salesforce |
| HubSpot |
| Oracle |
| IBM |
| Microsoft |
| Zoho Corporation |
| SAP |
| Adobe |
| Pipedrive |
| Others |
Supply & Pricing Matrix
GDPR certification tiers gate both vendor qualification and subscription pricing simultaneously, with compliance-ready platforms commanding premium positioning against uncertified alternatives while procurement committees filter RFP responses based on documented consent-logging capabilities.
Pricing Analysis
Current-generation cloud-native platforms extract 40-60% premiums over prior-generation on-premise licenses, while next-generation AI-embedded scoring modules introduce usage-based metering atop base subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by API call volume and analytics depth. Price differentiation hinges on SOC 2 certification status and dedicated customer success coverage. Cost compression in the SMB tier intensifies because freemium conversion funnels subsidize acquisition spend. Marketing agencies exhibit highest price sensitivity; Fortune 500 technology divisions show least.
Supply Chain Analysis
Just-in-time deployment preferences dominate among marketing agencies prioritizing campaign velocity, while strategic stockpiling of implementation partners characterizes enterprise buyers extending multi-year rollouts. Software development concentrates in the United States, India, and Ireland; cloud infrastructure provisioning centers on AWS, Azure, and Google Cloud regional data centers. Raw material dependencies include GPU compute capacity, open-source ML frameworks, and consent-management API libraries. Single-source vulnerability sits with hyperscaler concentration in Tier 1 data centers. Distribution runs through direct sales teams for enterprise accounts and self-service portals for sub-50-seat buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as mid-market B2B buyers resume deferred CRM replacement cycles, with GDPR enforcement deadlines acting as the forcing function for 2024-2025 procurement acceleration.
For Market Incumbents: Secure API interoperability moats by embedding native connectors to Salesforce, HubSpot, and Oracle ecosystems before challenger platforms achieve parity. Invest in vertical-specific compliance tooling for financial services and healthcare to defend against specialized entrants. Threat from cloud-native challengers with freemium mechanics demands preemptive bundling of analytics modules at standard tier pricing.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized SaaS ecosystem where vernacular language support and domestic data residency requirements have kept global vendors underpenetrated. Target marketing agencies in tier-2 Indian cities with white-label architectures and rapid deployment templates. Go-to-market angle: position as the compliance-native alternative for EU-facing exporters lacking GDPR expertise.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as multi-tenant architectures achieve scale efficiencies, compressing break-even timelines for subscription revenue streams. Long-term viability favors platforms with demonstrated net revenue retention above 110% and expanding attach rates for analytics modules. Acquisition target archetype: vertical specialists with embedded healthcare or financial services compliance tooling. Signal to watch: Series C software companies consolidating marketing technology stacks and mandating API depth over feature breadth in vendor evaluations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native API connectors to Salesforce and HubSpot reduce implementation friction and professional services overhead. |
| Geographic Expansion | Regional data center deployments in Frankfurt and Mumbai satisfy GDPR and RBI data localization mandates. |
| Strategic Partnership | Embedding compliance modules through system integrator networks accelerates enterprise procurement cycles. |
| Product Launch | Conversational lead qualification engines fragment SDR functions and capture budget from inside sales tooling. |
| Acquisition of Specialist Firm | Vertical compliance tooling for EU AI Act documentation burdens creates defensive moats in financial services. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary validation through regulatory filings anchors the qualitative findings. Interview sources include CMOs at B2B technology vendors, RevOps directors at Series C software companies, procurement leads at marketing agencies, and compliance officers at financial services firms. Secondary sources encompass SEC 10-K disclosures, GDPR enforcement actions by European data protection authorities, EU AI Act implementation guidance, and hyperscaler capex reports. Bottom-up sizing of vendor-reported seat counts triangulates against top-down TAM estimates derived from CRM spend analysis.
Sensitivity analysis around cloud adoption curves and regulatory enforcement timelines shapes the analytical framework. Segmentation dimensions modeled include deployment model, solution type, end-user category, and customer segment maturity across the projection horizon. CAGRs derive from logistic diffusion curves fitted to historical SaaS penetration patterns. Industry-specific inputs include GDPR fine trajectories and marketing technology stack consolidation rates among venture-backed companies.
Decision-makers should treat outputs as directional under base assumptions of continued mid-market B2B cloud migration and stable GDPR enforcement intensity; material deviation would warrant model refresh. Forecasts embed assumptions regarding compliance module attach rates and API interoperability standardization. Regulatory fragmentation beyond current EU AI Act scope or hyperscaler pricing discontinuities would revise projections. Revision becomes warranted when net revenue retention benchmarks for installed base platforms cross 95% thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Global Customer Experience Management Software Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
CRM Analytics Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market