
 Key Opinion Leader Management Market | 2026-2036
Key Opinion Leader Management Market Size, Share, and Industry Trends Forecast 2026-2036
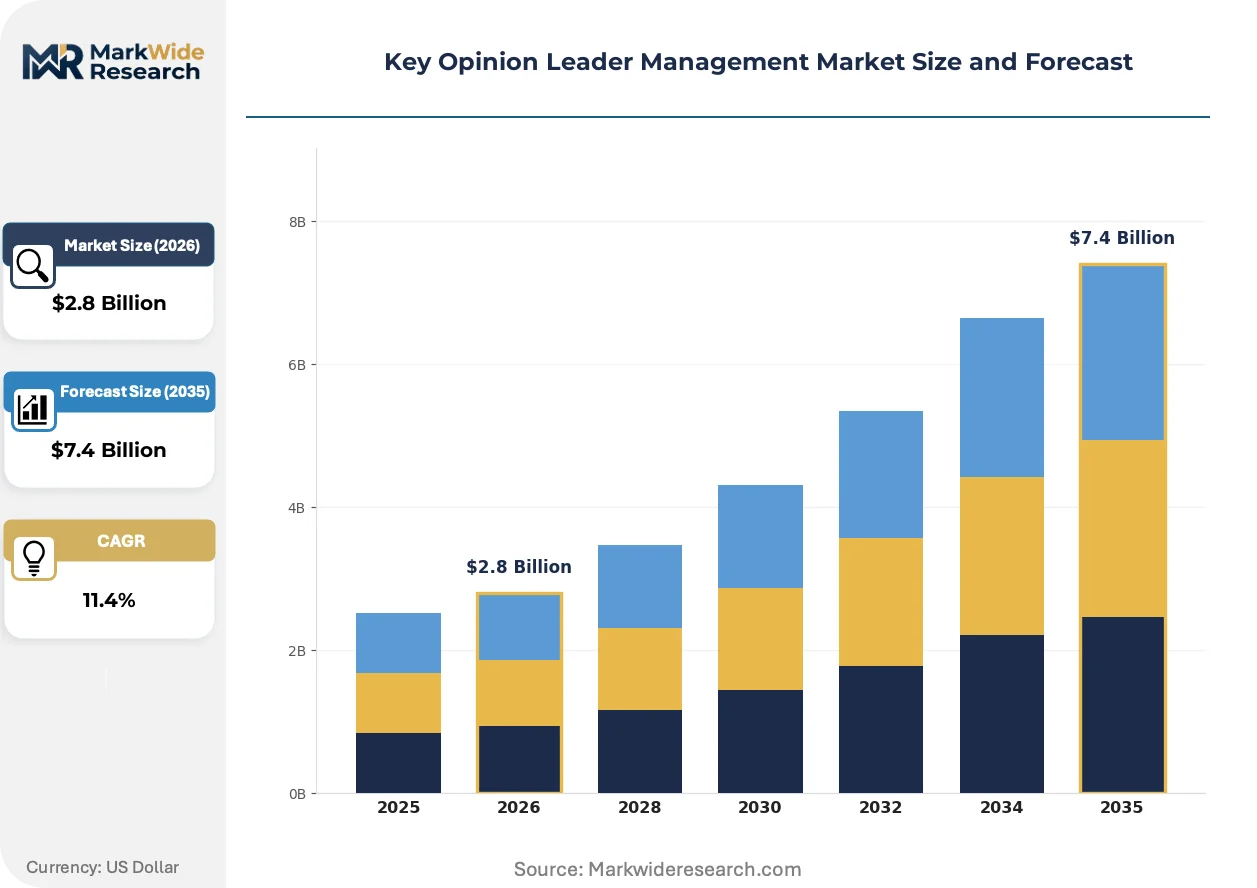
Key Opinion Leader Management Market Outlook
ISO 27001 certification for data security and HCP engagement governance is redrawing competitive boundaries in KOL management. Veeva Systems leverages its cloud-native CRM architecture to sustain dominance in life sciences customer relationship infrastructure. IQVIA Holdings anchors its position through proprietary real-world data linkages that differentiate KOL identification algorithms. Parexel International competes via embedded clinical trial services that extend KOL engagement into protocol design and site activation workflows.
Key opinion leader management encompasses the systematic identification, segmentation, engagement, and performance measurement of influential healthcare professionals who shape treatment paradigms and prescribing behaviors, typically executed through integrated software platforms that consolidate relationship data, publication histories, speaking engagements, and digital sentiment signals into unified stakeholder profiles. Engagement platforms and data analytics now command the strongest margin pools as pharmaceutical procurement prioritizes outcome-verifiable KOL interactions over transactional consulting arrangements. AI analytics within technology stacks represents the fastest-expanding capability layer, displacing manual KOL tiering with predictive influence scoring and network mapping algorithms.
FDA oversight of manufacturer-HCP financial transparency through Open Payments reporting, coupled with EMA's evolving Medical Device Regulation disclosure requirements, elevates audit-ready documentation from preference to prerequisite in platform selection. The FDA's recent digital health guidance and OPDP enforcement patterns further tighten permissible boundaries for promotional engagement, directly shaping platform compliance module roadmaps. Stakeholders must weigh whether to consolidate around full-suite providers or assemble best-of-breed point solutions as regulatory fragmentation between FDA, EMA, and national pharmacovigilance authorities intensifies.
Market Dynamics
Pharmaceutical procurement teams now mandate unified engagement platforms that consolidate KOL relationship data, clinical trial networks, and compliance documentation into single architectures. This consolidation pressure fragments point-solution vendors while rewarding full-suite providers capable of ISO 27001-certified data governance and audit-ready transparency reporting.
Growth Catalysts
- Decentralized trial expansion:Biopharma sponsors require KOL management tools that extend into site activation workflows and protocol co-design with investigator networks across dispersed geographic footprints.
- EMA Medical Device Regulation disclosure mandates:European compliance requirements for manufacturer-HCP financial transparency accelerate platform investments that automate documentation and audit trails.
- AI-powered influence scoring:Machine learning algorithms now predict KOL network effects and prescribing impact, displacing manual tiering methodologies with data-driven stakeholder prioritization.
Market Restraints
- Specialized talent scarcity:Platform vendors struggle to recruit professionals fluent in both pharmaceutical compliance requirements and cloud-native software architecture.
- Data integration complexity:Legacy CRM systems at major biopharma incumbents resist seamless API connectivity with modern KOL engagement platforms, prolonging implementation cycles.
- Regulatory fragmentation:Divergent disclosure standards between FDA Open Payments, EMA transparency rules, and national pharmacovigilance authorities force redundant compliance module development.
Strategic Opportunities
- Real-world data convergence:Linkage between KOL engagement platforms and proprietary clinical outcomes databases creates differentiated influence identification algorithms unavailable to standalone CRM vendors.
- Digital health guidance expansion:FDA's evolving framework for manufacturer communications via digital channels opens compliant engagement pathways previously restricted under off-label promotion monitoring.
- Biotech procurement autonomy:Mid-cap biopharma companies bypass enterprise IT procurement gatekeepers, creating direct sales opportunities for agile platform providers with rapid deployment capabilities.
Industry Challenges
- Legacy system coexistence:Pharmaceutical IT departments demand hybrid architectures that preserve existing Veeva CRM investments while incrementally adopting specialized KOL analytics modules.
- Certification timeline compression:ISO 27001 and SOC 2 Type II audit cycles now determine competitive eligibility, with six-month certification delays eliminating vendors from active procurement evaluations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Key Opinion Leader Management Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Engagement Platforms, Data Analytics, Strategy Development End User: Pharmaceutical Companies, Biotech Firms, Medical Device Manufacturers, Healthcare Agencies Application: Market Access, Clinical Research, Brand Promotion, Stakeholder Engagement Technology: CRM Systems, Social Media Monitoring, Data Management, AI Analytics |
| Companies Covered | Aissel Technologies, Parexel International, Veeva Systems, Syneos Health, IQVIA Holdings, Reltio, MSL Insight, Covance (part of LabCorp Drug Development), Genpact, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Key Opinion Leader Management Market Strategic Shifts
Artificial intelligence is decomposing traditional KOL identification methodologies while regulatory digitization and procurement centralization reshape vendor competitive requirements. These intersecting forces favor platform providers capable of predictive analytics, automated compliance documentation, and seamless enterprise system integration.
Predictive influence scoring algorithms now process publication histories, speaking engagement patterns, and digital sentiment signals to forecast KOL impact on treatment paradigms. Large biopharma procurement teams deploy these tools to optimize advisory board composition and medical education investments. The technology is decomposing static tiering frameworks into dynamic, continuously updated stakeholder prioritization systems that respond to real-time network changes.
EMA's evolving Medical Device Regulation disclosure requirements now mandate granular documentation of manufacturer transfers of value to healthcare professionals. Platform vendors embed automated audit trail generation and cross-border reporting modules to address this compliance burden. European biopharma subsidiaries face the steepest adaptation curve as they reconcile legacy spreadsheet-based tracking with integrated system architectures.
Centralized procurement functions at top-twenty biopharma companies now consolidate KOL management spending under single vendor relationships with outcome-verifiable contract structures. Regional medical affairs teams lose autonomy over platform selection as headquarters procurement mandates standardization. This concentration is most pronounced among United States-based headquarters operations, where procurement sophistication and compliance risk tolerance drive vendor consolidation decisions.
Key Opinion Leader Management Market Segmentation
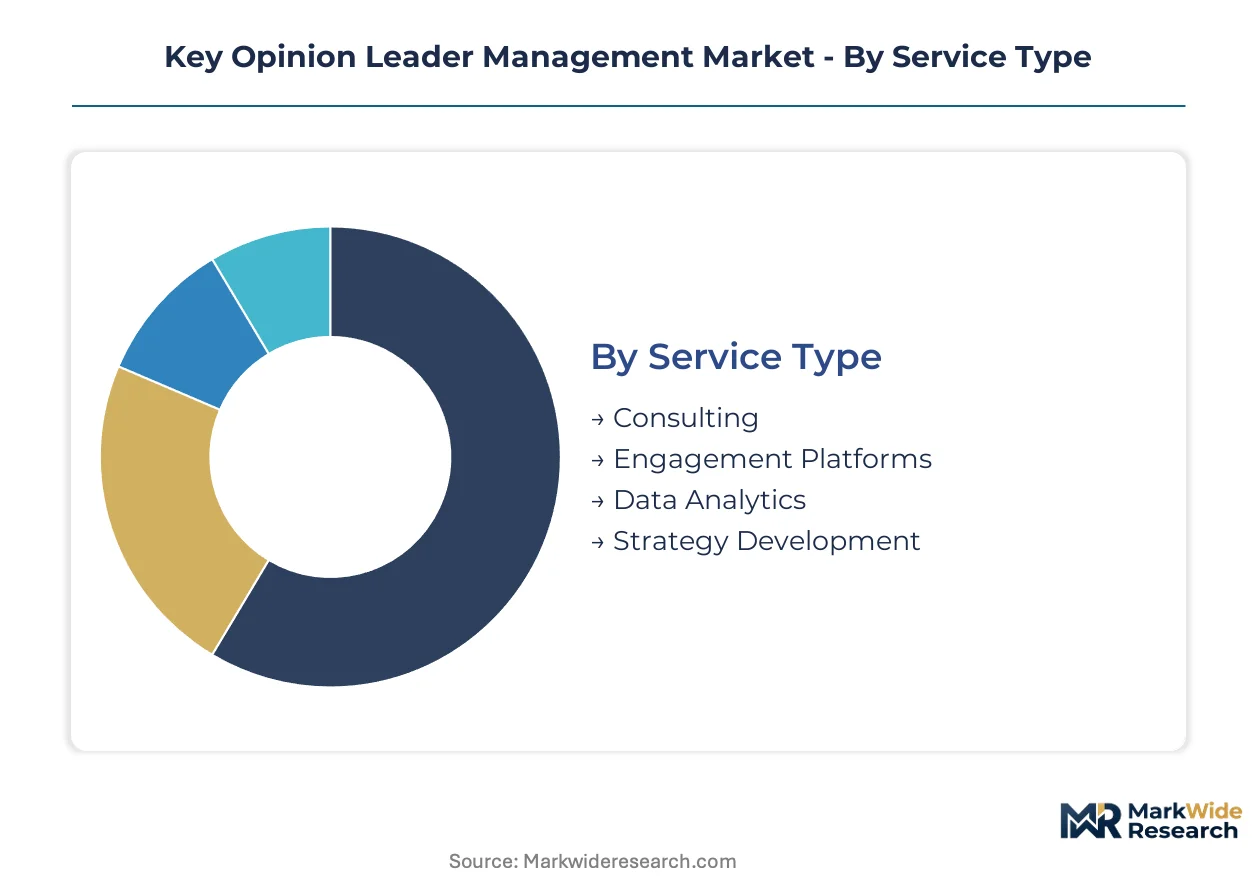
Segmentation in KOL management reveals how regulatory complexity and procurement centralization fragment vendor capabilities. Pharmaceutical buyers prioritize segments that unify compliance documentation with predictive stakeholder intelligence.
Service Type:
FDA Open Payments reporting and EMA transparency mandates differentiate service tiers by audit-readiness and automated documentation depth.
- Engagement Platforms:Cloud-native architectures consolidate relationship data, clinical trial networks, and compliance documentation into unified stakeholder profiles. United States biopharma headquarters drive procurement sophistication here, demanding ISO 27001 certification and outcome-verifiable contract structures.
- Data Analytics:Machine learning algorithms process publication histories, speaking engagement patterns, and digital sentiment signals to forecast KOL network effects. Pharmaceutical procurement teams deploy these tools to optimize advisory board composition and medical education investments.
- Consulting:Advisory services guide tiering methodologies and engagement strategy for organizations lacking internal analytics capabilities.
- Strategy Development:Framework design for stakeholder prioritization and long-term relationship roadmapping across therapeutic areas.
Engagement Platforms handle the majority of throughput; Data Analytics is expanding most quickly on share.
End User:
Procurement autonomy varies sharply by organizational scale and IT governance maturity.
- Pharmaceutical Companies:Enterprise-scale deployments mandate unified architectures that preserve existing CRM investments while incrementally adopting specialized KOL analytics modules. Centralized procurement functions at top-twenty biopharma companies consolidate spending under single vendor relationships.
- Biotech Firms:Mid-cap companies bypass enterprise IT procurement gatekeepers, creating direct sales opportunities for agile platform providers with rapid deployment capabilities.
- Medical Device Manufacturers:EMA Medical Device Regulation disclosure requirements accelerate platform investments that automate documentation and audit trails for manufacturer transfers of value.
- Healthcare Agencies:Public-sector procurement emphasizes transparency reporting and public disclosure compliance over predictive analytics capabilities.
Pharmaceutical Companies dominate current deployment volume; Biotech Firms are gaining share fastest as procurement autonomy expands.
Application:
Functional use cases align with distinct regulatory boundaries and internal stakeholder ownership.
- Clinical Research:KOL management tools extend into site activation workflows and protocol co-design with investigator networks across decentralized trial footprints. FDA oversight of manufacturer-HCP financial transparency elevates audit-ready documentation from preference to prerequisite.
- Market Access:Stakeholder identification algorithms target payers, formulary committees, and health technology assessment bodies to accelerate reimbursement timelines.
- Brand Promotion:FDA's digital health guidance and OPDP enforcement patterns tighten permissible boundaries for promotional engagement, directly shaping platform compliance module roadmaps.
- Stakeholder Engagement:Systematic relationship management across advisory boards, medical education programs, and scientific exchange activities.
Clinical Research absorbs the largest platform investment; Market Access is climbing the fastest as reimbursement complexity intensifies.
Technology:
Technology stack choices determine integration feasibility with legacy pharmaceutical IT infrastructure.
- AI Analytics:Predictive influence scoring and network mapping algorithms displace manual KOL tiering with data-driven stakeholder prioritization. AI analytics within technology stacks represents the fastest-expanding capability layer.
- CRM Systems:Cloud-native architectures sustain dominance in life sciences customer relationship infrastructure through seamless enterprise system integration.
- Social Media Monitoring:Digital sentiment signal capture tracks KOL activity across professional and public channels for real-time influence assessment.
- Data Management:Proprietary real-world data linkages create differentiated influence identification algorithms unavailable to standalone vendors.
CRM Systems anchor current infrastructure spend; AI Analytics shows the steepest expansion trajectory as procurement prioritizes predictive capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharma headquarters concentration determines regional platform spending intensity. Enterprise procurement teams at top-tier pharmaceutical companies mandate unified KOL management architectures with ISO 27001 certification and audit-ready compliance documentation.
United States
FDA Open Payments reporting requirements and OPDP enforcement patterns drive platform sophistication among Boston-Cambridge and San Francisco biotech clusters. The FDA's digital health guidance shapes compliance module roadmaps for manufacturer-HCP engagement. New Jersey and Pennsylvania host legacy pharmaceutical headquarters where centralized procurement mandates vendor consolidation.
Germany
EMA transparency rules and evolving Medical Device Regulation disclosure requirements accelerate automated documentation investments. Frankfurt and Munich anchor mid-cap biopharma procurement autonomy that bypasses enterprise IT gatekeepers. German subsidiaries reconcile spreadsheet-based tracking with integrated system architectures.
Switzerland
Swissmedic oversight and Basel's pharmaceutical headquarters density create demand for predictive influence scoring algorithms. Roche and Novartis procurement patterns shape regional vendor selection criteria. Zurich clusters host specialized compliance consulting services for cross-border transparency reporting.
United Kingdom
London's medical affairs headquarters concentrate spending on cloud-native engagement platforms with real-world data linkages. MHRA alignment with FDA digital health frameworks influences platform compliance specifications. Cambridge life science clusters drive AI-powered KOL identification adoption.
Japan
PMDA pharmacovigilance requirements and Tokyo-based pharmaceutical procurement prioritize audit-ready documentation over predictive analytics. Osaka-Kobe biopharma manufacturing hubs extend KOL engagement into clinical trial site activation. METI digital health initiatives shape permissible promotional engagement boundaries.
Key Opinion Leader Management Market Competitive Environment
Player mix skews toward full-suite platform providers with embedded compliance capabilities. Consolidation pressure fragments point-solution vendors while rewarding ISO 27001-certified architectures. Two strategic archetypes dominate: cloud-native CRM incumbents with life sciences specialization, and clinical research organizations extending KOL management into trial workflows. Competitive moves center on strategic partnerships with real-world data providers and portfolio diversification into AI-powered influence scoring.
Within the full-suite tier, Veeva Systems and IQVIA Holdings exemplify contrasting platform philosophies. Veeva Systems occupies a position anchored in cloud-native CRM architecture with seamless enterprise integration. IQVIA Holdings represents the data-convergence archetype, leveraging proprietary real-world data linkages to differentiate KOL identification algorithms. Parexel International sits within the clinical-research-embedded category, extending KOL engagement capabilities into protocol design and site activation workflows.
| Leading Market Players |
|---|
| Aissel Technologies |
| Parexel International |
| Veeva Systems |
| Syneos Health |
| IQVIA Holdings |
| Reltio |
| MSL Insight |
| Covance (part of LabCorp Drug Development) |
| Genpact |
| Others |
Value Chain & Pricing Dynamics
Outcome-verifiable contract structures with tiered SaaS licensing and per-seat indexation lock in multi-year platform access for pharmaceutical procurement teams while embedding ISO 27001 certification costs into base rates. United States biopharma headquarters leverage these arrangements to secure audit-ready compliance documentation and predictive analytics modules within unified pricing frameworks.
Pricing Analysis
Cost-plus arrangements with annual CPI indexation anchor enterprise KOL management platform pricing. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade, integration complexity, and real-world data linkage depth. Pricing pressure stems from mid-cap biotech procurement teams demanding rapid-deployment packages at compressed rates. Pharmaceutical companies show lowest price sensitivity due to compliance risk exposure, while healthcare agencies prioritize transparency reporting over predictive capabilities and negotiate aggressively on module scope.
Supply Chain Analysis
Implementation lead times stretching twelve to eighteen months strain pharmaceutical IT departments managing hybrid CRM migrations. Platform development concentrates in the United States, Germany, and Switzerland where regulatory expertise and cloud infrastructure density cluster. Proprietary algorithms, real-world data licenses, and compliance documentation engines constitute critical input dependencies. Single-source vulnerability runs through specialized AI talent pools concentrated in Boston-Cambridge and Zurich clusters. Distribution runs through direct enterprise sales teams with embedded implementation consultants rather than channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopharma procurement cyclicality is recovering as decentralized trial expansion and FDA digital health guidance renewal drive platform replacement cycles. Sponsors are releasing pent-up investment in unified engagement architectures after compliance-documentation backlogs cleared.
For Market Incumbents: Secure ISO 27001 certification renewals ahead of six-month procurement evaluation windows to maintain competitive eligibility. Embed AI-powered influence scoring deeper into existing CRM architectures to defend against standalone analytics vendors. Consolidate real-world data partnerships to differentiate KOL identification algorithms beyond commodity relationship management features. For New Entrants and Emerging Players: Mid-cap biotech procurement autonomy represents the most penetrable entry point where enterprise IT gatekeepers are bypassed. Target rapid-deployment SaaS packages with pre-configured FDA Open Payments reporting modules. Pursue channel partnerships with clinical research organizations to embed KOL management into site activation workflows. For Investors and Strategic Acquirers: Capital is best deployed toward platform providers with embedded compliance capabilities and proprietary data linkages rather than point-solution vendors facing consolidation pressure. Long-term viability favors full-suite architectures serving top-twenty biopharma headquarters with outcome-verifiable contract structures. Watch FDA OPDP enforcement pattern intensity as the inflection signal for compliance-module investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | Six-month audit timelines now determine competitive eligibility in United States procurement evaluations. |
| Real-World Data Partnership | Proprietary clinical outcomes linkages differentiate KOL identification algorithms from standalone CRM vendors. |
| AI-Powered Influence Scoring Launch | Machine learning modules displace manual tiering methodologies with predictive stakeholder prioritization systems. |
| Mid-Cap Biotech Direct Sales Expansion | Rapid-deployment capabilities bypass enterprise IT gatekeepers in procurement-autonomous organizations. |
| Compliance Module Roadmap Extension | EMA Medical Device Regulation disclosure requirements drive automated audit trail generation investments. |
Study Parameters
Desk research of FDA Open Payments databases, EMA transparency filings, and clinical trial registry records preceded structured interviews with medical affairs executives, regulatory affairs leads, procurement directors, and platform vendor product managers. Primary fieldwork across Boston-Cambridge, New Jersey, Basel, and London clusters validated secondary intelligence on procurement centralization trends. Bottom-up platform deployment estimates triangulated against top-down biopharma IT spending benchmarks.
Variance decomposition across service type, end user scale, application function, and technology stack informed projection construction across the analysis window. Segmentation modeling incorporated deployment model complexity, organizational IT governance maturity, therapeutic area regulatory intensity, and regional disclosure regime clustering. CAGRs derived from weighted average of historical platform adoption curves and procurement budget elasticity estimates. Forecast inputs included decentralized trial penetration rates and FDA digital health guidance implementation timelines.
Forecasts assume regulatory continuity in FDA Open Payments, EMA Medical Device Regulation, and PMDA pharmacovigilance regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Customer Information System (CIS) Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Lead Management Market