
 Collaborative Customer Interfaces Market | 2026-2036
Collaborative Customer Interfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Collaborative Customer Interfaces Market Outlook
India is tilting toward cloud-native interface development as domestic SaaS engineering capacity expands. Salesforce leverages its AppExchange ecosystem to anchor enterprise clients across verticals. Microsoft competes through native Teams-CRM integration, extending its productivity suite dominance into customer-facing workflows. SAP sustains its position in manufacturing-heavy segments where ERP-linked interfaces command premium deployment budgets.
Collaborative customer interfaces encompass software platforms enabling synchronous multi-party interaction between businesses and their clients through unified messaging, co-browsing, and shared document environments. These systems typically operate via WebRTC protocols with sub-200ms latency thresholds to preserve conversational fluidity during real-time engagement sessions. Cloud deployment models capture the dominant margin pool as enterprises abandon on-premise maintenance overhead, while SaaS delivery structures accelerate vendor switching and compress implementation timelines. CRM software types retain the largest installed base, though collaboration tools exhibit the steepest trajectory as hybrid work patterns institutionalize persistent client workspaces.
The EU AI Act and GDPR compliance frameworks reshape platform architecture requirements for automated response functionalities across European deployments. India's TRAI data localization guidelines and the RBI's cloud security directives impose infrastructure residency constraints on financial services implementations. FDA 21 CFR Part 11 considerations extend into pharmaceutical customer portals where audit trails govern promotional material exchanges. Stakeholders must weigh regulatory fragmentation against unified platform roadmaps when prioritizing geographic expansion sequences.
Market Dynamics
Cloud-first deployment mandates from EU regulators are compressing implementation timelines while forcing platform standardization across financial services infrastructure. WebRTC protocol maturation enables sub-200ms latency thresholds that preserve conversational fluidity during synchronous multi-party sessions.
Growth Catalysts
- EU AI Act compliance architecture:Automated response functionalities across European deployments require explainable AI frameworks, creating upgrade cycles for legacy customer portals.
- Industrial manufacturers in Germany:Supply chain portal integration demands collaborative interfaces linking ERP systems with external supplier networks.
- WebRTC protocol standardization:Browser-native real-time communication eliminates client-side software dependencies, reducing IT support overhead for enterprise deployments.
Market Restraints
- Data residency infrastructure costs:India's TRAI localization guidelines and RBI cloud security directives impose redundant server requirements across Mumbai, Chennai, and Hyderabad clusters.
- GDPR audit trail complexity:Pharmaceutical customer portals must maintain immutable records of promotional material exchanges under FDA 21 CFR Part 11 and overlapping EU frameworks.
- Legacy CRM integration friction:On-premise systems from the 2010s lack API architectures necessary for synchronous co-browsing and shared document environments.
Strategic Opportunities
- Underpenetrated pharmaceutical vertical:Audit-trail-compliant collaborative portals for promotional material exchange remain nascent outside top-20 global drug manufacturers.
- Convergence of AI agents with persistent workspaces:Hybrid work patterns institutionalize client workspaces where automated assistants handle routine queries before human handoff.
- EU Green Deal procurement criteria:Public sector RFPs increasingly specify energy-efficient cloud infrastructure, favoring vendors with carbon-neutral data center certifications.
Industry Challenges
- WebRTC engineering talent scarcity:Real-time media pipeline optimization requires specialized skills concentrated in Bangalore, Berlin, and San Francisco metro areas.
- Multi-jurisdiction compliance sequencing:Vendors must architect separate instances for EU AI Act, GDPR, and India's divergent data localization regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaborative Customer Interfaces Market |
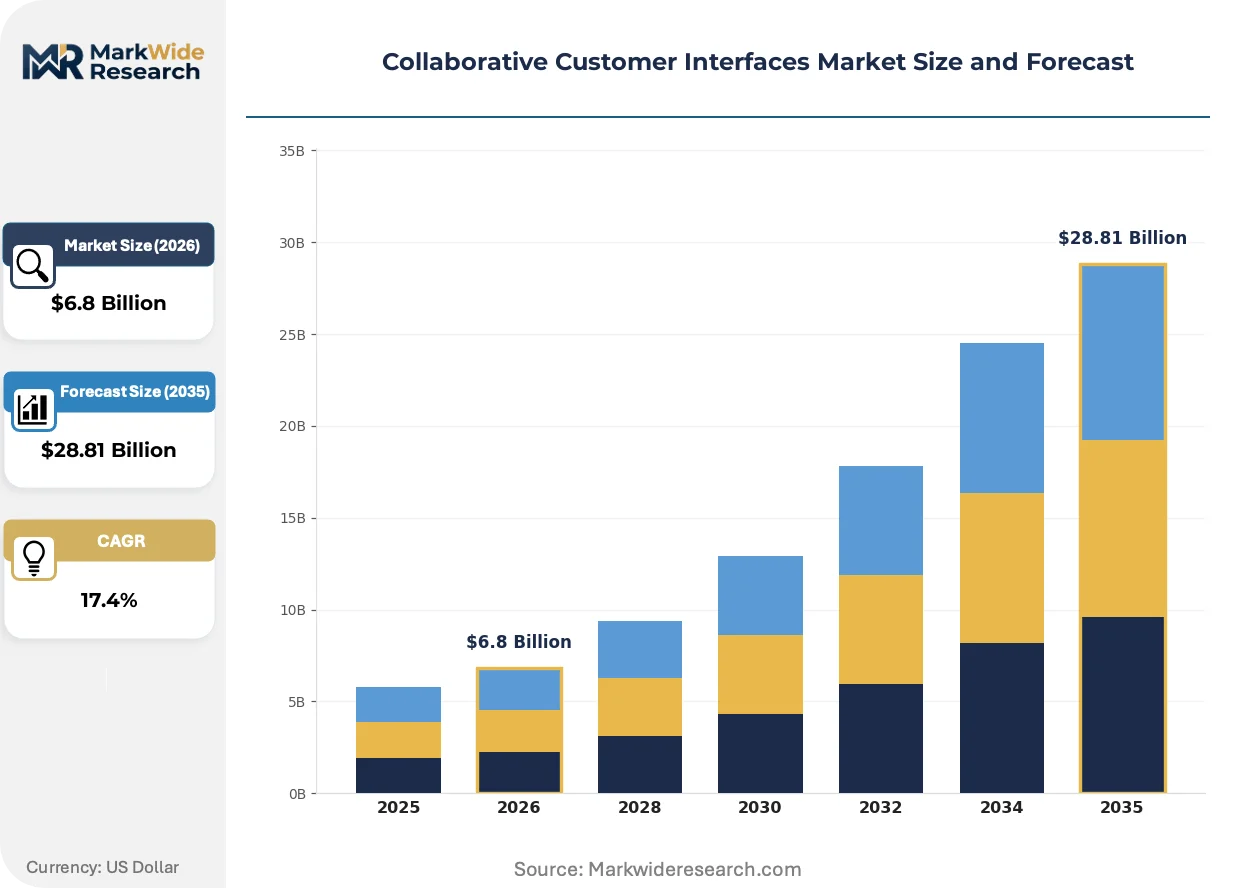
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: CRM, CMS, Collaboration Tools, Social Media Platforms Deployment Model: Cloud, On-Premise, Hybrid, SaaS Customer Segment: Small Businesses, Enterprises, Startups, Nonprofits Functionality: Real-Time Communication, Data Analytics, Automated Responses, Customer Feedback |
| Companies Covered | Salesforce, Zendesk, Microsoft, Oracle, SAP, HubSpot, Freshworks, ServiceNow, Zoho, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaborative Customer Interfaces Market Strategic Shifts
Platform architecture is pivoting toward embedded AI agents that maintain conversational context across asynchronous and synchronous touchpoints. Vendors compete on latency optimization and regulatory pre-certification rather than feature breadth alone.
WebRTC-based co-browsing technology is virtualizing the traditional screen-sharing paradigm by enabling pixel-perfect rendering without plugin dependencies. Retail banking institutions in Germany and France are deploying these capabilities for mortgage application reviews. The technology is virtualizing branch-based consultation models, compressing physical footprint requirements while preserving human relationship elements.
The EU AI Act's risk classification system imposes documentation burdens on automated customer response systems deployed across member states. High-risk applications must maintain human oversight protocols and algorithmic transparency registers. Pharmaceutical and financial services portals face the steepest compliance costs, with vendors pre-building audit-ready architectures for German and French initial deployments.
Enterprise buying committees now demand consumption-based pricing aligned to active user sessions rather than seat-based licenses. IT procurement teams in industrial manufacturing verticals negotiate outcome metrics tied to resolution time reduction. This shift is most pronounced in Germany's automotive supplier network, where shared supplier portals bill by transaction volume rather than fixed annual contracts.
Collaborative Customer Interfaces Market Segmentation
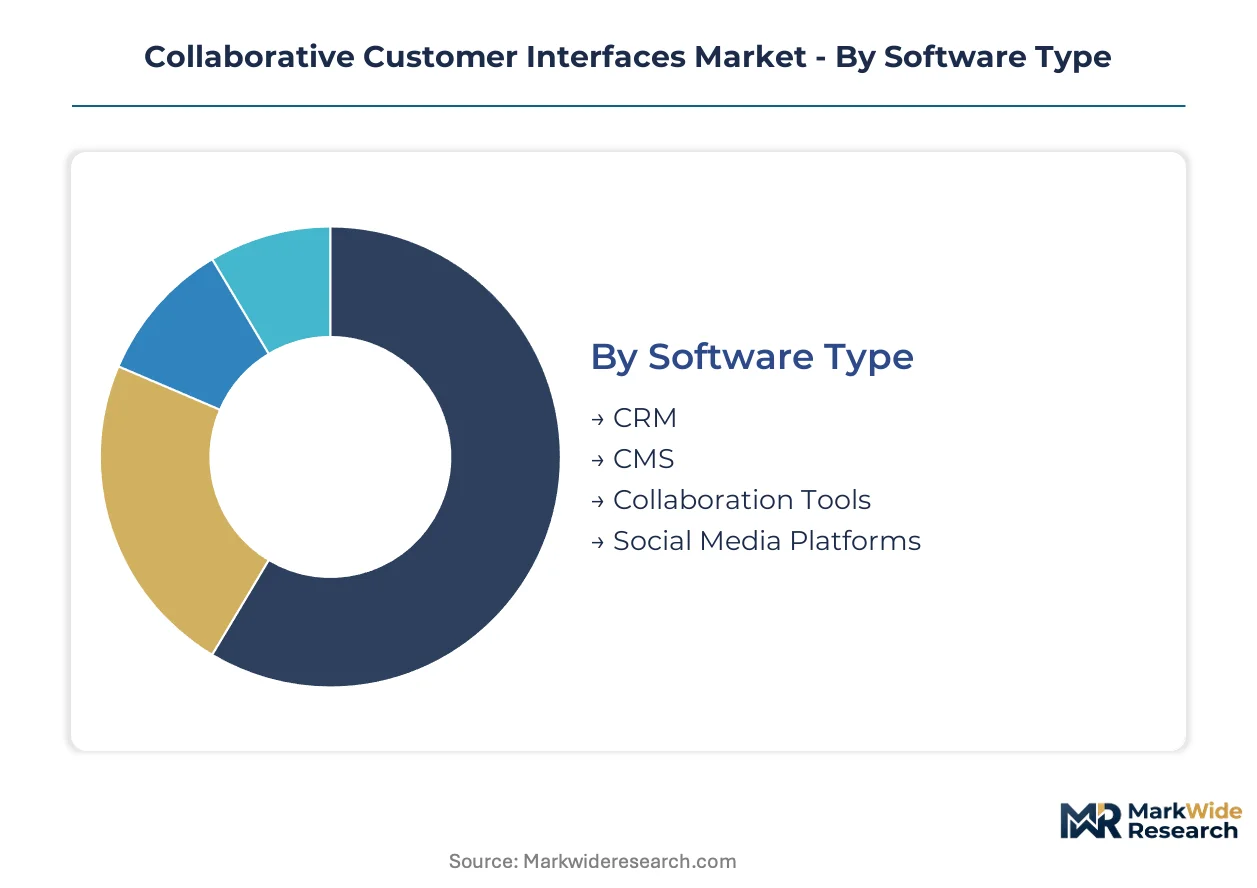
Segmentation in collaborative customer interfaces reveals how deployment preferences and functional requirements diverge across buyer maturity levels. Procurement patterns split between enterprises seeking ERP-integrated suites and agile organizations prioritizing rapid implementation. Understanding these divides enables vendors to align pricing architectures with operational complexity rather than forcing uniform platform adoption.
Software Type:
Mature categories dominate installed base revenue while emerging formats capture new project budgets.
- CRM:These platforms anchor customer data repositories with synchronous interaction layers bolted onto legacy contact management cores. Banking institutions in Germany deploy CRM-linked interfaces for mortgage consultation workflows, though integration costs erode margin on older installations.
- Collaboration Tools:Persistent workspaces with embedded client channels institutionalize hybrid engagement models through WebRTC-native architectures. Demand concentrates among industrial manufacturers integrating supplier portals into ERP-driven procurement workflows.
- CMS:Content management systems with collaborative review cycles support regulated document exchanges in pharmaceutical promotional material workflows.
- Social Media Platforms:Branded community interfaces enable asynchronous customer peer support with escalation pathways to human agents.
CRM retains volume leadership; Collaboration Tools holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates capital-intensive infrastructure commitments from operational expenditure flexibility.
- Cloud:Multi-tenant architectures eliminate server maintenance overhead while enabling automatic compliance patching for GDPR and EU AI Act requirements. EU regulators mandate cloud-first deployment for financial services infrastructure, compressing procurement timelines.
- SaaS:Subscription delivery accelerates vendor switching and compresses implementation timelines through pre-configured industry templates. India's SaaS engineering capacity expansion drives domestic platform development for cost-sensitive buyers.
- Hybrid:Split architectures preserve sensitive data on-premise while pushing collaborative features to edge cloud nodes.
- On-Premise:Legacy installations persist in defense and classified government environments with air-gapped security requirements.
Cloud captures the dominant margin pool; SaaS climbs the fastest as procurement teams abandon capital approval cycles.
Customer Segment:
Application complexity scales with organizational process maturity and integration depth requirements.
- Enterprises:Multi-divisional deployments demand API architectures linking collaborative interfaces with SAP and Oracle ERP systems. Manufacturing-heavy segments in Germany command premium deployment budgets for supply chain portal integration.
- Small Businesses:Rapid deployment priorities favor pre-integrated suites with minimal IT support requirements. India's domestic SaaS expansion targets this segment with localized pricing and regional language support.
- Startups:Agile procurement favors consumption-based billing aligned to growth trajectories rather than fixed seat licenses.
- Nonprofits:Grant-funded implementations prioritize donor-visible engagement metrics over backend integration sophistication.
Enterprises retain volume leadership; Small Businesses gains share fastest as platform economics democratize.
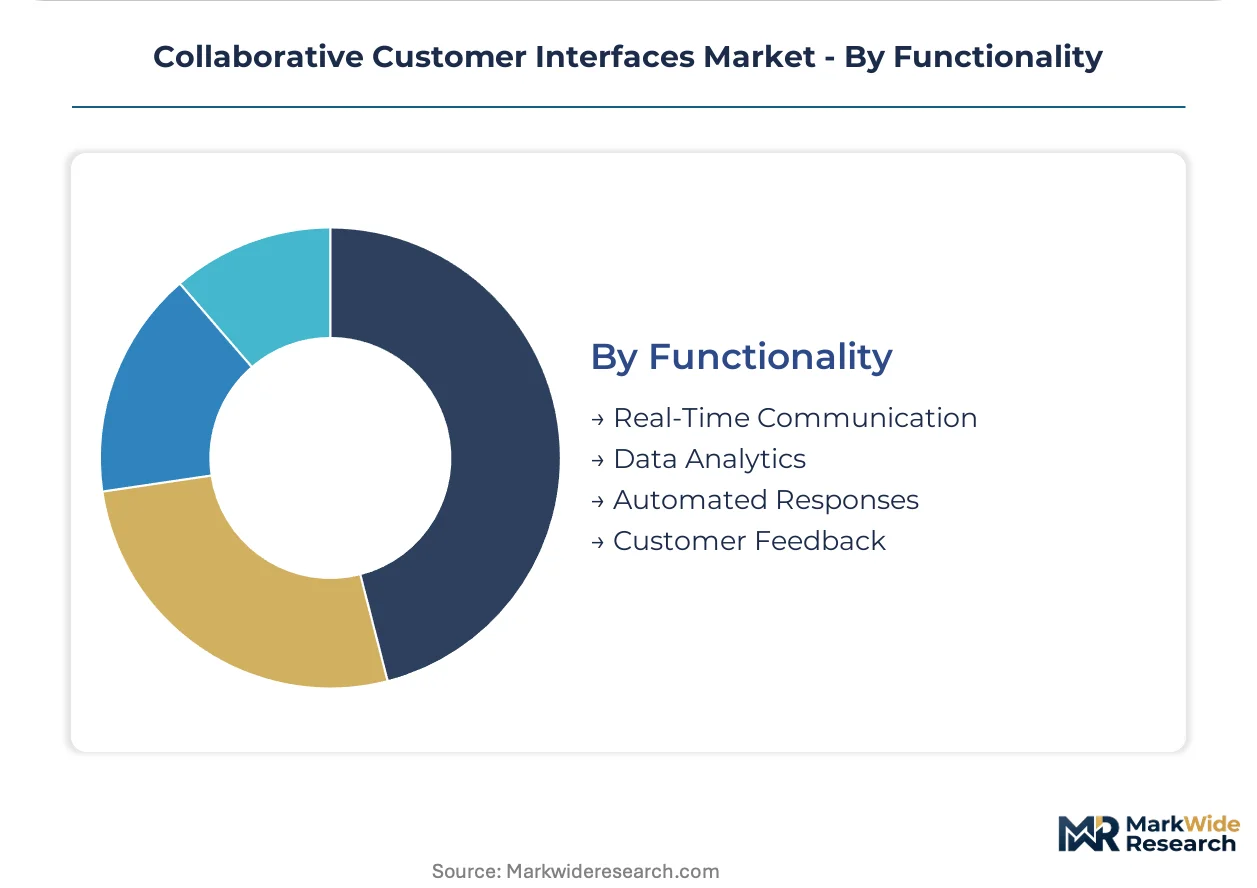
Functionality:
Customer type differentiation separates routine query automation from high-touch advisory workflows.
- Real-Time Communication:WebRTC protocols enable sub-200ms latency thresholds for synchronous co-browsing and unified messaging. Retail banking institutions deploy these capabilities for virtual branch consultations, compressing physical footprint requirements.
- Automated Responses:AI-driven response systems require explainable frameworks under EU AI Act risk classifications. Pharmaceutical and financial services portals face the steepest compliance costs for algorithmic transparency registers.
- Data Analytics:Interaction mining across synchronous and asynchronous touchpoints generates predictive customer health scores.
- Customer Feedback:Embedded survey mechanisms with real-time sentiment analysis trigger escalation protocols before relationship deterioration.
Real-Time Communication retains volume leadership; Automated Responses expands most quickly as AI agent integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European deployment timelines as the continent's financial services regulators mandate cloud-first infrastructure upgrades. Retail banking institutions across Germany and France compress procurement cycles to meet compliance deadlines. Industrial manufacturers in Stuttgart and Munich integrate collaborative interfaces into supplier-facing ERP portals.
Germany
Automotive suppliers and industrial machinery producers drive demand for ERP-linked collaborative portals. The KBA and BSI enforce strict data residency requirements for connected vehicle customer interfaces. Manufacturing clusters in Baden-Württemberg and Bavaria deploy supply chain portals linking Siemens and SAP systems with external supplier networks.
United States
Enterprise software buyers prioritize native integration with existing productivity suites. The FDA's 21 CFR Part 11 framework extends audit trail requirements into pharmaceutical customer portals. Boston and San Francisco metro areas concentrate SaaS engineering talent developing WebRTC-native architectures for financial services clients.
India
Domestic SaaS engineering capacity expansion enables cost-competitive platform development for mid-market buyers. TRAI data localization guidelines and RBI cloud security directives impose multi-cluster infrastructure requirements. Mumbai, Chennai, and Hyderabad host redundant server deployments serving financial services implementations.
United Kingdom
Financial services institutions modernize client-facing infrastructure ahead of FCA operational resilience deadlines. The Information Commissioner's Office enforces GDPR-aligned transparency requirements for automated customer response systems. London's fintech corridor drives adoption of consumption-based pricing models tied to active user sessions.
France
Retail banking groups deploy virtual branch consultation capabilities to reduce physical footprint costs. The CNIL mandates algorithmic transparency registers for high-risk AI applications in customer-facing systems. Paris-based insurance conglomerates pilot collaborative interfaces for complex policy advisory workflows.
Collaborative Customer Interfaces Market Competitive Environment
Capability concentration sits with specialized collaboration vendors; scale advantage sits with platform conglomerates integrating productivity suites. The market structures around three tiers: cloud-native specialists with WebRTC expertise, productivity-suite incumbents extending into customer workflows, and ERP-linked providers serving manufacturing verticals. Dominant competitive moves include strategic partnerships for regulatory pre-certification and portfolio diversification into AI agent capabilities.
Within the productivity-suite tier, Microsoft and Salesforce occupy anchor positions representing divergent integration philosophies. SAP exemplifies the ERP-linked archetype serving manufacturing-heavy segments. Zendesk represents the cloud-native specialist model focused on mid-market rapid deployment. These three companies illustrate how competitive positioning fragments across integration depth versus implementation speed trade-offs.
| Leading Market Players |
|---|
| Salesforce |
| Zendesk |
| Microsoft |
| Oracle |
| SAP |
| HubSpot |
| Freshworks |
| ServiceNow |
| Zoho |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in India's SaaS engineering clusters compresses vendor margins while accelerating price competition for mid-market deployments. Utilization rates below 70% in Bangalore and Hyderabad development centers force domestic platforms to undercut multinational pricing, reshaping procurement negotiations across Asia-Pacific financial services implementations.
Pricing Analysis
Geographic price spreads between German enterprise deployments and Indian mid-market implementations exceed 3x for functionally equivalent WebRTC-native platforms. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, with ERP-linked deployments commanding substantial premiums over standalone collaboration tools. Pricing pressure stems from cloud infrastructure commoditization as hyperscalers absorb compute costs into bundled productivity suites. Small businesses exhibit highest price sensitivity, while manufacturing enterprises in Germany prioritize compliance certification over unit cost.
Supply Chain Analysis
Export control regimes restricting semiconductor and encryption technology flows constrain WebRTC media pipeline component sourcing for vendors serving defense-adjacent verticals. Engineering talent concentrates in India, Germany, and the United States, with specialized real-time optimization skills tethered to Bangalore, Berlin, and San Francisco metro areas. Cloud infrastructure dependencies rest on hyperscaler data center networks, while regulatory fragmentation forces redundant server deployments across Mumbai, Chennai, and Hyderabad clusters. Single-source vulnerability sits with specialized WebRTC engineering pools. Distribution runs through direct enterprise sales with systems integrator overlays for complex ERP integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-native collaboration platforms that bypass traditional CRM integration architectures entirely. Defense requires hardening core integration moats while absorbing automation capabilities before pure-play AI entrants capture advisory workflow budgets.
For Market Incumbents: Harden ERP integration architectures through deeper SAP and Oracle API partnerships, preventing displacement by standalone AI collaboration tools. Invest in EU AI Act pre-certification to capture upgrade cycles at German financial institutions facing compliance deadlines. Vertical integration into WebRTC engineering talent pools in Bangalore and Berlin reduces dependency on scarce specialized labor.
For New Entrants and Emerging Players: Build out pharmaceutical vertical penetration where audit-trail-compliant promotional material portals remain underdeveloped outside top-20 global manufacturers. Target India's mid-market with localized SaaS offerings leveraging domestic engineering cost advantages. Pursue consumption-based pricing models aligned to transaction volume rather than seat licenses, mirroring German automotive supplier procurement preferences.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native specialists with embedded AI agent capabilities, signaling durable cash flow quality through economic cycles. Long-term viability favors platforms with regulatory pre-certification across EU AI Act and FDA 21 CFR Part 11 frameworks. Acquisition targets should demonstrate WebRTC engineering density in constrained talent markets. Watch for inflection when enterprise buying committees mandate outcome-based pricing tied to resolution time reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Teams-CRM linkages extend Microsoft's productivity dominance into customer-facing workflows. |
| Regulatory Pre-Certification | EU AI Act audit-ready architectures capture upgrade cycles at German retail banking institutions. |
| Acquisition of Specialist Firm | WebRTC engineering talent scarcity makes Bangalore and Berlin development teams strategic assets. |
| Geographic Expansion | India's domestic SaaS capacity enables cost-competitive platform development for mid-market buyers. |
| Strategic Partnership | SAP-aligned integration partnerships command premium deployment budgets in Stuttgart manufacturing clusters. |
Study Parameters
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and channel partners anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, AppExchange marketplace data, and EU regulatory submission databases. Bottom-up deployment counts across software type and deployment model segments were triangulated against top-down vendor revenue estimates.
Scenario bracketing around EU AI Act implementation timelines, WebRTC protocol maturation curves, and cloud infrastructure cost trajectories bounded the projection range across the analysis window. Segmentation modeling incorporated software type, deployment model, organization size, vertical integration complexity, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns and disclosed vendor booking data.
Stress conditions across EU regulatory enforcement intensity, WebRTC engineering wage inflation, and hyperscaler pricing power were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance timeline adherence and platform substitution elasticities. Material shifts in EU AI Act risk classification thresholds or abrupt WebRTC talent pool migration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Thailand CRM Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Europe Cloud CRM Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market
Customer Relationship Management (CRM)
Global Customer Experience Management Software Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Retail CRM Software Market