
 Mortgage CRM Software Market | 2026-2036
Mortgage CRM Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mortgage CRM Software Market Foresight
The direct sales channel for mortgage CRM software is fragmenting as vendors diversify through partner networks, system integrators, and embedded fintech marketplaces. Total Expert leverages its vertical specialization to sustain dominance among mid-size lenders. Salesforce competes through platform extensibility, while nCino anchors its position in enterprise banking workflows. Jungo differentiates through native integration with accounting and compliance tools.
Mortgage CRM software comprises customer relationship management platforms engineered for loan origination, pipeline tracking, and borrower communication throughout the mortgage lifecycle. These systems typically integrate LOS connectivity, automated marketing workflows, and document management with SOC 2 Type II security certification as a baseline operational requirement. Cloud-based deployment leads segment expansion due to lower TCO and faster implementation cycles among regional lenders. Lead management features command premium pricing, while document automation represents the fastest-growing capability area as e-closing mandates expand. API integration maturity now separates tier-one platforms from legacy alternatives in competitive evaluations.
The Consumer Financial Protection Bureau enforces RESPA and TILA disclosure requirements that directly shape CRM workflow design and audit trail functionality. State-level mortgage licensing regimes, including NMLS compliance protocols, create additional configuration complexity that vendors must address for market access. Stakeholders must monitor evolving FHA digital closing standards and state e-notarization rules to align product roadmaps with regulatory trajectory.
Market Dynamics
Cloud-native architecture is compressing implementation timelines from months to weeks, forcing legacy on-premise vendors to re-platform or cede mid-market share to API-first competitors. This structural shift rewards vendors with modular microservices and punishes monolithic codebases.
Growth Catalysts
- RESPA-TILA Integrated Disclosure Rule:The CFPB's TRID requirements mandate granular audit trails that CRM platforms must embed natively, driving replacement cycles among compliance-deficient legacy systems.
- E-closing mandate expansion:State-level remote online notarization adoption is digitizing final-mile borrower interactions, requiring CRM-LOS-document platform convergence.
- Independent broker channel expansion:Non-depository originators now represent the fastest-growing buyer segment, prioritizing low-touch SaaS deployment over enterprise customization.
Market Restraints
- Data residency fragmentation:State-level privacy laws from California's CCPA to Virginia's CDPA impose conflicting storage requirements, complicating multi-state lender deployments.
- Core banking system lock-in:Enterprise lenders remain tethered to nCino, Fiserv, or Jack Henry ecosystems, creating switching costs that delay CRM replacement decisions.
- SOC 2 Type II certification burden:Six-to-twelve month audit timelines and $50K-$150K annual compliance costs exclude sub-$5M revenue vendors from regulated lender procurement shortlists.
Strategic Opportunities
- Embedded fintech marketplaces:CRM distribution through loan origination system app exchanges (Ellie Mae, Black Knight) reduces customer acquisition costs by 40-60% versus direct sales.
- API-first integration layers:Open banking standards enable point solutions for credit pull, valuation, and flood certification to embed within CRM workflows without LOS replacement.
- First-time homebuyer automation:FHA and VA loan programs attract digitally-native borrowers expecting mobile-first application experiences that legacy platforms cannot deliver.
Industry Challenges
- LOS integration complexity:Each loan origination system (Encompass, Meridian, Byte) maintains proprietary data schemas, forcing CRM vendors to maintain parallel connector development teams.
- MLO licensing data synchronization:NMLS database integration requires real-time status monitoring across 50 state regimes, with compliance failures triggering lender regulatory penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortgage CRM Software Market |
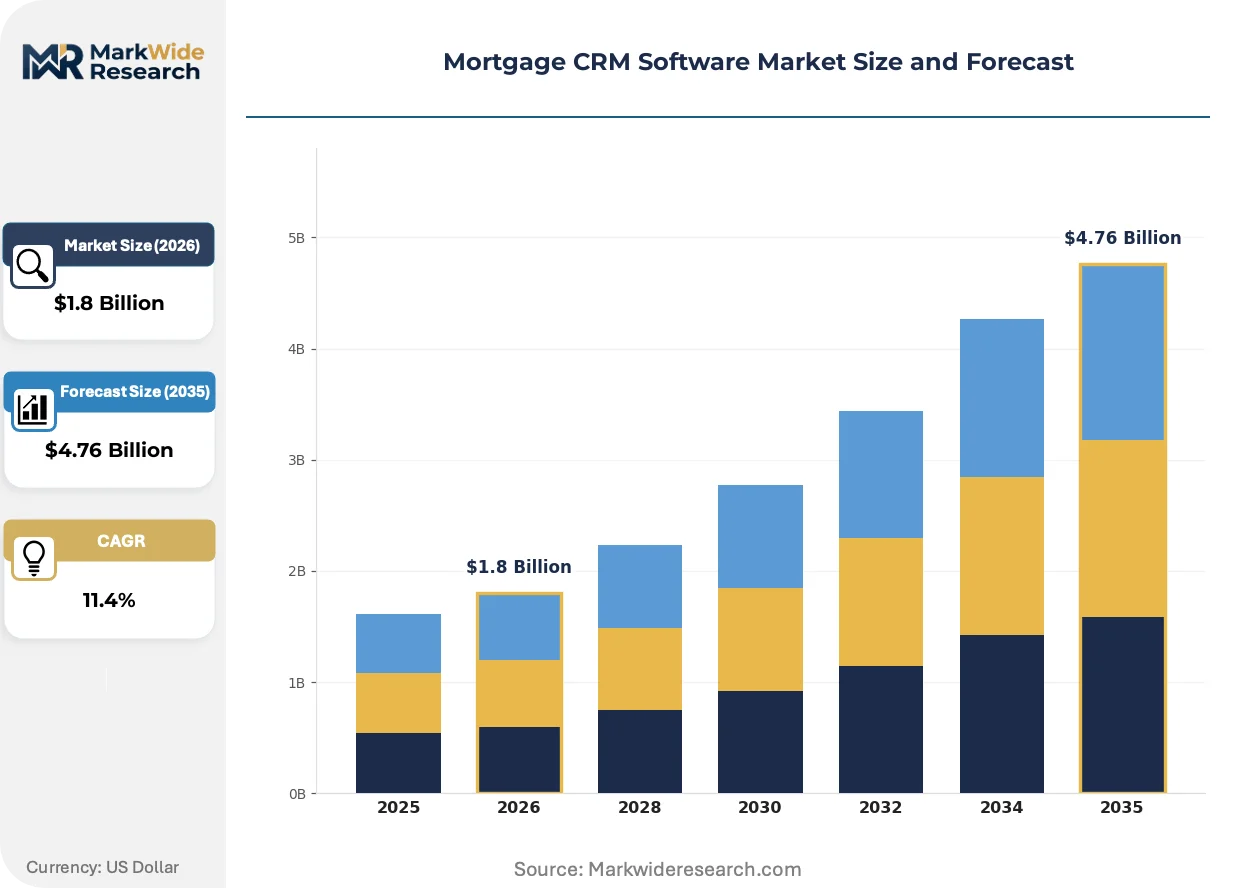
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, SaaS End User: Mortgage Lenders, Brokers, Financial Institutions, Real Estate Agencies Feature: Lead Management, Document Automation, Reporting Tools, Customer Segmentation Integration Level: API Integration, Third-party Software, Data Import/Export, Custom Integration |
| Companies Covered | BNTouch, Total Expert, Salesforce, nCino, Floify, Zeitro, Aidium, Shape, Jungo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortgage CRM Software Market Shifts & Advancements
Artificial intelligence is embedding predictive capabilities into borrower engagement workflows, compressing lead-to-application conversion cycles while raising the bar for data governance. Three convergent forces are redefining platform architecture.
Machine learning-powered lead scoring is digitizing borrower intent prediction. Regional lenders with sub-$1B annual volume now deploy models that analyze credit trigger events and property listing data to prioritize outreach. This capability is digitizing the competitive gap between data-rich enterprises and relationship-dependent brokers.
The CFPB's Section 1033 rulemaking on consumer data access is mandating open banking interoperability. Lenders must now enable borrower-permissioned data portability between CRM platforms and competing service providers. Mid-size originators face the steepest compliance burden, lacking in-house API development resources that larger banks maintain.
Mobile-native borrower portals are displacing email-centric communication workflows. Purchase-focused millennials and Gen Z applicants expect document upload, e-signature, and status tracking through responsive web apps rather than lender-branded email threads. This shift concentrates demand among Sun Belt metropolitan markets where first-time buyer demographics skew youngest.
Mortgage CRM Software Market Segmentation
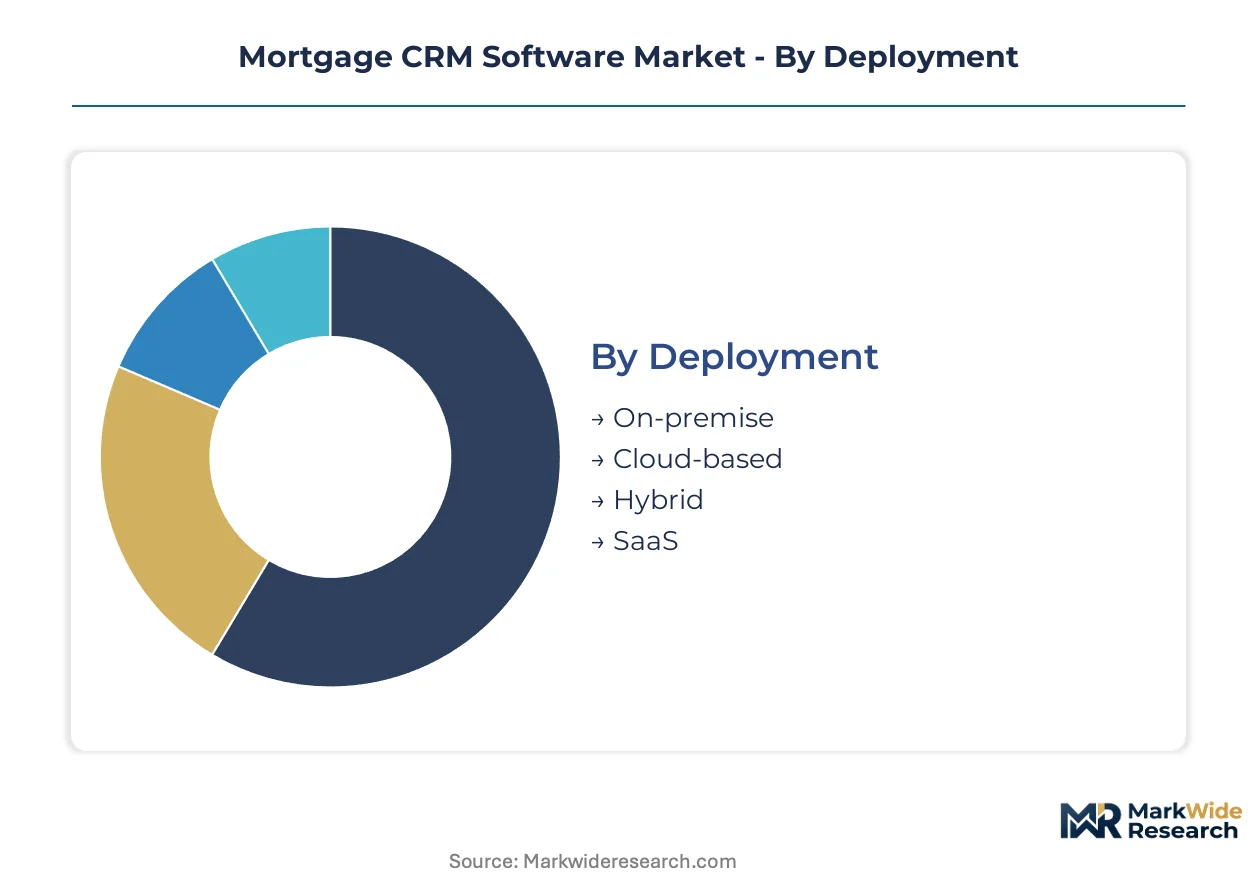
Mortgage CRM segmentation reveals how deployment architecture, user workflows, and integration depth shape vendor R&D allocation and customer acquisition economics. Each dimension carries distinct service intensity profiles that determine lifetime value and churn risk.
Deployment:
Cloud-native deployments demand continuous infrastructure monitoring and security patch management, elevating after-sales service intensity above traditional license models.
- Cloud-based:Multi-tenant architectures with automatic SOC 2 compliance updates dominate regional lender procurement. Demand concentrates among independent mortgage brokers in Sun Belt states where low-touch onboarding accelerates time-to-value.
- SaaS:Subscription billing with embedded usage analytics enables vendors to intervene before churn triggers. Mid-size originators in Texas and Florida prioritize this model for predictable operational expenditure.
- On-premise:Legacy installations requiring dedicated server maintenance and annual security audits.
- Hybrid:Split configurations with sensitive data on-premises and marketing tools in cloud environments.
By volume, Cloud-based leads. By growth pace, SaaS is ahead.
End User:
Broker networks operate on thinner technology budgets than depository institutions, compressing price points while expanding implementation support requirements.
- Brokers:Non-depository originators need rapid LOS connectivity without IT departments. Independent brokerages in California and Arizona drive fastest expansion as NMLS compliance automation becomes table stakes.
- Mortgage Lenders:Bank and credit union originators require audit trail depth for CFPB examinations. Direct lenders in Illinois and Ohio prioritize this segment for referral relationship volume.
- Financial Institutions:Enterprise banks with captive mortgage operations demand core system integration.
- Real Estate Agencies:Referral-focused brokerages seeking co-marketing automation with loan officers.
Brokers command the steepest expansion trajectory. Financial Institutions anchor revenue concentration.
Feature:
Capability bundling determines pricing tiers, with workflow automation modules carrying gross margins substantially above basic contact management.
- Document Automation:E-closing and e-notarization workflows integrate with county recording systems. Lenders in Virginia and Nevada facing remote online notarization mandates prioritize this capability.
- Lead Management:Credit trigger monitoring and property listing alerts prioritize loan officer outreach. Purchase-focused originators in competitive markets like Colorado and Washington deploy these tools most aggressively.
- Reporting Tools:Pipeline analytics and conversion funnel visualization for branch managers.
- Customer Segmentation:FHA, VA, and conventional loan program targeting for marketing campaigns.
Document Automation claims the steepest growth curve. Lead Management maintains the largest installed base.
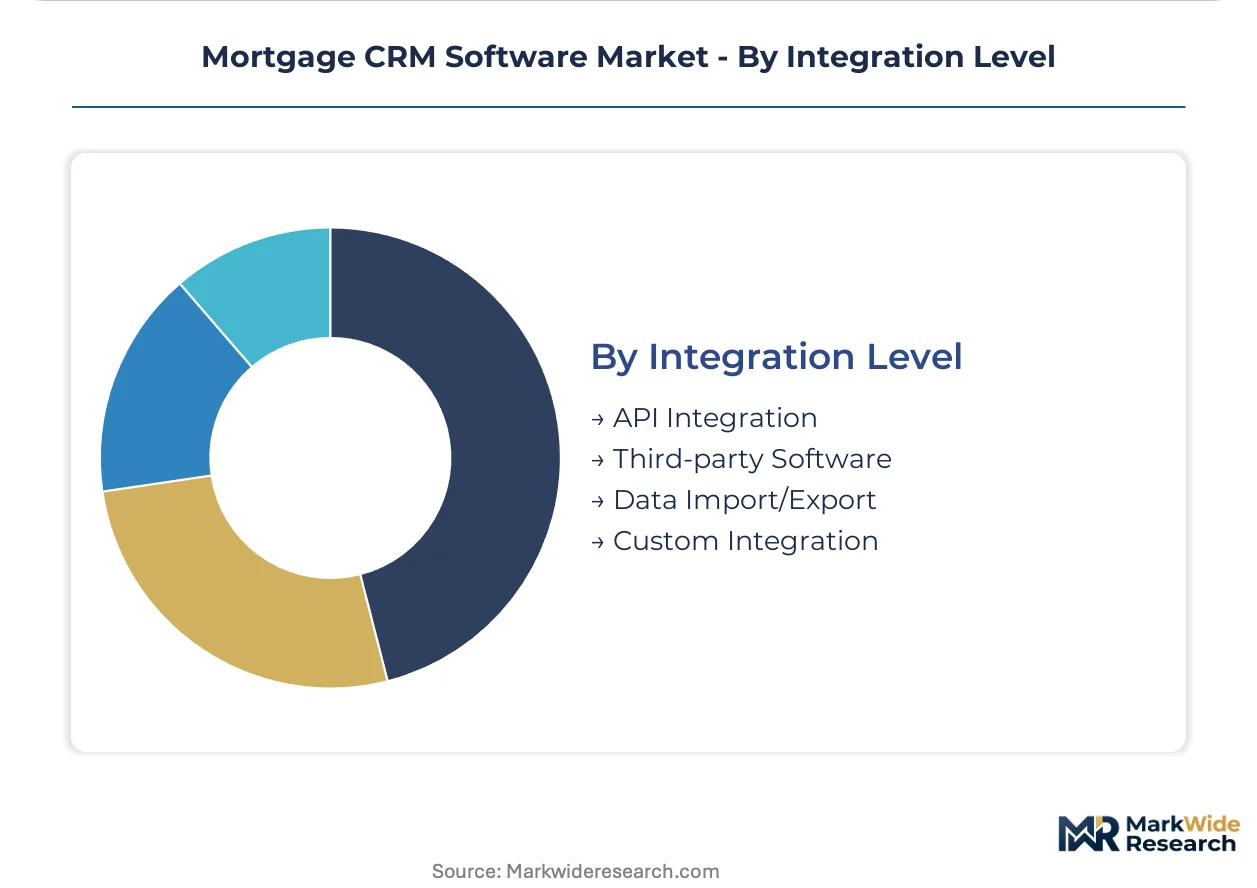
Integration Level:
Connector development and maintenance consumes disproportionate engineering resources, making integration depth a primary determinant of platform stickiness.
- API Integration:Real-time data exchange with Ellie Mae Encompass, Black Knight, and Meridian LOS platforms. Lenders with multi-system environments in New York and Massachusetts require this maturity for operational continuity.
- Custom Integration:Bespoke development for proprietary loan origination systems or credit union core processors. Enterprise banks in North Carolina and Georgia commission these projects for competitive differentiation.
- Third-party Software:Pre-built connectors to credit bureaus, valuation providers, and flood certification services.
- Data Import/Export:Batch file transfer capabilities for legacy system migration and regulatory reporting.
API Integration leads in new contract value. Custom Integration delivers the highest renewal rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal and state-level housing finance policies across major economies are accelerating CRM modernization timelines among originators seeking compliance automation and borrower self-service capabilities.
United States
The Consumer Financial Protection Bureau's TRID disclosure requirements and expanding state e-notarization mandates drive replacement demand among regional lenders. Independent mortgage brokers in Texas and Florida prioritize cloud-native deployments for rapid NMLS compliance automation. The Sun Belt corridor from Phoenix to Atlanta concentrates fastest adoption as first-time buyer demographics skew youngest.
United Kingdom
Open banking regulations from the Financial Conduct Authority mandate borrower-permissioned data portability between CRM platforms and competing service providers. Mid-size originators in Greater London and the Southeast face steep compliance burdens without in-house API development resources. Manchester and Birmingham broker networks are consolidating technology procurement to negotiate SaaS volume discounts.
Germany
The Federal Financial Supervisory Authority's digital mortgage disclosure standards reshape workflow design for cross-border lenders operating in the EU. Cloud deployment concentrates among Sparkassen and cooperative banks in Bavaria and North Rhine-Westphalia seeking lower TCO. Frankfurt's fintech cluster is incubating API-first challengers targeting the Mittelstand lender segment.
Canada
OSFI B-20 mortgage underwriting guidelines and provincial privacy law fragmentation complicate multi-jurisdiction CRM deployments for national lenders. Credit unions in Ontario and British Columbia lead cloud migration as core processor integrations mature. Toronto's technology corridor hosts emerging vendors specializing in embedded fintech marketplace distribution.
Australia
ASIC's responsible lending obligations and open banking regime under the Consumer Data Right mandate granular audit trail functionality. Non-bank originators in New South Wales and Victoria prioritize mobile-native borrower portals for millennial and Gen Z applicants. Sydney's fintech ecosystem is developing point solutions for credit pull and valuation workflow embedding.
Mortgage CRM Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: vertical specialists with native mortgage workflows, horizontal platform vendors extending through fintech partnerships, and emerging API-first challengers attacking mid-market share. Tier-one incumbents defend position through LOS integration depth, while tier-two players compete on implementation speed and subscription flexibility. Dominant competitive moves include embedded marketplace distribution through loan origination system app exchanges and modular microservices architecture re-platforming.
Within the vertical specialist tier, Total Expert and Jungo exemplify archetypes prioritizing native compliance tool integration and accounting system connectivity respectively. Salesforce occupies a position representing horizontal platform extensibility competing through ecosystem breadth rather than mortgage-specific depth. These three anchors illustrate how vendor R&D allocation diverges between workflow specialization and platform generality.
| Leading Market Players |
|---|
| BNTouch |
| Total Expert |
| Salesforce |
| nCino |
| Floify |
| Zeitro |
| Aidium |
| Shape |
| Jungo |
| Others |
Supply & Pricing Matrix
San Francisco's fintech corridor concentrates cloud infrastructure capacity for mortgage CRM platforms, with hyperscaler data center expansions in Northern California directly shaping downstream SaaS pricing power for regional lenders.
Pricing Analysis
Certification level creates the primary spread between SOC 2 Type II validated platforms and unaudited alternatives. The dominant pricing structure runs through tiered subscription models with lead management modules commanding premiums over basic contact databases. Price differentiation stems from API integration maturity and embedded compliance automation depth. Cost compression in the independent broker tier is intensifying as low-touch SaaS vendors compete on implementation speed. Independent mortgage brokers exhibit highest price sensitivity, while enterprise depository institutions prioritize audit trail depth over subscription cost.
Supply Chain Analysis
AWS, Microsoft Azure, and Google Cloud Platform hold concentrated capacity for multi-tenant mortgage CRM deployments. Geographic supply concentration centers on the United States, Ireland, and Singapore for primary data residency compliance. Raw material dependencies include API gateway infrastructure, identity verification services, and e-signature certificate authorities. Single-source vulnerability sits with LOS connector maintenance teams, where proprietary data schema expertise concentrates among specialized engineering pools. Distribution runs through direct sales organizations, system integrator partnerships, and embedded fintech marketplaces within loan origination system exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
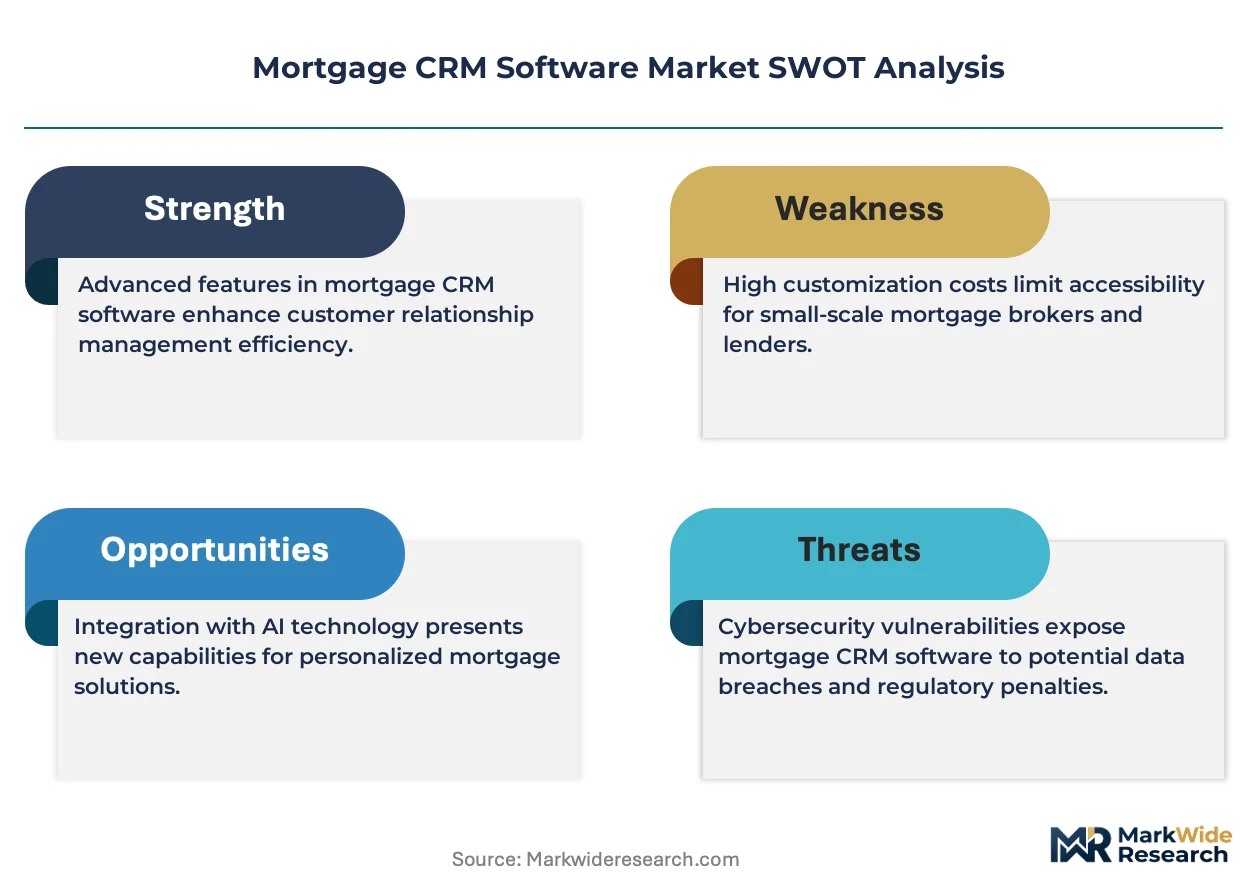
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive advantage. CFPB compliance requirements and NMLS synchronization complexity erect switching costs that protect incumbent positions.
For Market Incumbents: Entrench through deeper LOS integration with Ellie Mae Encompass and Black Knight, while expanding API-first microservices architecture to counter emerging cloud-native challengers. Prioritize backward integration into document automation capabilities as e-closing mandates expand across Sun Belt states.
For New Entrants and Emerging Players: Pursue white-space opportunities in independent mortgage broker networks across Texas and Florida, where low-touch SaaS deployment gaps persist. Target mobile-native borrower portal functionality for first-time homebuyer segments. Lead with embedded fintech marketplace distribution through loan origination system app exchanges to compress customer acquisition economics.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with native compliance tool integration over horizontal platform extenders. Long-term viability hinges on regulatory entrenchment depth and LOS connector portfolio breadth. Acquisition target archetype: API-first challengers with proven NMLS automation and multi-state deployment capability. The signal to watch is CFPB Section 1033 implementation pace, which will determine open banking interoperability investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native LOS connectivity with Encompass reduces implementation timelines from months to weeks for regional lenders. |
| Strategic Partnership | Embedded fintech marketplace distribution through Ellie Mae app exchanges cuts customer acquisition costs substantially. |
| Acquisition of Specialist Firm | Document automation capabilities address Virginia and Nevada remote online notarization mandate compliance requirements. |
| Product Launch | Mobile-native borrower portals capture millennial and Gen Z applicants in Sun Belt metropolitan markets. |
| Geographic Expansion | Multi-state NMLS compliance automation unlocks independent broker networks in California and Arizona. |
Research Methodology
A spread of perspectives from mortgage CRM product managers, loan origination system integration specialists, compliance officers at regional lenders, and independent mortgage broker technology buyers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through CFPB regulatory filings, NMLS database documentation, SEC disclosures from publicly traded fintech vendors, and loan origination system partner ecosystem directories. Bottom-up sizing of deployment volumes across cloud, SaaS, on-premise, and hybrid architectures triangulated against top-down addressable market estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end user category, feature capability bundling, and integration complexity tier. CAGRs were derived from fitted growth curves calibrated to vendor revenue disclosures and buyer procurement cycle surveys. Industry-specific forecast inputs incorporated TRID compliance replacement cycle timing and state-level e-notarization adoption trajectories.
Macroeconomic conditions sit as an overlay; deviation in mortgage origination volume, interest rate movements, and housing affordability indices would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation pace and cloud infrastructure cost curves. Quarterly review of CFPB rulemaking announcements, state e-notarization legislative calendars, and hyperscaler data center expansion plans is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Thailand CRM Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Pharmaceutical Customer Relationship Management (CRM) Software Market
Customer Relationship Management (CRM)
Online CRM Software Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
Global Customer Success Management Market