
 Retail CRM Software Market | 2026-2036
Retail CRM Software Market Size, Share, and Industry Trends Forecast 2026-2036
Retail CRM Software Market Insights
The EU AI Act is expanding compliance obligations for algorithmic customer profiling across European retail operations. Salesforce leverages its Einstein AI layer to sustain competitive positioning in predictive analytics for brick-and-mortar chains. HubSpot CRM anchors its growth in mid-market retailers seeking unified marketing automation. Oracle CX dominates enterprise installations through deep ERP integration and industry-specific data models.
Retail CRM software comprises integrated platforms that consolidate customer interaction data, transaction histories, and behavioral signals into unified profiles accessible across sales, marketing, and service channels. These systems typically operate through API-connected cloud architectures with real-time synchronization across point-of-sale terminals, e-commerce storefronts, and mobile applications to enable personalized engagement at scale. Cloud-based deployments lead adoption among retailers prioritizing elastic infrastructure and rapid feature iteration, while on-premises solutions retain traction among operators with stringent data residency requirements. Customer segmentation capabilities command premium pricing as retailers invest in micro-targeting precision, and marketing automation modules represent the fastest-expanding feature category as brands automate lifecycle campaigns across digital and physical touchpoints.
The EU AI Act and GDPR jointly constrain how European retailers deploy automated decision-making in loyalty programs and dynamic pricing, compelling vendors to build explainability tools and consent management frameworks directly into platform architectures. In the United States, state-level privacy statutes including the California Consumer Privacy Act create a fragmented compliance landscape that favors configurable CRM architectures with jurisdiction-specific data handling rules. Stakeholders must evaluate whether their vendor roadmaps incorporate native privacy engineering or rely on bolt-on compliance layers that fragment customer views.
Market Dynamics
The Retail CRM Software Market is experiencing structural compression as unified data platforms consolidate fragmented point solutions, with specialty retail chains accelerating replacement cycles to achieve omnichannel visibility.
Growth Catalysts
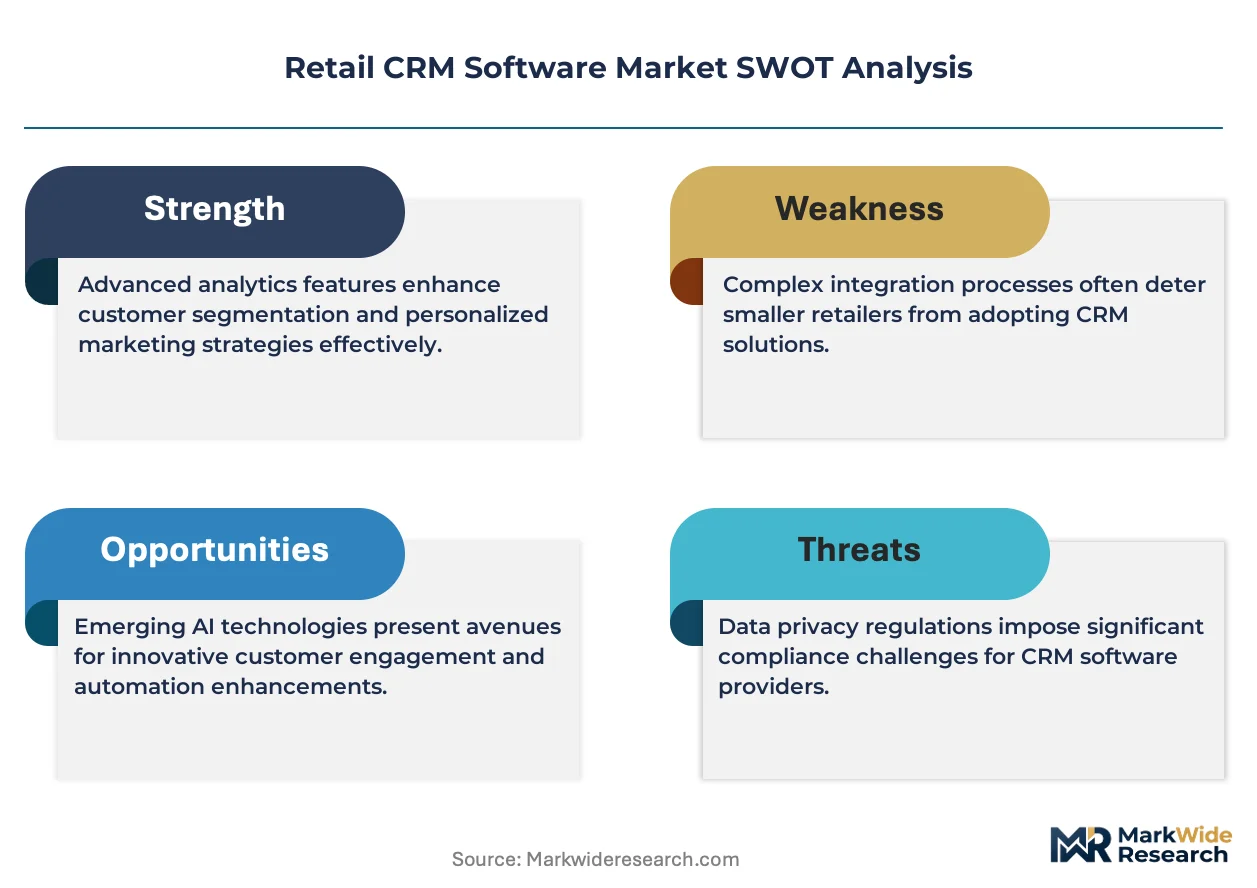
- EU AI Act Compliance Infrastructure:The EU AI Act mandates explainability in algorithmic customer profiling, compelling retailers to upgrade CRM architectures with native consent management and audit trails. Vendors embedding these capabilities capture replacement demand from legacy installations.
- Real-Time Inventory Synchronization:Cloud-native API architectures now enable millisecond latency between POS terminals, e-commerce storefronts, and mobile applications. Mid-market apparel chains deploy these integrations to eliminate stockout-driven cart abandonment.
- Behavioral Micro-Targeting:Customer segmentation modules command premium pricing as retailers invest in precision marketing automation. Lifecycle campaign orchestration across digital and physical touchpoints drives module attach rates.
Market Restraints
- GDPR-EU AI Act Overlap:Dual compliance obligations in automated decision-making for loyalty programs and dynamic pricing create architectural complexity. European retailers face extended vendor evaluation cycles.
- Data Residency Requirements:On-premises deployments retain traction among operators in Germany and France with stringent sovereignty mandates, limiting cloud migration velocity.
- Integration Debt:Legacy ERP systems in established retail chains require costly middleware layers to connect modern CRM platforms, inflating total cost of ownership.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentives for electronics manufacturing create demand traceability requirements. Domestic retail chains seek CRM platforms with supplier integration modules.
- Conversational AI Convergence:Natural language processing merging with predictive analytics enables voice-activated customer service automation. Grocery chains pilot these interfaces for order modification.
- California Privacy Fragmentation:The California Consumer Privacy Act and subsequent amendments favor configurable CRM architectures with jurisdiction-specific data handling rules. Vendors with native privacy engineering capture US enterprise accounts.
Industry Challenges
- Consent Workflow Engineering:Building granular preference centers that satisfy both GDPR and EU AI Act requirements demands specialized product teams. Vendors struggle to hire privacy engineers with retail domain expertise.
- Legacy POS Integration:Decades-old terminal infrastructure in department stores requires custom API development. Implementation timelines stretch beyond initial projections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail CRM Software Market |
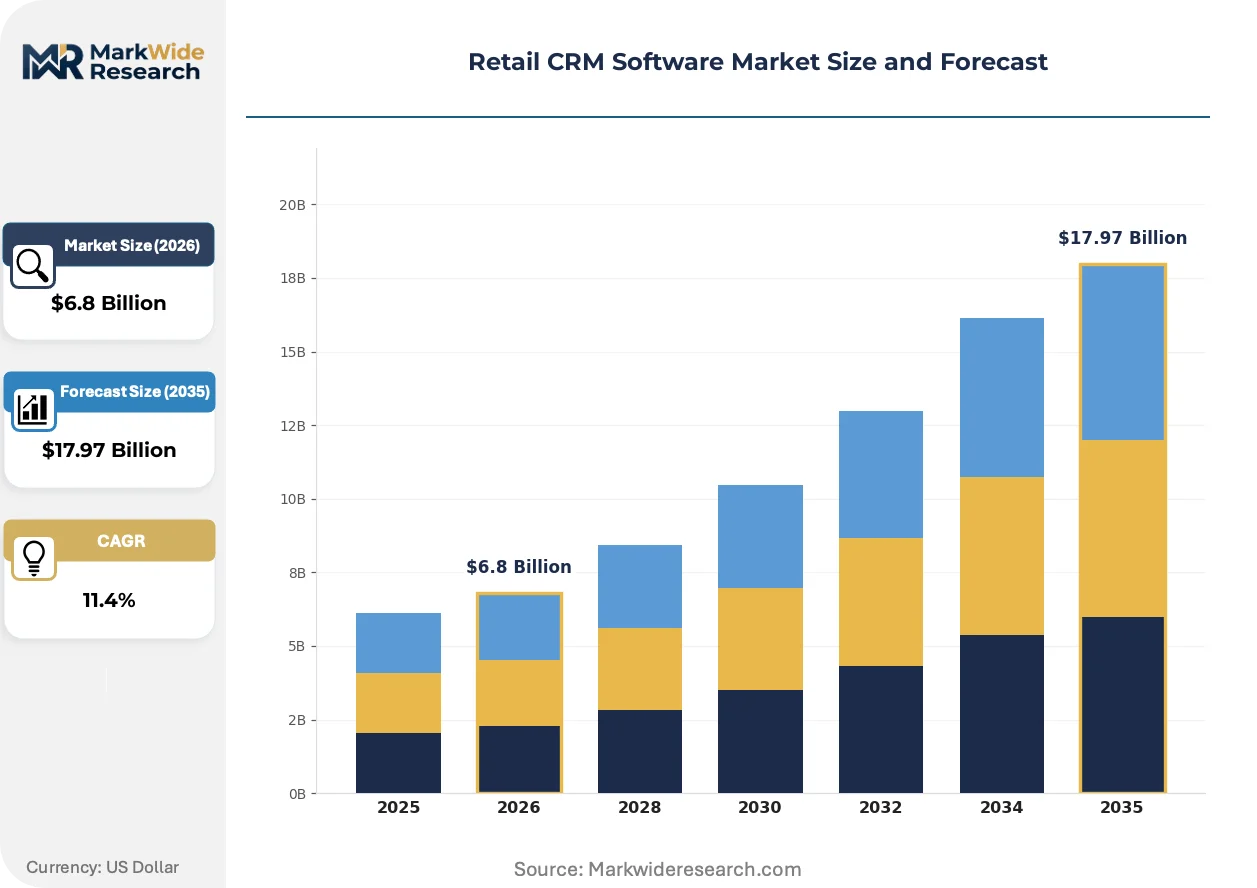
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-based, On-premises, Hybrid, Mobile Deployment Model: Public Cloud, Private Cloud, SaaS, IaaS End User Type: Small Enterprises, Medium Enterprises, Large Enterprises, E-commerce Feature Set: Lead Management, Marketing Automation, Analytics, Customer Segmentation |
| Companies Covered | Salesforce, HubSpot CRM, Zoho CRM, Freshworks, Zence, Microsoft Dynamics 365, Oracle CX, Pipedrive, Creatio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail CRM Software Market Trends and Innovations
Artificial intelligence layers are penetrating core CRM functions, transforming how retailers predict churn and optimize lifetime value calculations. Three developments define this shift.
Unified customer data platforms are expanding into predictive inventory allocation, synthesizing purchase histories with external demand signals to automate replenishment decisions. Grocery and fast-fashion retailers deploy these capabilities to reduce markdown exposure. The technology is expanding into supplier collaboration networks, compressing forecast-to-shelf cycles.
The EU AI Act's risk-based classification system imposes documentation burdens on high-risk automated decision-making in credit scoring and loyalty tiering. Retailers must maintain technical files demonstrating algorithmic fairness. European operations face the steepest compliance costs, accelerating consolidation toward vendors with pre-built audit frameworks.
After-sales service unbundling is fragmenting traditional support contracts. Retailers now procure customer service automation, warranty management, and returns processing as separate modules. This pattern concentrates among direct-to-consumer brands in the United States seeking operational flexibility over bundled suites.
Retail CRM Software Market Segmentation
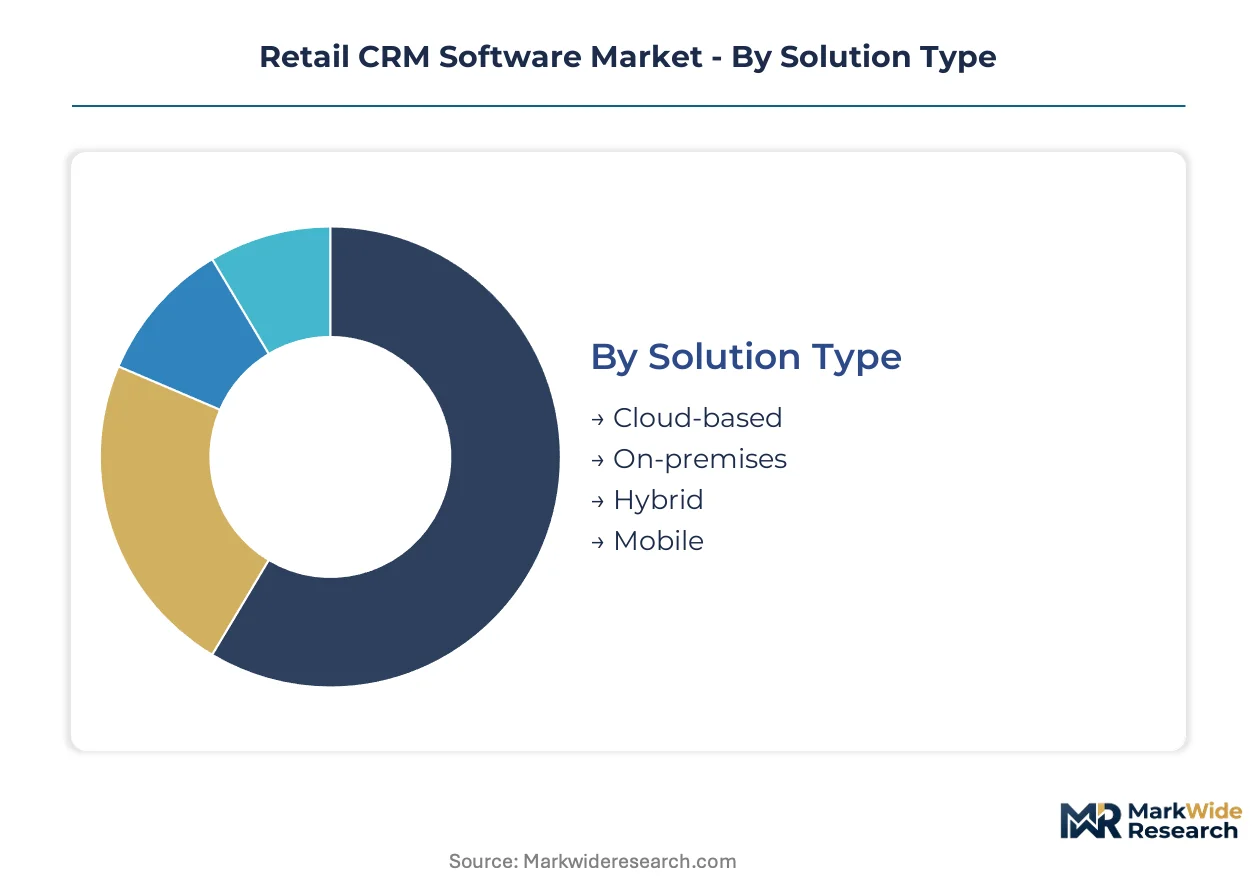
Retail CRM segmentation reveals how deployment architecture, infrastructure sourcing, organizational scale, and functional depth shape vendor selection and pricing power. Understanding these dimensions exposes where platform consolidation concentrates and where point solutions retain viability.
Solution Type:
Cloud-based deployments dominate transaction volume while on-premises solutions command premium pricing for data sovereignty compliance.
- Cloud-based:Multi-tenant architectures with elastic compute scaling support real-time synchronization across POS, e-commerce, and mobile touchpoints. Demand concentrates among mid-market apparel chains in the United States eliminating stockout-driven cart abandonment through millisecond inventory visibility.
- On-premises:Single-tenant installations with localized data storage satisfy stringent residency mandates. German and French retailers under GDPR and national sovereignty requirements sustain this segment despite higher total cost of ownership.
- Hybrid:Split architectures partition sensitive customer data on-premises while pushing analytics workloads to cloud infrastructure.
- Mobile:Native iOS and Android applications extending core CRM functionality to field sales and store associates.
Mature deployment sits with on-premises installations in European department stores. Newer deployment is concentrated in cloud-based platforms among digitally native retailers.
Deployment Model:
Infrastructure abstraction level determines operational control trade-offs and compliance flexibility across jurisdictions.
- SaaS:Fully managed application layers with vendor-controlled updates and security patching. Large enterprise retailers in the United States prioritize rapid feature iteration over customization depth.
- Private Cloud:Dedicated tenant environments with configurable network isolation and encryption standards. Financial services-affiliated retailers in Switzerland and Luxembourg mandate this architecture for customer data handling.
- Public Cloud:Shared infrastructure with consumption-based pricing and geographic redundancy.
- IaaS:Bare-metal provisioning with retailer-managed middleware and application stacks.
Established procurement patterns favor SaaS for speed-to-value. Compliance-driven sectors are expanding most quickly in private cloud configurations.
End User Type:
Organizational scale dictates integration complexity, customization requirements, and average contract value.
- Large Enterprises:Multi-divisional implementations spanning thousands of stores with ERP interconnection requirements. Oracle CX and Salesforce deployments concentrate among Fortune 500 retailers prioritizing unified customer views across acquired banners.
- E-commerce:Direct-to-consumer brands with API-first architectures and headless commerce integration. Shopify-native CRM adoption climbs fastest among digitally verticalized brands in California and New York.
- Medium Enterprises:Regional chains with 50-500 locations seeking pre-configured industry templates.
- Small Enterprises:Independent retailers with basic contact management and email marketing needs.
Feature saturation defines large enterprise deployments. E-commerce represents the steepest expansion trajectory as pure-play brands displace traditional retail.
Feature Set:
Module attach rates diverge sharply between foundational data management and advanced predictive capabilities.
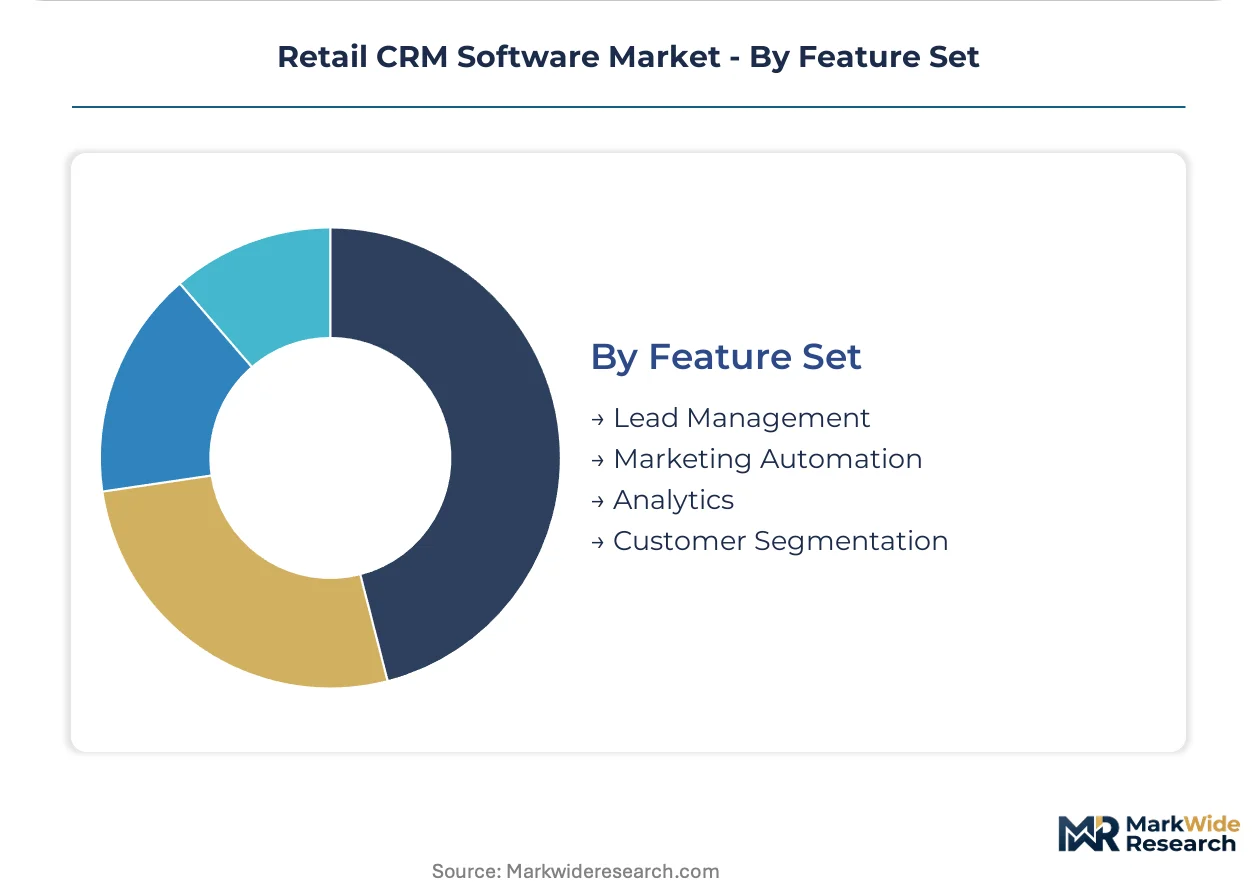
- Customer Segmentation:Algorithmic clustering engines processing behavioral signals, transaction histories, and external demographic overlays. Specialty retail chains in the United Kingdom deploy these modules for micro-targeting precision that commands premium platform pricing.
- Marketing Automation:Lifecycle campaign orchestration across email, SMS, push notifications, and in-store beacon triggers. Fast-fashion retailers in Italy and Spain attach this module fastest to automate seasonal clearance campaigns.
- Lead Management:Pipeline tracking and opportunity scoring for B2B wholesale and corporate account teams.
- Analytics:Dashboard visualization and ad-hoc reporting on customer lifetime value and churn prediction.
Standardized deployment sits with lead management across legacy installations. Marketing automation is gaining share fastest as retailers automate touchpoint orchestration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail CRM software consumption concentrates in the United States and Western Europe, while development and cloud infrastructure gravitate toward India and Ireland. Production of CRM platforms spans distributed engineering centers rather than concentrated manufacturing.
United States
Enterprise retailers in California and New York prioritize omnichannel integration and real-time inventory synchronization. The California Consumer Privacy Act and subsequent amendments create jurisdiction-specific compliance requirements that favor configurable CRM architectures. The San Francisco Bay Area hosts the densest concentration of CRM platform headquarters and cloud infrastructure deployments.
Germany
Department store chains and automotive-affiliated retailers demand stringent data residency and ERP integration capabilities. The national data protection authority enforces GDPR compliance with particular rigor, sustaining demand for on-premises and private cloud deployments. The Rhine-Ruhr metropolitan region contains the highest concentration of legacy retail infrastructure requiring CRM modernization.
United Kingdom
Fast-fashion retailers and grocery chains invest in customer segmentation modules for micro-targeting precision. The Information Commissioner's Office mandates explicit consent mechanisms for automated marketing communications. London anchors both financial services-affiliated retail operations and SaaS vendor European headquarters.
France
Luxury goods houses and specialty retail chains deploy CRM platforms with emphasis on clienteling and personalized in-store experiences. CNIL enforcement of GDPR and emerging EU AI Act obligations shapes vendor selection criteria. The Paris metropolitan region concentrates headquarters of global luxury brands with sophisticated CRM requirements.
India
Domestic retail chains and e-commerce platforms accelerate cloud-native CRM adoption for customer acquisition at scale. The Production-Linked Incentive scheme for electronics manufacturing creates supplier traceability requirements that CRM platforms address. Bangalore and Mumbai host the primary engineering centers developing CRM software for global vendors.
Retail CRM Software Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with established cloud infrastructure. Market concentration remains moderate, with a handful of vendors capturing enterprise accounts while numerous specialists serve mid-market segments. Two strategic archetypes dominate: horizontal SaaS platforms with retail verticalization, and ERP-native solutions with deep enterprise integration. Competitive moves center on AI layer investments and geographic compliance certification rather than price-based rivalry.
Among horizontal platform providers, Salesforce and HubSpot CRM exemplify the SaaS-native archetype with retail-specific module development. Oracle CX occupies a position representing ERP-integrated deployments for Fortune 500 retailers. Zoho CRM anchors the mid-market accessibility tier with pricing models targeting regional chains. These three company structures—American Inc., American Inc., and Indian Co.—illustrate the geographic and strategic diversity of vendor origins without implying specific market share positions.
| Leading Market Players |
|---|
| Salesforce |
| HubSpot CRM |
| Zoho CRM |
| Freshworks |
| Zence |
| Microsoft Dynamics 365 |
| Oracle CX |
| Pipedrive |
| Creatio |
| Others |
Pricing and Supply Chain Analysis
Privacy engineering talent concentration in Bangalore and Dublin establishes labor-cost differentials that widen pricing-tier spreads between premium compliance-native platforms and economy-tier alternatives.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects cloud infrastructure cost pass-throughs and intensifying competition from Indian vendors. Subscription-based SaaS pricing dominates, with three-tier differentiation across premium enterprise, standard professional, and economy basic levels. Price differentiation hinges on GDPR-EU AI Act certification depth and real-time API volume allowances. Pricing pressure stems from open-source CRM alternatives gaining traction among digitally native retailers. Small enterprises exhibit highest price sensitivity, while Fortune 500 retailers prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure now mandate multi-hyperscaler qualification among enterprise retailers seeking geographic redundancy. Engineering talent concentrates in India, Ireland, and the United States, with Bangalore hosting the densest CRM development clusters. Platform architectures draw from open-source middleware, proprietary AI frameworks, and API gateway technologies. Single-source vulnerability persists in specialized privacy engineering skill pools. Distribution runs through direct vendor sales teams, systems integrators, and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over explainable AI layers and consent management engines determines margin capture.
For Market Incumbents: Deepen native privacy engineering capabilities to preempt regulatory fragmentation as the EU AI Act expands risk classifications. Acquire specialized consent workflow vendors in Germany and France before talent scarcity inflates valuations. Consolidate ERP integration partnerships to defend against Oracle CX's enterprise lock-in.
For New Entrants and Emerging Players: The price-point gap between Salesforce premium tiers and Zoho economy offerings creates entry space for compliance-focused mid-market alternatives. Target regional apparel chains in Italy and Spain with pre-configured GDPR templates and rapid deployment guarantees. Pursue channel partnerships with Shopify and WooCommerce for embedded CRM distribution.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated platforms with captive AI development and established EU AI Act audit frameworks. Long-term viability rests on consolidating fragmented mid-market vendors before cloud hyperscalers launch native retail CRM suites. Watch for CNIL enforcement patterns as the signal indicating compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Native Privacy Engineering Investment | Embedded GDPR-EU AI Act compliance reduces vendor evaluation cycles for European retailers. |
| ERP Integration Partnership | Deep Oracle and SAP connectivity captures Fortune 500 replacement demand. |
| Conversational AI Module Launch | Voice-activated service automation penetrates grocery and fast-fashion segments. |
| Geographic Compliance Certification | Pre-built CNIL and BSI audit frameworks accelerate German and UK sales cycles. |
| Acquisition of Consent Workflow Specialist | Granular preference center technology addresses EU AI Act explainability mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CRM product managers, retail CIOs, privacy compliance officers, and systems integration leads. Secondary sources encompassed SEC 10-K disclosures, CNIL enforcement bulletins, EU AI Act implementation guidance, and cloud hyperscaler capex reports. Bottom-up segment sizing triangulated against top-down market aggregation.
Granularity-level modeling deployed deployment architecture, organizational scale, and feature module attach rates as primary segmentation dimensions across the projection horizon. CAGRs derived from segment-level growth rate synthesis incorporating cloud adoption curves and compliance-driven replacement cycles. Forecast inputs included EU AI Act implementation timelines and PLI scheme traceability requirements.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than on-premises legacy installations due to vendor disclosure transparency. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and enterprise cloud migration velocity. A model refresh is warranted upon material change in EU AI Act risk classification scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Customer Communication Management Market
Customer Relationship Management (CRM)
Pharmaceutical Customer Relationship Management (CRM) Software Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market