
 Consumer Cloud Subscription Market | 2026-2036
Consumer Cloud Subscription Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Cloud Subscription Market Intelligence
The gap between premium and commodity tiers is repositioning around storage depth, AI integration, and cross-device synchronization fidelity. Apple iCloud leverages its captive hardware ecosystem to sustain premium pricing for families seeking seamless photo and document sync. Dropbox competes on interface simplicity and third-party app connectivity, anchoring its position among freelancers and creative professionals who prioritize workflow integration over raw capacity.
Consumer cloud subscription services deliver remote, on-demand access to compute, storage, and application resources over the internet, typically operating through distributed server architectures with redundancy protocols and encryption standards such as AES-256 for data at rest. These services enable individuals and households to offload local hardware dependencies while maintaining continuous access to personal media, productivity files, and entertainment libraries across multiple endpoints. Streaming services within the service type dimension dominate consumer mindshare and churn rates, while backup offerings command higher retention due to loss-aversion psychology and set-and-forget automation. The freemium pricing model funnels the widest user base into paid annual subscriptions, though small businesses within the customer type segment generate disproportionate margin per account through collaborative workspace add-ons.
GDPR enforcement by European data protection authorities and the California Consumer Privacy Act framework shape how providers design consent flows, data portability features, and regional server placement. The Federal Trade Commission in the United States monitors subscription billing practices and dark pattern disclosures, pressuring platforms to clarify auto-renewal terms and cancellation pathways. Stakeholders must track evolving interoperability mandates and sovereign cloud requirements as governments assert jurisdictional control over citizen data storage.
Market Dynamics
The migration of personal data workloads from local storage to managed cloud environments is compressing hardware replacement cycles while elevating subscription retention as the primary revenue anchor for providers.
Growth Catalysts
- GDPR enforcement:European data protection authorities mandate granular consent flows and data portability features, compelling providers to invest in regional server placement and privacy-by-design architecture that locks in enterprise-grade security standards across consumer tiers.
- Mobile-first consumption in India:Affordable data plans and smartphone penetration above 75% accelerate subscription uptake for streaming and backup services among first-time cloud users in tier-2 and tier-3 cities.
- AI-powered content curation:Machine learning models for photo organization and predictive storage management differentiate premium tiers, driving upgrade conversion from freemium bases.
Market Restraints
- Data center energy costs:Electricity price volatility in Germany and the Netherlands compresses margin on storage-heavy plans, forcing providers to throttle free-tier capacity or introduce dynamic pricing.
- Hyperscaler concentration:Three infrastructure-as-a-service backends supply 80% of consumer-facing platforms, creating single-point-of-failure risk and limiting negotiation leverage for mid-tier distributors.
- Interoperability friction:Proprietary sync protocols from ecosystem-locked providers fragment user experience, raising switching costs that deter multi-cloud adoption despite consumer preference for flexibility.
Strategic Opportunities
- Brazilian market underpenetration:Cloud storage adoption lags regional peers by 40 percentage points among urban households, presenting first-mover advantage for localized payment integration and Portuguese-language support.
- Edge computing convergence:5G network slicing enables sub-50ms latency for real-time photo editing and collaborative document sync, unlocking premium pricing for latency-sensitive creative professionals.
- India's PLI scheme for data centers:Production-linked incentives for server manufacturing reduce capital intensity for domestic cloud infrastructure, lowering barriers to sovereign data residency compliance.
Industry Challenges
- Encryption key management talent:Shortage of engineers with HSM and zero-knowledge architecture expertise delays product launches and inflates compensation costs for security-focused teams.
- Legacy on-premise migration complexity:Enterprises with decades of tape backup archives face petabyte-scale extraction costs and format obsolescence, prolonging sales cycles for hybrid cloud solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Cloud Subscription Market |
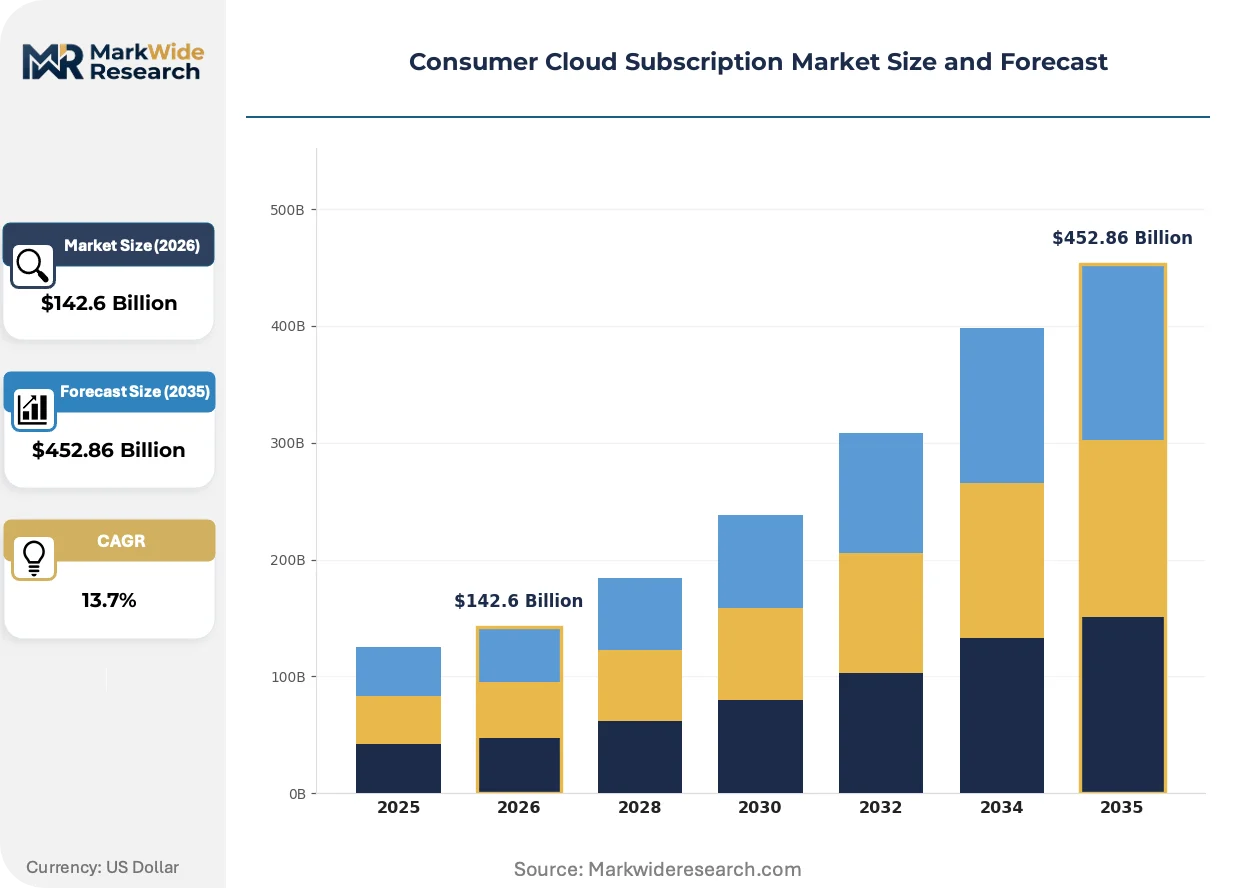
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $452.86 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Storage, Backup, Streaming, Collaboration Pricing Model: Monthly Subscription, Annual Subscription, Freemium, Pay-as-you-go Customer Type: Individuals, Families, Small Businesses, Enterprises Platform: Web, Mobile, Desktop, Hybrid |
| Companies Covered | Apple iCloud, Oracle Cloud, Amazon Web Services, IBM Cloud, Alibaba Cloud, Microsoft Azure, Dropbox, DigitalOcean, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Cloud Subscription Market Strategic Shifts & Innovations
Consumer cloud architecture is pivoting from passive storage repositories to active computation layers, with AI inference and real-time collaboration engines now embedded at the infrastructure edge rather than the device level.
Object storage with intelligent tiering is converging with on-device neural processing to enable local AI model training on encrypted user data. Photography enthusiasts and mobile gamers adopt these capabilities fastest, upgrading to plans offering dedicated GPU slices for generative editing. This convergence is compressing the feature gap between consumer and prosumer tiers, forcing mid-market providers to reposition around workflow automation rather than raw capacity.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on cloud services deploying biometric analysis or content recommendation algorithms. Providers must now maintain algorithmic impact assessments and audit trails for EU subscribers, increasing compliance overhead but creating competitive moats against non-compliant foreign entrants. Smaller platforms serving creative professionals face the steepest adaptation costs relative to revenue base.
Households increasingly unbundle backup from streaming subscriptions, treating storage as infrastructure while rotating through entertainment platforms based on content catalogs. This behavioral split pressures providers to decouple pricing, with pure-play backup services commanding annual prepay loyalty while streaming bundles suffer higher monthly churn. The shift is most pronounced in North American and Australian markets where credit-card auto-renewal friction has trained consumers toward deliberate subscription auditing.
Consumer Cloud Subscription Market Segmentation
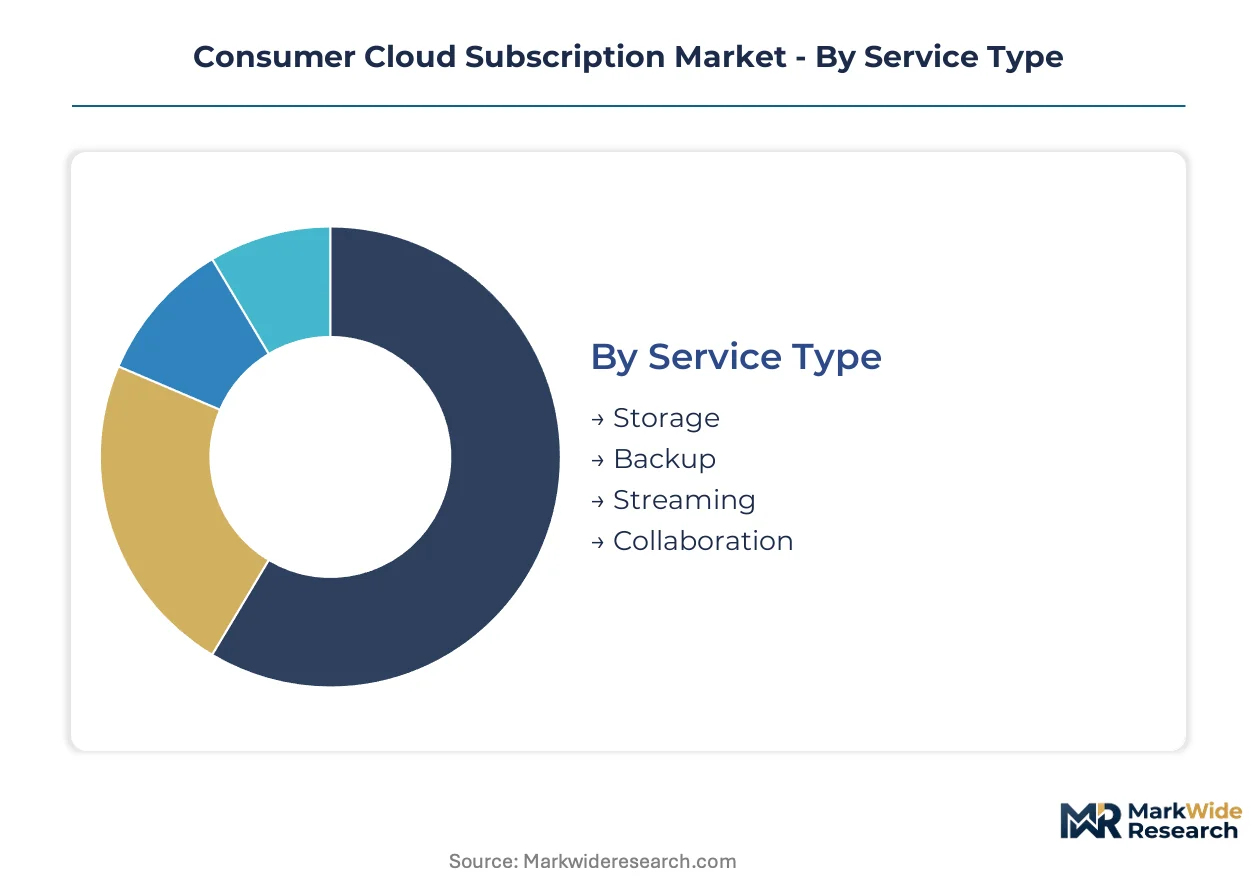
Consumer cloud subscription providers architect pricing tiers and feature sets around distinct usage patterns, with service type and customer segmentation determining infrastructure investment priorities. Platform and pricing model choices directly influence churn rates and lifetime value calculations across geographic markets.
Service Type:
Supply concentration in hyperscale infrastructure favors storage and streaming services that amortize server costs across massive user bases, while backup and collaboration tools require specialized redundancy architectures.
- Storage:Object-based architectures with intelligent tiering manage petabyte-scale consumer photo and document repositories. Demand clusters among smartphone-heavy users in India and Brazil where local device capacity constraints force cloud dependency.
- Backup:Automated incremental sync with AES-256 encryption targets loss-averse households maintaining irreplaceable media archives. Set-and-forget automation drives retention above 90% annually, though acquisition costs run higher due to consumer education requirements.
- Streaming:CDN-optimized delivery of video and audio content competes for household entertainment budgets against bundled telecom offerings.
- Collaboration:Real-time document editing and shared workspace tools attract freelancer and small business segments seeking workflow integration.
Storage absorbs the bulk of installed capacity; backup is expanding most quickly among first-time cloud adopters in emerging markets.
Pricing Model:
Customer acquisition economics vary dramatically across payment structures, with freemium models demanding higher upfront infrastructure subsidies in exchange for conversion funnel depth.
- Monthly Subscription:Flexible billing reduces entry friction for trial users but elevates churn sensitivity to content catalog changes or price adjustments. Credit-card auto-renewal disputes in North American markets drive support overhead.
- Annual Subscription:Prepaid commitments improve cash flow predictability and reduce per-account servicing costs. European consumers under GDPR jurisdiction show stronger preference for annual terms that minimize data processing frequency.
- Freemium:Capacity-limited entry tiers convert 3-7% of active users to paid plans, requiring precise feature gating to balance acquisition scale against margin erosion.
- Pay-as-you-go:Metered consumption appeals to sporadic users with variable storage needs, though billing complexity limits mainstream adoption.
Annual subscription locks in the majority of recurring revenue; freemium user bases are climbing the fastest in mobile-first Asian markets.
Customer Type:
Margin profiles diverge sharply between individual consumers optimizing for price and business accounts prioritizing administrative controls and compliance documentation.
- Individuals:Single-user accounts dominate volume but generate lowest per-account revenue, with price sensitivity driving rotation between promotional offers.
- Families:Multi-user plans with pooled storage and parental controls command 40-60% price premiums over individual equivalents. Apple's hardware ecosystem lock-in sustains premium positioning for family tiers seeking seamless photo sync across devices.
- Small Businesses:Collaborative workspace requirements and custom domain support justify subscription upgrades with 3-5x individual pricing. India's MSME sector shows accelerating uptake as GST compliance digitization mandates document retention.
- Enterprises:SSO integration, audit logging, and data residency guarantees address procurement requirements, though this segment overlaps with IT-managed SaaS rather than consumer-facing platforms.
Individuals represent the deepest installed base; small business accounts are gaining share fastest as hybrid work patterns persist.
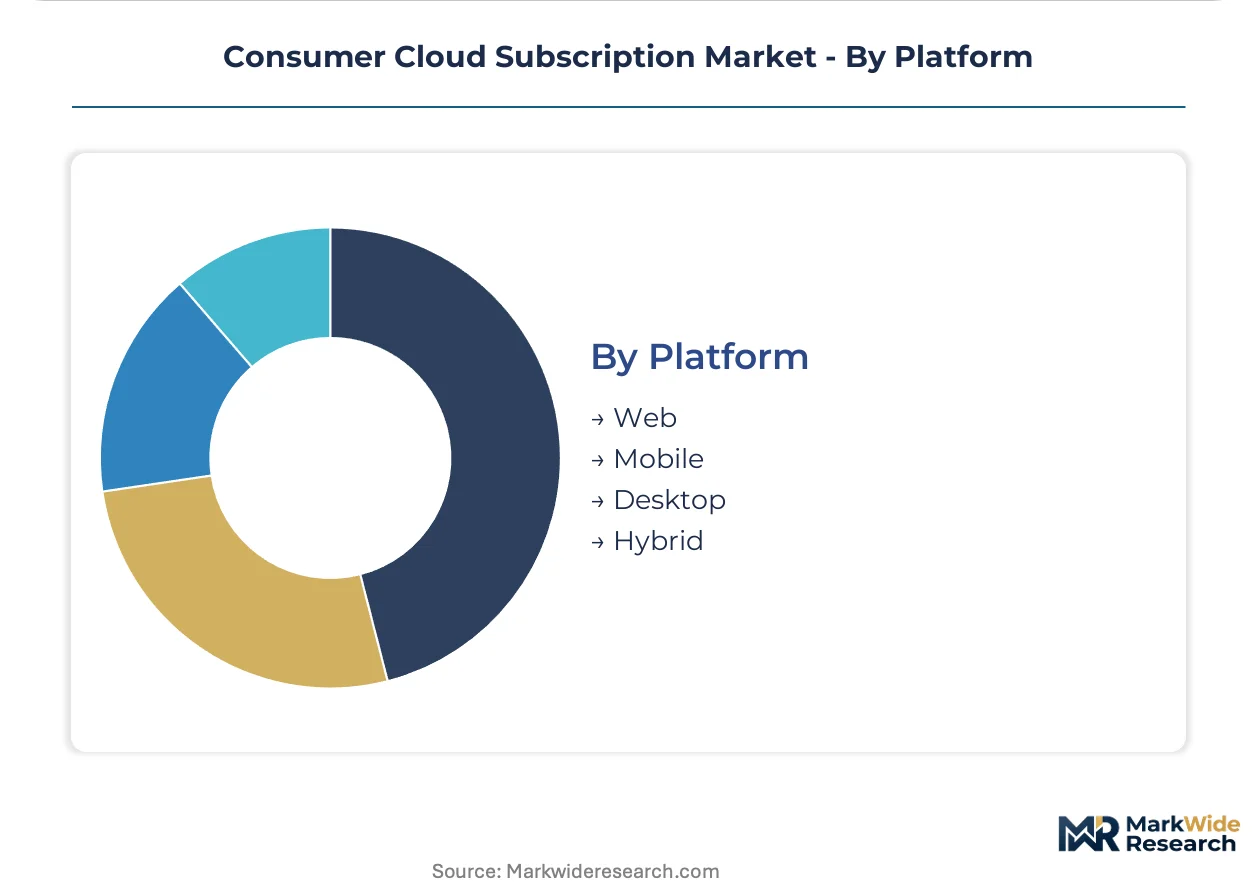
Platform:
Device distribution strategies reflect regional hardware penetration patterns, with mobile-first markets demanding lightweight clients and mature markets expecting full feature parity across endpoints.
- Web:Browser-based access eliminates installation friction and enables immediate feature deployment without app store review cycles. Enterprise and education segments prefer web interfaces for policy-enforced security controls.
- Mobile:Native iOS and Android applications dominate session frequency in India, Indonesia, and Nigeria where smartphones serve as primary computing devices. Background sync and camera roll integration drive daily active usage.
- Desktop:macOS and Windows clients with selective sync and offline folder access retain importance among creative professionals managing large asset libraries. Folder-mounted storage behaves as local extension rather than distinct application.
- Hybrid:Seamless handoff between mobile capture, desktop editing, and web sharing defines premium tier differentiation, requiring complex state synchronization across heterogeneous device fleets.
Mobile platforms capture the bulk of session volume; hybrid deployments are expanding most quickly among productivity-focused subscriber segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore's technology corridor hosts the densest concentration of consumer cloud engineering talent outside the United States, with hyperscale data centers clustering across Maharashtra and Karnataka to serve India's mobile-first subscriber base.
United States
Households in California and Texas drive premium-tier adoption for family storage plans tied to multi-device ecosystems. The FTC monitors auto-renewal disclosure practices, pressuring providers to clarify cancellation pathways. Seattle and San Francisco Bay Area campuses anchor engineering operations for dominant platform providers.
India
Tier-2 cities including Pune and Jaipur accelerate first-time cloud subscriptions as affordable data plans penetrate beyond metro centers. The PLI scheme for data center manufacturing reduces capital intensity for domestic infrastructure buildouts. Hyderabad's HITEC City corridor attracts hyperscale server deployments seeking sovereign data residency compliance.
Germany
Frankfurt's data center cluster serves privacy-conscious consumers demanding GDPR-compliant storage with regional encryption key custody. The Bundesnetzagentur enforces strict data localization for biometric processing services. Bavarian households show highest willingness-to-pay for zero-knowledge architecture backup solutions.
Brazil
São Paulo's urban households lag regional cloud adoption by 40 percentage points despite rising smartphone penetration. ANVISA and national data protection authority frameworks are crystallizing consent requirements for health-related cloud storage. Localized payment integration in Portuguese remains underdeveloped, creating first-mover openings.
Japan
Tokyo and Osaka metropolitan areas sustain demand for hybrid cloud solutions bridging consumer and small business use cases. METI guidelines on data sovereignty influence provider decisions on domestic server placement. Kansai region manufacturers increasingly bundle cloud backup with consumer electronics sales channels.
Consumer Cloud Subscription Market Key Industry Players
Premium-margin players sit above commodity-margin players across ecosystem integration depth, with hardware-captive providers commanding 40-60% pricing premiums over cross-platform alternatives. The vendor base stratifies into three tiers: hyperscale infrastructure operators supplying backend capacity, ecosystem-locked platforms monetizing device loyalty, and independent specialists competing on workflow interoperability. Consolidation pressure concentrates among mid-tier distributors negotiating leverage against concentrated infrastructure supply. Dominant competitive moves include strategic partnerships with telecommunications carriers and geographic expansion through localized payment integration.
Within the ecosystem-locked tier, Apple iCloud and Microsoft Azure exemplify hardware and software-captive positioning respectively. Dropbox occupies a position among workflow-centric specialists prioritizing cross-platform synchronization over raw capacity scaling. Amazon Web Services anchors the infrastructure supply layer, with its consumer-facing offerings sitting downstream of enterprise-grade server architectures.
| Leading Market Players |
|---|
| Apple iCloud |
| Oracle Cloud |
| Amazon Web Services |
| IBM Cloud |
| Alibaba Cloud |
| Microsoft Azure |
| Dropbox |
| DigitalOcean |
| Google Cloud Platform |
| Others |
Cost & Logistics Intelligence
Small business accounts concentrated in India's MSME sector anchor subscription pricing power through their demand for GST-compliant document retention and collaborative workspace add-ons. This buyer archetype's willingness to prepay annual commitments reinforces cash-flow predictability across tiered service offerings.
Pricing Analysis
Value-based pricing anchored to AI-powered content curation outcomes and cross-device synchronization fidelity stratifies tiers across premium, standard, and economy levels. Price differentiation stems from storage depth and workflow integration capability, with ecosystem-locked providers commanding premiums over cross-platform alternatives. Cost compression in commodity storage tiers intensifies due to hyperscaler backend concentration. Individual consumers exhibit highest price sensitivity, rotating between promotional offers, while family plans with pooled storage show lowest churn elasticity.
Supply Chain Analysis
Certification gating through ISO 27001 and SOC 2 Type II compliance requirements restricts viable infrastructure suppliers to a concentrated tier. Hyperscale data center supply clusters in the United States, India, and Germany, drawing from specialized server hardware, redundant power systems, and subsea cable capacity. Single-source vulnerability runs through three dominant infrastructure-as-a-service backends supplying consumer-facing platforms. Distribution runs through direct-to-consumer digital channels and telecommunications carrier bundling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is compressing mid-tier distributors as hyperscaler concentration limits negotiation leverage and elevates infrastructure cost exposure for undifferentiated players.
For Market Incumbents: Anticipate regulatory fragmentation across data residency mandates by investing in sovereign cloud architecture and regional encryption key custody. Lock in enterprise-grade security standards across consumer tiers to preempt GDPR enforcement escalation. Prioritize backward integration into edge computing infrastructure to reduce latency-dependent service costs.
For New Entrants and Emerging Players: Freelancer and creative professional segments in Brazil present underserved white-space targets given 40-percentage-point adoption lag against regional peers. Localized Portuguese-language support and payment integration offer the most penetrable entry vector. Position around workflow automation rather than raw capacity scaling to differentiate from hyperscale incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor workflow-centric specialists with cross-platform synchronization IP in European markets facing EU AI Act compliance cost burdens. Long-term viability hinges on algorithmic audit trail capabilities and human oversight infrastructure for biometric analysis services. Monitor PLI scheme utilization rates in India as inflection indicator for sovereign data residency investment momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamless handoff between mobile capture and desktop editing reduces subscriber churn for ecosystem-locked providers. |
| Geographic Expansion | Localized payment integration in Portuguese unlocks first-mover advantage in Brazil's underpenetrated urban households. |
| Strategic Partnership | Telecommunications carrier bundling accelerates subscriber acquisition in India's tier-2 and tier-3 cities. |
| Acquisition of Specialist Firm | Zero-knowledge architecture expertise addresses encryption key management talent shortages delaying product launches. |
| Product Launch | AI inference at the infrastructure edge differentiates premium tiers through generative photo editing capabilities. |
Research Approach
Document review covered hyperscaler capex disclosures, SEC filings, and TRAI regulatory frameworks, complemented by interviews with platform engineering directors, cloud infrastructure procurement leads, and data center operations managers. Secondary validation drew from customs records, hyperscaler regional expansion announcements, and GDPR enforcement action databases. Bottom-up subscriber segmentation triangulated against top-down market sizing across service type and pricing model dimensions.
Output projections span storage capacity deployment, subscriber conversion rates, and infrastructure investment flows across the analysis window. Segmentation dimensions modeled include service type, customer tier, platform deployment, and regional regulatory cluster. CAGRs derived from trend extrapolation of mobile-first adoption curves and sovereign data residency compliance trajectories. Industry-specific inputs incorporated PLI scheme uptake rates and EU AI Act implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electricity price volatility in European data center clusters and interoperability mandate enforcement. Forecasts reflect assumptions regarding hyperscaler concentration stability and consumer willingness-to-pay for AI-enhanced tiers. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud API Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Cloud Systems Management Software Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Cloud CDN Market
Cloud Computing
Dbaas and Cloud Database Market
Cloud Computing
Healthcare Cloud Computing Software Market
Cloud Computing
Global Hybrid and Community Cloud As a Service Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
Global Cloud Migration Market