
 Cloud Microservices Market | 2026-2036
Cloud Microservices Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Microservices Market Intelligence
Demand from Small & Medium Enterprises is rotating market focus away from solely serving large enterprises. Amazon Web Services leverages its first-mover advantage and extensive service portfolio to capture a significant portion of this segment. Microsoft Corporation competes directly through its Azure platform, offering integrated development tools and enterprise support. Red Hat specializes in open-source solutions, providing foundational technologies for hybrid cloud deployments.
Cloud microservices define an architectural approach where a large application is built as a suite of small, independently deployable services. Each service runs in its own process and communicates via lightweight mechanisms, often an HTTP API, enabling continuous delivery and improved scalability. Within service offerings, Platform as a Service (PaaS) and Container as a Service (CaaS) are central to development, while Function as a Service (FaaS) represents the fastest-growing model. Hybrid Cloud deployments are gaining traction over purely public or private models, offering enterprises greater flexibility and data control.
Data sovereignty and privacy regulations, including Europe's GDPR and the US HIPAA for healthcare data, directly influence architectural design and deployment location choices. In China, MIIT oversight on cloud services and GB standards for data security add another layer of compliance complexity for providers. The key decision for enterprises becomes balancing the agility of microservices against the increasing overhead of managing security and compliance across a distributed system.
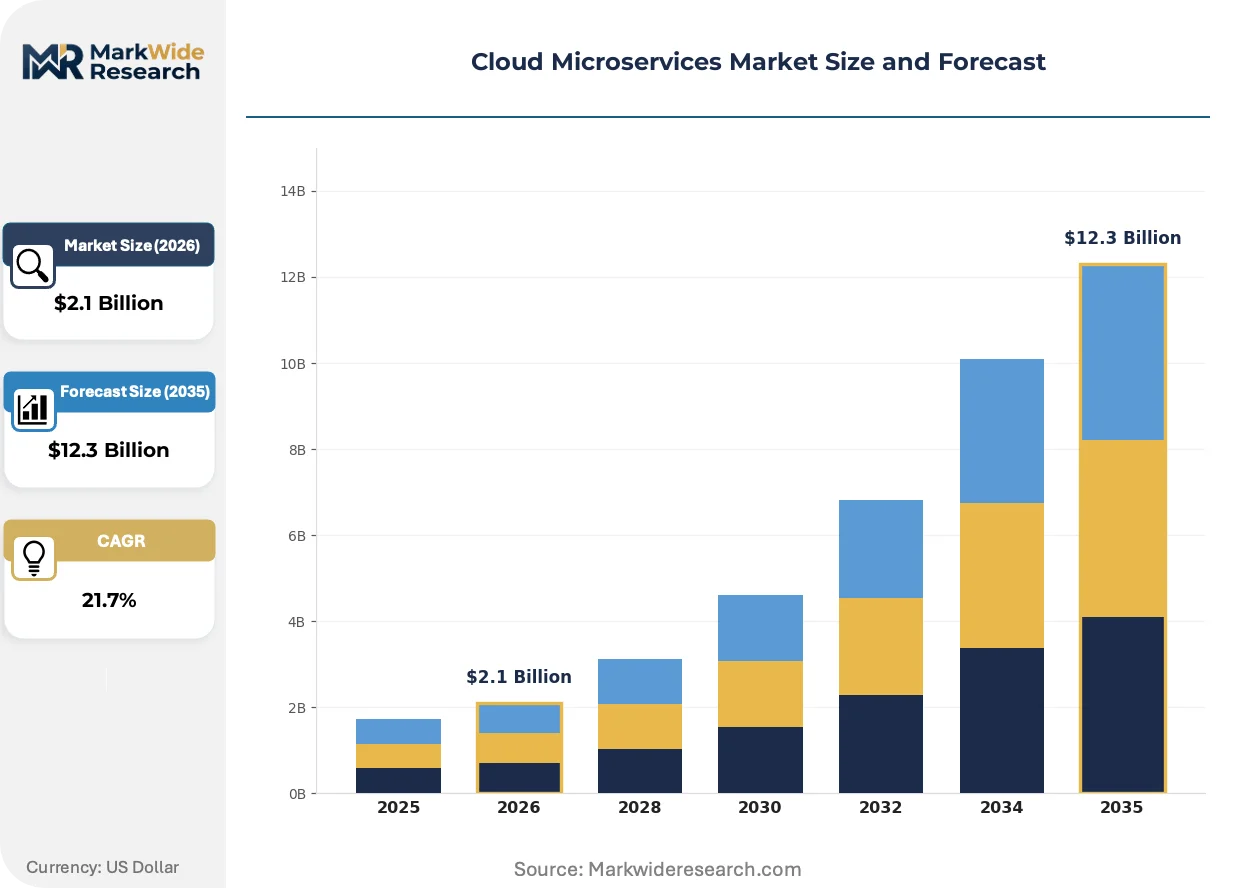
Market Dynamics
The market's core dynamic is the architectural tension between the agility benefits of distributed services and the rising operational complexity of managing security and compliance, a challenge amplified by global data sovereignty mandates from regulators like China's MIIT.
Growth Catalysts
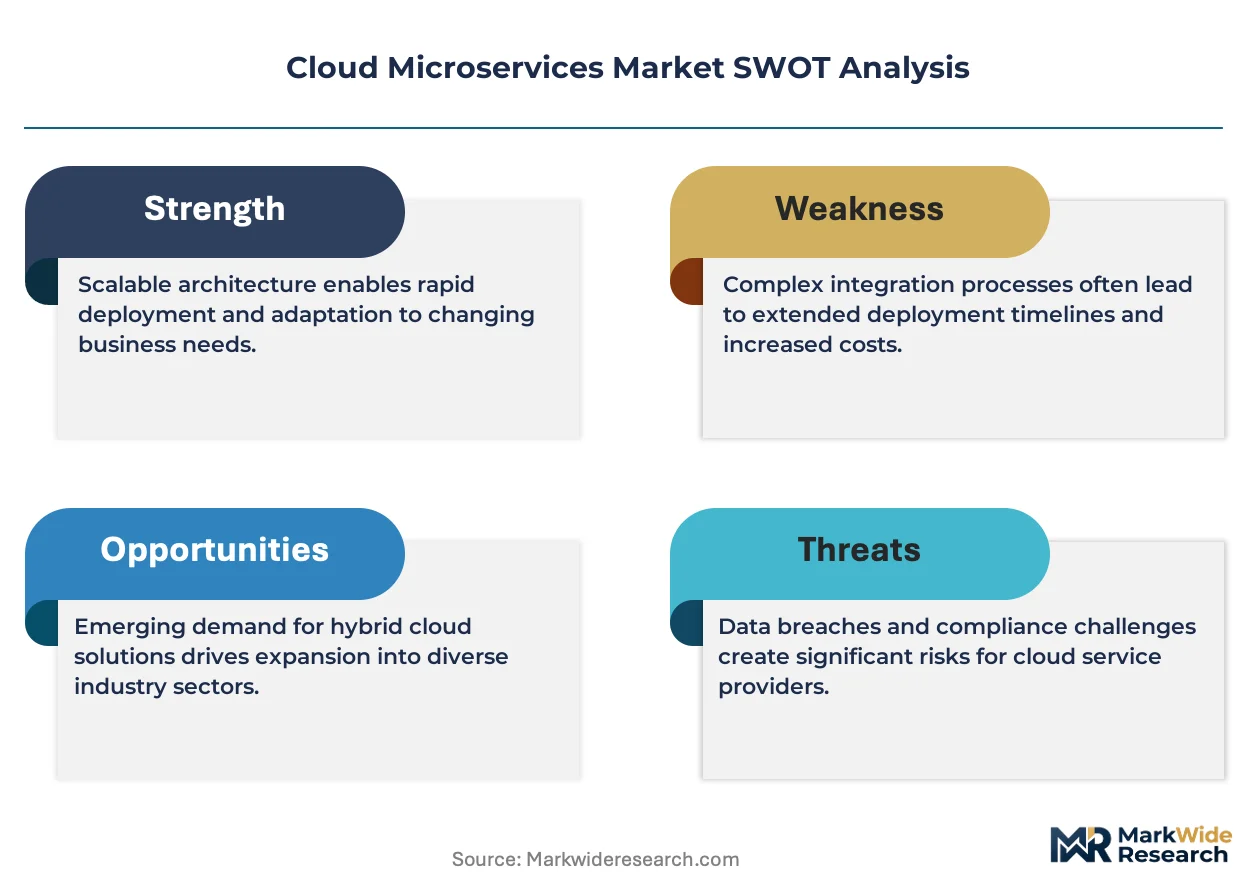
- Container Orchestration Platforms:Widespread adoption of platforms like Kubernetes streamlines the deployment, scaling, and management of containerized applications, significantly lowering the barrier to entry for enterprises transitioning from monolithic architectures to microservices. This accelerates development cycles and improves infrastructure utilization.
- E-commerce and Fintech Demand:The need for scalable, resilient, and independently updatable services in the E-commerce and financial technology sectors, particularly in high-growth software development centers in India, directly fuels microservices adoption to support rapid feature releases.
- Hybrid Cloud Flexibility:The increasing preference for hybrid cloud deployments allows organizations to leverage public cloud services for stateless applications while keeping sensitive data on-premises, offering a balance between agility and data control that microservices architectures facilitate.
Market Restraints
- Distributed System Complexity:The inherent difficulty in managing service discovery, inter-service communication, and observability across a distributed architecture increases operational overhead. This requires specialized tooling and expertise, acting as a significant barrier for organizations without mature DevOps practices.
- Expanded Security Surface:Each microservice is a potential entry point for an attack, creating a much larger and more complex security perimeter to defend compared to a single monolithic application. Enforcing consistent security policies across services is a major challenge.
- Specialized Talent Costs:A pronounced scarcity of engineers with deep expertise in distributed systems, DevOps, and site reliability engineering (SRE) drives up labor costs. This high cost of talent acts as a structural barrier, particularly for small and medium enterprises.
Strategic Opportunities
- Function as a Service (FaaS):Serverless computing, or FaaS, presents a significant opportunity by abstracting away all infrastructure management. This allows developers to focus solely on writing business logic, drastically reducing operational overhead and accelerating time-to-market for new features and applications.
- Edge Computing Integration:Deploying microservices on edge computing nodes offers a new frontier for applications requiring low-latency processing, such as industrial IoT and autonomous vehicle systems. This creates opportunities for specialized platforms optimized for resource-constrained edge environments.
- Compliance-as-a-Service Platforms:There is a growing need for microservices platforms pre-configured to meet specific regulatory requirements, such as HIPAA for healthcare data in the US or GDPR in Europe, simplifying the compliance burden for organizations in regulated industries.
Industry Challenges
- Talent Pipeline Gaps:A persistent shortage of developers and operations professionals skilled in cloud-native technologies, including containerization and service mesh management, constrains the ability of enterprises to effectively build and maintain complex microservice-based applications at scale.
- Legacy System Integration:Established enterprises face significant friction when integrating new microservices with deeply entrenched monolithic legacy systems. This process often introduces technical debt, architectural complexity, and potential points of failure, slowing down modernization initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Microservices Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $12.3 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, Community Cloud Service Offering: Platform as a Service, Infrastructure as a Service, Software as a Service, Function as a Service, Container as a Service Application Area: Banking, Telecommunication, E-commerce, Manufacturing, Media & Entertainment End User Type: Startups, Small & Medium Enterprises, Large Enterprises, Government Agencies, Non-Governmental Organizations |
| Companies Covered | IBM Corporation, Cisco Systems, Amazon Web Services, Nutanix, Red Hat, Microsoft Corporation, Oracle Corporation, CoreWeave, Alphabet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Microservices Market Strategic Shifts & Innovations
Architectural patterns are evolving toward greater abstraction to manage complexity, while non-technical forces like data privacy regulations are directly influencing design choices. The focus is shifting from simply breaking up monoliths to building manageable, secure, and compliant distributed systems.
Service Mesh technology offers a dedicated infrastructure layer for managing service-to-service communication, security, and observability. Large enterprises with complex, polyglot microservice environments are the primary adopters. This technology is fragmenting application networking logic away from service code into a separate, centrally managed platform, simplifying developer workflows.
Europe's EU AI Act is introducing risk-based requirements for artificial intelligence systems, many of which are built on microservices. This regulation forces organizations to implement granular governance, logging, and traceability for each service involved in an AI model's decision-making process. The MLOps (Machine Learning Operations) segment is most affected, now embedding compliance checks directly into deployment pipelines.
A notable behavioral shift is occurring as enterprises move from adopting a single vendor's entire PaaS to a "composable" approach. Buyers are increasingly selecting best-of-breed, specialized services from multiple providers and integrating them. This trend toward composable architectures is most visible within the financial services and retail sectors in North America and Europe, which prioritize flexibility over vendor lock-in.
Cloud Microservices Market Segmentation
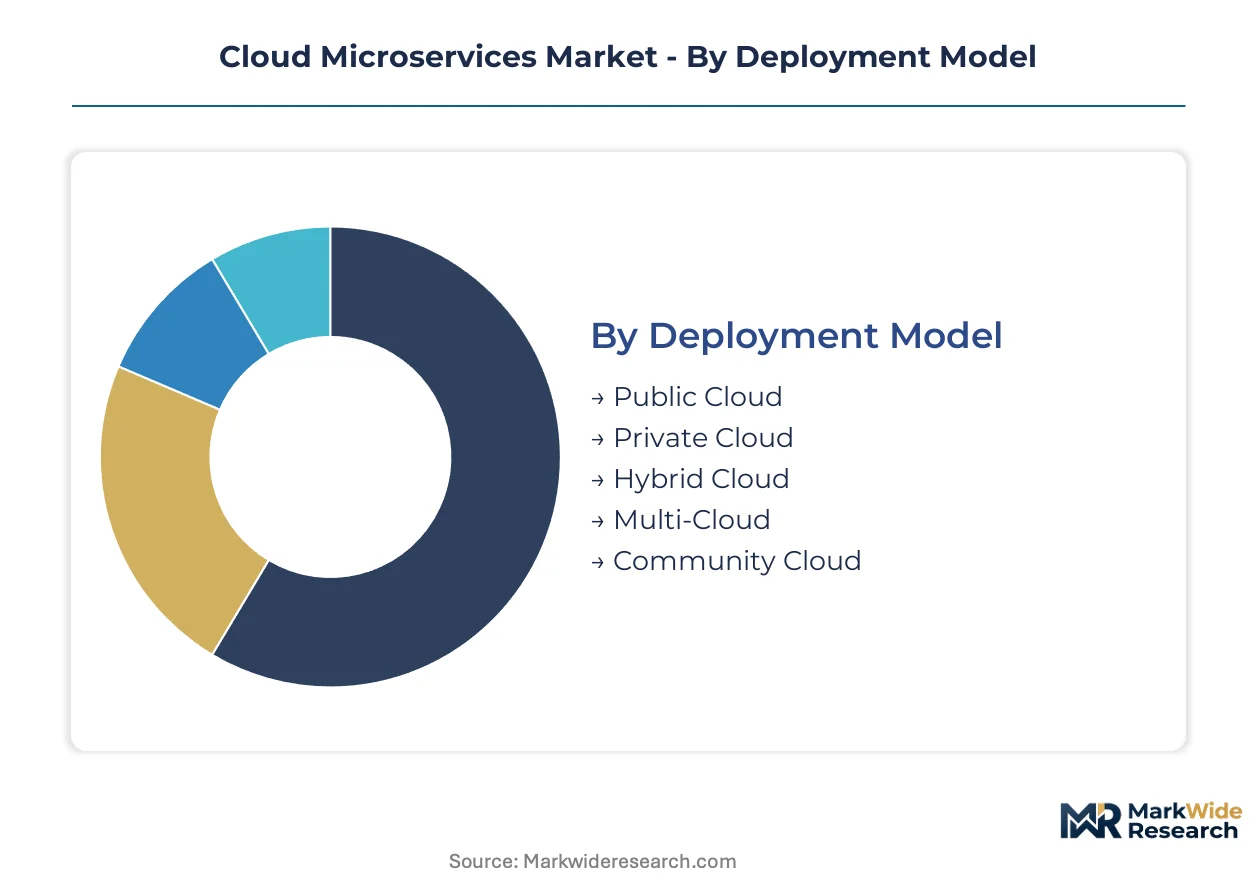
The Cloud Microservices Market is segmented to provide a granular view of architectural preferences, service consumption patterns, and end-user adoption across various industry landscapes. Understanding these distinct segments is crucial for providers to tailor offerings and for enterprises to align their digital transformation strategies effectively.
Deployment Model:
Regulatory environments significantly influence an enterprise's choice of cloud deployment model for microservices, balancing data residency requirements with operational flexibility.
- Hybrid Cloud:Combines on-premises infrastructure with public cloud services, allowing data control and agility. Enterprises leverage this model for sensitive data while utilizing public resources for stateless applications.
- Public Cloud:Services delivered over the internet by third-party providers, offering massive scalability and reduced capital expenditure. Organizations adopt public cloud microservices for rapid deployment and elastic resource provisioning.
- Private Cloud:Dedicated cloud infrastructure for a single organization, providing enhanced security and control.
- Multi-Cloud:Utilizing multiple public cloud providers to avoid vendor lock-in and optimize services.
- Community Cloud:Shared cloud infrastructure among organizations with common concerns, such as specific security requirements.
Established volume favors Public Cloud; emerging adoption favors Hybrid Cloud.
Service Offering:
The level of abstraction provided by various service offerings directly impacts developer productivity and the operational burden associated with microservices deployments.
- Function as a Service (FaaS):Serverless computing model where developers deploy individual functions without managing the underlying infrastructure. This model drastically reduces operational overhead, accelerating time-to-market for new features.
- Container as a Service (CaaS):Provides a platform for managing and deploying containerized applications, abstracting away underlying infrastructure. Widespread adoption of Kubernetes drives CaaS use, simplifying microservices orchestration.
- Platform as a Service (PaaS):Offers a complete development and deployment environment, enabling developers to focus on application logic.
- Infrastructure as a Service (IaaS):Provides virtualized computing resources over the internet, giving users control over operating systems and applications.
- Software as a Service (SaaS):Delivers ready-to-use applications over the internet, requiring no infrastructure management from the end-user.
Function as a Service represents the fastest-growing model, while Platform as a Service and Container as a Service remain central to many development workflows.
Application Area:
The inherent need for scalability and rapid feature deployment across diverse industry verticals shapes the adoption of cloud microservices architectures.
- E-commerce:Requires highly scalable and resilient applications to handle fluctuating traffic and frequent updates for product catalogs and payment systems. This sector drives microservices adoption to support rapid feature releases, especially in India.
- Banking:Demands robust, secure, and independently deployable services for managing financial transactions, customer accounts, and regulatory compliance. Microservices enable modular development of core banking systems and new fintech offerings.
- Telecommunication:Utilizes microservices for network function virtualization and agile service delivery to subscribers.
- Manufacturing:Leverages microservices for IoT data processing, supply chain optimization, and smart factory automation.
- Media & Entertainment:Adopts microservices for content streaming, digital rights management, and personalized user experiences.
E-commerce and Banking sectors generate substantial demand for microservices, reflecting their need for agile and scalable digital platforms.
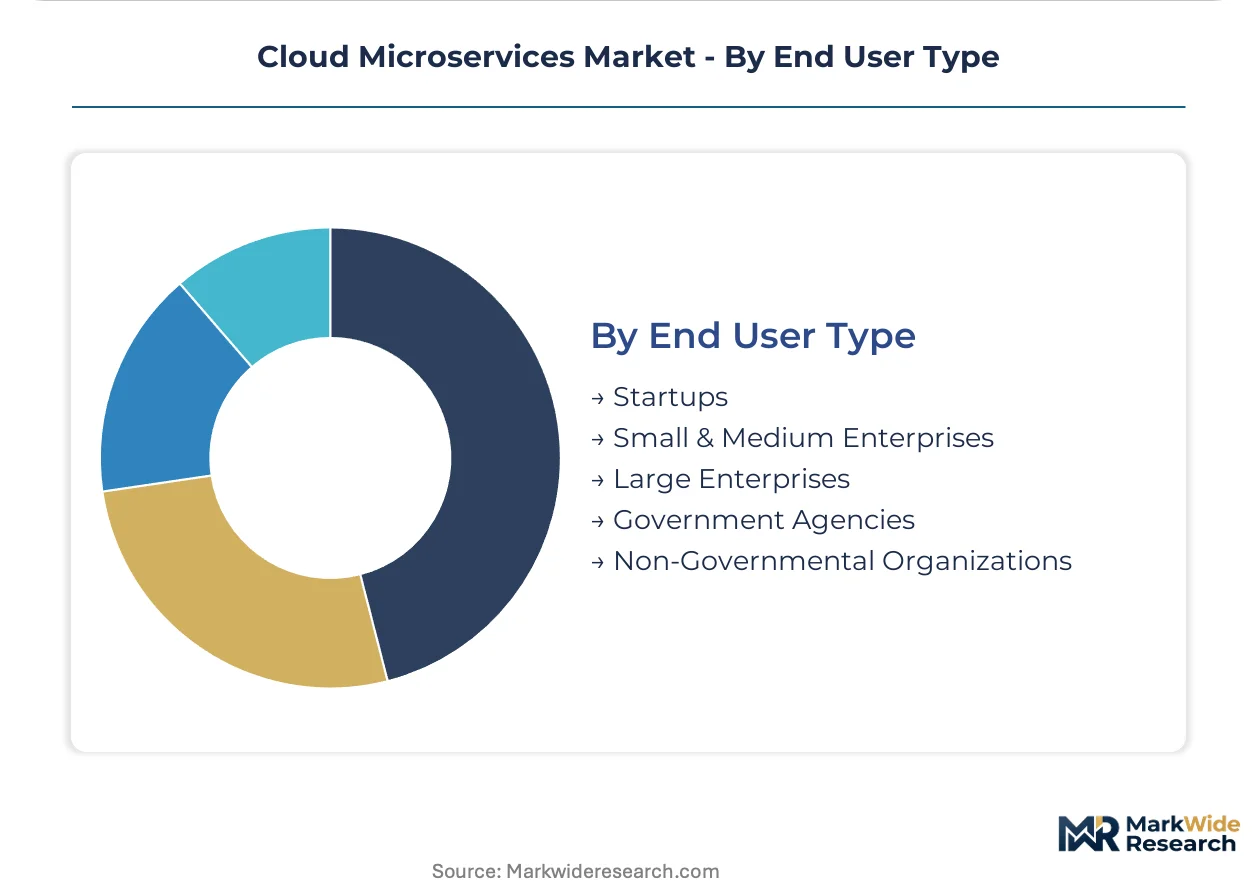
End User Type:
The organizational scale and available technical expertise within different end-user types determine the complexity and scope of their cloud microservices implementations.
- Large Enterprises:Possess the resources and complex application portfolios that benefit most from microservices' modularity and scalability. These organizations often face challenges integrating microservices with legacy systems.
- Small & Medium Enterprises:Increasingly adopt microservices to build scalable applications without the overhead of monolithic architectures. Demand from SMEs shifts market focus away from solely serving large corporations.
- Startups:Utilize microservices for rapid prototyping and scaling new applications with minimal initial infrastructure investment.
- Government Agencies:Deploy microservices for modernizing public services and enhancing data security and interoperability.
- Non-Governmental Organizations:Adopt microservices to build flexible and cost-effective platforms for their outreach and operational activities.
Large Enterprises represent a foundational demand base, while Small & Medium Enterprises demonstrate a notable expansion in microservices adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration in cloud microservices aligns with established technology hubs and rapidly digitizing economies. These regions foster significant innovation and adoption, driven by robust digital infrastructure and evolving regulatory landscapes. Enterprises are actively integrating microservices to enhance scalability and agility.
United States
Large enterprises in the United States drive demand for microservices, particularly within financial services and e-commerce. HIPAA regulations influence architectural choices for healthcare data, emphasizing secure, distributed systems. Silicon Valley and Seattle serve as major innovation centers, attracting investment in cloud-native technologies.
India
India's burgeoning e-commerce and fintech sectors fuel microservices adoption for scalable applications. The Digital India initiative encourages modernization, influencing technology choices. Major software development centers in Bengaluru and Hyderabad are at the forefront of microservices implementation.
Germany
Demand for microservices in Germany stems from its advanced manufacturing and automotive industries, supporting Industry 4.0. GDPR mandates strict data privacy, impacting microservice design and deployment strategies. Munich and Berlin are key hubs, fostering innovation in industrial IoT and cloud-native solutions.
China
China's vast digital economy and rapid e-commerce growth necessitate highly scalable microservices architectures. MIIT oversight on cloud services and GB standards for data security shape deployment and compliance requirements. Tech giants in Shenzhen and Beijing are leading the development of cloud infrastructure and microservices platforms.
United Kingdom
The United Kingdom's strong financial services sector and growing digital government initiatives propel microservices adoption. GDPR (retained EU law) directly impacts data handling, requiring precise architectural considerations for compliance. London and Manchester are prominent centers for fintech innovation and digital transformation projects.
Cloud Microservices Market Key Industry Players
Concentration sits with major cloud service providers and specialized open-source platform vendors within the cloud microservices market. The market exhibits a tiered structure, with hyperscale cloud providers at the top, followed by enterprise software specialists and open-source platform developers. Dominant competitive moves include portfolio diversification into specialized microservices offerings and strategic partnerships to expand ecosystem reach, particularly for compliance-as-a-service platforms.
Hyperscale cloud providers like Amazon Web Services exemplify the extensive service portfolio approach, leveraging first-mover advantage across various microservices offerings, including FaaS and CaaS. Microsoft Corporation occupies a strong position through its Azure platform, providing integrated development tools and enterprise support for hybrid cloud deployments. Red Hat represents the open-source specialization, offering foundational technologies for hybrid cloud deployments and container orchestration, appealing to enterprises seeking vendor flexibility.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems |
| Amazon Web Services |
| Nutanix |
| Red Hat |
| Microsoft Corporation |
| Oracle Corporation |
| CoreWeave |
| Alphabet Inc. |
| Others |
Cost & Logistics Intelligence
Stringent data privacy regulations, including Europe's GDPR and the US HIPAA, directly influence cloud microservices supply qualification and drive price differentiation. This regulatory framework necessitates specialized compliance features, impacting how service providers structure their offerings.
Pricing Analysis
Europe's GDPR dictates the pricing tier structure for cloud microservices, especially concerning data residency and processing. The dominant pricing model is subscription-based, often augmented by usage-based fees for compute, storage, and network egress. Price differentiation stems from specialized compliance certifications and the depth of managed services provided. Pricing softness reflects intense competition among hyperscale cloud providers. Small and Medium Enterprises exhibit higher price sensitivity compared to large enterprises, which prioritize comprehensive compliance and enterprise-grade support.
Supply Chain Analysis
The United States, China, and India collectively anchor the global supply of cloud microservices platforms and development talent. Supply relies on robust data center infrastructure, including high-performance servers, networking hardware, and specialized cooling systems. A structural risk involves reliance on a few hyperscale providers for foundational infrastructure, creating potential single-source vulnerabilities for specific cloud-native services. Distribution runs primarily through direct sales channels from major cloud providers and an ecosystem of managed service partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud microservices market faces a significant talent gap, particularly in specialized DevOps and site reliability engineering skills. This scarcity of expertise constrains enterprise adoption and effective management of complex distributed systems.
For Market Incumbents: Shield core platform revenue by deepening vertical integration into specialized observability and security tooling. Consolidate market share through strategic acquisitions of niche FaaS or CaaS providers to counter emerging open-source alternatives. Invest heavily in R&D for AI-driven compliance automation to reduce the operational overhead of distributed security. Enhance enterprise support to differentiate against lower-cost, less integrated offerings. For New Entrants and Emerging Players: HIPAA compliance certification offers a fast-track entry point into the US healthcare microservices segment. Target underserved small and medium enterprises with specialized Compliance-as-a-Service platforms, simplifying regulatory adherence. Focus on edge computing integration for industrial IoT applications requiring low-latency processing. A compelling go-to-market angle involves offering pre-configured, industry-specific microservices stacks that drastically reduce time-to-compliance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across specialized AI/MLOps platforms within the cloud microservices ecosystem. Long-term viability (5-10 year window) favors platforms that effectively abstract operational complexity and automate compliance. Identify acquisition targets with proprietary service mesh technology or advanced compliance-as-a-service IP. The signal to watch is the sustained growth in serverless function adoption within highly regulated industries.| Strategic Initiative | Industry Significance |
|---|---|
| Launch Compliance-as-a-Service Platform | This initiative directly addresses regulatory burdens, simplifying adherence for enterprises in regulated sectors. |
| Integrate Advanced Service Mesh Technology | This move enhances inter-service communication, security, and observability for complex microservices deployments. |
| Form Strategic Partnerships with Edge Computing Providers | These collaborations enable low-latency processing for industrial IoT and autonomous systems at the network edge. |
| Acquire Niche FaaS or CaaS Specialist Firms | This expands core cloud offerings, capturing expertise and market share in rapidly growing serverless and container segments. |
| Expand into Emerging Software Development Centers | This move taps into new talent pools and addresses demand from high-growth e-commerce and fintech markets in India. |
Research Approach
Cross-validation between industry reports and financial filings anchors the qualitative findings of this study. Primary interviews with CTOs, DevOps engineers, IT procurement officers, and regulatory compliance specialists provided granular market insights. Secondary validation utilized SEC filings, industry association reports, and government technology initiatives. A robust bottom-up and top-down triangulation approach reconciled discrepancies and confirmed market sizing.
Sensitivity analysis was applied to key variables, establishing a robust analytical framework across the projection horizon. The modeling incorporated segmentation dimensions including deployment model, service offering, application area, end-user type, and regional regulatory compliance. Compound Annual Growth Rates were derived through regression analysis of historical market data and projected technology adoption curves. Key industry-specific forecast inputs included Kubernetes adoption rates and FaaS consumption trends.
Decision-makers should treat outputs as directional under assumptions of a stable regulatory environment and consistent cloud infrastructure investment; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions. Geopolitical shifts or unforeseen data sovereignty laws represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Italy Cloud Computing Market