
 Bare Metal Cloud Service Market | 2026-2036
Bare Metal Cloud Service Market Size, Share, and Industry Trends Forecast 2026-2036
Bare Metal Cloud Service Market Analysis
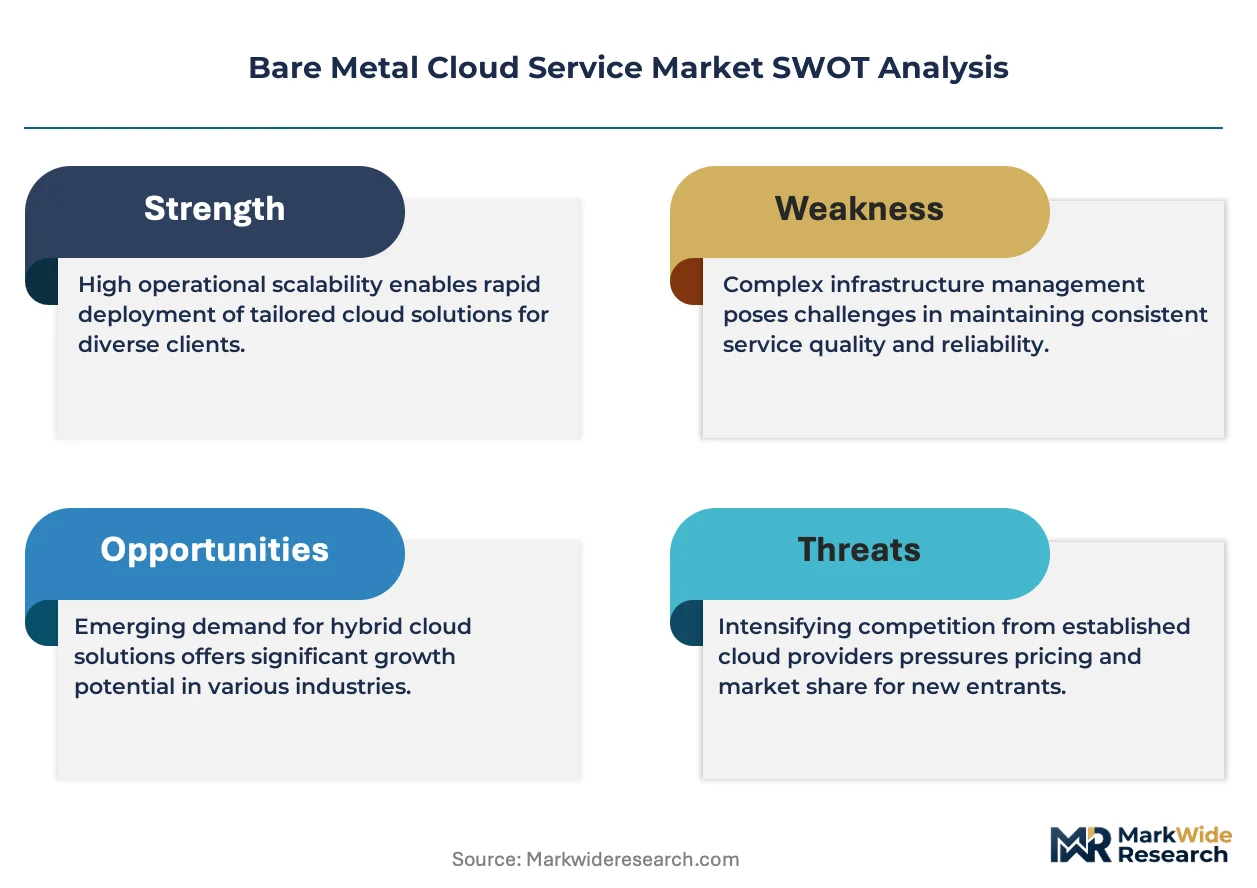
Platform engineering talent scarcity is bifurcating the competitive landscape into hyperscaler-dominated enterprise tiers and specialist-driven mid-market niches. IBM Cloud leverages its hybrid cloud heritage to sustain mainframe-to-edge integration pipelines. Oracle Cloud Infrastructure anchors high-performance computing workloads for financial risk modeling. Vultr competes aggressively on price-performance for developer-centric deployments.
Bare metal cloud service provisions dedicated physical servers without virtualization overhead, delivering direct hardware access with sub-millisecond latency thresholds for compute-intensive workloads. Its primary purpose serves applications requiring deterministic performance: high-frequency trading, genomic sequencing, and real-time rendering pipelines. Hybrid cloud deployment models capture the widest margin pools as enterprises straddle on-premise legacy systems with elastic burst capacity. Gaming verticals represent the fastest-expanding segment as multiplayer infrastructure demands dedicated GPU clusters. Managed services within the service type dimension show deepening attach rates as customers outsource platform maintenance.
FCC guidelines on data sovereignty intersect with EU GDPR cross-border transfer rules to shape multi-tenant restrictions and regional data residency requirements. ISO 27001 and SOC 2 Type II certifications function as baseline market-access credentials for enterprise procurement committees. NIST cybersecurity frameworks increasingly influence contract terms for US federal-adjacent workloads. Stakeholders must weigh capital intensity against utilization economics when committing to owned-fleet expansion versus wholesale colocation partnerships.
Market Dynamics
Platform engineering talent scarcity is bifurcating the bare metal cloud competitive landscape into hyperscaler-dominated enterprise tiers and specialist-driven mid-market niches, forcing infrastructure decisions through workforce availability rather than pure technical specifications.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises are migrating AI training workloads to single-tenant bare metal environments to satisfy data sovereignty and auditability requirements under the EU AI Act's high-risk system classifications.
- High-frequency trading infrastructure:Financial services firms in Frankfurt, London, and Singapore are expanding dedicated server deployments to achieve sub-microsecond latency for algorithmic execution platforms.
- Genomic sequencing compute demands:Pharmaceutical and biotech research pipelines require direct GPU access without hypervisor overhead for population-scale genomic analysis, pulling capacity toward specialized bare metal providers.
Market Restraints
- Silicon supply concentration:GPU and high-core-count CPU availability remains constrained by TSMC and Samsung foundry allocation priorities, creating 12-18 month lead times for fleet expansion.
- Power density limitations:Data center physical infrastructure in Amsterdam, Frankfurt, and Dublin faces stranded power constraints that cap per-rack deployment density for high-wattage AI training servers.
- Colocation wholesale dependency:Bare metal specialists without owned real estate remain exposed to Equinix, Digital Realty, and STACK Infrastructure pricing power in tier-one markets.
Strategic Opportunities
- India enterprise digitalization:RBI data localization requirements and SEBI audit trail mandates are creating compliant bare metal demand among fintech and insurance carriers in Mumbai and Bangalore.
- Edge rendering for immersive gaming:Unreal Engine 5 nanite streaming and cloud gaming latency requirements are converging to create distributed GPU cluster demand closer to metropolitan player bases.
- ISO 27001 certification arbitrage:Mid-market providers achieving SOC 2 Type II and ISO 27001 certifications can displace uncertified competitors in enterprise procurement shortlists without direct price competition.
Industry Challenges
- Firmware supply chain integrity:Baseboard management controller vulnerabilities and opaque vendor patching cycles expose bare metal deployments to persistent compromise risks that virtualization layers historically mitigated.
- Hybrid orchestration complexity:Platform engineering teams struggle to unify Kubernetes scheduling across on-premise VMware estates, hyperscaler virtualized instances, and bare metal nodes with divergent network fabrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bare Metal Cloud Service Market |
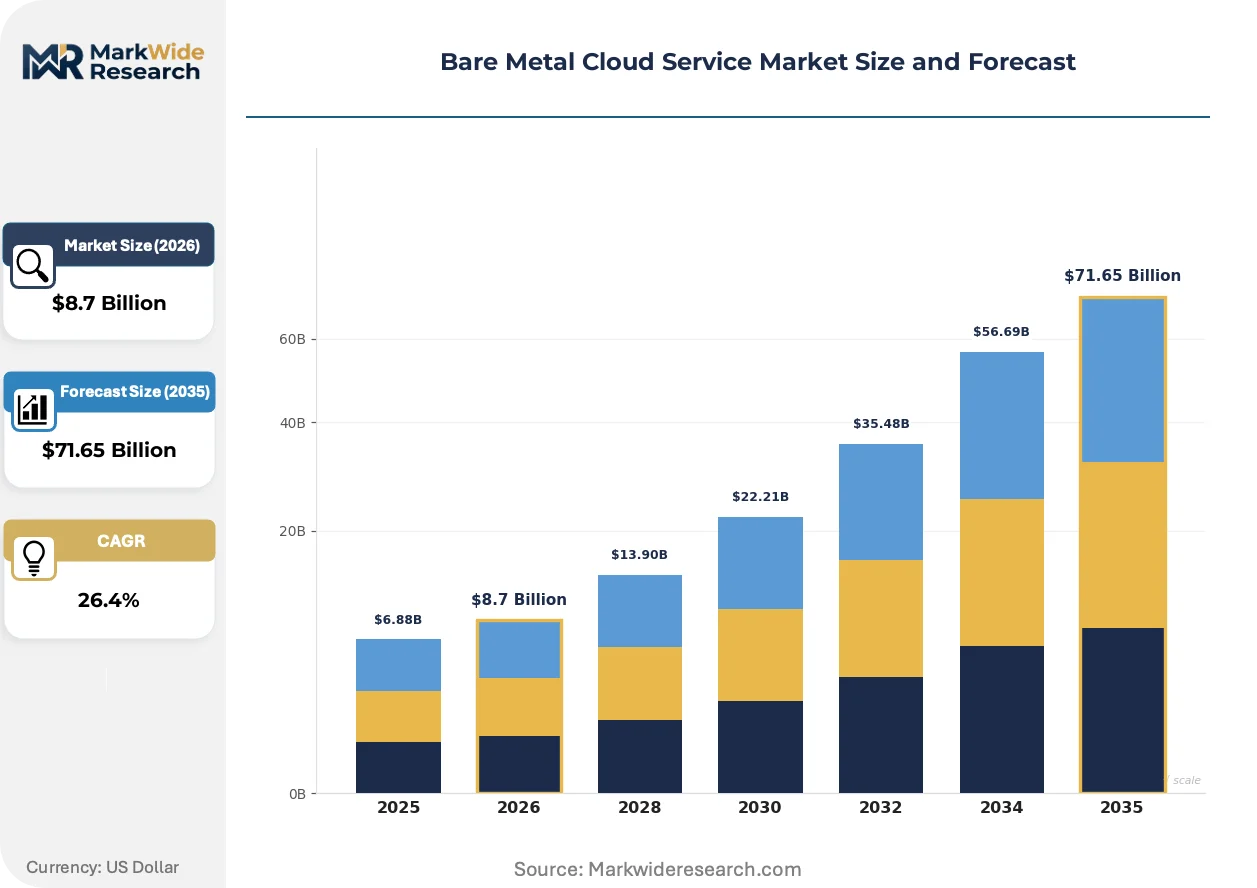
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, Managed Services, Backup Solutions, Disaster Recovery Industry Vertical: Healthcare, Finance, Telecommunications, Gaming End User: Startups, Enterprises, SMEs, Educational Institutions |
| Companies Covered | Atlantic.Net, Google Cloud, IBM Cloud, DigitalOcean, Vultr, OVHcloud, Liquid Web, Oracle Cloud Infrastructure, PhoenixNAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bare Metal Cloud Service Market Emerging Trajectories
Composable infrastructure architectures are fragmenting traditional server form factors, enabling granular resource disaggregation that challenges conventional bare metal provisioning models.
SmartNICs and DPUs from NVIDIA, AMD, and Marvell are decomposing network, storage, and security functions from host CPUs into dedicated silicon. Financial services firms in London and Singapore are deploying these at scale for latency-sensitive trading stacks. This silicon offload is decomposing the historical premium attached to high-core-count processors in bare metal pricing models.
The EU AI Act's risk classification system is mandating single-tenant compute environments for high-risk AI training workloads. European enterprises must maintain audit trails for training data provenance and model versioning. German automotive manufacturers and French healthcare AI developers are restructuring cloud contracts to exclude multi-tenant virtualized infrastructure from compliance scope.
Consumption-based billing models are displacing traditional monthly server rental contracts in developer-centric segments. Vultr and comparable providers now meter GPU seconds and egress bandwidth with granularity matching hyperscaler serverless pricing. This billing compression is most visible among gaming studios and ML engineering teams in North American and Western European markets where capital efficiency pressures dominate procurement criteria.
Bare Metal Cloud Service Market Segmentation
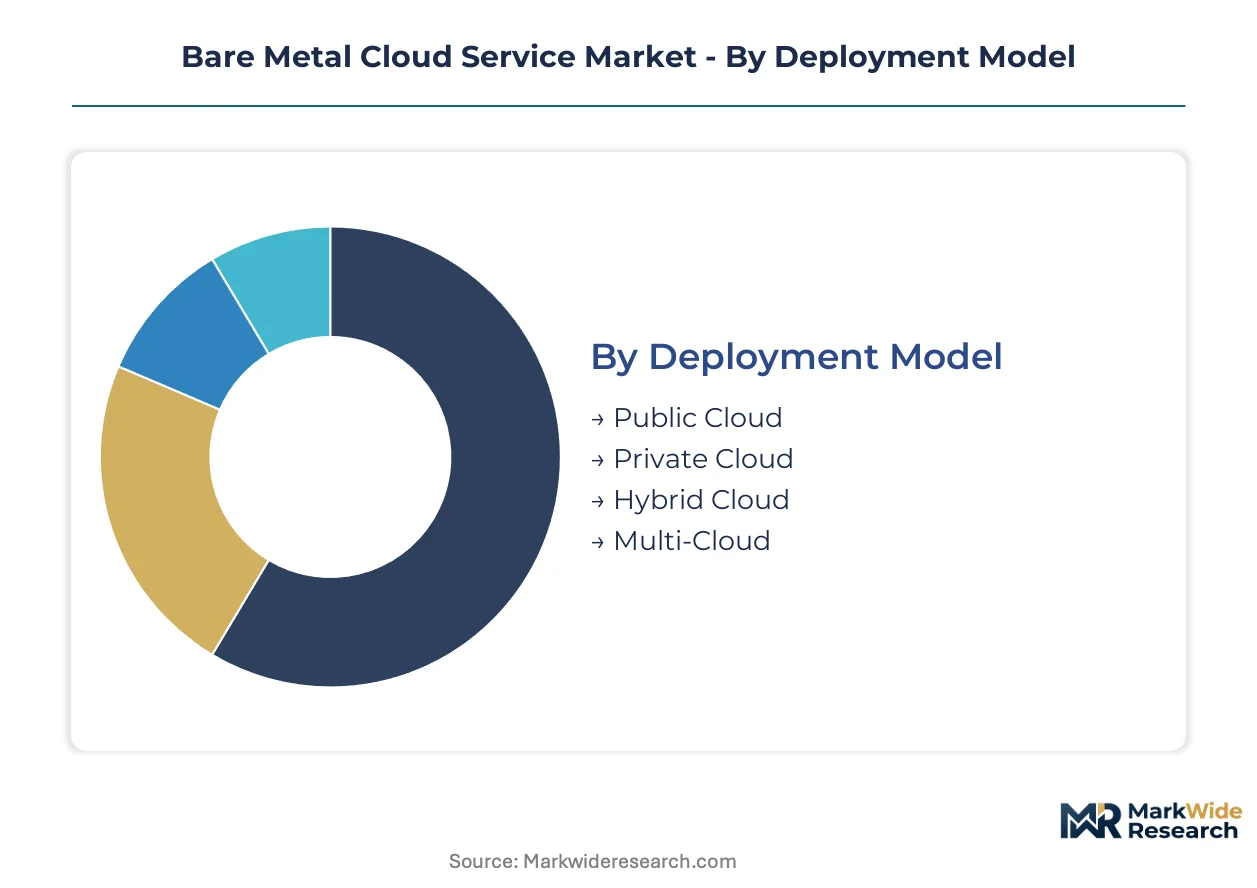
Bare metal cloud segmentation reveals divergent procurement patterns across workload sensitivity and compliance exposure. Deployment models and service types cluster around latency requirements, while vertical and user dimensions expose price-performance trade-offs that reshape provider positioning.
Deployment Model:
Public cloud deployments concentrate in North American developer ecosystems and Asian gaming hubs, while private and hybrid models dominate European regulated industries under data sovereignty constraints.
- Public Cloud:Shared physical infrastructure delivers sub-hour provisioning for burst workloads and development environments. Demand clusters in US West Coast technology corridors and Singapore financial districts where latency tolerance permits multi-tenant facilities.
- Hybrid Cloud:Combines on-premise owned hardware with elastic bare metal burst capacity through unified orchestration layers. German automotive manufacturers and Dutch pharmaceutical firms deploy this model to satisfy EU AI Act audit requirements while preserving legacy mainframe integration.
- Private Cloud:Dedicated single-tenant data halls with custom network segmentation. French healthcare AI developers and UK quantitative trading firms mandate this architecture for high-risk system classifications under national regulator interpretations of GDPR Article 32.
- Multi-Cloud:Workload distribution across geographically dispersed bare metal providers to eliminate single-point-of-failure. Japanese gaming publishers and Australian fintech startups adopt this pattern for disaster recovery without hyperscaler lock-in.
Hybrid cloud commands the established base. The steepest expansion runs through multi-cloud configurations.
Service Type:
Service packaging separates capital-heavy self-managed deployments from recurring-revenue managed offerings, with margin profiles inverting between developer-centric and enterprise procurement contexts.
- IaaS:Raw server provisioning with API-driven automation and no operational support layer. US technology startups and Indian SaaS scale-ups favor this model for cost control and custom kernel modifications.
- Managed Services:Provider assumes firmware patching, hardware replacement, and network monitoring responsibilities. German Mittelstand manufacturers and Italian insurance carriers outsource platform engineering to compensate for domestic talent scarcity.
- Backup Solutions:Immutable snapshot replication to secondary bare metal sites with defined recovery point objectives. Swiss private banks and Luxembourg fund administrators mandate this for FINMA and CSSF operational resilience guidelines.
- Disaster Recovery:Warm standby infrastructure with automated failover orchestration. UK retail banking groups deploy this across Dublin and Amsterdam facilities to satisfy PRA operational continuity requirements.
Managed services capture margin expansion. IaaS retains volume leadership.
Industry Vertical:
Vertical specialization determines certification requirements and latency thresholds, with financial services and gaming presenting opposing demand profiles around deterministic performance versus elastic scale.
- Finance:Algorithmic trading infrastructure and risk modeling clusters demand microsecond-level network determinism. Frankfurt and London exchanges anchor continental deployment, with Singapore and Tokyo capturing Asia-Pacific latency arbitrage.
- Gaming:Multiplayer server hosting and cloud rendering pipelines require GPU-dense configurations with metropolitan edge placement. South Korean esports broadcasters and Nordic game studios drive capacity expansion in Stockholm and Helsinki data centers.
- Healthcare:Genomic sequencing and medical imaging AI training workloads need direct GPU access without hypervisor overhead. French hospital networks and German research consortia structure procurement around ISO 27001 and MDR compliance scope.
- Telecommunications:5G core network functions and edge computing nodes deploy on carrier-neutral bare metal for radio access network virtualization. Italian and Spanish mobile operators expand Madrid and Milan facilities for Open RAN infrastructure.
Finance commands premium pricing. Gaming shows the steepest capacity expansion trajectory.
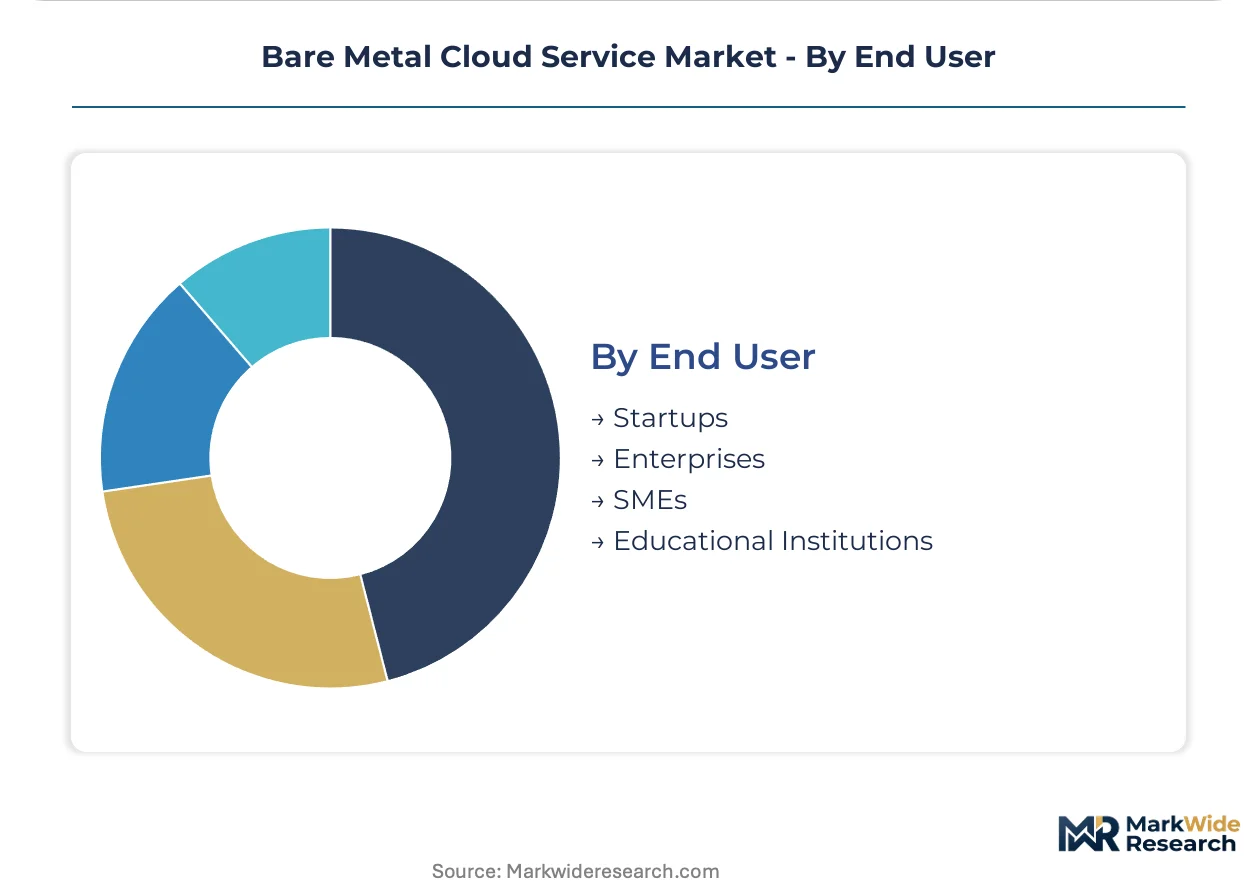
End User:
User scale segments procurement sophistication, with enterprise buyers demanding contract customization and startups prioritizing consumption-based billing granularity.
- Enterprises:Multi-year committed use agreements with custom service level objectives and dedicated account engineering. German automotive OEMs and US pharmaceutical majors negotiate these terms for supply chain continuity.
- Startups:Hourly or per-second metering with automated scaling and minimal procurement friction. Israeli cybersecurity ventures and Brazilian fintech scale-ups optimize burn rate through usage-based bare metal.
- SMEs:Standardized monthly rental contracts with bundled support tiers. Spanish logistics operators and Polish e-commerce platforms occupy this mid-market tier.
- Educational Institutions:Discounted research computing allocations with grant-funded project timelines. Dutch technical universities and Canadian AI research institutes access subsidized HPC clusters through national cyberinfrastructure programs.
Enterprises anchor revenue stability. Startups drive billing innovation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German automotive manufacturers prioritize single-tenant compliance infrastructure, while US gaming studios optimize for elastic GPU burst capacity. Asian financial hubs in Singapore and Tokyo anchor low-latency trading deployments with distinct regulatory frameworks.
United States
Financial services firms in Chicago and New York deploy bare metal for high-frequency trading infrastructure, demanding sub-microsecond network determinism. FCC data sovereignty guidelines intersect with state-level privacy statutes to shape multi-tenant restrictions. Northern Virginia's data center corridor concentrates hyperscaler and specialist capacity expansion for federal-adjacent workloads.
Germany
Automotive OEMs and healthcare AI developers migrate training workloads to compliant single-tenant environments under EU AI Act high-risk system classifications. KBA and national regulator interpretations of GDPR Article 32 mandate audit trails for model versioning. Frankfurt's data center cluster anchors continental cloud capacity with strict data residency enforcement.
United Kingdom
Quantitative trading firms in London mandate dedicated single-tenant architectures for algorithmic execution platforms. PRA operational continuity requirements drive disaster recovery deployments across Dublin and Amsterdam facilities. The UK financial regulator's interpretation of operational resilience guidelines shapes procurement specifications for bare metal failover infrastructure.
Singapore
ASEAN financial institutions deploy bare metal for latency-sensitive trading stacks and cross-border payment infrastructure. Monetary Authority of Singapore guidelines on technology risk management influence single-tenant requirements for systemically important institutions. The city-state's data center cluster serves as regional hub for Asia-Pacific latency arbitrage.
India
Fintech scale-ups and insurance carriers in Mumbai and Bangalore expand bare metal adoption under RBI data localization requirements and SEBI audit trail mandates. The central bank's strict interpretation of payment data storage rules excludes multi-tenant virtualized infrastructure from compliance scope. Domestic cloud providers compete with global specialists on price-performance for developer-centric deployments.
Bare Metal Cloud Service Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in bare metal cloud infrastructure. Hyperscalers leverage global fiber networks and enterprise sales engines to capture committed-use agreements. Specialist providers compete on provisioning speed and consumption-based billing granularity. Strategic moves concentrate on geographic expansion into compliance-heavy European markets and GPU cluster densification for AI training workloads.
Within the integrated infrastructure tier, IBM Cloud and Oracle Cloud Infrastructure exemplify hybrid cloud heritage positioning, while Vultr occupies a specialist position among developer-centric providers. These three anchors represent divergent competitive vectors: mainframe-to-edge integration pipelines, high-performance computing for financial risk modeling, and aggressive price-performance metering for GPU seconds and egress bandwidth.
| Leading Market Players |
|---|
| Atlantic.Net |
| Google Cloud |
| IBM Cloud |
| DigitalOcean |
| Vultr |
| OVHcloud |
| Liquid Web |
| Oracle Cloud Infrastructure |
| PhoenixNAP |
| Others |
Supply Flow & Price Mechanics
Hyperscaler fleet scale economies compress unit economics for high-core-count GPU servers, concentrating pricing power among providers with owned data center real estate while specialist competitors absorb wholesale colocation markups from Equinix and Digital Realty in Frankfurt and Amsterdam. This concentration forces bare metal specialists toward consumption-based billing granularity to offset structural cost disadvantages against vertically integrated leaders.
Pricing Analysis
Contract structures bifurcate between multi-year committed use agreements for enterprise procurement and per-second metering for developer-centric segments. Three-tier pricing structure across premium certified, standard managed, and economy self-service levels separates ISO 27001-compliant deployments from uncertified alternatives. Cost compression in economy tiers is intensifying because Vultr and comparable providers meter GPU seconds with hyperscaler-matching granularity. Startups exhibit highest price sensitivity; German automotive OEMs demonstrate lowest sensitivity due to EU AI Act compliance mandates.
Supply Chain Analysis
Inventory strategy favors just-in-time provisioning for standard CPU configurations, while GPU cluster deployments require strategic stockpiling against TSMC and Samsung foundry allocation cycles. Supply concentrates in Taiwan for advanced GPU silicon, South Korea for high-bandwidth memory, and the United States for networking silicon from NVIDIA and Marvell. Single-source vulnerability runs through TSMC's N4 and N3 process nodes for AI training accelerators. Distribution runs through direct sales engines for enterprise commitments and self-service portals for developer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services attach rates are expanding faster than raw server provisioning as German Mittelstand manufacturers outsource platform engineering to compensate for domestic talent scarcity. This service-layer expansion creates recurring revenue pools that offset capital intensity in fleet ownership.
For Market Incumbents: Consolidate hybrid cloud orchestration capabilities to defend against hyperscaler encroachment on mainframe-to-edge integration pipelines. Deepen ISO 27001 and SOC 2 Type II certification coverage to exclude uncertified competitors from enterprise procurement shortlists. Prioritize owned data center expansion in Frankfurt and Amsterdam to reduce wholesale colocation dependency.
For New Entrants and Emerging Players: Lead with consumption-based billing granularity targeting gaming studios and ML engineering teams in North American markets where capital efficiency pressures dominate procurement criteria. Target Indian fintech scale-ups under RBI data localization requirements as the most penetrable geography. Structure go-to-market around automated API-driven provisioning with sub-hour deployment SLAs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bare metal specialists with GPU cluster densification capabilities and European compliance certifications. Long-term viability hinges on differentiation from hyperscaler virtualization layers through deterministic performance guarantees. Acquisition target archetype: regional providers with owned Frankfurt or Amsterdam facilities and existing ISO 27001 certification. Watch SmartNIC and DPU deployment penetration in financial services as inflection indicator for silicon offload adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| GPU Cluster Densification | Captures AI training workload migration under EU AI Act single-tenant mandates. |
| Compliance Certification Investment | ISO 27001 and SOC 2 Type II credentials unlock enterprise procurement shortlists. |
| Consumption-Based Billing Transition | Meters GPU seconds and egress bandwidth to match hyperscaler serverless pricing. |
| Edge Rendering Infrastructure | Deploys metropolitan GPU clusters for Unreal Engine 5 nanite streaming latency requirements. |
| Hybrid Orchestration Platform | Unifies Kubernetes scheduling across on-premise VMware estates and bare metal nodes. |
Methodological Framework
A standing panel of platform engineering directors, cloud procurement officers, data center facility managers, and bare metal provider sales executives provided ongoing calibration across primary interview cycles. Secondary validation drew from hyperscaler capex disclosures, data center leasing reports from Equinix and Digital Realty, EU regulatory filings on AI Act implementation, and cloud infrastructure trade publications. Bottom-up server deployment estimates and top-down market sizing triangulated through cross-referencing provider capacity announcements with colocation absorption metrics.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler infrastructure spending trends and enterprise IT budget surveys. Segmentation dimensions modeled encompass deployment model, service type packaging, industry vertical compliance requirements, and end-user scale archetypes across the projection horizon. CAGRs were derived from fitted growth curves anchored to observed adoption inflections in financial services and gaming verticals. Forecast inputs incorporated EU AI Act compliance timeline assumptions and GPU supply allocation priorities from TSMC and Samsung.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or alternative semiconductor foundry capacity expansion would require recalibration. Forecasts reflect assumptions regarding data sovereignty policy continuity and power density constraints in tier-one European markets. Revision becomes warranted when GPU supply allocation cycles or FCC data sovereignty interpretations cross material threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Cloud Enablement Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Cloud Integration Software Market