
 Clip Band Market | 2026-2036
Clip Band Market Size, Share, and Industry Trends Forecast 2026-2036
Clip Band Market Outlook
Aftermarket customization services is reshaping margin distribution in the clip band value chain. Conair LLC leverages its salon-channel relationships to sustain premium positioning in professional hair accessories. Silke London specializes in silk-wrapped designs that command higher unit economics through material differentiation. Goody Products Inc. anchors mass-market volume through dominant retail shelf presence across North American drugstore chains.
A clip band is a flexible or rigid fastening device engineered to secure, bundle, or adorn hair, materials, or objects through spring tension, elastic recovery, or magnetic attraction, typically manufactured via injection molding, metal stamping, or textile weaving with tensile strengths ranging from 2 to 50 newtons depending on application. Its primary commercial purpose spans personal grooming, industrial cable management, and medical device fixation. Elastic bands and magnetic clips capture divergent margin pools, with the former dominating high-volume fashion accessory channels and the latter expanding fastest in healthcare and fitness applications where quick-release functionality commands price premiums. Metal and silicone material grades are splitting along regulatory lines, as medical-grade silicone attracts specialized certification costs that polyester and standard nylon segments avoid.
The FDA regulates clip bands intended for medical or surgical use under device classification pathways, while the EU MDR and REACH frameworks govern biocompatibility and chemical substance restrictions for products entering European markets. California's Proposition 65 adds state-level disclosure requirements that affect labeling and material sourcing for brands distributing in the United States. Stakeholders must monitor evolving dermatological testing standards and regional chemical restriction lists to preserve market access and avoid reformulation costs.
Market Dynamics
EU MDR biocompatibility mandates are forcing medical-grade silicone certification upgrades across European supply chains, splitting material sourcing strategies between regulated healthcare channels and unregulated consumer segments.
Growth Catalysts
- EU Medical Device Regulation:MDR compliance requirements for skin-contact fasteners are expanding addressable demand for certified clip band suppliers serving German surgical instrument manufacturers.
- Quick-release magnetic mechanisms:Fitness and patient monitoring applications are pulling magnetic clip variants into premium price tiers through rapid-detachment functionality.
- Precision manufacturing clusters:Stuttgart and Munich industrial zones concentrate automotive and healthcare OEM procurement, creating localized demand density for certified fastening solutions.
Market Restraints
- Medical-grade silicone input costs:Specialized biocompatibility certification adds 15-25% material cost premiums that polyester and standard nylon competitors avoid.
- German supply concentration:Precision manufacturing capabilities cluster in southern Germany, creating geographic dependency for EU-sourced medical device fasteners.
- REACH chemical restrictions:ECHA substance restrictions on phthalates and heavy metals limit formulation flexibility for cost-optimized consumer-grade products.
Strategic Opportunities
- Aftermarket customization services:Salon-channel personalization is opening margin pools beyond standard manufacturing, with color-matching and engraving services capturing value-added revenue.
- Dual-use material platforms:Convergence of textile weaving and metal stamping processes enables hybrid clip architectures serving both fashion accessory and medical fixation markets.
- California Proposition 65 compliance:State-level disclosure mandates create competitive differentiation for brands investing in transparent supply chain documentation for US distribution.
Industry Challenges
- Dermatological testing timelines:ISO 10993 biocompatibility validation extends product development cycles by 8-14 months for medical-grade variants.
- Legacy injection molding retooling:Multi-cavity tool modifications for magnetic clip integration demand capital outlays that mid-scale manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clip Band Market |
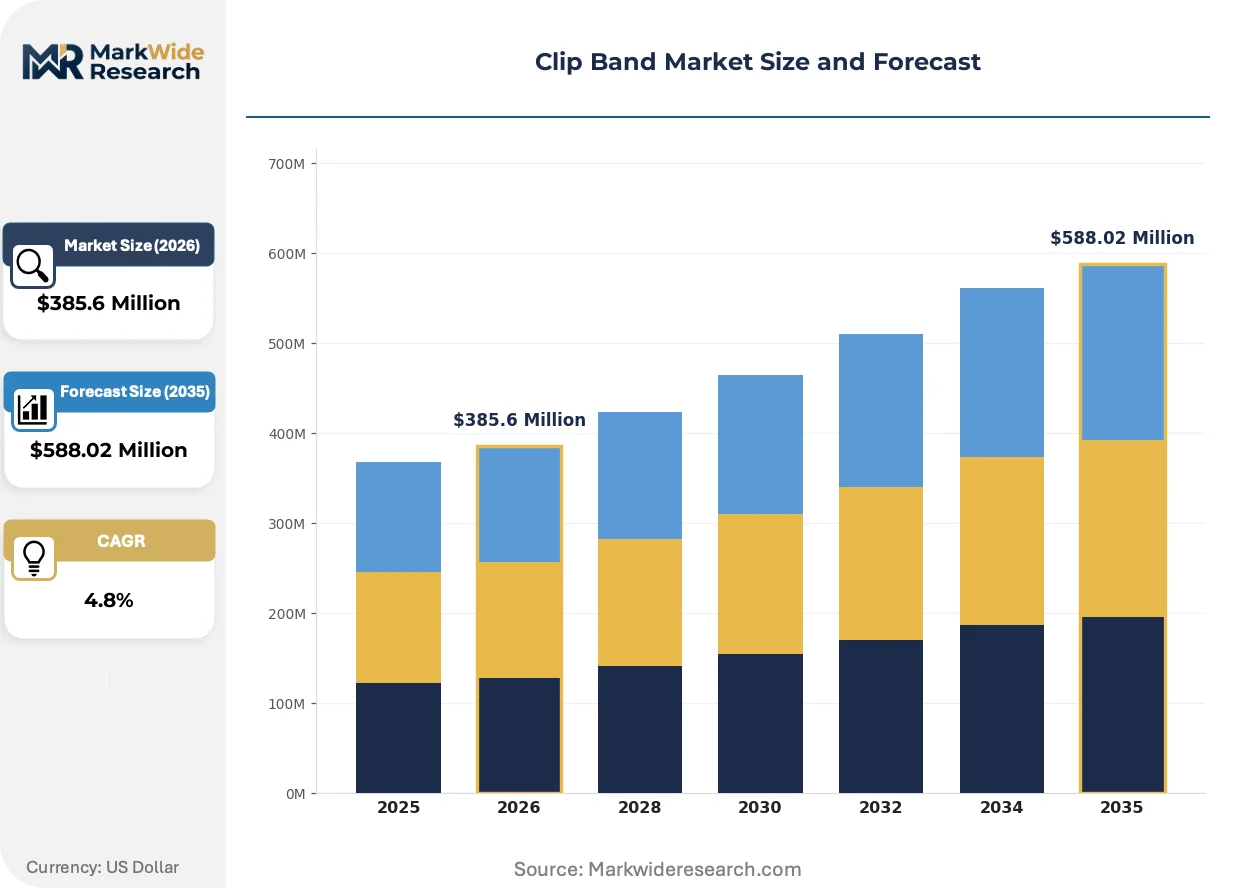
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Bands, Adjustable Clips, Magnetic Clips, Plastic Fasteners Material: Polyester, Silicone, Nylon, Metal Application: Fashion Accessories, Fitness Gear, Industrial Use, Office Supplies End User: Consumers, Retailers, Manufacturers, Educational Institutions |
| Companies Covered | Goody Products Inc., Claire's Stores Inc., Conair LLC, H&M Hennes & Mauritz Retail Private Limited, Forever 21, Annie International Inc., Silke London, HAIRDRAMACO INDIA PRIVATE LIMITED, Jennifer Behr LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clip Band Market Strategic Shifts
Material science advances and regulatory fragmentation are bifurcating clip band development pathways, with medical-grade certifications commanding premium positioning while fast-fashion cycles compress consumer segment innovation timelines.
Bioresorbable polymer formulations are rendering obsolete traditional metal staples in internal surgical fixation applications. German orthopedic device manufacturers are piloting magnesium-alloy clip bands for temporary wound closure. The structural consequence is compressing permanent implant market share while expanding temporary fixation addressable demand.
REACH Annex XVII restrictions on nickel release rates are tightening metal alloy specifications for skin-contact applications. ECHA enforcement actions against non-compliant jewelry fasteners are extending scrutiny to hair accessories with metal components. Medical device suppliers with pre-validated nickel-free formulations are capturing share from consumer brands facing reformulation costs.
Direct-to-salon distribution models are bypassing traditional retail intermediaries in professional hair accessory segments. Independent stylists in London and New York are consolidating purchasing through specialized B2B platforms. This channel shift is most visible in premium silk-wrapped variants where material provenance and customization justify relationship-based procurement over mass-market shelf presence.
Clip Band Market Segmentation
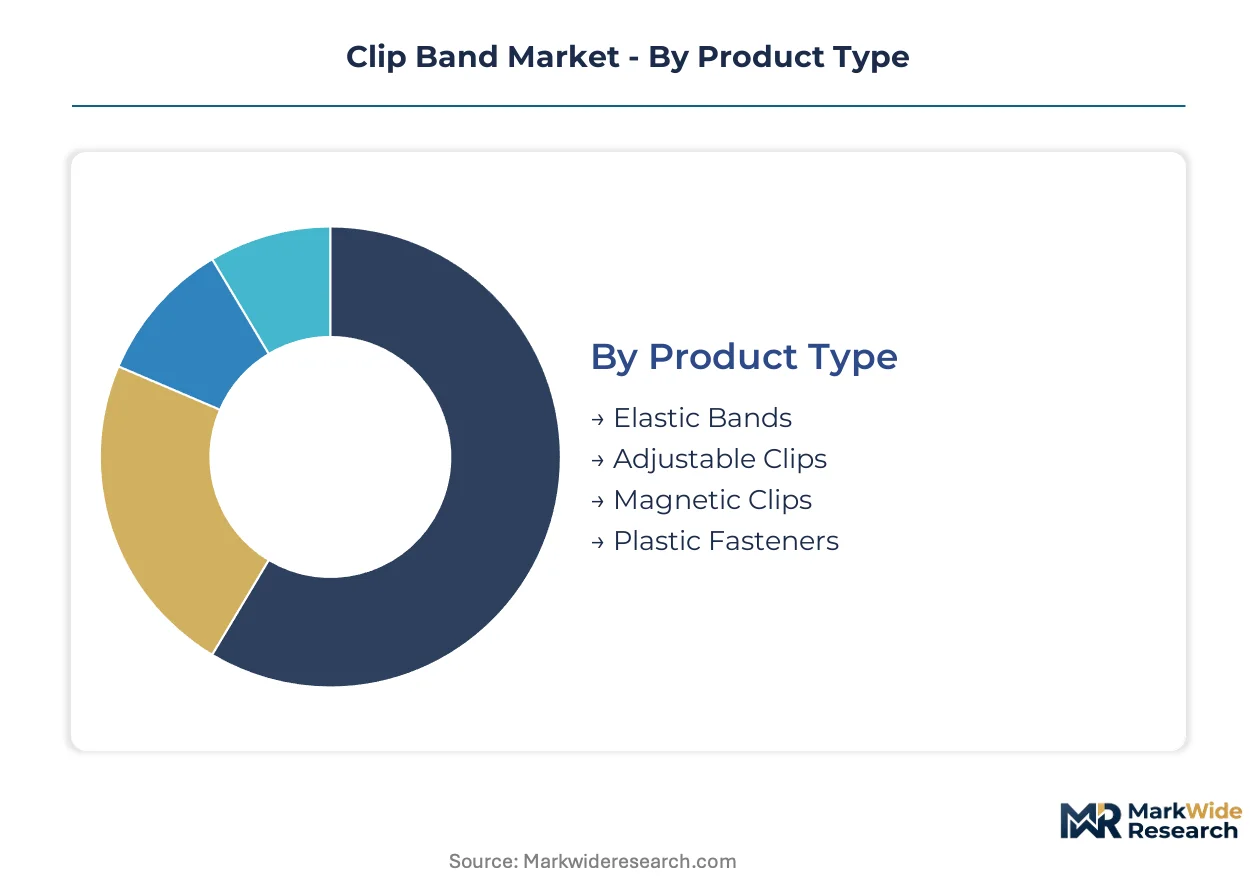
Clip band procurement patterns diverge sharply across use-case intensity, with medical-grade specifications commanding certification premiums while fashion accessories compete on color-matching speed and shelf turnover. Segmentation reveals how material choices and distribution channels partition margin pools between regulated healthcare supply chains and high-volume consumer retail.
Product Type:
The use-case spectrum spans gentle hair retention to surgical-grade fixation, with each product architecture optimizing for specific tension, release speed, and reusability requirements.
- Elastic Bands:Woven textile cores with synthetic rubber strands deliver 2-15 newtons of recovery force for repetitive stretch cycles. Demand concentrates in North American drugstore chains where Goody Products anchors mass-market volume through dominant retail shelf presence. Unit economics compress under fast-fashion inventory cycles.
- Magnetic Clips:Neodymium magnet arrays embedded in polymer housings enable single-hand release for patient monitoring and fitness tracking applications. German surgical instrument manufacturers in Stuttgart precision clusters are pulling these variants into premium price tiers through rapid-detachment functionality. Quick-release mechanisms justify 40-60% price premiums over spring-tension alternatives.
- Adjustable Clips:Ratchet or sliding mechanisms accommodate variable bundle diameters in cable management and salon applications. Silke London deploys these architectures for silk-wrapped premium positioning.
- Plastic Fasteners:Single-mold polypropylene or ABS constructions serve disposable medical and industrial bundling where cost minimization dominates specification. REACH phthalate restrictions constrain formulation flexibility for EU-bound shipments.
The dominant share belongs to Elastic Bands, while Magnetic Clips is closing the gap fastest.
Material:
Cost tiers separate certified biocompatible grades from commodity thermoplastics, with regulatory compliance costs fragmenting supplier bases along certification depth.
- Silicone:Medical-grade platinum-cured formulations meet ISO 10993 biocompatibility for skin-contact surgical applications. FDA device classification pathways and EU MDR compliance extend development cycles by 8-14 months, concentrating procurement among German orthopedic device manufacturers with validated supply chains. Specialized certification adds 15-25% material cost premiums.
- Polyester:Woven or braided polyethylene terephthalate fibers dominate fashion accessory channels through dye-affinity and tensile consistency. Conair LLC leverages salon-channel relationships to sustain premium positioning through color-matching services.
- Nylon:Polyamide 6,6 variants balance abrasion resistance and moisture absorption for fitness gear and industrial cable bundling. Standard grades avoid REACH nickel-release scrutiny affecting metal alternatives.
- Metal:Stainless steel or aluminum stampings serve high-tension industrial and medical fixation where magnetic interference prohibits polymer solutions. ECHA enforcement actions against non-compliant jewelry fasteners extend scrutiny to hair accessories with nickel-bearing alloys.
Silicone commands the highest unit margins, though Polyester ships the greatest aggregate volume.
Application:
Customer type determines specification rigor, with institutional procurement demanding traceability that consumer channels sacrifice for speed-to-shelf.
- Fashion Accessories:Seasonal color cycles and influencer-driven demand patterns compress design-to-retail timelines. Direct-to-salon distribution models in London and New York are bypassing traditional retail intermediaries for premium silk-wrapped variants.
- Fitness Gear:Sweat-resistance and quick-adjust functionality prioritize polymer-over-metal construction for wearable device integration. Aftermarket customization services capture value-added revenue through engraving and color-matching.
- Industrial Use:UV-stability and chemical resistance specifications dominate cable management and manufacturing line applications. Volume procurement concentrates through automotive OEM supply agreements.
- Office Supplies:Cost-optimized polypropylene variants serve document bundling and organizational applications with minimal performance differentiation.
Fashion Accessories retains the largest revenue base, yet Fitness Gear is expanding most quickly through wearable device convergence.
End User:
Procurement authority sits with distinct organizational layers, from individual stylists consolidating through B2B platforms to manufacturer quality departments enforcing incoming material certification.
- Consumers:Individual purchasing decisions respond to point-of-sale placement and social media trend velocity. Mass-market volume flows through North American drugstore chains and European supermarket general merchandise.
- Retailers:Category managers negotiate exclusive colorways and packaging formats to defend private label positioning. Inventory commitments shift toward dual-use material platforms serving adjacent accessory categories.
- Manufacturers:Medical device and automotive OEMs demand lot-level traceability and ISO 13485 supplier certification. German precision manufacturing clusters concentrate procurement density for certified fastening solutions.
- Educational Institutions:Bulk procurement of standard-grade fasteners for classroom and administrative applications prioritizes unit cost over performance specifications.
Manufacturers drive the highest-margin demand segment, while Retailers intermediate the greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes clip bands predominantly for surgical instrument fixation and automotive cable management, while the United States channels demand through mass-market retail and fitness wearable integration. China and India concentrate production for export-oriented fashion accessories, diverging from European medical-grade procurement patterns.
Germany
Stuttgart and Munich precision manufacturing clusters drive medical-grade silicone procurement for orthopedic device OEMs. EU MDR biocompatibility mandates force certification upgrades across skin-contact fastener supply chains. Baden-Württemberg's surgical instrument manufacturers validate nickel-free metal formulations ahead of REACH Annex XVII enforcement timelines.
United States
FDA device classification pathways govern clip bands intended for patient monitoring and surgical applications, separating regulated healthcare channels from consumer segments. California Proposition 65 disclosure requirements constrain formulation flexibility for brands distributing nationwide. Greater Boston's medical device corridor concentrates demand for quick-release magnetic variants in wearable health monitoring.
China
NMPA medical device registration requirements segment domestic production between export-oriented fashion accessories and regulated healthcare supply. Yangtze River Delta injection molding clusters supply polypropylene fasteners for North American drugstore chains. SAMR quality inspections tighten on nickel-release rates for metal components bound for European markets.
United Kingdom
London's direct-to-salon distribution platforms consolidate independent stylist procurement for premium silk-wrapped variants. ECHA REACH compliance costs push reformulation of metal alloy specifications for hair accessories with skin contact. Manchester textile weaving facilities supply polyester cores to continental European fashion accessory brands.
India
CDSCO medical device rules classify surgical-grade clip bands under notified device categories, requiring import license equivalents for foreign suppliers. Maharashtra's plastic processing belt manufactures cost-optimized polypropylene variants for educational and office supply bulk procurement. BIS quality certification programs expand for textile-woven elastic bands serving domestic fashion accessory demand.
Clip Band Market Competitive Environment
Capability concentration sits with medical-grade silicone specialists holding ISO 10993 validation; scale advantage sits with mass-market injection molders serving retail drugstore chains. The vendor base splits between certified healthcare suppliers and fast-fashion accessory producers. Three archetypes dominate: precision medical device component specialists, salon-channel premium brands, and high-volume retail shelf-space holders. Competitive moves concentrate on dual-use material platform development and direct-to-stylist distribution bypasses.
Among mass-market shelf-space holders, Goody Products Inc. anchors North American drugstore channel presence, while Conair LLC occupies a position within salon-relationship-driven premium tiers. Silke London exemplifies the material-differentiation archetype through silk-wrapped positioning. These three represent divergent margin-capture strategies: volume scale, channel control, and unit premiumization.
| Leading Market Players |
|---|
| Goody Products Inc. |
| Claire's Stores Inc. |
| Conair LLC |
| H&M Hennes & Mauritz Retail Private Limited |
| Forever 21 |
| Annie International Inc. |
| Silke London |
| HAIRDRAMACO INDIA PRIVATE LIMITED |
| Jennifer Behr LLC |
| Others |
Value Chain & Pricing Dynamics
EU MDR biocompatibility mandates function as a regulatory chokepoint that compresses pricing spreads between certified medical-grade silicone and commodity polyester alternatives while forcing supply chain restructuring toward German validation hubs. This certification barrier simultaneously elevates input costs for healthcare-bound production and strands unvalidated capacity in consumer-grade segments.
Pricing Analysis
Long-term offtake contracts dominate medical-grade silicone procurement, with German orthopedic device OEMs locking in 18-36 month supply agreements that insulate validated suppliers from spot-market volatility. Price differentiation hinges on ISO 10993 certification depth and lot-level traceability rather than raw material grades. Pricing pressure stems from REACH Annex XVII nickel restrictions accelerating metal-to-polymer substitution in skin-contact applications. Mass-market fashion accessory buyers exhibit highest price sensitivity, while surgical instrument manufacturers accept 40-60% premiums for rapid-detachment magnetic functionality.
Supply Chain Analysis
Export-control scrutiny on neodymium magnet processing limits rare-earth element flows from China to European medical device manufacturers, constraining magnetic clip variant expansion. Geographic supply concentration centers on Germany for precision metal stamping, China for polypropylene injection molding, and India for textile-woven elastic cores. Raw material dependencies span platinum-cured silicone from specialty chemical suppliers, neodymium-iron-boron magnets, and medical-grade stainless steel alloys. Single-source vulnerability sits with Yangtze River Delta molders serving North American drugstore chains. Distribution runs through Stuttgart precision clusters for healthcare OEMs and direct-to-salon platforms for premium fashion accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping clip band value capture as direct-to-salon distribution and wearable device integration create interoperability demands between fashion accessory and medical-grade specifications.
For Market Incumbents: Pre-empt channel disintermediation by consolidating direct-to-stylist platform relationships before independent B2B procurement scales. Secure backward integration into platinum-cured silicone compounding to defend margin position against REACH-driven reformulation cycles. Invest in dual-use material platforms spanning textile weaving and metal stamping to serve converging fashion-medical demand.
For New Entrants and Emerging Players: Build out aftermarket customization capabilities targeting London and New York salon networks where relationship-based procurement displaces mass-market shelf competition. Exploit underpenetrated fitness wearable integration in Greater Boston's medical device corridor. Lead with quick-release magnetic architectures that command premium positioning through rapid-detachment functionality.
For Investors and Strategic Acquirers: EU MDR biocompatibility mandates reshape the acquisition landscape by concentrating value in ISO 10993-validated suppliers with German OEM relationships. Long-term viability favors precision medical component specialists over fast-fashion volume players facing compressed innovation cycles. Monitor ECHA enforcement actions against nickel-bearing jewelry fasteners as signal for accelerated metal-to-polymer substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Material Platform Development | Converging textile weaving and metal stamping processes captures fashion-medical crossover demand. |
| Direct-to-Salon Distribution Launch | Bypassing retail intermediaries in London and New York consolidates premium silk-wrapped variant procurement. |
| ISO 10993 Certification Investment | Biocompatibility validation opens German orthopedic OEM supply agreements with 15-25% material premiums. |
| Neodymium Magnet Supply Agreement | Securing rare-earth element flows from China insulates magnetic clip production against export-control tightening. |
| REACH Annex XVII Compliance Program | Nickel-free formulation validation ahead of ECHA enforcement captures share from reformulation-lagged competitors. |
Study Parameters
A standing panel of surgical instrument procurement managers, biomedical engineers at German orthopedic OEMs, salon-channel category buyers, and textile weaving facility operators provided ongoing calibration against secondary validation from FDA device classification filings, EU MDR technical documentation, ECHA REACH substance restriction updates, and customs trade data on silicone and magnet inputs. Bottom-up demand modeling from end-use applications triangulated against top-down supply capacity assessments across precision manufacturing clusters.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product architecture, material certification grade, application intensity, and end-user procurement authority. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory compliance cost passthrough and channel shift velocity. Industry-specific forecast inputs included ISO 10993 validation timeline distributions and direct-to-salon platform adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Yangtze River Delta polypropylene molders or accelerated bioresorbable polymer substitution by German orthopedic device manufacturers would shift outcomes. Material shifts in EU MDR enforcement intensity or neodymium export-control tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Hair Salon Equipment Market
Consumer Goods
Consumer Grade Smart Wearable Device Market
Consumer Goods
Tactical Footwear Market
Consumer Goods
Philippines Skin Care Products Market
Consumer Goods
Global Smart Appliances Market
Consumer Goods
US Cookware Market
Consumer Goods
Residential Cooker Hoods Market
Consumer Goods
Refrigerator Door Seal Market
Consumer Goods
Camping Equipment and Furniture Market
Consumer Goods
Dust Covers Market
Consumer Goods
Electric Soap Dispenser Market
Consumer Goods
Mushroom Cosmetics Market
Consumer Goods
Saudi Arabia Cookware Market
Consumer Goods
Mechanical Keyboard Market
Consumer Goods
Pet Clean-Up and Odor-Control Products Market
Consumer Goods
Refurbished Electronics Market