
 PVC Footwear Market | 2026-2036
PVC Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Footwear Market Analytics
Southeast Asian compound manufacturers is pivoting toward phthalate-free formulations to serve export markets. VKC Group leverages its Kerala manufacturing base to dominate South Indian distribution. Bata Shoe Organization sustains multi-price-point coverage across urban and rural channels. Crocs, Inc. differentiates through proprietary closed-cell resin technology that extends beyond conventional PVC blends.
PVC footwear comprises injection-molded or calendered polyvinyl chloride uppers and soles, often plasticized with DINP or DOTP alternatives, achieving Shore A hardness ratings between 55 and 75 for flexibility. Its primary commercial purpose centers on waterproof, chemical-resistant, low-cost foot protection for occupational and casual environments. Sandals and slippers capture the highest volume share in tropical climates where moisture resistance dictates purchase decisions. Work wear applications command premium positioning through steel-toe and anti-slip certifications that justify higher unit economics. Fashion footwear remains the most volatile segment, with trend cycles compressing inventory turns for specialty retailers.
REACH restrictions on SVHC candidate substances and California Proposition 65 litigation pressure reformulation timelines for brands selling into regulated jurisdictions. India's BIS certification mandate for plasticized footwear creates compliance barriers for unorganized producers while formalizing quality benchmarks. ISO 20345 safety standards govern industrial boot specifications across export destinations, filtering supplier eligibility by testing capacity. Stakeholders must monitor regulatory divergence between EU chemical hazard classifications and emerging economy enforcement gaps that fragment compliance costs.
Market Dynamics
REACH compliance deadlines and phthalate substitution mandates are forcing compound reformulation across European supply chains, while agricultural mechanization in tropical belts sustains volume demand for chemical-resistant boots.
Growth Catalysts
- REACH SVHC restrictions:ECHA's expanding candidate list accelerates DINP-to-DOTP plasticizer migration, creating specification upgrade cycles among export-oriented compounders.
- Mechanized agriculture:Southeast Asian plantation operators prioritize steel-toe PVC boots for pesticide handling and wet-field traction, anchoring industrial-grade volume.
- Closed-cell resin advances:Proprietary foaming technologies reduce unit weight while maintaining Shore A hardness, opening athletic-casual crossover applications.
Market Restraints
- Plasticizer cost volatility:DOTP feedstock fluctuations tied to PTA and 2-EH spot markets compress margin predictability for mid-tier compounders.
- Supplier concentration:Southeast Asian resin production clusters in Thailand and Vietnam create geographic vulnerability to monsoon logistics disruptions.
- Biopolymer substitution:PLA and bio-PU alternatives gain shelf space in European fashion channels, pressuring PVC's low-cost positioning.
Strategic Opportunities
- India BIS formalization:Mandatory IS 15844 certification for plasticized footwear filters unorganized competitors, expanding addressable market share for compliant producers.
- Healthcare antistatic applications:ESD-rated PVC clogs penetrate pharmaceutical cleanrooms and electronics assembly floors, diversifying beyond traditional workwear.
- D2C channel expansion:Direct-to-farmer digital platforms in Indonesia and Philippines bypass layered distributor markups, capturing rural price-sensitive demand.
Industry Challenges
- ISO 20345 testing capacity:Safety boot certification requires capital-intensive impact and compression equipment, excluding smaller molders from premium industrial contracts.
- Legacy equipment retooling:Phthalate-free formulations demand modified screw geometries and temperature profiles, straining technical upgrade budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Footwear Market |
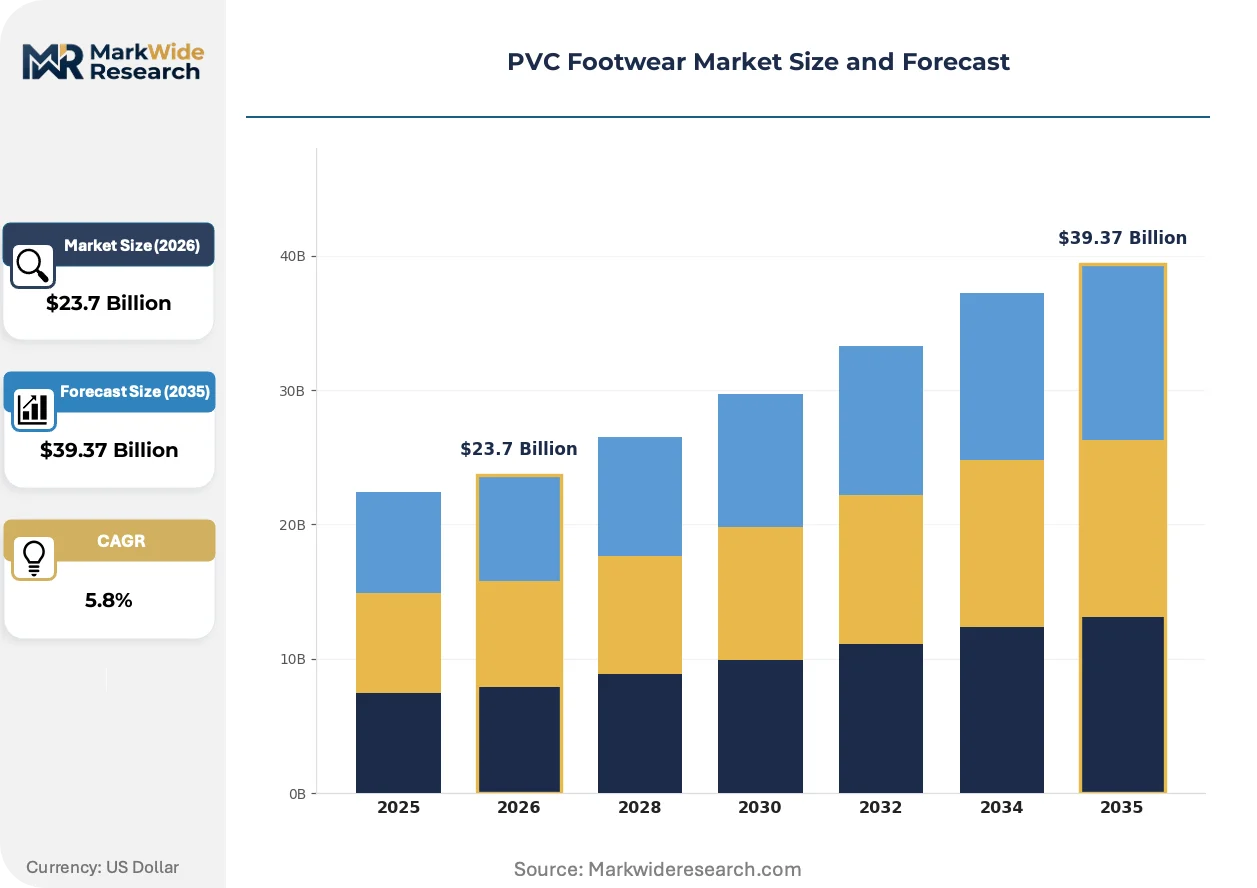
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandals, Boots, Slippers, Formal Shoes End User: Adults, Children, Seniors, Athletes Sales Channel: Online Retail, Specialty Stores, Supermarkets, Discount Outlets Application: Casual Wear, Work Wear, Sports Wear, Fashion Footwear |
| Companies Covered | VKC Group, Havaianas, Bata Shoe Organization, Skechers USA, Inc., Dr. Martens plc, Crocs, Inc., Grendene, Liberty Shoes, Fujian Jinyang Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Footwear Market Evolving Landscape
Material science advances and regulatory stringency are compressing traditional formulation cycles while digital distribution reconfigures last-mile access patterns across tropical consumer belts.
Closed-cell injection molding is consolidating position as the dominant lightweighting pathway for casual PVC footwear. Plantation operators and urban commuters alike prioritize mass-reduced soles that retain chemical resistance. This convergence is consolidating technical differentiation among compounders capable of cell-structure control at industrial scale.
California Proposition 65 litigation against DINP-containing products is accelerating warning-label mandates and settlement-driven reformulation across US-bound supply chains. Importers now face dual-track compliance: REACH-registered European formulations versus Prop 65-screened California shipments. Children's and occupational segments bear the highest retooling burden as exposure-risk calculations tighten.
Buyer aggregation through agricultural cooperative procurement is displacing traditional distributor networks in Indonesia and Vietnam. Smallholder collectives negotiate volume-direct contracts with Kerala-based manufacturers, compressing intermediary margins. This channel shift is most pronounced in East Java and Mekong Delta rice-growing belts where cooperative penetration exceeds forty percent of rural footwear purchases.
PVC Footwear Market Segmentation
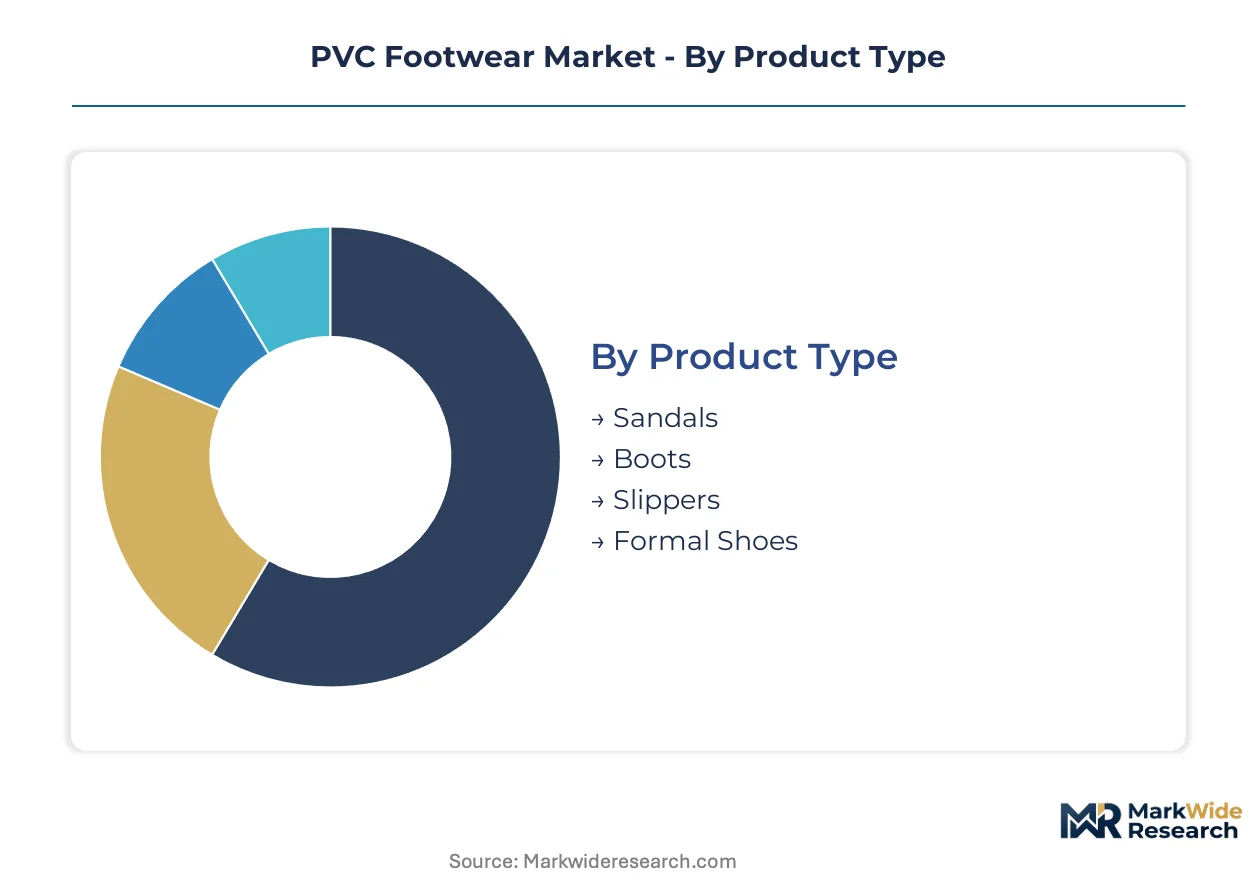
PVC footwear segmentation reflects divergent technical requirements across climate zones, occupational hazards, and price sensitivity thresholds. Material hardness ratings, plasticizer loadings, and reinforcement specifications vary systematically by end-use, creating distinct manufacturing competencies and margin architectures.
Product Type:
Injection-molded construction and calendered sheet forming define the technical axis, with Shore A hardness and plasticizer content calibrated to flexural demands and chemical exposure levels.
- Sandals:Open-toe designs utilize Shore A 55-65 formulations with DINP or DOTP plasticizers for tropical moisture resistance. Rural Indian and Southeast Asian households drive volume through price points below synthetic rubber alternatives. Monsoon seasonality compresses inventory cycles for Kerala-based distributors serving plantation belts.
- Boots:Steel-toe and chemical-resistant variants achieve Shore A 70-75 hardness with reduced plasticizer migration for occupational safety. Agricultural mechanization in Indonesian palm oil and Vietnamese rice cultivation sustains industrial-grade procurement through cooperative buying channels.
- Slippers:Closed-cell foam injection reduces unit weight for indoor moisture management. Mass-market production clusters in Tamil Nadu and Gujarat supply domestic Indian demand with BIS IS 15844 compliance.
- Formal Shoes:Gloss-finished calendered uppers with TPR sole bonding target urban semi-formal occasions. Limited penetration outside price-sensitive emerging markets due to leather and synthetic upper competition.
Sandals lead on scale across tropical consumption belts; boots lead on momentum through agricultural safety mandates.
End User:
Foot morphology, exposure risk profiles, and regulatory scrutiny intensity differentiate formulation and certification requirements across demographic segments.
- Adults:Occupational and casual segments dominate, with size grading standardized to EUR 35-48 ranges. REACH and California Proposition 65 compliance costs concentrate in export-oriented production for this cohort.
- Children:Phthalate restrictions tighten most severely for juvenile exposure risk categories. ECHA SVHC candidate list expansions and DINP litigation settlements force reformulation timelines ahead of other segments.
- Seniors:Anti-slip sole geometries and wider last constructions address balance stability requirements. Japanese JIS T 8103 standards for elderly footwear influence design specifications in aging Asian markets.
- Athletes:Closed-cell resin foaming technologies reduce density for crossover athletic-casual applications. Crocs proprietary compounds demonstrate technical feasibility beyond conventional PVC blends.
Adult segments anchor manufacturing scale; children's segments face steepest regulatory compliance cost escalation.
Sales Channel:
Distribution infrastructure maturity and buyer information access determine pricing transparency and margin capture across channel architectures.
- Online Retail:Direct-to-farmer platforms in Indonesia and Philippines bypass traditional distributor markups. Cooperative procurement aggregation compresses intermediary margins in East Java and Mekong Delta rice belts.
- Specialty Stores:Safety boot certification displays and fitting services justify premium positioning for ISO 20345-compliant workwear. Capital-intensive impact testing equipment requirements filter supplier eligibility.
- Supermarkets:Mass-market sandals and slippers move through high-velocity SKU rationalization. VKC Group and Bata Shoe Organization maintain shelf space dominance through multi-price-point coverage.
- Discount Outlets:Unorganized producers without BIS certification supply price-sensitive rural demand. Quality variance creates reputation risk for formal sector brands with downstream traceability.
Supermarkets retain volume leadership; online retail gains share fastest through cooperative procurement digitization.
Application:
Functional performance requirements and fashion cycle volatility create divergent margin stability and inventory risk profiles.
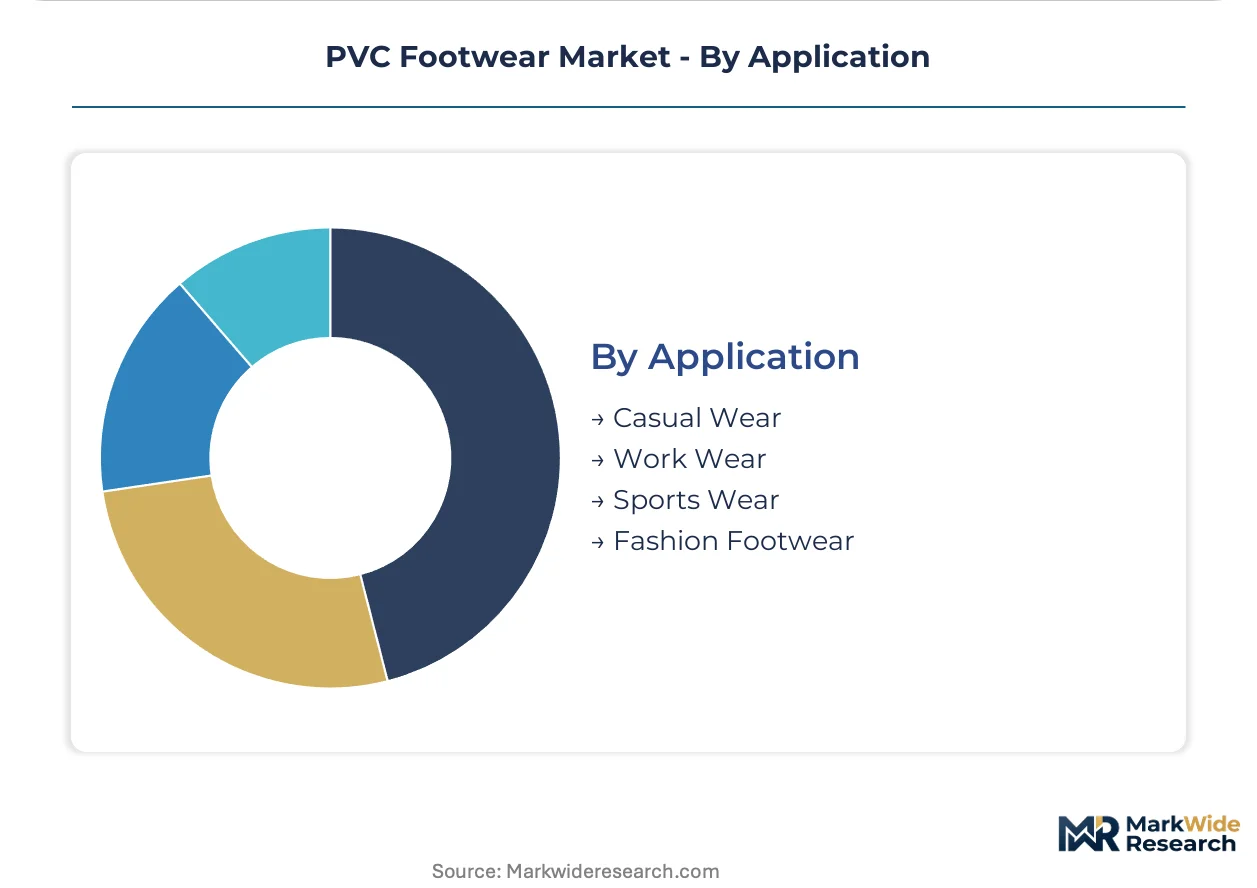
- Casual Wear:Waterproof comfort positioning dominates tropical urban commuting and household use. Closed-cell lightweighting technologies expand addressable occasions beyond traditional PVC applications.
- Work Wear:Chemical resistance and steel-toe certification command premium unit economics. ISO 20345 testing capacity constraints exclude smaller molders from plantation and industrial contracts.
- Sports Wear:Limited penetration due to EVA and PU dominance in performance athletic segments. Proprietary foaming advances enable niche crossover positioning at lower density thresholds.
- Fashion Footwear:Compressed trend cycles elevate inventory obsolescence risk for specialty retailers. Biopolymer substitution pressure from PLA and bio-PU alternatives concentrates in European fashion channels.
Casual wear anchors volume stability; work wear delivers margin durability through certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Indonesia diverge sharply in PVC footwear demand drivers, with Kerala-based mass production serving plantation belts while Javanese cooperatives reshape procurement channels through digital aggregation platforms.
India
Monsoon-driven replacement cycles and agricultural mechanization sustain volume demand for chemical-resistant boots across South Indian plantation belts. BIS IS 15844 certification mandates filter unorganized producers, formalizing quality benchmarks for plasticized footwear. VKC Group leverages its Kerala manufacturing base to dominate distribution through price-sensitive rural channels.
Indonesia
Palm oil plantation operators prioritize steel-toe PVC boots for pesticide handling and wet-field traction, anchoring industrial-grade procurement volumes. Agricultural cooperative buying channels displace traditional distributor networks in East Java and Sumatra. Surabaya-based compounders pivot toward phthalate-free formulations to serve export market specifications.
Vietnam
Mekong Delta rice cultivation sustains demand for waterproof work boots through cooperative procurement aggregation exceeding forty percent of rural purchases. ECHA REACH compliance requirements reshape compound formulations for EU-bound production. Ho Chi Minh City resin processing clusters face monsoon logistics vulnerability during Q3 production cycles.
Thailand
Rubber plantation mechanization drives safety footwear adoption with ISO 20345 certification requirements filtering supplier eligibility. The country's national chemical safety regulator enforces evolving phthalate restrictions aligned with regional harmonization efforts. Bangkok industrial zones concentrate injection-molding capacity serving domestic and regional export demand.
United States
California Proposition 65 litigation against DINP-containing products accelerates warning-label mandates and settlement-driven reformulation across US-bound supply chains. EPA chemical hazard classifications influence downstream exposure-risk calculations for children's and occupational segments. Los Angeles and Long Beach port complexes handle bulk import volumes subject to dual-track compliance screening.
PVC Footwear Market Competitive Landscape
South Asian producers anchor the mass-market tier; Brazilian and American specialists hold differentiated positions through proprietary compounds and brand equity. The vendor base stratifies across three archetypes: Kerala-based mass manufacturers, closed-cell resin technology licensors, and safety-certified industrial boot fabricators. M&A activity concentrates on cooperative procurement platform acquisitions; capacity expansion targets BIS-compliant production lines for Indian formalization.
Among mass-market manufacturers, VKC Group and Bata Shoe Organization exemplify scale-driven positioning across multi-price-point rural and urban channels. Within technology-differentiated tiers, Crocs, Inc. occupies a position defined by proprietary closed-cell resin formulations extending beyond conventional PVC blends.
| Leading Market Players |
|---|
| VKC Group |
| Havaianas |
| Bata Shoe Organization |
| Skechers USA, Inc. |
| Dr. Martens plc |
| Crocs, Inc. |
| Grendene |
| Liberty Shoes |
| Fujian Jinyang Group Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Backward integration into resin compounding anchors supply position and pricing power for Kerala-based manufacturers serving BIS-certified domestic demand. Captive control over DINP-to-DOTP formulation shifts insulates margin stability against plasticizer feedstock volatility while export-oriented compounders absorb specification upgrade costs.
Pricing Analysis
Capacity additions in Tamil Nadu and Gujarat are reshaping price floors for mass-market sandals and slippers. Three-tier pricing structure across BIS-certified, organized non-certified, and unorganized economy levels segments buyer access. Price differentiation hinges on IS 15844 compliance status and steel-toe ISO 20345 certification tier. Margins are tightening due to DOTP feedstock fluctuations tied to PTA and 2-EH spot markets. Plantation procurement cooperatives in Indonesia and Vietnam exhibit lowest price sensitivity; discount outlet rural consumers in India show highest.
Supply Chain Analysis
Dual-sourcing qualification mandates from EU and US importers force compounders to maintain parallel REACH-registered and Prop 65-screened formulation streams. Geographic supply concentrates in Thailand, Vietnam, and India for resin processing and injection-molding capacity. Raw material dependencies center on PVC resin, plasticizer feedstocks, and steel-toe reinforcement components. Single-source vulnerability runs through Southeast Asian monsoon logistics disruptions during Q3 production cycles. Distribution runs through agricultural cooperative platforms in Indonesia and Philippines, layered distributor networks in India, and safety equipment specialty channels for certified workwear.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play between India's BIS formalization compliance costs and Southeast Asia's phthalate-free export reformulation burdens. The cost differential favors captive resin integration in Kerala against import-dependent Vietnamese compounders facing dual-track specification screening.
For Market Incumbents: Acquire cooperative procurement platform assets in East Java and Mekong Delta rice belts to lock in plantation volume contracts. Invest in closed-cell foaming R&D to extend proprietary compound differentiation beyond conventional PVC blends. Biopolymer substitution pressure from PLA and bio-PU alternatives in European fashion channels threatens low-cost positioning; defend through BIS certification barriers that filter unorganized competitors.
For New Entrants and Emerging Players: Agricultural cooperative procurement managers in Indonesian palm oil and Vietnamese rice cultivation represent underserved buyer archetypes with concentrated volume potential. Target ESD-rated PVC clogs for pharmaceutical cleanrooms and electronics assembly floors in Thailand and Malaysia. Bypass layered distributor markups through direct-to-farmer digital platforms replicating East Java cooperative aggregation models.
For Investors and Strategic Acquirers: Roll-up economics work for BIS-compliant mid-tier manufacturers because mandatory IS 15844 certification filters unorganized competitors and expands addressable market share for formal sector producers. Five-to-ten year viability hinges on phthalate-free formulation transition completion and closed-cell resin technology licensing penetration. Watch ECHA SVHC candidate list expansion velocity as inflection indicator for accelerated DINP-to-DOTP migration timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive DINP-to-DOTP formulation control insulates margin stability against PTA and 2-EH feedstock volatility. |
| BIS Certification Investment | IS 15844 compliance filters unorganized competitors and formalizes quality benchmarks for plasticized footwear. |
| Cooperative Procurement Platform Acquisition | East Java and Mekong Delta aggregation networks displace traditional distributor markups in plantation belts. |
| Closed-Cell Resin Technology Licensing | Proprietary foaming reduces unit weight while maintaining Shore A hardness for athletic-casual crossover applications. |
| Phthalate-Free Formulation Transition | REACH SVHC and California Proposition 65 compliance enables dual-track EU and US market access. |
Research Methodology
Multiple input streams — primary interviews with compounder plant managers, safety boot procurement leads at plantation operators, and distributor channel partners; secondary validation through BIS certification databases, ECHA REACH registration filings, and customs/trade data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured formulation shift timelines and cooperative procurement aggregation patterns across Kerala, East Java, and Mekong Delta production clusters.
Data-stream reconciliation anchored analytical framework development across the projection horizon. Segmentation dimensions modeled include product construction type, end-user demographic, sales channel architecture, and application function with regional regulatory cluster overlays. CAGRs were derived through trend extrapolation and driver elasticity assessment. Industry-specific forecast inputs incorporated plasticizer substitution cost curves and ISO 20345 testing capacity expansion trajectories.
Underlying measurement precision varies by segment; BIS-certified and REACH-registered production carry tighter precision than unorganized economy supply. Forecasts reflect assumptions on regulatory enforcement consistency and cooperative procurement digitization velocity. Deviation in ECHA SVHC candidate list expansion or California Proposition 65 settlement patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Running Shoes Market
Footwear
E-Commerce Footwear Market
Footwear
High Heels Footwear Market
Footwear
Hiking Footwear Market
Footwear
Golf Footwear Market
Footwear
Barefoot Shoes Market
Footwear
Platform Boots Market
Footwear
Trail Running Shoes Market
Footwear
Training Shoes Market
Footwear
Protective Footwear Market
Footwear
Wedge Boots Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Footwear Testing Services Market
Footwear
Custom Shoes Market
Footwear
Refurbished Sneaker Market
Footwear
Flip Flops Market