
 Decompression Toys Market | 2026-2036
Decompression Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Decompression Toys Market Outlook
Buyer concentration across the decompression toys sector is decoupling from traditional toy retail chains as direct-to-consumer channels and corporate procurement offices fragment purchasing power across new entry points. Tangle Creations leverages its patented link geometry to sustain niche dominance in therapeutic settings. ZURU Toys competes through mass-market scale and rapid product rotation across global big-box shelves. Hasbro, Inc. anchors its position via licensed character tie-ins that extend brand recognition into stress-relief product lines.
Decompression toys are tactile manipulatives engineered from elastomeric compounds—typically silicone, thermoplastic polyurethane, or closed-cell foam—designed to redirect nervous energy through repetitive hand motion and proprioceptive feedback. Injection molding and rotational casting dominate production, with durometer ratings between 20 and 40 Shore A optimizing squeeze resistance for adult grip strength. Stress balls occupy the largest volume tier, though sensory socks command premium positioning within occupational therapy supply chains. Silicone formulations lead material value pools due to hypoallergenic certification requirements, while foam variants dominate unit economics in bulk educational procurement.
The EU Toy Safety Directive and ASTM F963 in the United States govern phthalate limits and small-part choking hazards, compelling manufacturers to submit third-party lab testing for market access. Japan's Ministry of Economy, Trade and Industry enforces Food Sanitation Law analogs for mouthing-age products, adding compliance layers for exporters. Stakeholders must monitor evolving chemical disclosure mandates under REACH and emerging state-level transparency laws in California and Washington that could reshape formulation standards and supplier qualification protocols.
Market Dynamics
Corporate procurement offices now source decompression toys through wellness benefit platforms, bypassing traditional retail channels and fragmenting purchasing power across occupational therapy networks, educational supply chains, and direct-to-consumer marketplaces.
Growth Catalysts
- ASTM F963 compliance pathways:Medical-grade silicone formulations meeting United States chemical thresholds open institutional procurement channels previously closed to toy-grade materials.
- Occupational therapy adoption:Sensory integration protocols in Germany, Japan, and the United States incorporate tactile manipulatives into standardized treatment regimens for attention disorders and anxiety management.
- Employee wellness mandates:North American and European corporations embed stress-relief tools into benefits packages, creating recurring B2B demand independent of seasonal retail cycles.
Market Restraints
- Medical-grade silicone cost premiums:Hypoallergenic certification requirements under REACH and state-level transparency laws in California and Washington inflate raw material costs 40-60% above commodity elastomer grades.
- Injection molding capacity concentration:Tooling fabrication and rotational casting expertise clusters in Guangdong province and select German industrial zones, creating geographic supply vulnerability.
- Digital wellness app substitution:Smartphone-based breathing exercises and haptic feedback applications capture younger demographic segments seeking portable stress management without physical inventory.
Strategic Opportunities
- Underpenetrated clinical channels in France and Italy:Occupational therapy supply chains in these markets lack dedicated sensory product distributors, creating first-mover advantage for compliant manufacturers.
- EU Green Deal circularity incentives:Biodegradable thermoplastic polyurethane formulations qualify for green procurement preferences in public sector wellness tenders.
- Subscription wellness box integration:Direct-to-consumer channels bypass retail margin compression while capturing recurring revenue through curated monthly deliveries.
Industry Challenges
- Durometer calibration expertise scarcity:Precision tuning of Shore A ratings between 20 and 40 for adult grip optimization requires specialized polymer engineering talent concentrated in limited manufacturing regions.
- Multi-jurisdiction certification timelines:Simultaneous EU Toy Safety Directive, ASTM F963, and Japan Food Sanitation Law analog testing extends product launch cycles 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decompression Toys Market |
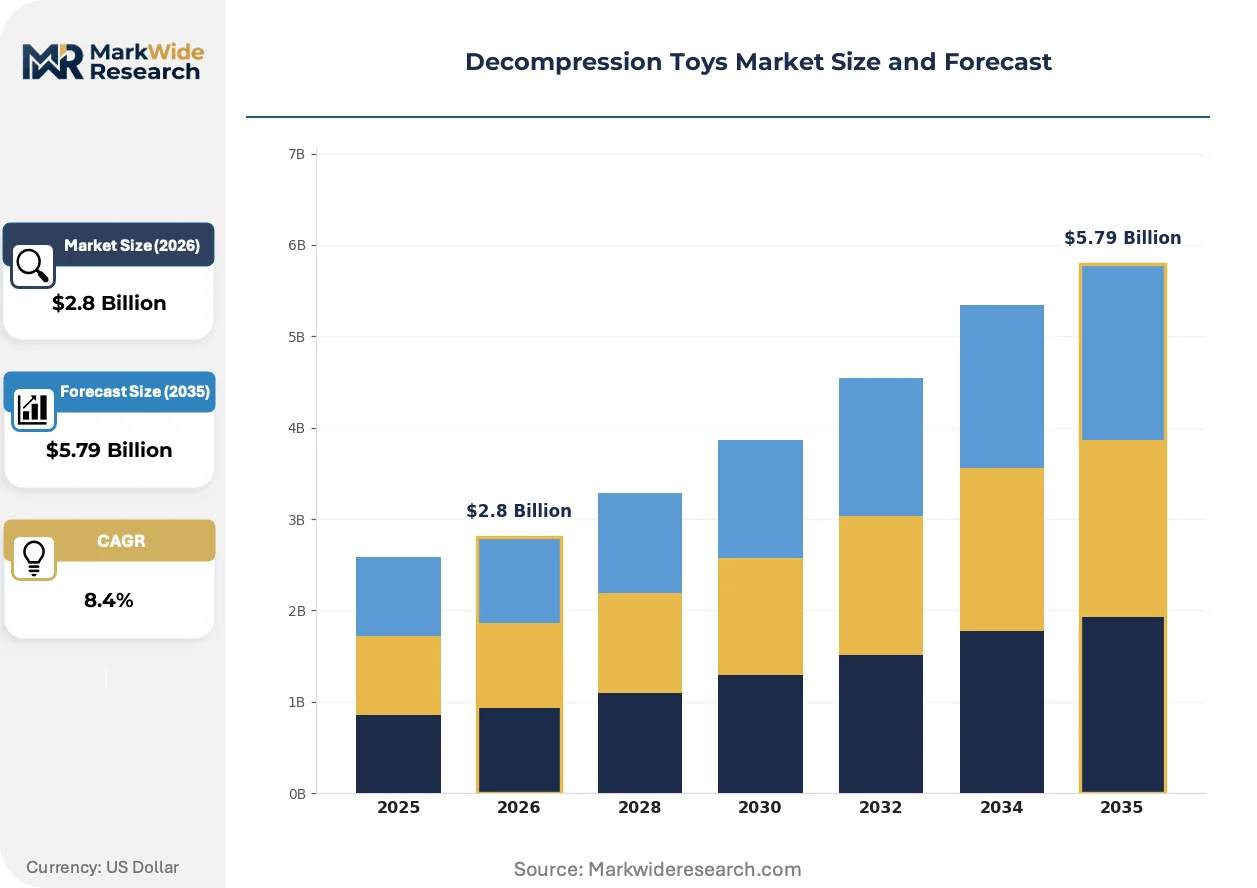
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stress Balls, Fidget Spinners, Sensory Socks, Squishy Toys Material: Silicone, Foam, Plastic, Metal Target Audience: Children, Adults, Therapists, Educators Distribution Channel: Online Retail, Specialty Stores, Toy Stores, Mass Merchandisers |
| Companies Covered | The LEGO Group, Tangle Creations, ZURU Toys, Crazy Aaron’s, CHANG QING SHU TOYS, Antsy Labs, Hasbro, Inc., Tomy International, Spin Master Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decompression Toys Market Strategic Shifts
Material science advances and procurement channel fragmentation are compressing traditional supply hierarchies while elevating clinical-grade specifications into mass-market expectations.
Smart elastomer formulations embedding pressure-sensitive conductive polymers are unifying tactile feedback with biometric monitoring capabilities. Occupational therapy clinics in Germany and the United States pilot these hybrid devices for quantified stress response tracking. This convergence is unifying previously separate wellness hardware and digital health categories into single procurement decisions.
REACH chemical disclosure mandates and emerging state-level transparency laws in California and Washington are forcing reformulation of legacy phthalate-dependent compounds. Manufacturers now submit third-party lab documentation as standard practice rather than exception. Small-batch silicone suppliers in Bavaria and Michigan gain procurement preference over high-volume Asian competitors lacking documentation depth.
Corporate wellness platforms now curate tactile stress-relief products alongside mental health app subscriptions, unbundling traditional toy retail from B2B purchasing decisions. Human resources departments in technology and financial services sectors negotiate direct supplier relationships, bypassing distributor markups. This channel rotation is most visible in the United States, where employer-sponsored wellness spending exceeds individual retail purchases in several metropolitan employment clusters.
Decompression Toys Market Segmentation
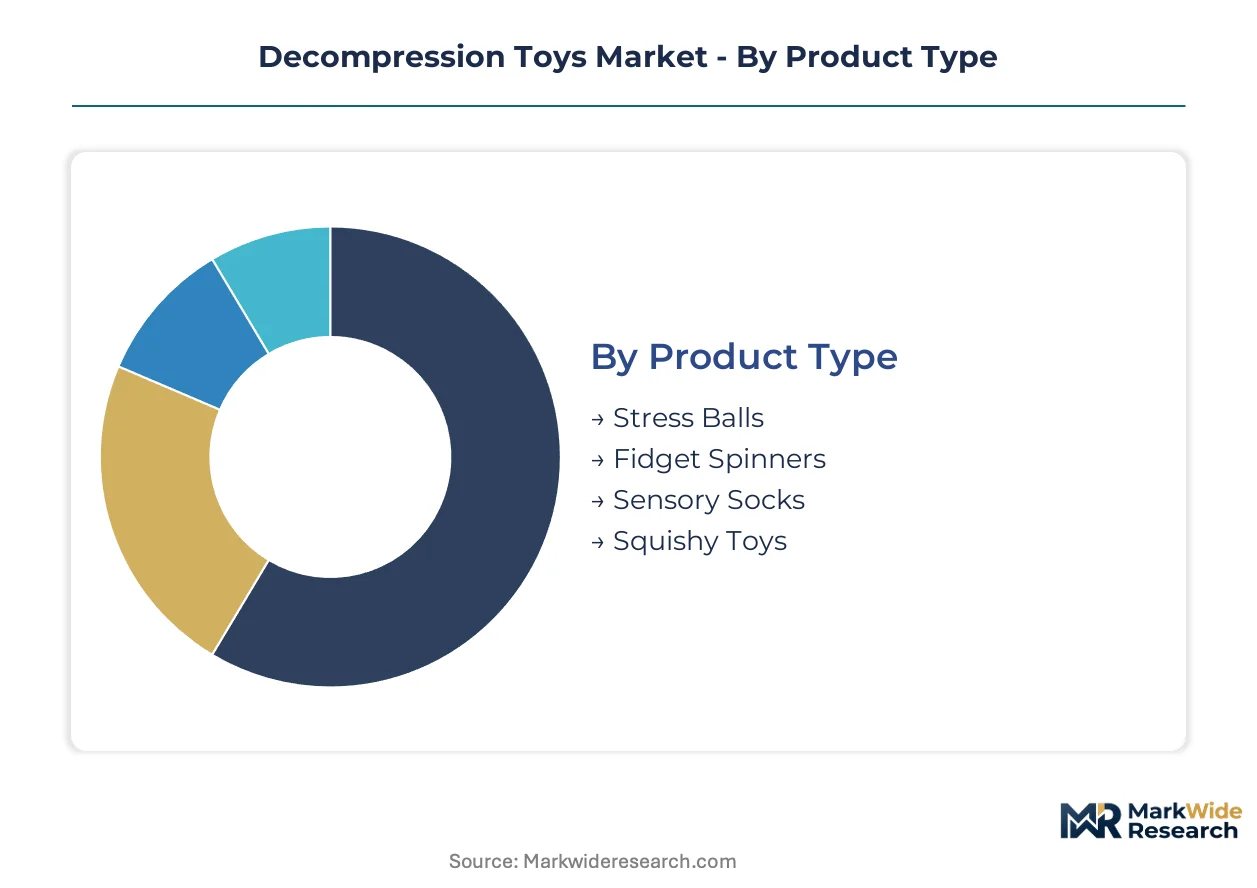
Decompression toys fragment across multiple decision axes that reshape procurement patterns and margin structures. Product specifications, material compliance tiers, and channel economics each create distinct competitive battlegrounds requiring targeted positioning strategies.
Product Type:
Volume concentration versus therapeutic premiumization drives buyer selection across tactile formats.
- Stress Balls:Injection-molded elastomer spheres dominate institutional procurement through occupational therapy networks in Germany and the United States. Corporate wellness mandates in North America generate recurring bulk orders independent of seasonal retail cycles.
- Fidget Spinners:Rotational inertia devices with steel or ceramic bearings command premium positioning in adult consumer segments. Japanese electronics sector employees sustain demand through desk-accessory positioning despite educational institution bans.
- Sensory Socks:Compression textile designs with graduated resistance target clinical applications in occupational therapy supply chains.
- Squishy Toys:Slow-rebound polyurethane formulations capture impulse purchasing through direct-to-consumer channels and subscription wellness boxes.
Stress Balls leads on scale; Sensory Socks leads on momentum.
Material:
Certification depth and raw material cost tier determine supplier qualification and margin capture.
- Silicone:Medical-grade formulations meeting ASTM F963 and EU Toy Safety Directive thresholds open institutional procurement channels. Hypoallergenic certification requirements under REACH inflate input costs but secure preference in Bavaria and Michigan manufacturing clusters.
- Foam:Closed-cell polyurethane dominates educational procurement through unit economics advantage. Bulk orders from United States school districts prioritize cost efficiency over clinical-grade specifications.
- Plastic:ABS and thermoplastic elastomer variants serve mass-market price points through rotational casting in Guangdong province.
- Metal:Stainless steel and aluminum alloys concentrate in precision-engineered fidget mechanisms for durability-focused segments.
Silicone commands margin leadership; Foam commands volume leadership.
Target Audience:
Application setting and purchasing authority define product specification requirements and channel strategy.
- Children:Safety certification and choking hazard compliance dominate procurement criteria. ASTM F963 small-part testing and Japan Food Sanitation Law analogs govern mouthing-age product formulations.
- Adults:Workplace stress management applications prioritize discrete form factors and professional aesthetics. Technology and financial services sectors in the United States embed tactile tools into benefits packages.
- Therapists:Occupational therapy protocols in Germany and the United States incorporate standardized sensory integration regimens requiring documented durometer specifications.
- Educators:Classroom behavior management applications drive bulk procurement through educational supply chains with simplified compliance requirements.
Adults segment climbs the fastest in revenue contribution; Therapists segment deepens fastest in specification intensity.
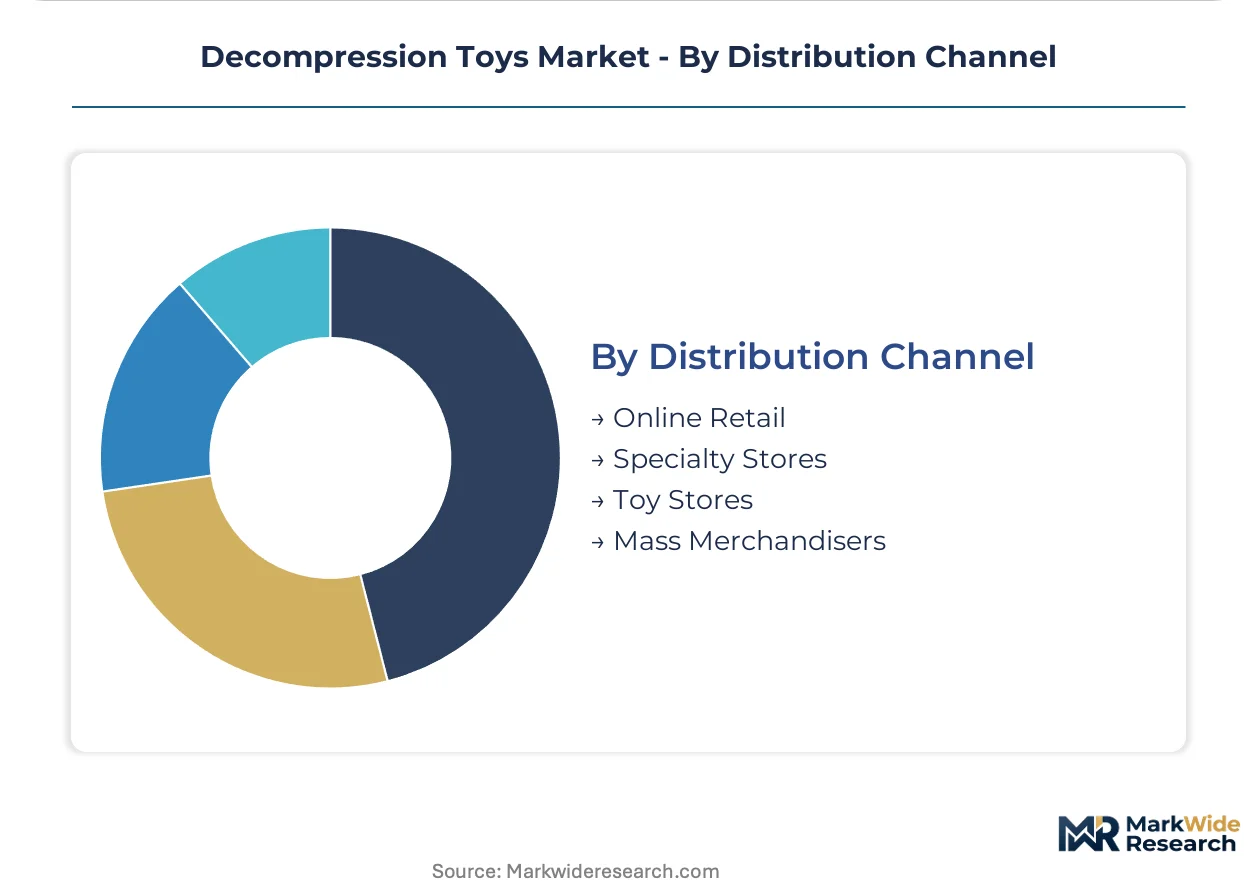
Distribution Channel:
Channel selection determines margin retention, customer data access, and compliance documentation requirements.
- Online Retail:Direct-to-consumer platforms capture recurring revenue through subscription wellness box integration. Human resources departments negotiate supplier relationships bypassing traditional distributor markups.
- Specialty Stores:Occupational therapy supply chains and sensory-focused retailers serve clinical-grade demand with technical consultation services.
- Toy Stores:Seasonal retail cycles and licensed character tie-ins anchor mass-market volume through impulse purchasing.
- Mass Merchandisers:Big-box shelf placement drives rapid product rotation and economies of scale for foam-based educational variants.
Mass Merchandisers leads on unit volume; Online Retail leads on margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's occupational therapy networks absorb clinical-grade silicone formulations at triple the per-capita rate of France, while Japan's corporate desk-accessory culture sustains premium fidget mechanics despite educational bans.
United States
Technology and financial services employers embed tactile stress-relief tools into benefits packages, generating recurring B2B procurement independent of retail cycles. ASTM F963 compliance opens institutional channels previously closed to toy-grade materials. Manufacturing clusters in Michigan and Bavaria supply medical-grade silicone to East Coast corporate wellness platforms.
Germany
Standardized sensory integration protocols for attention disorders drive occupational therapy demand for documented durometer specifications. EU Toy Safety Directive thresholds govern phthalate limits and chemical disclosure. Industrial zones in North Rhine-Westphalia concentrate injection molding expertise for precision-engineered elastomer components.
Japan
Electronics sector employees sustain demand for discrete desk accessories through professional aesthetics positioning. METI enforces Food Sanitation Law analogs for mouthing-age products, adding compliance layers for importers. Tokyo and Osaka metropolitan areas anchor corporate procurement offices sourcing through direct supplier relationships.
China
Guangdong province clusters rotational casting and tooling fabrication capacity serving global mass-market volume. GB standards and SAMR oversight govern domestic chemical safety thresholds. Pearl River Delta manufacturers face margin pressure from REACH documentation requirements and state-level transparency laws in export markets.
United Kingdom
Corporate wellness mandates in London and Southeast employment clusters fragment purchasing power across direct-to-consumer channels. CE marking and post-Brexit UKCA certification create dual compliance pathways. Midlands-based educational supply chains prioritize foam variants for cost-efficient bulk classroom procurement.
Decompression Toys Market Competitive Environment
Guangdong-based manufacturers anchor the volume tier through rotational casting scale; German and US specialists hold premium positioning via medical-grade silicone certification. Market structure fragments across three distinct layers: mass-market big-box suppliers, clinical-grade occupational therapy vendors, and direct-to-consumer subscription platforms. Dominant competitive moves include geographic certification stacking for multi-jurisdiction access and backward integration into medical-grade silicone compounding.
Among diversified toy conglomerates, Hasbro, Inc. and Spin Master Ltd. occupy positions leveraging licensed character recognition to extend brand equity into stress-relief product lines. Within the therapeutic specialist tier, Tangle Creations exemplifies niche dominance through proprietary link geometry patents. ZURU Toys represents mass-market scale velocity through rapid product rotation and global retail shelf penetration.
| Leading Market Players |
|---|
| The LEGO Group |
| Tangle Creations |
| ZURU Toys |
| Crazy Aaron's |
| CHANG QING SHU TOYS |
| Antsy Labs |
| Hasbro, Inc. |
| Tomy International |
| Spin Master Ltd. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into medical-grade silicone compounding anchors premium pricing power for Bavarian and Michigan manufacturers while Guangdong rotational casters compete on unit economics. This supply-side stratification creates divergent margin structures across institutional procurement channels and mass-market retail tiers.
Pricing Analysis
Capacity additions in Guangdong province are reshaping price floors for foam-based educational variants while silicone formulations maintain premium positioning through REACH documentation depth. Three-tier pricing structure across medical-grade, toy-grade, and uncertified economy levels separates occupational therapy supply chains from school district bulk procurement. Cost compression in the foam tier intensifies because of rotational casting scale concentration. Educational buyers exhibit highest price sensitivity; corporate wellness offices prioritize certification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Los Angeles anchor hub-and-spoke patterns for EU and North American clinical-grade fulfillment. Manufacturing concentrates in Guangdong province, North Rhine-Westphalia, and Michigan. Raw material flows draw from German silicone compounders, Chinese TPU resin suppliers, and Japanese precision bearing manufacturers. Single-source vulnerability clusters in Guangdong tooling fabrication. Distribution runs through occupational therapy networks, direct-to-consumer platforms, and big-box retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: REACH compliance costs in Germany and California create 40-60% raw material premiums that certified Asian exporters can capture through documentation investment.
For Market Incumbents: Cement dominance in occupational therapy channels by acquiring Bavarian silicone compounders with existing REACH certification depth. Digital wellness app substitution threatens physical product relevance; counter through smart elastomer development embedding biometric feedback capabilities. For New Entrants and Emerging Players: Launch via subscription wellness box integration targeting technology sector HR departments in Austin and Seattle. France and Italy present underpenetrated clinical channels lacking dedicated sensory product distributors. Prioritize ASTM F963 pre-certification to accelerate institutional procurement access. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap silicone formulators because certification documentation creates sticky supplier relationships with limited replication. Five-to-ten year viability hinges on clinical-channel penetration rates. Watch for EU Green Deal circularity incentives triggering biodegradable TPU formulation pivots as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Silicone Backward Integration | Captive compounding secures REACH documentation depth for Bavarian and Michigan manufacturing clusters. |
| Smart Elastomer Product Launch | Pressure-sensitive conductive polymers unify tactile feedback with biometric monitoring for German therapy clinics. |
| Subscription Wellness Box Partnership | Recurring revenue bypasses retail margin compression in North American corporate procurement channels. |
| France/Italy Distribution Channel Expansion | First-mover advantage in occupational therapy supply chains lacking dedicated sensory product vendors. |
| Biodegradable TPU Formulation Pivot | EU Green Deal circularity incentives qualify green procurement preferences in public sector wellness tenders. |
Study Parameters
Bottom-up occupational therapy and corporate wellness modeling reconciled against top-down rotational casting capacity tracking forms the analytical core. Primary interviews with occupational therapists, HR benefits administrators, silicone compounders, and educational supply procurement officers combined with secondary validation from EU Toy Safety Directive filings, ASTM F963 lab documentation databases, and REACH chemical disclosure registries. Cross-referencing customs records from Guangdong export clusters with Bavarian manufacturing output data enables supply-side triangulation.
Historical trendline analysis of silicone raw material cost movements and certification timeline patterns informed projection frameworks across the modeling period. Segmentation dimensions include product type, material compliance tier, target audience archetype, and distribution channel structure. CAGRs derive from elasticity modeling of institutional procurement growth versus retail channel displacement. Forecast inputs incorporate occupational therapy protocol adoption rates and corporate wellness benefit penetration metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration scenarios or digital wellness substitution breakthroughs. Outputs reflect documented assumptions regarding certification timeline stability and raw material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Toy Collectibles Market
Toys and Games
Animation Toys Market
Toys and Games
Plastic Toy Storage Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
Action Figures Market
Toys and Games
Traditional Toys and Games Market
Toys and Games
Cat Toys Market
Toys and Games
Table Top Games Market
Toys and Games
Connected Toys Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Ride-Ons Market
Toys and Games
Blind Box Toys Market
Toys and Games
China Toys Market
Toys and Games
Bubble Tubes Market
Toys and Games
Global Blind Boxes Market
Toys and Games
Microwaveable Stuffed Animal Toys Market