
 Beard Grooming Products Market | 2026-2036
Beard Grooming Products Market Size, Share, and Industry Trends Forecast 2026-2036
Beard Grooming Products Market Intelligence
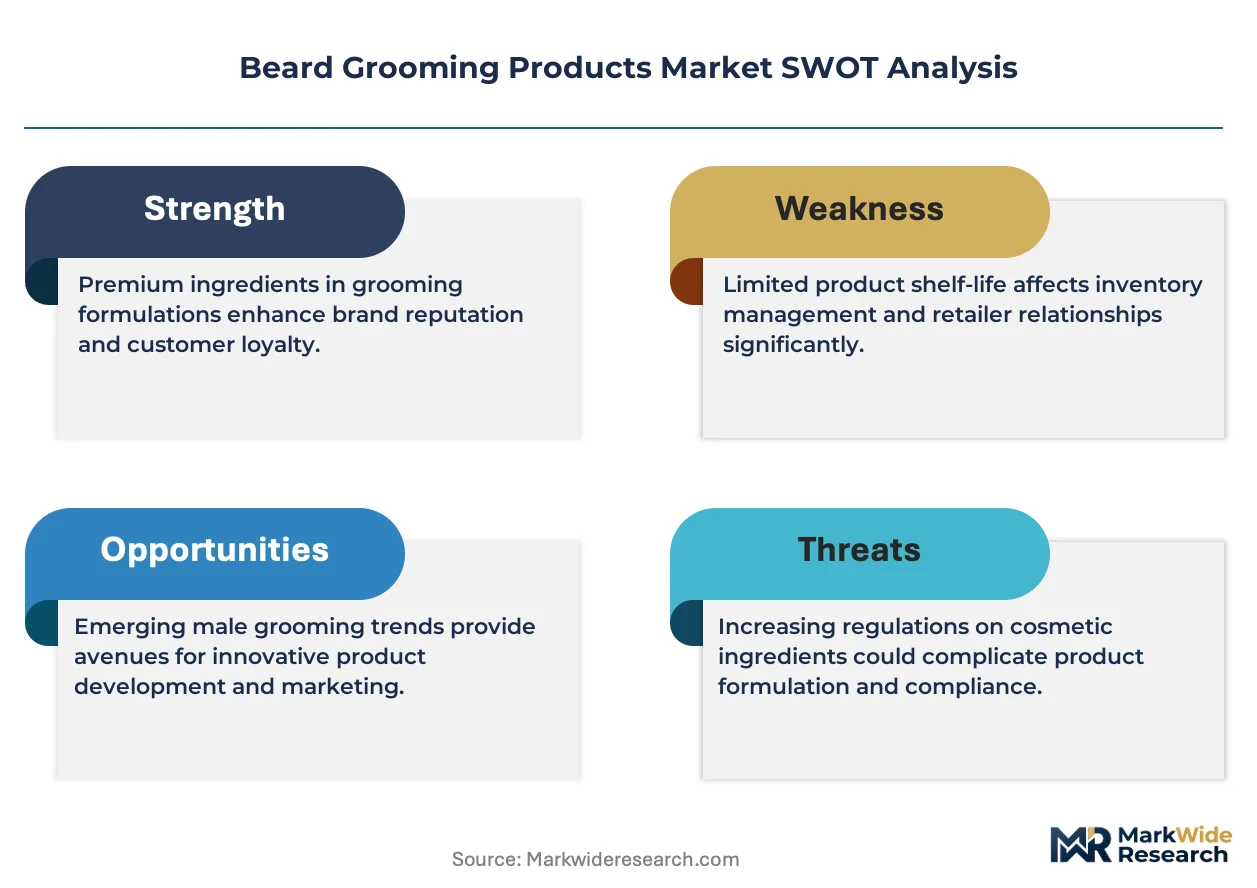
Plant-derived carrier oils are replacing petroleum-based mineral oils in premium beard formulations, a material substitution that is realigning product economics toward cleaner ingredient decks. Beardbrand leverages its direct-to-consumer platform to sustain margin control across premium oils and balms. Honest Amish anchors its market position through heritage craft positioning and Amish-made authenticity claims. Jack Black competes in the masstige tier with dermatologist-tested formulations distributed through Sephora and Ulta channels.
Beard grooming products encompass topical preparations designed for facial hair maintenance, typically comprising carrier oils such as jojoba or argan combined with essential oils for fragrance and conditioning performance. These formulations function to soften coarse hair, moisturize underlying skin, and reduce beardruff through lipid-replenishing mechanisms. Oils and balms command the deepest margin pools due to repeat purchase frequency and premium positioning, while washes represent the fastest-growing product type as consumers extend routines beyond basic oiling. The salon and barbershop end-user segment is outpacing personal use in value terms, driven by professional-grade conditioning treatments and private-label backbar adoption.
FDA oversight of cosmetic labeling claims and EU REACH restrictions on synthetic fragrance compounds are reshaping formulation roadmaps and ingredient sourcing requirements for cross-border brands. The EU Green Deal and emerging state-level clean beauty legislation in California and New York are accelerating disclosure mandates for natural origin percentages and biodegradability metrics. Stakeholders must monitor evolving regulatory divergence between North American and European compliance frameworks while calibrating regional SKU strategies.
Market Dynamics
Direct-to-consumer subscription models are compressing traditional retail margins while elevating ingredient transparency requirements across beard grooming formulations.
Growth Catalysts
- EU REACH fragrance restrictions:Synthetic compound limitations are accelerating natural essential oil adoption in premium beard oil formulations.
- Barbershop professionalization:Licensed grooming establishments are expanding backbar conditioning treatments and private-label retail SKUs.
- Plant-derived carrier oils:Jojoba and argan substitution for petroleum-based mineral oils is realigning clean-label product economics.
Market Restraints
- Argan supply concentration:Moroccan cooperative-dependent sourcing creates price volatility for premium beard oil feedstocks.
- FDA cosmetic labeling enforcement:Structure-function claim scrutiny elevates compliance costs for cross-border brand expansions.
- Private-label substitution:Retailer captive brands are compressing margin pools in standard-tier beard washes and balms.
Strategic Opportunities
- EU Green Deal biodegradability mandates:First-mover disclosure of natural origin percentages captures premium positioning in German and French metros.
- Professional salon channel expansion:Licensed barbershops in Texas and California are adopting recurring revenue models through subscription backbar replenishment.
- Waterless formulation convergence:Solid balm and concentrated oil formats reduce shipping weights and unlock sustainability certifications.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging natural ingredient stability with shelf-life requirements commands premium compensation.
- California SB 574 compliance timelines:Fragrance ingredient disclosure mandates require reformulation cycles that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beard Grooming Products Market |
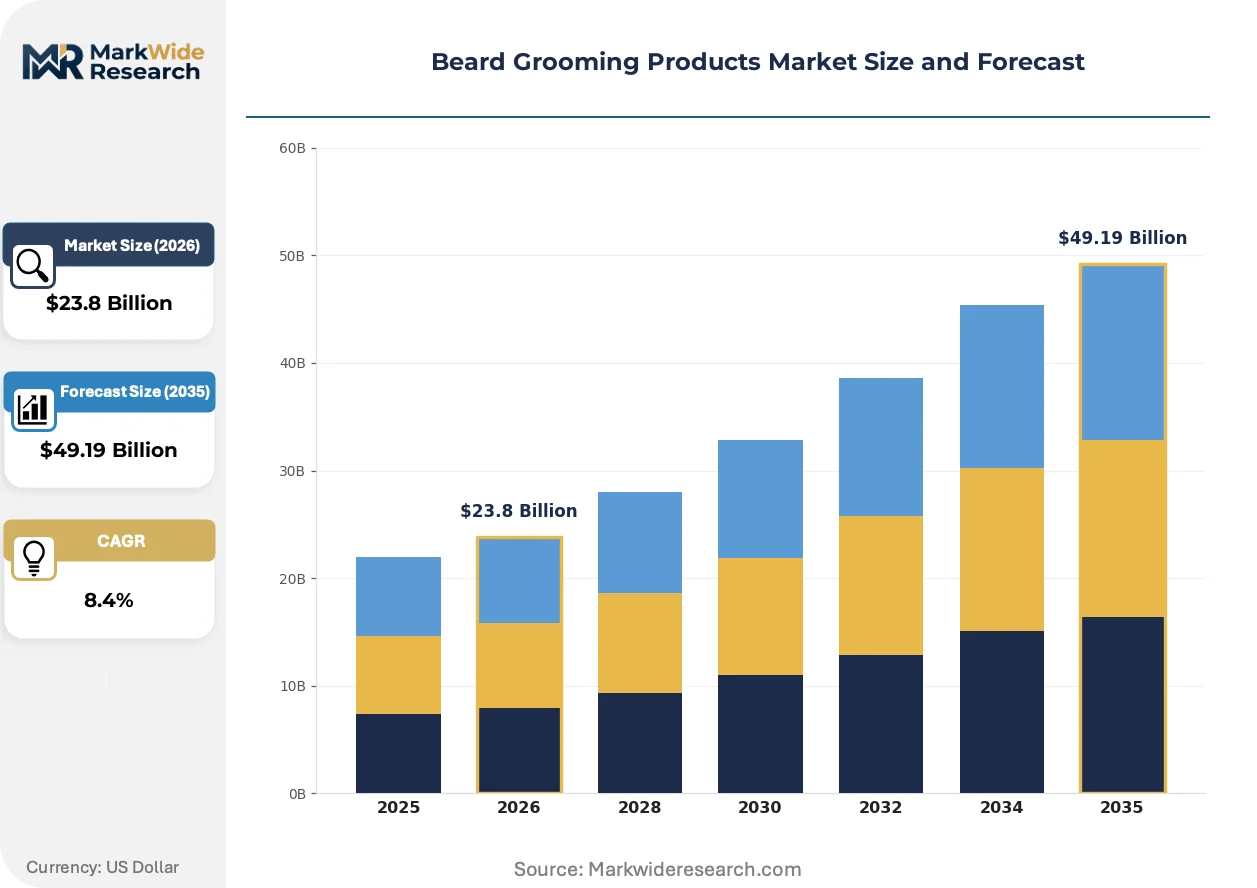
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $49.19 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Balms, Washes, Conditioners Application: Daily Care, Styling, Conditioning, Maintenance End User: Personal Use, Salons, Barbershops, Online Retailers Packaging Type: Bottles, Jars, Tubes, Sachets |
| Companies Covered | Scotch Porter, Viking Revolution, Beardbrand, Cremo Styling, Wild Willies, Honest Amish, Beardo, Jack Black, The Art of Shaving, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beard Grooming Products Market Strategic Shifts & Innovations
Formulation chemistry and distribution architecture are undergoing parallel transformation as ingredient provenance claims and channel control become primary competitive battlegrounds.
Biotechnology-derived squalane from sugarcane fermentation is decentralizing supply chains away from shark liver and olive oil dependencies. Premium beard oil manufacturers in Brooklyn and Austin are adopting this feedstock to bypass agricultural commodity volatility. The shift is compressing traditional carrier oil procurement hierarchies and enabling vertically integrated ingredient sourcing.
California's SB 574 and New York's emerging clean beauty legislation are mandating fragrance ingredient disclosure down to twenty parts per million. Cross-border brands must maintain parallel SKU formulations or accept label complexity that elevates packaging costs. Masstige-tier products distributed through Sephora and Ulta channels face the steepest compliance burden.
Barbershop clients are extending professional conditioning treatments into at-home maintenance routines through subscription replenishment. Direct-to-consumer platforms are displacing mass retail discovery for premium oil and balm purchases. This pattern concentrates most visibly in urban metro clusters across the United States where licensed grooming establishments anchor community credibility.
Beard Grooming Products Market Segmentation
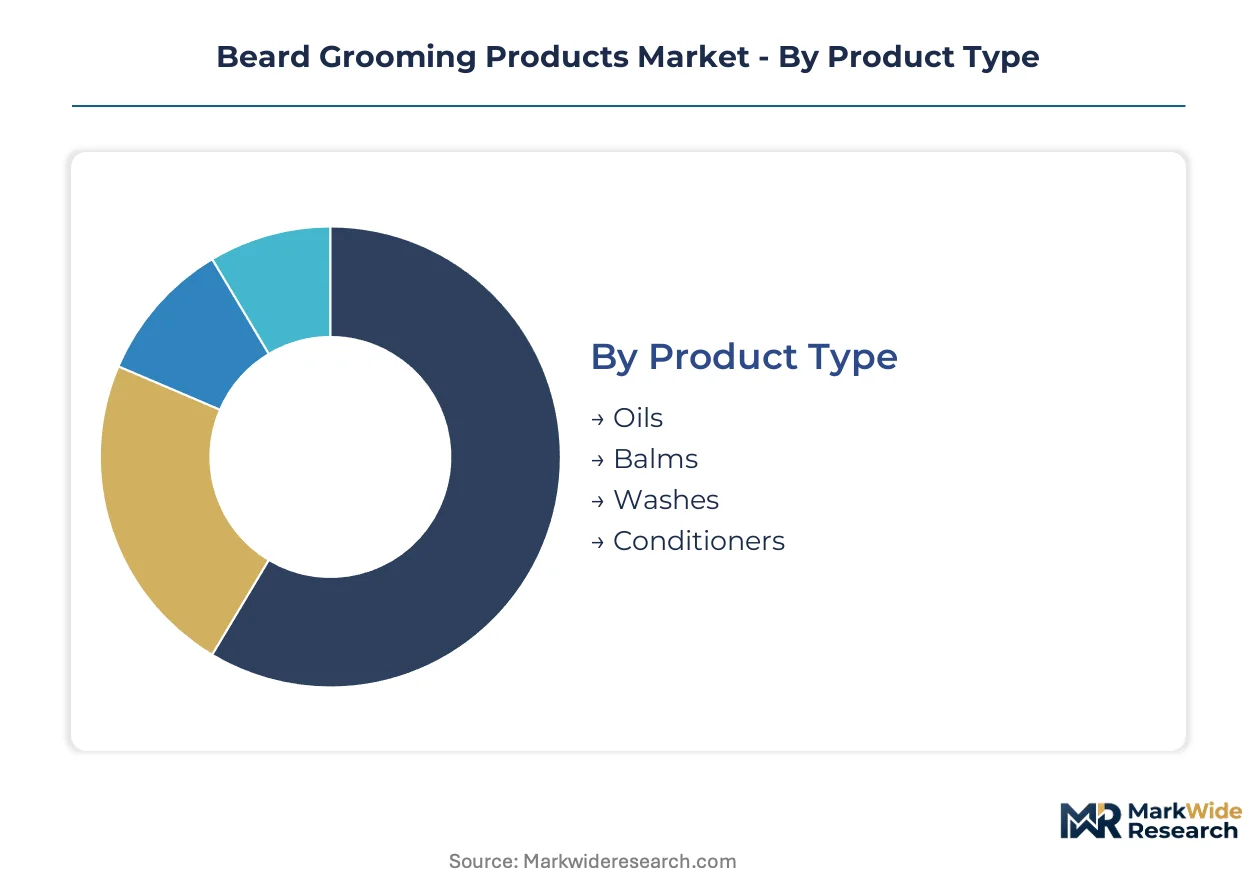
Segmentation in beard grooming products reveals how formulation chemistry, channel control, and usage rituals fragment purchasing behavior across distinct buyer profiles. Understanding these divides enables calibrated positioning against margin pools that vary dramatically by product format and end-use context.
Product Type:
Cost tier separates occasional purchasers from committed routine builders in this category.
- Oils:Lipid-based formulations combining jojoba, argan, or squalane with essential oil fragrance systems. Brooklyn and Austin manufacturers concentrate production here, drawn by repeat purchase frequency and premium positioning that sustains direct-to-consumer margins.
- Balms:Semi-solid preparations incorporating beeswax or plant-based waxes for styling hold and additional conditioning. German and French metros show accelerating preference for waterless balm formats that satisfy EU Green Deal biodegradability disclosure expectations.
- Washes:Surfactant-based cleansers designed for facial hair and underlying skin pH balance. Demand concentrates in subscription box channels where trial-to-repeat conversion drives volume.
- Conditioners:Rinse-out or leave-in treatments extending salon-grade conditioning into at-home routines. Licensed barbershops in Texas and California are adopting these for backbar replenishment programs.
Oils lead volumes today; washes are gaining share fastest through subscription channel expansion.
Application:
Volume concentration tracks ritual frequency and step complexity in male grooming routines.
- Daily Care:Baseline moisturizing and softening applications performed each morning. Urban metro clusters in the United States concentrate demand here, with direct-to-consumer platforms displacing mass retail discovery for replenishment.
- Styling:Shaping and hold applications requiring wax or polymer components. Masstige-tier distribution through Sephora and Ulta channels elevates ingredient transparency requirements for cross-border brands.
- Conditioning:Deep hydration treatments addressing beardruff and coarse texture. Professional salon channel expansion in California and Texas is driving adoption of recurring revenue models.
- Maintenance:Periodic trimming prep and post-grooming skin recovery. Private-label substitution pressure is compressing margin pools in this application tier.
Daily care anchors current volume; conditioning applications show the steepest expansion trajectory as professional treatments extend into home use.
End User:
Customer type determines margin structure through channel control and purchase frequency differentiation.
- Personal Use:Individual consumers purchasing for at-home beard maintenance routines. Subscription models are compressing traditional retail margins while elevating ingredient transparency requirements.
- Salons:Licensed grooming establishments offering professional conditioning and styling services. EU REACH fragrance restrictions are accelerating natural essential oil adoption in backbar formulations.
- Barbershops:Specialized facial hair establishments with private-label retail SKU development. This end-user segment is outpacing personal use in value terms through professional-grade treatment adoption.
- Online Retailers:E-commerce platforms and subscription services curating multi-brand assortments. FDA cosmetic labeling enforcement elevates compliance costs for cross-border brand expansions into this channel.
Barbershops lead value generation today; online retailers are climbing the fastest as direct-to-consumer platforms consolidate discovery.
Packaging Type:
Supply concentration and sustainability certification access differentiate format selection.
- Bottles:Glass or PET containers for liquid oils and washes with dropper or pump dispensing. California SB 574 compliance timelines are forcing reformulation cycles that compress launch windows for fragrance-intensive bottled products.
- Jars:Wide-mouth containers for semi-solid balms enabling finger-application. Waterless formulation convergence favors jars for solid balm formats that reduce shipping weights.
- Tubes:Squeeze containers for conditioners and washes targeting travel and gym use. Biodegradability mandates under the EU Green Deal are accelerating tube material innovation.
- Sachets:Single-use pouches for trial sizes and travel convenience. Argan supply concentration from Moroccan cooperative-dependent sourcing creates price volatility affecting sachet unit economics.
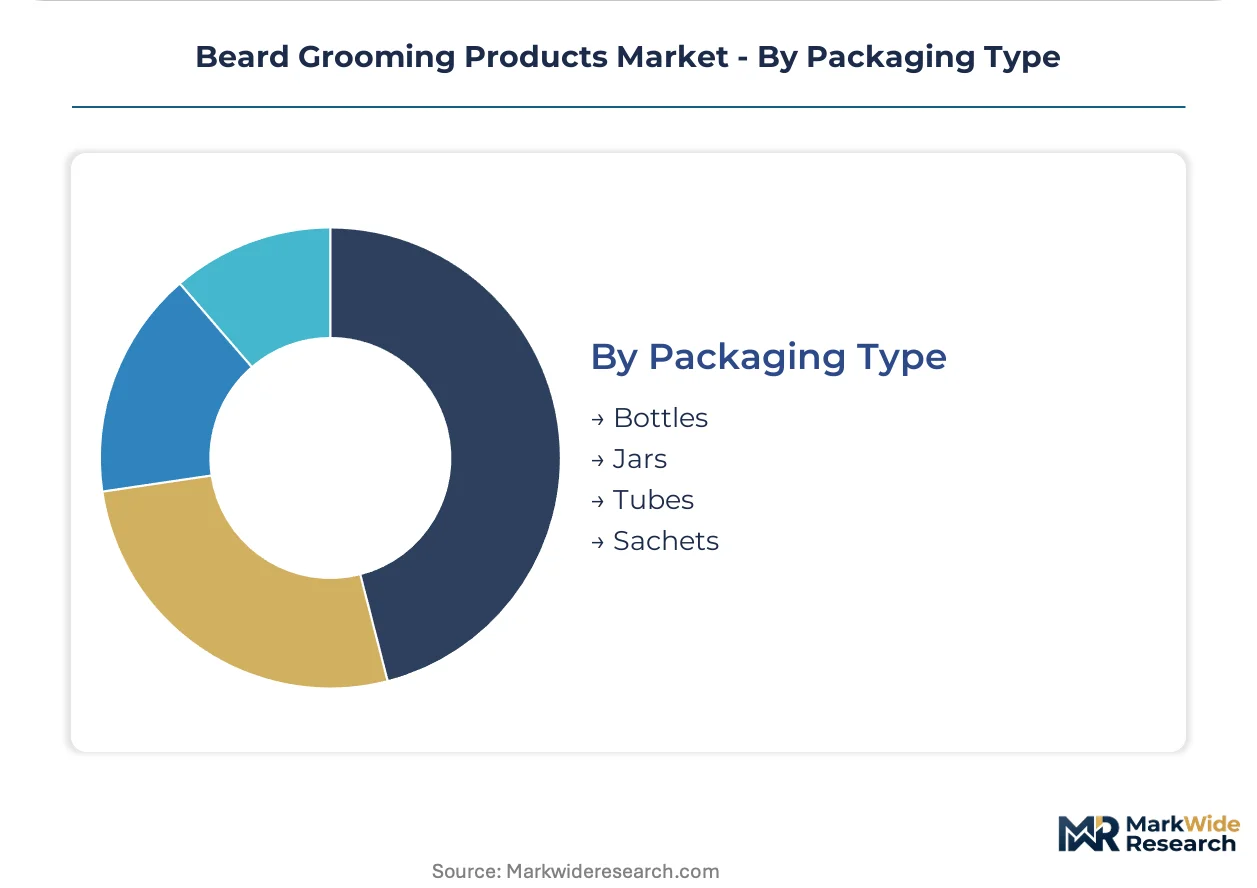
Bottles dominate current shipment volumes; jars are expanding most quickly through solid format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brooklyn and Austin anchor the premium beard oil manufacturing cluster, with direct-to-consumer platforms displacing traditional retail discovery across urban metro concentrations. The United States concentrates subscription model innovation, while European regulatory frameworks accelerate natural ingredient disclosure mandates. Industrial activity clusters around licensed barbershop networks and professional grooming establishments in specific metro zones.
United States
Urban metro clusters in Texas and California drive professional salon channel expansion through recurring revenue backbar replenishment programs. FDA cosmetic labeling enforcement elevates compliance costs for cross-border brand expansions into direct-to-consumer channels. Brooklyn and Austin manufacturers concentrate production of lipid-based formulations combining jojoba and squalane for premium positioning.
Germany
EU REACH fragrance restrictions accelerate natural essential oil adoption in premium beard oil formulations across German metros. The EU Green Deal mandates biodegradability disclosure requirements that favor waterless balm formats. Berlin and Hamburg anchor formulation chemistry innovation bridging natural ingredient stability with shelf-life performance requirements.
France
Paris and Lyon concentrate demand for clean-label product economics as plant-derived carrier oils replace petroleum-based mineral oils. ANSM oversight of cosmetic safety claims elevates formulation standards for cross-border distribution. French metros show accelerating preference for solid balm formats that satisfy EU Green Deal sustainability certification requirements.
United Kingdom
London anchors direct-to-consumer platform consolidation for premium oil and balm purchases through subscription discovery models. Post-Brexit regulatory divergence from EU REACH frameworks creates parallel compliance requirements for fragrance ingredient disclosure. UK barbershop professionalization expands private-label retail SKU development in licensed grooming establishments.
Canada
Health Canada PMRA oversight of cosmetic product safety shapes formulation roadmaps for brands seeking North American market access. Toronto and Vancouver concentrate urban demand for dermatologist-tested masstige-tier products distributed through specialty retail channels. Canadian consumers extend professional conditioning treatments into at-home maintenance routines through subscription replenishment models.
Beard Grooming Products Market Key Industry Players
Portfolio diversification dominates the current landscape as established grooming brands extend into adjacent beard care categories. The vendor base organizes around three strategic tiers: heritage craft specialists leveraging authenticity positioning, direct-to-consumer platforms controlling margin through subscription economics, and masstige-tier players distributed through specialty retail channels. Two competitive moves define current dynamics: backward integration into captive ingredient sourcing for supply security, and professional salon channel partnerships that lock in recurring backbar replenishment contracts.
Within the heritage craft tier, Honest Amish anchors market position through Amish-made authenticity claims and traditional formulation approaches. Beardbrand exemplifies the direct-to-consumer archetype with platform-controlled distribution sustaining premium margins across oils and balms. Jack Black occupies the masstige-tier position with dermatologist-tested formulations reaching consumers through Sephora and Ulta channel presence.
| Leading Market Players |
|---|
| Scotch Porter |
| Viking Revolution |
| Beardbrand |
| Cremo Styling |
| Wild Willies |
| Honest Amish |
| Beardo |
| Jack Black |
| The Art of Shaving |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between EU REACH-compliant natural formulations and conventional synthetic alternatives manifests in both margin structures and raw material procurement hierarchies. Premium positioning commands ingredient transparency premiums through Moroccan argan cooperative networks while standard-tier products face margin compression from private-label substitution.
Pricing Analysis
Input-cost pass-through from argan and jojoba feedstock volatility shapes three-tier pricing stratification across premium, standard, and economy levels. Price differentiation rests on certification tier—EU REACH compliance versus conventional formulation—and volume scale through subscription commitment. Pricing pressure intensifies in the masstige tier as California SB 574 disclosure mandates elevate packaging and reformulation costs. Direct-to-consumer subscribers demonstrate lowest price sensitivity; mass retail purchasers in standard-tier washes show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Moroccan cooperative-dependent argan sourcing that concentrates premium feedstock procurement. Geographic supply concentration spans Morocco for argan, the United States for biotechnology-derived squalane, and France for essential oil distillation. Raw material dependencies encompass plant-derived carrier oils, beeswax alternatives, and natural fragrance compounds. Regulatory restriction risk from EU REACH fragrance limitations threatens formulation continuity. Distribution runs through direct-to-consumer platforms, licensed barbershop backbar networks, and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal biodegradability mandates in Germany and France create premium positioning opportunities unavailable in less regulated North American jurisdictions.
For Market Incumbents: Anticipate private-label substitution pressure in standard-tier washes by deepening backward integration into captive squalane fermentation capacity. Lock in recurring revenue through barbershop backbar replenishment contracts in Texas and California metro clusters. Certification investment in EU REACH compliance creates defensive moats against cross-border entrants facing dual formulation requirements.
For New Entrants and Emerging Players: Biotechnology-derived squalane from sugarcane fermentation offers technology-first wedge positioning that bypasses agricultural commodity volatility plaguing incumbent supply chains. Target waterless solid balm formats in German and French metros where EU Green Deal disclosure mandates accelerate clean-label preference. Deploy subscription-first go-to-market architecture to compress customer acquisition costs against retail-dependent incumbents.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemistry expertise bridges natural ingredient stability with shelf-life performance requirements. Long-term viability favors vertically integrated platforms controlling ingredient sourcing and direct-to-consumer distribution. Acquisition target archetype: regional barbershop chains with private-label development capability. Watch biotechnology feedstock cost curves as inflection signal for margin structure transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Squalane Fermentation | Brooklyn and Austin manufacturers bypass Moroccan argan price volatility through captive biotechnology feedstock. |
| Barbershop Channel Partnership Expansion | Licensed grooming establishments in Texas and California anchor recurring backbar replenishment revenue streams. |
| EU REACH Compliance Certification | Natural essential oil adoption satisfies fragrance restrictions while capturing premium positioning in German metros. |
| Waterless Solid Balm Format Launch | Reduced shipping weights unlock EU Green Deal sustainability certification access in Paris and Lyon. |
| Direct-to-Consumer Platform Migration | Subscription economics displace mass retail discovery while sustaining margin control across oil and balm portfolios. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at heritage craft specialists, category buyers at Sephora and Ulta, procurement leads at Moroccan argan cooperatives, and formulation chemists at Brooklyn and Austin manufacturers with secondary validation. Secondary sources encompassed FDA cosmetic labeling guidance, EU REACH substance restrictions, customs records for carrier oil imports, and Nielsen retail audit data for grooming category performance. Bottom-up SKU-level modeling and top-down category sizing triangulated volume and value estimates.
Historical reference periods anchored the projection horizon through trend extrapolation and driver elasticity modeling across product type, application ritual, end-user channel, and packaging format segmentation dimensions. CAGRs derived from segment-level growth rate synthesis and cross-referencing against macro grooming expenditure patterns. Forecast inputs incorporated subscription model penetration curves and regulatory compliance cost trajectories.
The model holds under stable EU regulatory frameworks and consistent biotechnology feedstock scaling; deviation in Moroccan argan harvest yields or California disclosure timeline acceleration would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Cosmetic Palettes Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Nail Lamps Market