
 Basket Granulator Extruder Market | 2026-2036
Basket Granulator Extruder Market Size, Share, and Industry Trends Forecast 2026-2036
Basket Granulator Extruder Market Insights
Multi-source procurement for precision-engineered components is recalibrating how buyers evaluate basket granulator extruder suppliers. Hosokawa Micron Powder Systems leverages its micronization heritage to anchor premium positioning in North American pharmaceutical installations. Changzhou Hywell Machinery Co., Ltd. dominates Asian supply chains through integrated fabrication capabilities that shorten lead times for custom basket designs.
A basket granulator extruder employs a rotating perforated basket to force wet or plasticized material through precision apertures, forming uniform extrudates typically ranging from 0.5 mm to 3.0 mm in diameter for subsequent spheronization or drying. Pelletizing technology leads equipment value pools due to sustained demand for controlled-release oral dosage forms, while coating integration represents the fastest-growing configuration as manufacturers seek combined-process footprints. Pharmaceutical application margins exceed those in food processing, though chemicals and plastics provide volume stability for standardized basket geometries.
FDA 21 CFR Part 211 and EMA GMP Annex 15 shape equipment qualification protocols, compelling vendors to supply exhaustive documentation packages that extend sales cycles but protect installed-base revenue. ISO 9001 and ASME BPE standards further segment the supply base, favoring manufacturers with certified quality management systems. Stakeholders must weigh containment performance against cleanability validation as regulatory scrutiny on cross-contamination tightens across multiple jurisdictions.
Market Dynamics
Containment-capable basket granulator extruder designs are displacing legacy open-system configurations as pharmaceutical manufacturers face intensified regulatory scrutiny on cross-contamination risks and operator exposure limits.
Growth Catalysts
- EMA GMP Annex 15:European pharmaceutical facilities must demonstrate validated cleaning protocols, forcing equipment upgrades toward documented containment performance.
- Controlled-release oral dosage expansion:Pelletizing demand from contract manufacturing organizations is pulling precision basket extrusion capacity into multi-product facilities.
- China's oral solid dosage capacity buildout:Domestic pharmaceutical producers are localizing basket granulator procurement to shorten qualification timelines for export markets.
Market Restraints
- Stainless steel alloy volatility:Basket fabrication depends on 316L and specialty duplex grades subject to nickel and molybdenum price swings that compress equipment margins.
- Perforation machining concentration:Precision aperture drilling for pharmaceutical-grade baskets clusters with German and Swiss machine tool suppliers, creating single-source vulnerability.
- Wet granulation substitution:Dry granulation roller compactors are capturing scale-up batches where moisture sensitivity eliminates extrusion steps.
Strategic Opportunities
- India's CDMO expansion:Domestic contract development and manufacturing organizations are qualifying basket extruders for US FDA and EMA dual-inspection readiness.
- Continuous processing integration:Real-time release testing protocols are creating demand for basket extruders with PAT sensor ports and automated discharge.
- CE marking and REACH alignment:Equipment vendors certifying to both frameworks can access European chemical and food applications with reduced requalification burden.
Industry Challenges
- Containment validation expertise scarcity:Qualified engineers capable of executing SMEPAC testing and OEL band verification are concentrated with specialized consultancies.
- Legacy DCS integration friction:Modern basket extruders with advanced HMI must interface with 1990s-era distributed control systems in established pharmaceutical plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basket Granulator Extruder Market |
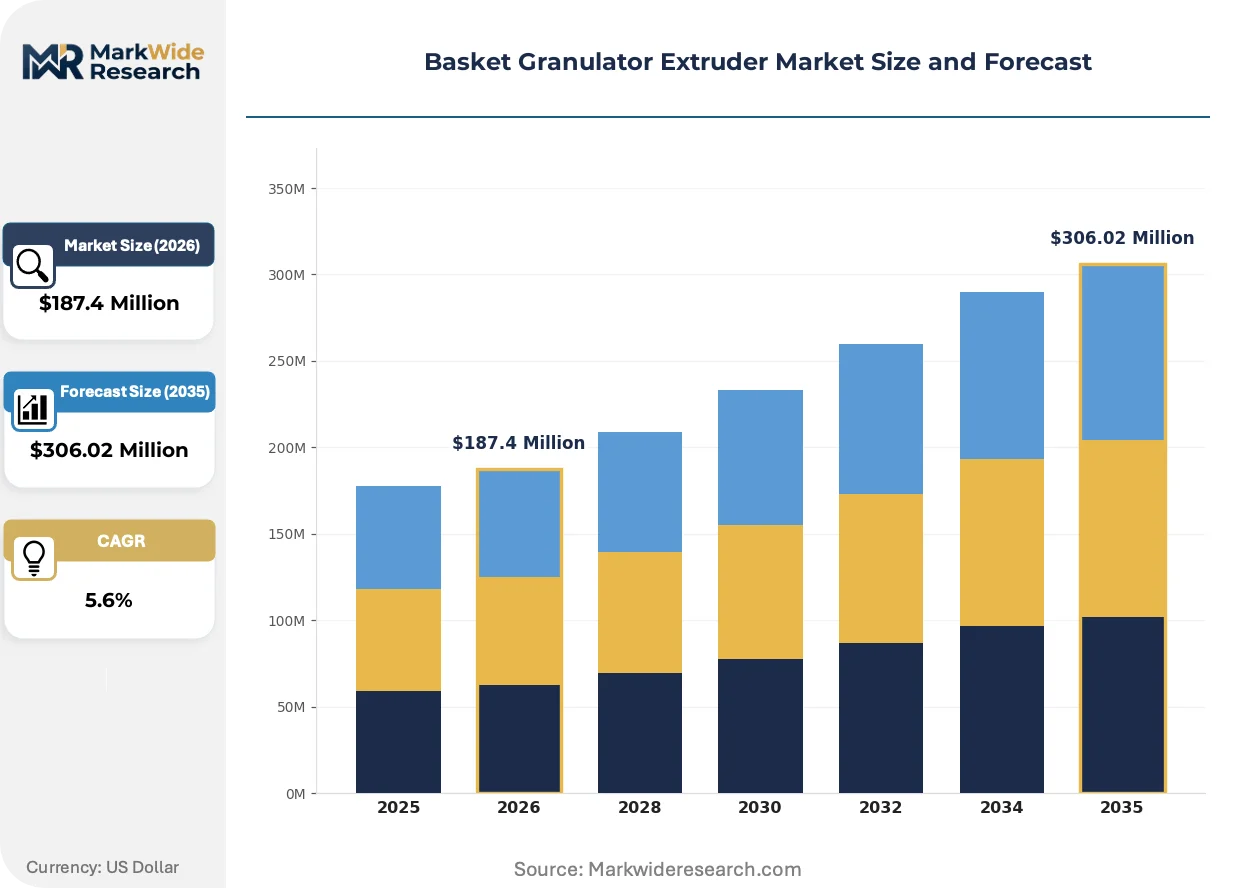
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $306.02 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pelletizing, Mixing, Coating, Drying Application: Pharmaceuticals, Chemicals, Food Processing, Plastics End User: Manufacturers, Laboratories, Research Institutions, Contract Manufacturers Distribution Channel: Direct Sales, Wholesalers, Online Retailers, Distributors |
| Companies Covered | Higao Tech, Umang Pharmatech, Hosokawa Micron Powder Systems, Changzhou Hywell Machinery Co., Ltd., SB Panchal & Company, LCI Corporation, Junzhuo Machinery, Jiangyin Aupu Machinery Co., Ltd., Hywell Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basket Granulator Extruder Market Trends and Innovations
Active substitution of mechanical drive systems with servo-electric architectures is compressing batch-to-batch variability while enabling recipe-driven changeover automation.
Electromechanical torque-controlled basket drives are absorbing the precision gap between pneumatic and hydraulic alternatives in high-shear wet extrusion applications. Mid-scale pharmaceutical manufacturers are adopting these systems to reduce utility infrastructure demands. The technology is absorbing market share from conventional variable-frequency motor arrangements by eliminating gearbox backlash and enabling direct torque measurement for process analytical technology integration.
REACH substance restrictions on chromium(VI) plating are forcing basket manufacturers toward PVD coating alternatives for wear-resistant aperture surfaces. Equipment suppliers must revalidate surface finish specifications with pharmaceutical customers who previously accepted hexavalent chrome passivation. German and Swiss component fabricators are responding fastest, establishing qualified PVD supply chains before sunset dates tighten.
Buyers are unbundling after-sales service contracts from initial equipment purchases, driving standalone qualification and maintenance revenue pools. Large pharmaceutical manufacturers are insourcing routine maintenance while retaining vendor relationships for specialist containment integrity testing. This pattern is most visible in United States facilities where total cost of ownership modeling dominates capital approval processes.
Basket Granulator Extruder Market Segmentation
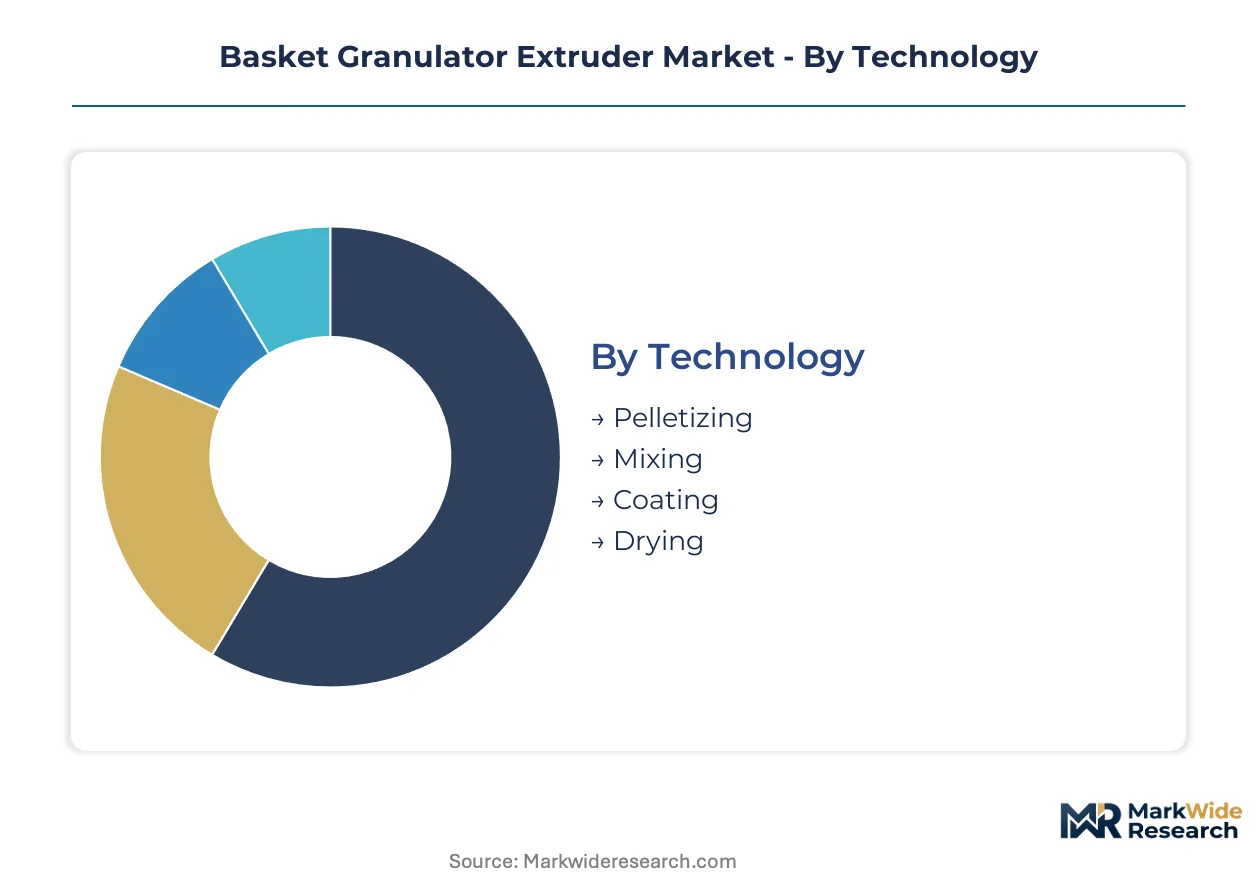
Basket granulator extruder procurement patterns diverge sharply between integrated process lines and standalone installations, with technology choices cascading through application requirements and channel economics. Understanding these segment boundaries clarifies where equipment vendors must anchor qualification documentation versus where standard catalog configurations suffice.
Technology:
Pelletizing and coating systems dominate integrated pharmaceutical lines, while mixing and drying modules serve both standalone and embedded deployments across multiple sectors.
- Pelletizing:Employs precision perforated baskets to extrude wet mass into uniform cylinders for subsequent spheronization, with aperture diameters calibrated to 0.5–3.0 mm for controlled-release oral dosage manufacturing. Demand clusters with contract development and manufacturing organizations in Germany and the United States as multi-product facilities expand pellet capacity for FDA and EMA dual-inspection readiness.
- Coating:Integrates extrusion with functional film application in combined-process footprints, reducing material handling and contamination exposure. The fastest expansion trajectory in this category stems from pharmaceutical manufacturers consolidating unit operations to meet containment validation requirements under EMA GMP Annex 15.
- Mixing:Combines high-shear wet massing with basket extrusion in single-vessel configurations for batch sizes below 500 kg. Food processors in Switzerland leverage these systems for rapid recipe changeover in nutritional supplement manufacturing.
- Drying:Pairs extrusion with fluid bed or vacuum drying modules for moisture-sensitive APIs, with stainless steel 316L basket construction mandatory for corrosion resistance. Chemical producers in Japan adopt these configurations for catalyst pellet production requiring precise residual moisture control.
Volume placements concentrate in Pelletizing; the faster expansion belongs to Coating.
Application:
Margin structures stratify sharply across applications, with pharmaceutical qualification burdens creating pricing premiums that subsidize standardized equipment for chemicals and plastics.
- Pharmaceuticals:Oral solid dosage manufacturing commands the highest equipment margins due to FDA 21 CFR Part 211 and EMA GMP Annex 15 documentation requirements, containment validation protocols, and SMEPAC testing obligations. Basket geometries here require surface finishes below 0.4 µm Ra with full material traceability.
- Chemicals:Catalyst and adsorbent pellet production tolerates wider dimensional tolerances, with 316L or duplex stainless baskets selected based on corrosive process media. German chemical clusters drive demand for explosion-proof electrical configurations meeting ATEX directives.
- Food Processing:Nutraceutical and functional food applications require FDA-compliant contact surfaces with clean-in-place validation, though without pharmaceutical-grade containment documentation. Swiss and Italian equipment suppliers dominate this segment through integrated fabrication capabilities.
- Plastics:Masterbatch and additive compounding utilizes standardized basket geometries with hardened tool steel apertures for abrasive filled polymers. Chinese domestic manufacturers capture volume through shortened lead times for custom perforation patterns.
Pharmaceuticals anchor revenue concentration; Food Processing is climbing the fastest as clean-label delivery formats expand.
End User:
Procurement authority and technical specification depth vary dramatically across end user types, with contract manufacturers demanding the most exhaustive vendor documentation packages.
- Manufacturers:Vertically integrated pharmaceutical and chemical producers with in-house engineering teams capable of executing installation qualification and operational qualification protocols independently. These buyers unbundle after-sales service contracts to optimize total cost of ownership.
- Laboratories:R&D and pilot-scale facilities requiring rapid scale-up pathways from 5 kg to 50 kg batch sizes, with basket extruders selected for geometric similarity to commercial-scale units. Swiss and German academic consortia drive demand for portable qualification documentation.
- Research Institutions:Public-sector formulation development centers with grant-funded equipment acquisition cycles and extended vendor evaluation timelines. These users prioritize equipment with published peer-reviewed validation studies.
- Contract Manufacturers:CDMOs and CMOs serving multiple sponsor clients simultaneously, requiring basket extruders with documented containment performance across OEL bands and rapid changeover automation. India's domestic CDMO expansion is pulling significant capacity into this segment.
Contract Manufacturers absorb the steepest expansion trajectory; Manufacturers retain the largest installed base.
Distribution Channel:
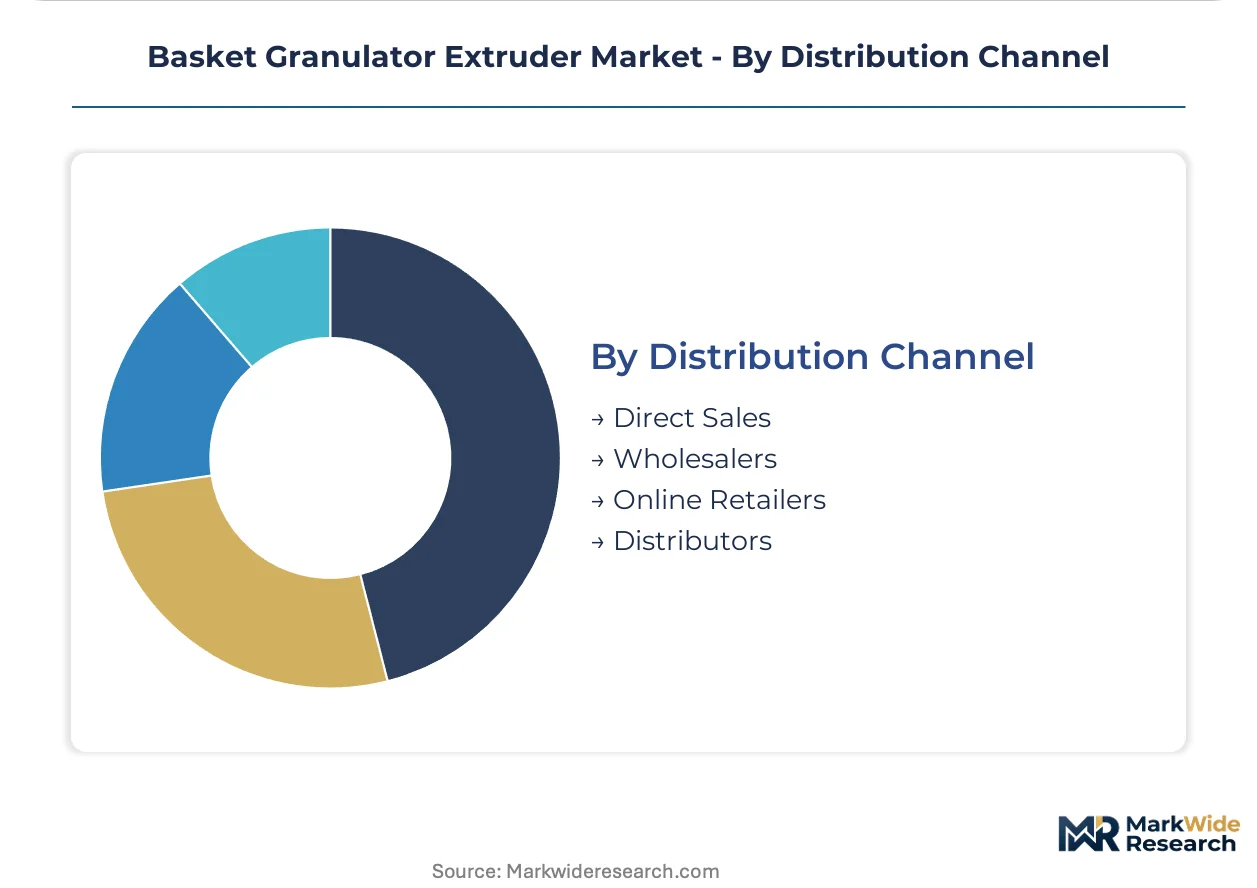
Channel selection correlates directly with equipment complexity and qualification burden, with direct relationships mandatory for pharmaceutical-grade installations.
- Direct Sales:Vendor field engineers execute factory acceptance testing and site acceptance testing for pharmaceutical and high-containment chemical applications. Hosokawa Micron Powder Systems and Changzhou Hywell Machinery anchor this channel through dedicated qualification teams.
- Wholesalers:Inventory-carrying intermediaries serving standardized food processing and plastics applications with catalog configurations and limited customization. European wholesalers concentrate in Germany and the Netherlands.
- Online Retailers:Digital procurement platforms for spare parts, consumable baskets, and replacement perforated cylinders with documented material certifications. These channels expand most quickly for aftermarket revenue pools.
- Distributors:Territory-exclusive representatives providing local language technical support and regulatory navigation, particularly critical in Brazil and Saudi Arabia where ANVISA and SFDA registration requirements demand specialized expertise.
Direct Sales commands the revenue concentration; Online Retailers are gaining share fastest in aftermarket segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturing and oral solid dosage capacity expansion concentrate demand across Germany, China, the United States, India, and Japan. Each market presents distinct regulatory pathways and industrial cluster dynamics.
Germany
EMA GMP Annex 15 enforcement drives equipment upgrades toward validated containment designs in the Rhine-Main pharmaceutical cluster. German chemical producers in Ludwigshafen and Leverkusen demand ATEX-compliant configurations for catalyst pellet operations. Precision aperture machining capabilities concentrate in Baden-Württemberg and Bavaria.
China
Domestic pharmaceutical producers localize basket granulator procurement to accelerate qualification timelines for US FDA and EMA export inspections. NMPA alignment with ICH Q7 guidelines shapes documentation requirements for equipment vendors. Yangtze River Delta manufacturers in Jiangsu and Zhejiang provinces anchor precision fabrication capacity.
United States
FDA 21 CFR Part 211 compliance burdens extend sales cycles while protecting installed-base service revenue for qualified vendors. CDMOs in New Jersey and Massachusetts expand pelletizing capacity for controlled-release oral dosage forms. Total cost of ownership modeling dominates capital approval processes across Midwest pharmaceutical corridors.
India
Domestic CDMO expansion pulls basket extruder demand toward US FDA and EMA dual-inspection readiness. CDSCO manufacturing license requirements for export-oriented facilities drive documentation intensity. Hyderabad and Ahmedabad clusters concentrate contract development and manufacturing organization capacity.
Japan
PMDA GMP inspections emphasize cleaning validation and cross-contamination prevention in multi-product facilities. Pharmaceutical manufacturers in Osaka and Tokyo prefectures prioritize equipment with PAT sensor integration for real-time release testing. METI industrial technology subsidies support servo-electric drive adoption.
Basket Granulator Extruder Market Competitive Landscape
Containment validation documentation and qualification team deployment dominate the current landscape as primary competitive differentiators. The vendor base stratifies across three tiers: integrated multinational powder processing specialists, regional machinery fabricators with pharmaceutical certification depth, and standardized equipment producers serving chemicals and plastics. Strategic archetypes include documentation-heavy premium-positioned suppliers, lead-time-optimized Asian fabricators, and aftermarket-focused service providers. M&A activity and geographic expansion represent the dominant competitive moves as vendors seek qualified engineering talent and local regulatory expertise.
Within the multinational specialist tier, Hosokawa Micron Powder Systems exemplifies premium positioning through dedicated qualification teams serving North American pharmaceutical installations. Changzhou Hywell Machinery Co., Ltd. represents the Asian fabrication archetype with integrated manufacturing capabilities that compress delivery timelines for custom basket geometries. Umang Pharmatech occupies a position within the India-focused CDMO service layer, anchoring regional demand for dual-inspection-ready equipment documentation.
| Leading Market Players |
|---|
| Higao Tech |
| Umang Pharmatech |
| Hosokawa Micron Powder Systems |
| Changzhou Hywell Machinery Co., Ltd. |
| SB Panchal & Company |
| LCI Corporation |
| Junzhuo Machinery |
| Jiangyin Aupu Machinery Co., Ltd. |
| Hywell Machinery |
| Others |
Pricing and Supply Chain Analysis
Contract manufacturers in India and CDMOs across Europe concentrate procurement authority for pharmaceutical-grade basket granulator extruders, anchoring a pricing model that unbundles equipment from qualification services to optimize total cost of ownership. This buyer concentration forces vendors to compete on documentation depth and containment validation speed rather than hardware margins alone.
Pricing Analysis
Warranty and service bundling separates premium pharmaceutical installations from standardized chemical and plastics configurations, with large manufacturers increasingly unbundling after-sales contracts to insource routine maintenance. Three-tier pricing structure across premium containment-validated, standard GMP-compliant, and economy catalog equipment reflects certification grade and documentation burden. Pricing pressure stems from stainless steel alloy volatility compressing fabrication margins, particularly for 316L and duplex grades. Food processors and plastics compounders exhibit the highest price sensitivity, while pharmaceutical CDMOs prioritize qualification speed over unit cost.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle complex qualification requirements, while wholesalers and online retailers serve aftermarket spare parts demand. Precision aperture machining concentrates in Germany and Switzerland, with basket fabrication capacity anchored in China's Yangtze River Delta and Jiangsu province. Raw material flows draw from nickel and molybdenum suppliers subject to commodity price swings, with specialty steel mills in Japan and South Korea feeding component fabricators. Single-source vulnerability in perforation machining creates structural risk, as German and Swiss machine tool suppliers dominate pharmaceutical-grade aperture drilling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around documentation-heavy vendors as EMA GMP Annex 15 and FDA 21 CFR Part 211 compliance burdens force smaller fabricators toward niche chemical and plastics applications.
For Market Incumbents: Extend containment validation service capabilities to capture unbundled qualification revenue from manufacturers insourcing routine maintenance. Deepen backward integration into precision aperture machining through partnerships with Baden-Württemberg machine tool suppliers, reducing single-source exposure. Anchor installed-base protection through PAT sensor integration and automated discharge architectures that complicate competitive displacement. For New Entrants and Emerging Players: Enter via India's CDMO expansion corridor, where domestic contract manufacturers seek dual-inspection-ready equipment documentation for US FDA and EMA markets. Target food processing applications in Switzerland and Italy, where clean-label delivery format growth outpaces pharmaceutical qualification barriers. Lead with integrated fabrication capabilities that compress lead times for custom basket geometries, mirroring Changzhou Hywell's Asian supply chain model. For Investors and Strategic Acquirers: The window for entry favors documentation-capable mid-cap specialists with established containment validation protocols and qualified engineering teams. Long-term viability hinges on servo-electric drive technology adoption and REACH-compliant PVD coating supply chains. Watch for SMEPAC testing and OEL band verification expertise scarcity as the inflection signal forcing acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Containment Validation Service Expansion | Captures unbundled revenue from CDMOs facing EMA GMP Annex 15 documentation requirements. |
| Backward Integration into Precision Machining | Reduces single-source vulnerability in German and Swiss aperture drilling capacity. |
| Servo-Electric Drive Platform Development | Enables PAT sensor integration for real-time release testing protocols in Japan and US facilities. |
| REACH-Compliant PVD Coating Qualification | Secures surface finish specifications ahead of chromium(VI) plating sunset dates in Europe. |
| India CDMO Channel Establishment | Positions for dual-inspection readiness demand from Hyderabad and Ahmedabad manufacturing clusters. |
Research Methodology
Document review covered FDA 21 CFR Part 211 guidance documents, EMA GMP Annex 15 inspection reports, and REACH substance restriction timelines, complemented by interviews with pharmaceutical plant engineers, CDMO procurement directors, containment validation consultants, and aftermarket service managers. Secondary sources included SEC filings from powder processing equipment vendors, customs data on stainless steel alloy imports, and ISO 9001 certification registries. Bottom-up equipment shipment analysis triangulated against top-down pharmaceutical capacity expansion announcements.
Cross-referencing historical qualification timeline data against expert panel input on regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application sector, end user category, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and oral solid dosage capacity buildout trajectories, with specific inputs from NMPA alignment with ICH Q7 guidelines and METI industrial technology subsidy programs.
Revisions become necessary when REACH substance restriction timelines accelerate, stainless steel alloy price volatility exceeds historical bands, or dry granulation roller compactor substitution captures scale-up batches previously routed to extrusion. Forecasts reflect assumptions regarding regulatory enforcement consistency and pharmaceutical outsourcing trends. Periodic stress-testing of base assumptions against CDSCO manufacturing license issuance rates and PMDA inspection frequency is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Cannabis Packaging Equipment Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Blow Molding Tools Market