
 Strapping Equipment Market | 2026-2036
Strapping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Strapping Equipment Market Analytics
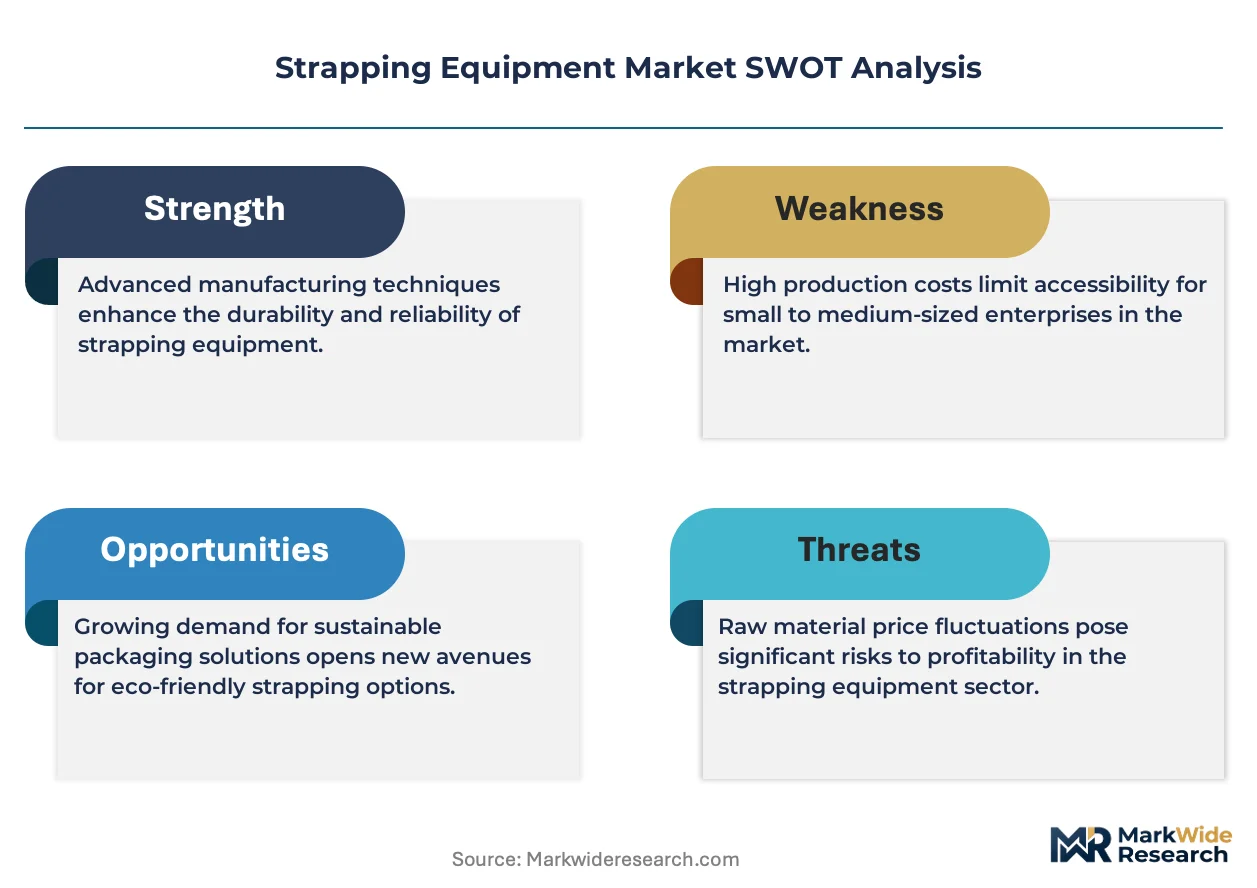
EU Green Deal packaging waste targets are decoupling strapping demand from virgin plastic intensity across European logistics corridors. Signode Industrial Group leverages its steel and polyester portfolio to serve heavy-industry palletizing requirements in Germany and the United States. FROMM Packaging Systems anchors its competitiveness in handheld and battery-powered strappers for construction and agricultural bundling. Mosca GmbH dominates automatic arch-type machines through precision tension-control engineering and dense service networks across Central Europe.
Strapping equipment encompasses mechanical and electromechanical systems that apply, tension, seal, and cut strap material around products, pallets, or loads, typically operating at tension forces from 50N to over 15,000N depending on strap grade and load specification. These systems secure goods for handling, storage, and transport across manufacturing and distribution environments. Automatic strapping systems command the premium equipment tier due to throughput requirements in beverage and corrugated packaging plants, while handheld strappers represent the fastest-expanding format driven by mobile fulfillment operations and last-mile logistics. Steel strap retains dominance in heavy-metal bundling and construction material shipping where elongation recovery and break strength exceed polymer capabilities.
OSHA machine guarding standards in the United States and CE marking requirements under the EU Machinery Directive shape equipment design, mandating two-hand operation, emergency stops, and interlocked access panels that add engineering cost but create compliance barriers for low-cost imports. Germany's KBA and France's ANSM do not regulate strapping equipment directly, though REACH chemical restrictions influence adhesive and coating formulations in strap manufacturing. Stakeholders must monitor whether extended producer responsibility frameworks expand to include strapping material take-back obligations, as this would reshape material economics toward closed-loop polyester recovery systems.
Market Dynamics
Automated fulfillment infrastructure is compressing equipment replacement cycles as e-commerce operators prioritize throughput density over capital longevity in warehouse design decisions.
Growth Catalysts
- EU Green Deal packaging directives:Mandatory recyclable content thresholds are accelerating polyester strap substitution for polypropylene in German automotive export corridors.
- Mobile fulfillment operations:Battery-powered handheld strappers are displacing manual tensioning tools in last-mile distribution centers handling variable load geometries.
- Steel strap demand:Heavy-metal bundling applications in construction material shipping maintain break-strength requirements that polymer grades cannot satisfy.
Market Restraints
- Steel price volatility:Raw material input fluctuations compress margin stability for manufacturers serving construction and heavy machinery verticals.
- CE marking compliance costs:EU Machinery Directive requirements for interlocked access panels and two-hand operation create engineering barriers for low-cost import competition.
- Polymer elongation limits:Technical performance ceilings in high-tension palletizing applications preserve steel's dominance despite weight and corrosion disadvantages.
Strategic Opportunities
- Closed-loop polyester recovery:Extended producer responsibility frameworks in France and Germany may mandate strapping material take-back obligations favoring recyclable strap architectures.
- Precision tension-control convergence:Integration of load-cell feedback with automatic arch-type machines enables adaptive sealing force for fragile corrugated packaging.
- Agricultural bundling expansion:Hay and silage compression operations in Eastern European markets remain underpenetrated by automated strapping relative to Western European adoption rates.
Industry Challenges
- Mechatronics skill scarcity:Maintenance of electromechanical tensioning systems requires technician competencies that outpace vocational training pipeline output in Central European manufacturing clusters.
- Legacy system integration friction:Retrofitting automatic strapping lines into existing conveyor infrastructure demands custom mechanical interfacing that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strapping Equipment Market |
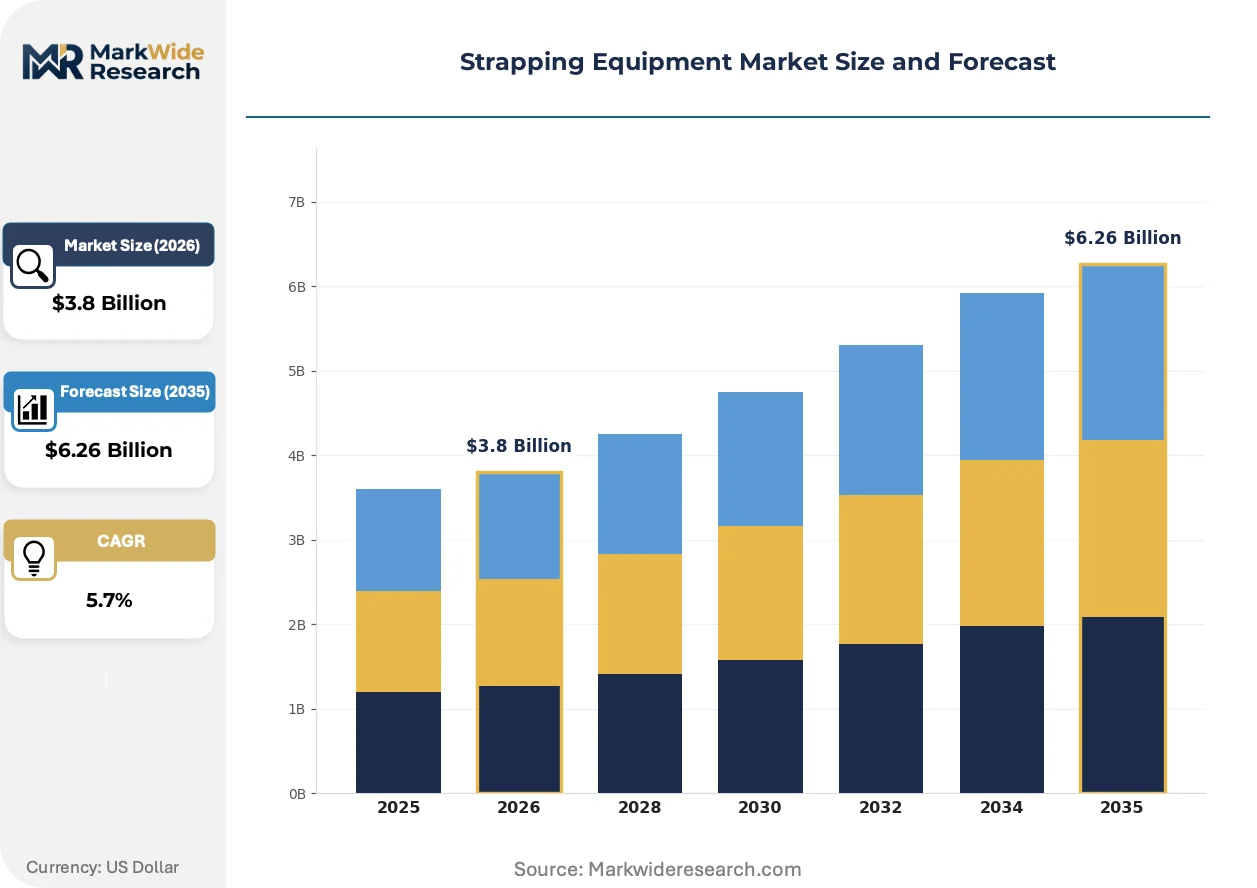
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Strapping, Automatic Strapping, Semi-Automatic Strapping, Handheld Strappers Material: Polypropylene, Polyester, Steel, Nylon End User: Healthcare, Electronics, Food & Beverage, Logistics Application: Packaging, Bundling, Palletizing, Shipping |
| Companies Covered | Signode Industrial Group, FROMM Packaging Systems, Mosca GmbH, StraPack Corp., Transpak Equipment Corp., Dynaric Inc., Samuel Strapping Systems, Polychem Corporation, M.J. Maillis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strapping Equipment Market Evolving Landscape
Intelligent tensioning systems are compressing the performance gap between steel and polymer straps while regulatory pressure on packaging circularity accelerates material substitution roadmaps.
Sensor-integrated strapping heads are unifying real-time tension monitoring with adaptive sealing algorithms. Beverage and corrugated packaging plants in Germany and the United States are retrofitting legacy arch-type machines with these modules to reduce strap breakage rates. This convergence is unifying quality control and equipment operation into single-operator oversight models, compressing labor requirements per line.
REACH chemical restrictions are reshaping adhesive formulations in polyester strap manufacturing. ECHA substance-of-very-high-concern listings are phasing out legacy coating chemistries used for strap surface treatment. Strap producers serving EU logistics corridors are reformulating with water-based alternatives that maintain friction coefficients for high-speed automatic feeding.
Equipment-as-a-service contracting is displacing capital purchase models in mid-scale fulfillment operations. Third-party logistics providers in the Netherlands and Belgium are bundling maintenance, strap supply, and throughput guarantees into per-unit pricing. This shift transfers obsolescence risk from warehouse operators to equipment vendors while locking in multi-year consumable commitments.
Strapping Equipment Market Segmentation
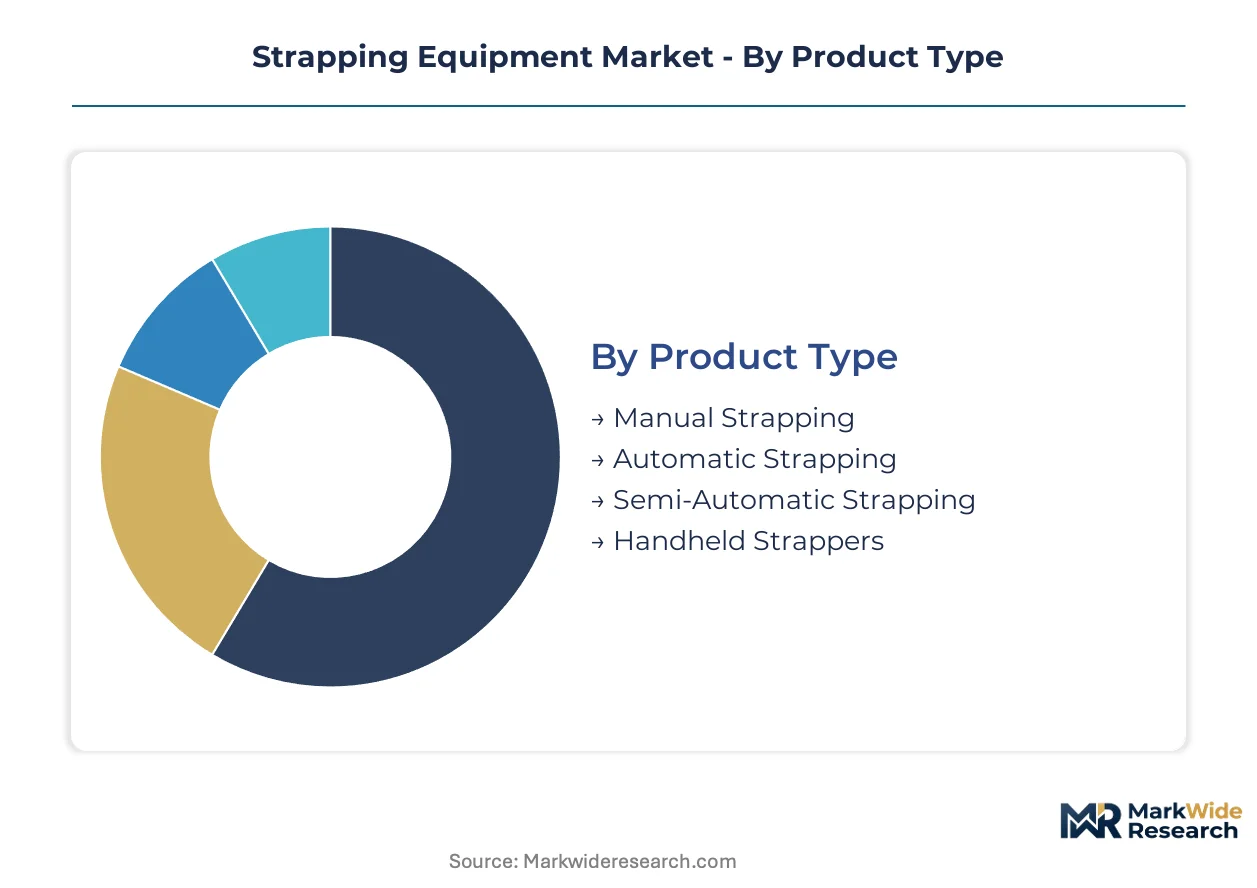
Strapping equipment segmentation reveals divergent margin profiles across automation tiers and material grades. Equipment format determines capital intensity and service attach rates, while material selection reflects load specification and regulatory pressure on recyclability.
Product Type:
Volume concentrates in entry-level manual formats, while premium capture belongs to integrated automatic systems serving high-throughput manufacturing.
- Automatic Strapping:Arch-type machines deploy electromechanical tensioning heads with programmable sealing force. Beverage bottling plants in Germany and corrugated packaging facilities in the United States deploy these systems for pallet throughput exceeding 40 units per hour. Capital replacement cycles compress as e-commerce fulfillment operators prioritize throughput density over equipment longevity.
- Handheld Strappers:Battery-powered units integrate brushless motors with lithium-ion cells delivering 2,000+ cycles per charge. Last-mile distribution centers handling variable load geometries drive fastest expansion, displacing manual tensioning tools in mobile fulfillment operations across Benelux logistics corridors.
- Manual Strapping:Entry-level tensioners and sealers serve small-scale agricultural bundling and construction material handling where capital constraints limit automation adoption.
- Semi-Automatic Strapping:Table-top machines bridge manual and fully automatic formats, finding placement in mid-scale warehousing operations with intermittent throughput requirements.
Today's leader: Automatic Strapping. Tomorrow's challenger: Handheld Strappers.
Material:
Steel commands break-strength applications where polymer elongation limits fail, while polyester gains regulatory tailwinds from EU packaging circularity mandates.
- Steel:High-tensile grades deliver 15,000N+ break strength with minimal elongation recovery. Heavy-metal bundling in construction material shipping and automotive coil wrapping maintain steel's dominance despite weight penalties and corrosion susceptibility. Raw material price volatility compresses margin stability for integrated producers.
- Polyester:Embossed and smooth-weave straps achieve 8,000N-12,000N tensile strength with superior weather resistance. German automotive export corridors accelerate substitution from polypropylene as EU Green Deal directives mandate recyclable content thresholds in packaging applications.
- Polypropylene:Lightweight extruded straps serve low-tension bundling in consumer goods distribution, facing displacement pressure from polyester in regulated European markets.
- Nylon:Specialty grades with high shock resistance find niche deployment in aerospace component securing and precision machinery transport where dynamic load absorption exceeds static strength requirements.
Steel retains the premium tier. Polyester climbs the fastest on regulatory momentum.
End User:
Logistics operators generate equipment volume through distributed fleet deployment, while food and beverage plants concentrate premium system sales.
- Logistics:Third-party warehousing and distribution operators deploy mixed equipment fleets across manual, semi-automatic, and handheld formats. Equipment-as-a-service contracting gains traction in Netherlands and Belgium, bundling maintenance and consumable supply into per-unit pricing.
- Food & Beverage:High-speed bottling and canning lines demand automatic arch-type machines with stainless steel construction for washdown compliance. Precision tension-control modules reduce strap breakage in fragile corrugated secondary packaging.
- Electronics:Cleanroom-compatible strapping systems with static-dissipative materials serve semiconductor and consumer electronics manufacturing, where particulate contamination risks mandate specialized equipment specifications.
- Healthcare:Pharmaceutical distribution centers deploy validated strapping systems with audit trail documentation for temperature-controlled supply chain compliance, though overall equipment scale remains limited relative to industrial verticals.
Logistics owns the volume base. Food & Beverage commands the margin premium.
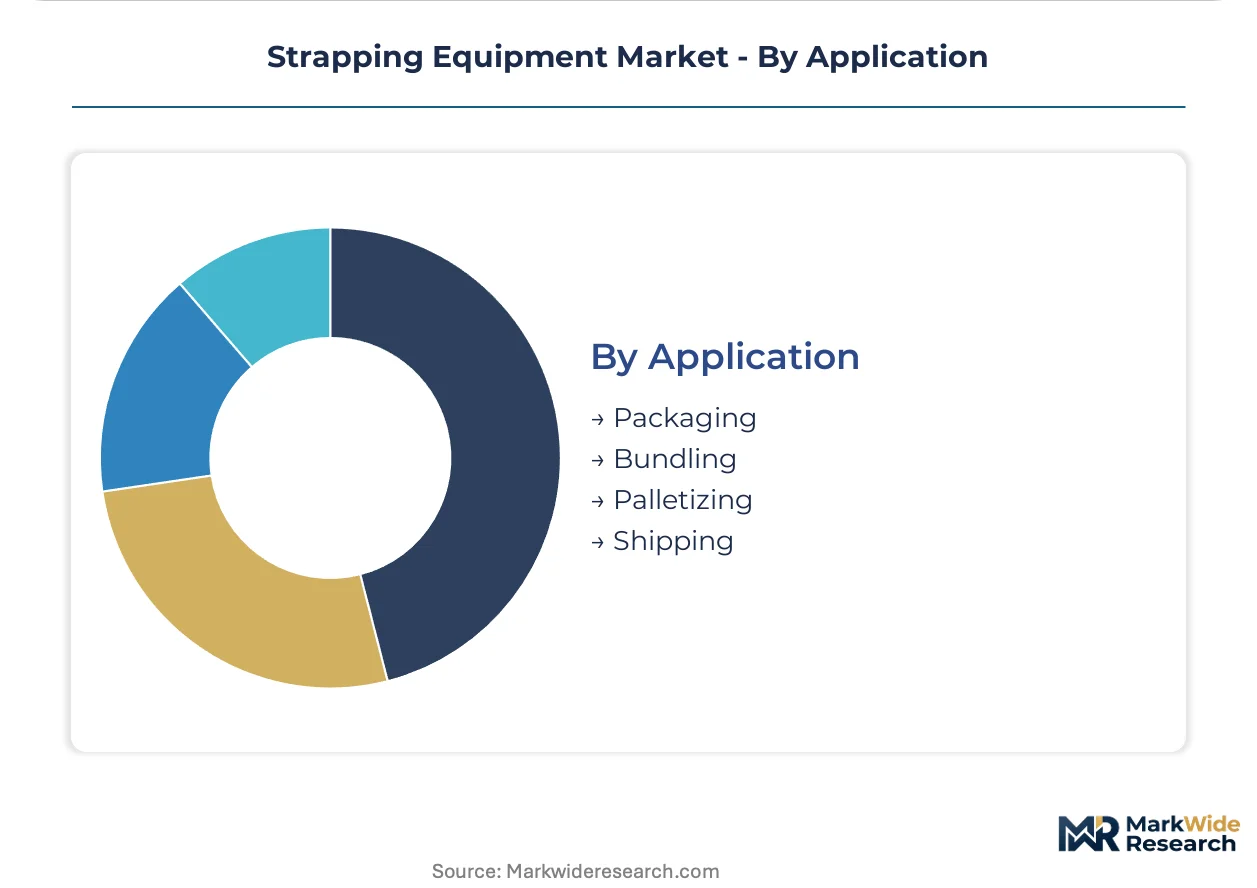
Application:
Palletizing absorbs the majority of automatic system deployment, while bundling applications sustain handheld tool demand across dispersed operations.
- Palletizing:Unit-load securing at production line termini requires consistent tension distribution across irregular stack geometries. Automatic strapping heads with load-cell feedback adapt sealing force to prevent product damage in corrugated and beverage applications.
- Bundling:Compression of hay, silage, and construction materials demands high-tension capacity across variable geometries. Eastern European agricultural markets remain underpenetrated by automated solutions relative to Western European adoption rates.
- Packaging:Primary and secondary package securing in consumer goods manufacturing employs semi-automatic and manual formats where throughput requirements permit operator-paced operation.
- Shipping:Container loading and dunnage securing utilize steel and heavy-grade polymer straps for load stabilization during intermodal transport, with tension specification varying by commodity density and voyage duration.
Palletizing anchors automatic equipment sales. Bundling offers the steepest expansion trajectory in agricultural automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strapping equipment manufacturing originated in post-war German industrial zones where steel-processing expertise converged with machinery engineering. Early automatic arch-type systems emerged from Stuttgart and Düsseldorf industrial clusters during the 1960s palletization boom.
Germany
Automotive export corridors through Stuttgart and Wolfsburg drive demand for high-throughput automatic systems bundling precision components. EU Green Deal packaging directives mandate recyclable polyester content thresholds that OEMs must satisfy for cross-border shipment compliance. The KBA regulates transport packaging safety standards that influence strapping tension specifications for heavy machinery exports.
United States
E-commerce fulfillment centers in Pennsylvania and Ohio deploy battery-powered handheld strappers for variable-load last-mile operations. OSHA machine guarding standards mandate two-hand operation and emergency stop integration that shape equipment design for domestic manufacturers. The Chicago-Milwaukee industrial corridor concentrates steel strap production serving construction material bundling across the Great Lakes region.
China
Export manufacturing zones in Guangdong and Jiangsu provinces absorb semi-automatic and manual formats for consumer goods containerization. GB standards for packaging machinery safety create technical barriers for European and Japanese equipment imports. The Yangtze River Delta logistics hub drives fleet deployment of handheld strappers across third-party warehousing operations serving East Asian trade routes.
Japan
Precision electronics manufacturing in the Nagoya-Toyota corridor requires cleanroom-compatible strapping systems with static-dissipative materials. METI industrial efficiency programs incentivize automation upgrades in small-to-mid-scale packaging operations. The Kansai region's pharmaceutical distribution network deploys validated systems with audit trail documentation for temperature-controlled supply chains.
Netherlands
Rotterdam-Europoort container handling operations sustain demand for heavy-grade steel and polymer straps in intermodal load stabilization. Equipment-as-a-service contracting models gain traction among third-party logistics providers bundling maintenance and consumable supply. The country's national packaging waste regulator enforces extended producer responsibility frameworks that may expand to strapping material take-back obligations.
Strapping Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the strapping equipment landscape. Integrated steel and polyester strap manufacturers maintain foundry-like control over material input costs, while specialized machinery engineers outsource component fabrication to concentrate on tension-control system development. The market structure fragments across three strategic archetypes: diversified industrial conglomerates with captive material production, precision machinery specialists with dense service networks, and regional fabricators serving price-sensitive agricultural and construction verticals. Competitive positioning depends on M&A activity consolidating regional service capabilities and strategic partnerships securing lithium-ion cell supply for handheld product lines.
Within the diversified industrial tier, Signode Industrial Group and Samuel Strapping Systems exemplify capital-intensive players with integrated steel production and machinery manufacturing capabilities. Among precision machinery specialists, Mosca GmbH occupies a position defined by German-engineered automatic arch-type systems and dense Central European service infrastructure. FROMM Packaging Systems represents the handheld and battery-powered segment, anchoring competitiveness in mobile fulfillment applications through portable format specialization.
| Leading Market Players |
|---|
| Signode Industrial Group |
| FROMM Packaging Systems |
| Mosca GmbH |
| StraPack Corp. |
| Transpak Equipment Corp. |
| Dynaric Inc. |
| Samuel Strapping Systems |
| Polychem Corporation |
| M.J. Maillis Group |
| Others |
Value Network & Pricing Analysis
Performance-tier divergence between CE-certified automatic arch-type machines and unbranded manual equipment manifests in pricing power that scales with service attach rates and captive strap supply contracts. German and Japanese OEMs command premium positioning through integrated polyester production and dense technician networks, while Chinese and Indian fabricators compete on unit economics for agricultural and construction verticals with minimal aftermarket bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked automatic systems with load-cell feedback from semi-automatic table-top units and entry-level manual tensioners. Price differentiation hinges on certification grade and after-sales service bundling, with EU Machinery Directive compliance adding engineering cost that filters low-cost imports from premium tiers. Cost compression in economy handheld segments is intensifying because lithium-ion cell supply competition from Chinese producers compresses powertrain margins. Third-party logistics operators in Benelux exhibit highest price sensitivity due to equipment-as-a-service contracting that transfers capital risk to vendors, while pharmaceutical distribution centers show least sensitivity given validation and audit trail requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for automatic arch-type systems in German automotive and US beverage corridors, while distributor networks serve fragmented agricultural and construction procurement across Eastern Europe and Southeast Asia. Geographic supply concentration centers on Germany for precision machinery engineering, China for lithium-ion cell and brushless motor components, and the United States for high-tensile steel strap production. Raw material dependencies rest on petrochemical feedstocks for polyester extrusion, iron ore and scrap metal for steel grades, and rare earth elements for permanent magnet motors in handheld units. Single-source vulnerability in semiconductor chips for sensor-integrated tensioning heads creates supply chain risk that equipment vendors are mitigating through dual-sourcing qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strapping equipment procurement arbitrage opportunities emerge between EU Green Deal compliance costs in Germany and unregulated manufacturing zones in Southeast Asia, where polyester strap production avoids extended producer responsibility fees.
For Market Incumbents: Deepen captive polyester recycling capabilities to preempt French and German extended producer responsibility mandates that threaten material economics for virgin-dependent producers. Consolidate regional service networks in Central European manufacturing clusters where mechatronics skill scarcity limits competitor technician deployment. Defend automatic equipment margins by integrating load-cell feedback modules that reduce strap breakage rates and lock in consumable supply contracts. For New Entrants and Emerging Players: The handheld strapper price-point gap between premium battery-powered units and economy manual tools creates entry space for mid-tier lithium-ion products with brushless motor reliability. Target Eastern European agricultural bundling markets where automated strapping penetration lags Western European adoption rates by a decade. Pursue private-label partnerships with third-party logistics providers in the Netherlands and Belgium seeking equipment-as-a-service flexibility without incumbent brand premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where dense service networks in Germany and Austria face technician pipeline constraints that limit organic expansion. Five-to-ten year viability favors precision machinery specialists with automatic arch-type expertise over diversified steel producers exposed to raw material volatility. Monitor EU packaging waste regulator announcements on strapping material take-back obligations as the inflection signal that would revalue closed-loop polyester recovery capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyester Recycling | Captive supply of EU Green Deal-compliant strap material insulates margin from virgin resin price swings. |
| Equipment-as-a-Service Contracting Expansion | Per-unit pricing bundles in Benelux transfer obsolescence risk while locking multi-year consumable commitments. |
| Sensor-Integrated Tensioning Module Launch | Adaptive sealing algorithms reduce breakage in German beverage and US corrugated packaging plants. |
| Regional Service Network Consolidation | Technician density in Stuttgart and Düsseldorf industrial clusters creates switching costs for automatic system buyers. |
| Agricultural Automation Partnership | Eastern European hay and silage compression operations remain underpenetrated by arch-type machine deployment. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and the Netherlands, with primary inputs from each market combining interviews with plant engineers, maintenance directors at beverage bottling facilities, procurement leads at third-party logistics providers, and aftermarket service heads at OEM distribution networks. Secondary validation draws from SEC 10-K filings of diversified industrial conglomerates, EU Machinery Directive compliance databases, ECHA REACH substance listings, and customs trade data on steel and polyester strap imports. Bottom-up equipment shipment tallies triangulate against top-down manufacturing value-added estimates across the analysis window.
Rate-of-change decomposition separates volume growth in automatic, semi-automatic, handheld, and manual formats from value migration between steel, polyester, polypropylene, and nylon material grades. Modeled segmentation spans automation tier, strap material, end-user vertical, and application type, with geographic regulatory clusters treated as distinct adoption environments. CAGRs derive from regression of historical shipment data against macro industrial production indices and e-commerce fulfillment capex disclosures. Industry-specific forecast inputs include EU packaging waste directive implementation timelines and lithium-ion cell cost curves from electric vehicle supply chain spillover.
Caveats apply where steel price volatility, REACH chemical restriction expansions, or CE marking enforcement intensity could materially shift the outlook for equipment margin structures and material substitution trajectories. Forecasts reflect documented assumptions on regulatory implementation pace and technology cost reduction slopes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Inflatable Void Fill System Market