
 LTFS Copy Software Market | 2026-2036
LTFS Copy Software Market Size, Share, and Industry Trends Forecast 2026-2036
LTFS Copy Software Market Foresight
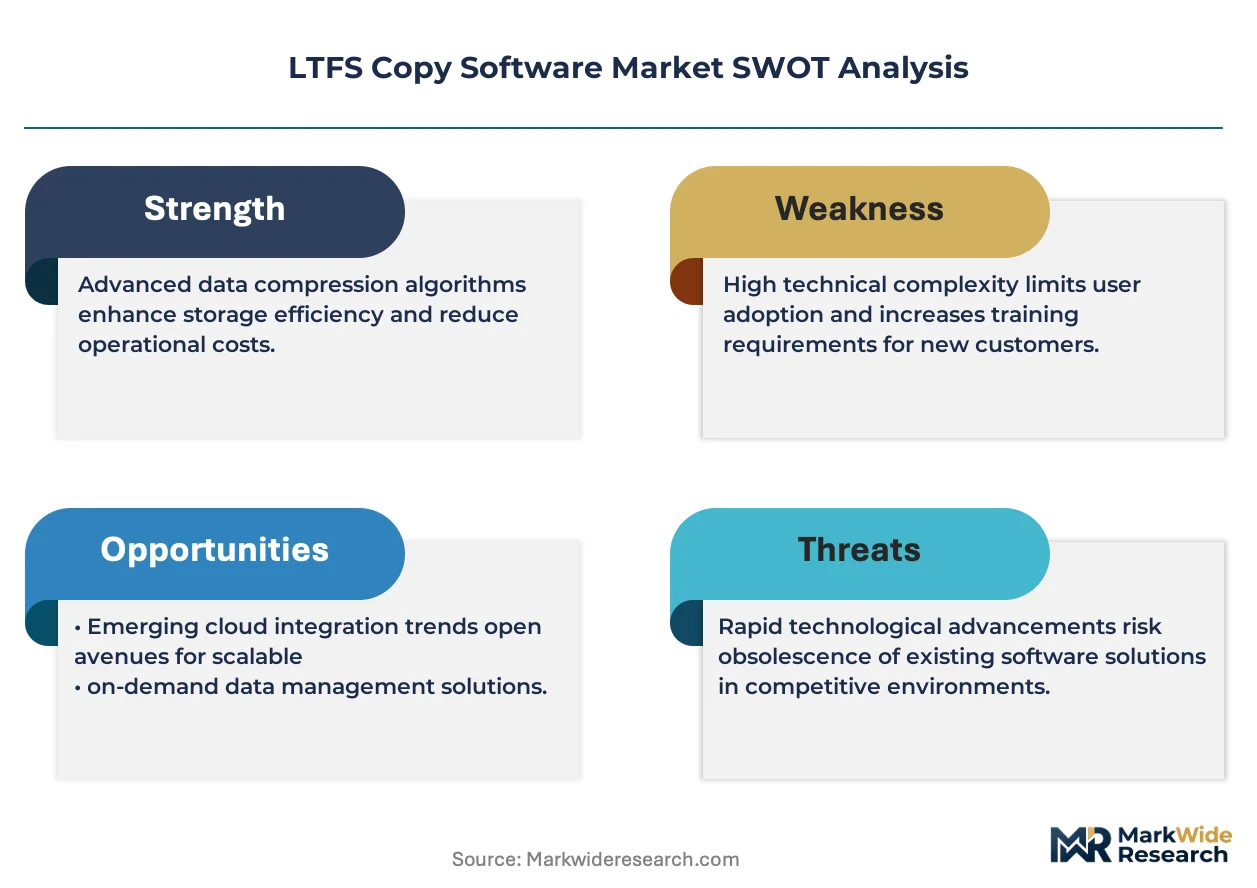
The capital-intensity divergence between enterprise-grade platform vendors and point-solution specialists is redrawing competitive boundaries in LTFS copy software. IBM leverages its tape hardware heritage to anchor integrated LTFS workflows across mainframe and storage environments. Veritas Technologies competes through broad data protection platform coverage that incorporates LTFS as one archive tier among many. Quantum Corporation specializes in high-performance tape automation, sustaining its position through deep vertical expertise in media and entertainment workflows.
LTFS Copy Software refers to applications that implement the Linear Tape File System format to enable drag-and-drop file operations on LTO tape cartridges without requiring proprietary backup software, typically supporting WORM capabilities, multi-file partition structures, and cross-platform readability between Linux, Windows, and macOS systems. Its primary purpose is to reduce tape management complexity while preserving air-gapped, offline data copies for compliance and disaster recovery. The integrated solution segment dominates current procurement as enterprises prefer LTFS embedded within broader data management platforms rather than standalone utilities. Cloud-based solutions represent the fastest-expanding category, driven by hybrid archive architectures that tier cold data between on-premises tape and cloud object storage. The LTFS Standard technology layer remains the foundational requirement, though API integrations are gaining traction as organizations demand programmatic control over tape libraries within automated DevOps pipelines.
The Federal Information Security Management Act and SEC recordkeeping rules in the United States impose retention obligations that sustain tape archive demand, while the EU GDPR's data portability and erasure requirements shape how LTFS copy software handles indexed metadata and searchability. ISO 27001 and IEC 27040 standards further influence product development around encryption and access control for offline storage media. Stakeholders must evaluate whether emerging quantum-resistant encryption standards will necessitate firmware or software updates across installed tape libraries before regulatory mandates crystallize.
Market Dynamics
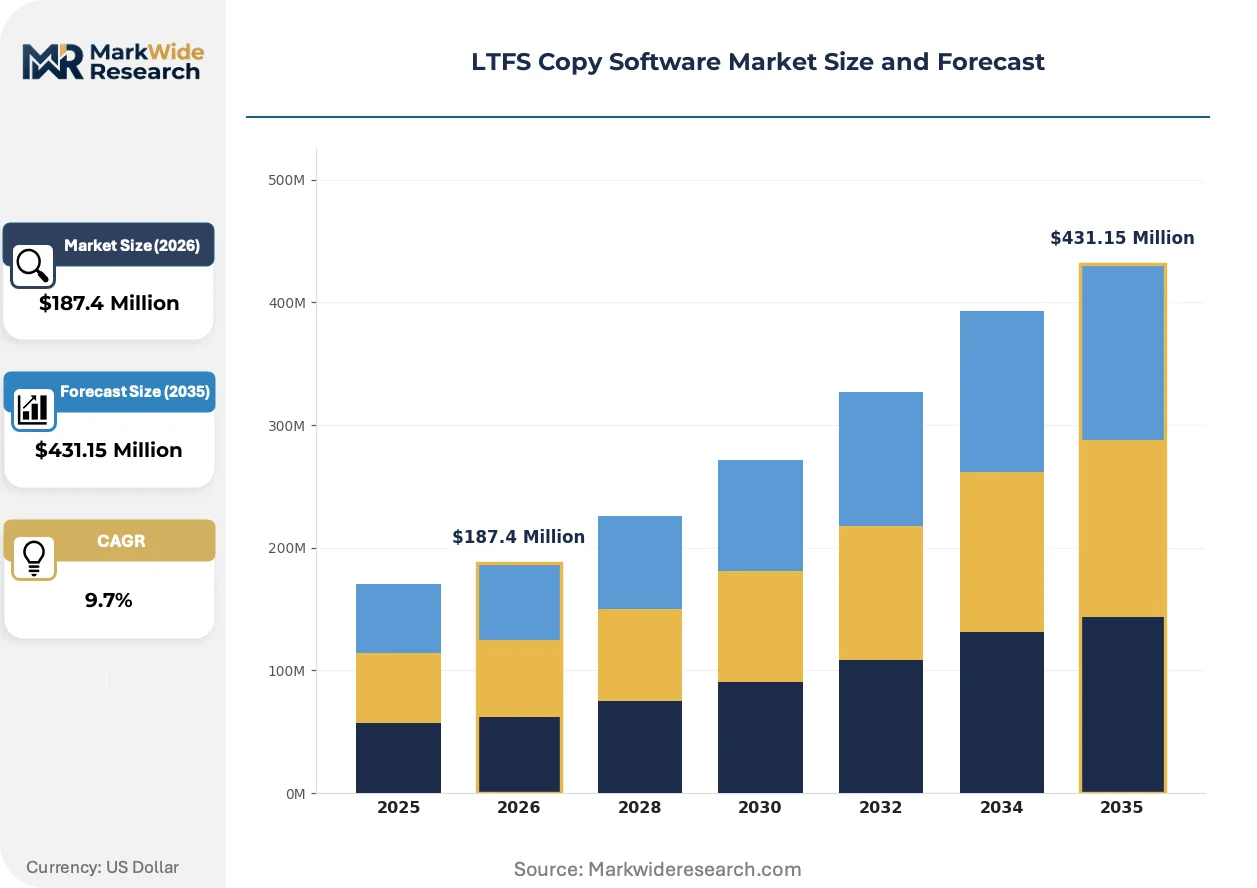
The transition from proprietary backup architectures to open-standard LTFS 2.0 workflows is restructuring procurement priorities across enterprise storage environments. This specification shift reduces vendor lock-in while demanding new software layers for cross-platform tape management.
Growth Catalysts
- Federal Retention Mandates:SEC recordkeeping rules and FISMA compliance obligations in the United States sustain capital flows into air-gapped tape infrastructure for long-term data preservation.
- Media Workload Expansion:Long-form video production pipelines in streaming content operations require petabyte-scale archives that LTFS simplifies through native file system accessibility.
- LTO-9 Density Gains:The 18TB native capacity per cartridge reduces physical media counts and floor space requirements for hyperscale data center operators managing cold storage tiers.
Market Restraints
- Tape Hardware Concentration:LTO drive manufacturing consolidates among three licensed producers, creating supply vulnerability for enterprises dependent on specific form factors.
- Skill Base Erosion:Magnetic storage expertise attrition in IT departments lengthens deployment timelines and elevates professional services dependency.
- Flash Cost Compression:QLC NAND price declines below archival tape total-cost-of-ownership thresholds for retention periods under seven years.
Strategic Opportunities
- Hybrid Cloud Orchestration:API-native LTFS controllers enable automated tiering between on-premises tape libraries and cloud object storage for variable retrieval latency requirements.
- Quantum-Resistant Encryption:NIST post-quantum cryptographic standards create upgrade cycles for firmware and key management systems across installed tape libraries.
- DevOps Pipeline Integration:Infrastructure-as-code templates for tape provisioning address gaps in automated data lifecycle management for regulated industries.
Industry Challenges
- Metadata Index Latency:LTFS partition indexing performance degrades at scale, complicating sub-minute retrieval service level agreements for active archive workloads.
- Cross-Platform Validation:Linux, Windows, and macOS LTFS implementations exhibit subtle incompatibilities in extended attribute handling that corrupt portability guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LTFS Copy Software Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Integrated Solution, Cloud-Based Solution, On-Premises Software Use Case: Data Migration, Backup Solutions, Archiving, Tape Management Customer Type: Media & Entertainment, Healthcare Providers, Financial Institutions, Educational Institutions Technology: LTFS Standard, Proprietary Technology, API Integrations, Security Features |
| Companies Covered | Commvault Systems, Veritas Technologies, IBM, Dell Technologies, Cohesity, Quantum Corporation, Veeam Software, NetApp, Spectra Logic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTFS Copy Software Market Shifts & Advancements
Software-defined storage controllers are redefining how enterprises interface with tape hardware. The convergence of API-first architectures with traditional magnetic media is compressing deployment cycles and expanding addressable use cases beyond classic backup.
Object-storage gateways with native LTFS translation layers are displacing conventional hierarchical storage management middleware in enterprise data centers. Media and entertainment studios with petabyte-scale content libraries are adopting these gateways to present tape as S3-compatible endpoints. This displacement eliminates separate backup catalog databases and reduces operational complexity for archive administrators managing multi-petabyte repositories.
GDPR Article 17 erasure requirements are forcing metadata architecture redesigns in European LTFS deployments. Indexed search capabilities must now support granular file-level deletion without compromising tape cartridge integrity. Financial services firms in Germany and France are retrofitting existing libraries with cryptographic shredding modules to satisfy CNIL and BfDI audit expectations.
Subscription-based capacity licensing is replacing perpetual software ownership in North American enterprise procurement. Data protection teams favor operational expenditure models that align costs with actual tape consumption rather than peak provisioned capacity. This shift is most pronounced among healthcare systems in Texas and California managing unpredictable imaging archive growth.
LTFS Copy Software Market Segmentation
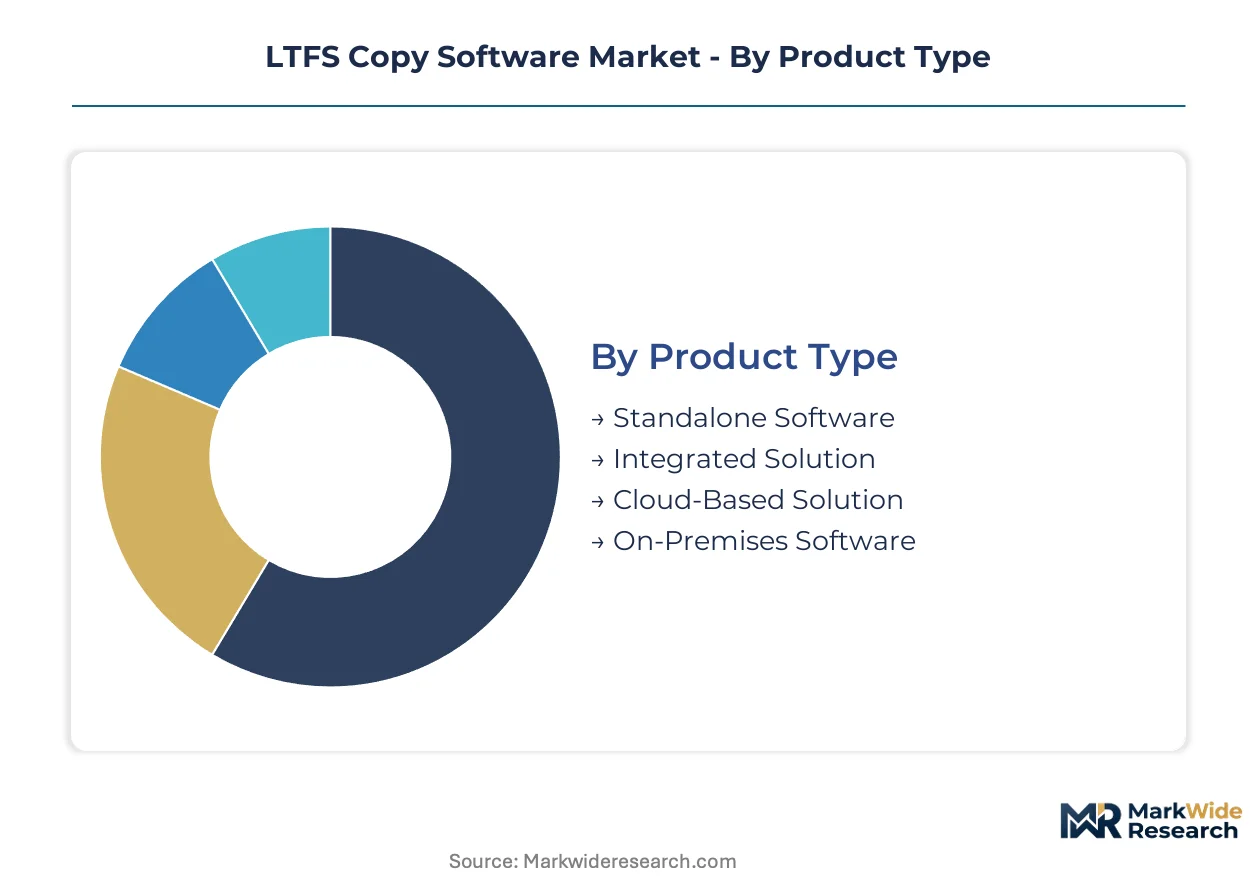
LTFS copy software procurement patterns diverge sharply across deployment models and vertical workflows. Understanding these fault lines reveals where vendor consolidation pressure concentrates versus where specialist solutions retain pricing power.
Product Type:
Domestic demand concentrates in integrated and on-premises deployments, while cloud-native solutions draw disproportionate export-led procurement from multinational enterprises with distributed archive requirements.
- Integrated Solution:Embedded within broader data management platforms, this model eliminates separate backup catalog maintenance. Enterprises in the United States with FISMA compliance obligations favor this approach for unified audit trails across tape and disk tiers.
- Cloud-Based Solution:API-native controllers enable automated tiering between on-premises tape libraries and cloud object storage. Healthcare systems in California and Texas are expanding adoption fastest under subscription licensing models that match costs to unpredictable imaging archive growth.
- Standalone Software:Point utilities for basic drag-and-drop LTFS operations serve smaller media post-production houses with limited IT staff.
- On-Premises Software:Perpetual licensing persists among federal agencies and defense contractors with air-gapped security requirements.
Integrated solutions hold the largest share; momentum sits with cloud-based alternatives.
Use Case:
Cost tiering separates high-frequency retrieval workloads from deep-cold archives, with backup and migration commanding premium pricing versus tape management utilities.
- Archiving:Long-form video production pipelines in streaming content operations require petabyte-scale repositories with native file system accessibility. Media and entertainment studios in Los Angeles and London drive specification requirements for multi-petabyte partition handling.
- Data Migration:Cross-platform transfers between legacy proprietary formats and LTFS 2.0 demand specialized validation tools. Financial institutions in Frankfurt and Singapore are prioritizing migration investments ahead of quantum-resistant encryption mandates.
- Backup Solutions:Traditional disaster recovery workflows retain steady demand among regional healthcare networks with HIPAA obligations.
- Tape Management:Library automation and cartridge tracking serve hyperscale data center operators managing LTO-9 density gains across reduced physical footprints.
Archiving commands the deepest customer relationships; data migration is climbing the fastest as format transitions accelerate.
Customer Type:
Application complexity varies dramatically, with media workflows demanding real-time metadata indexing while financial and healthcare sectors prioritize immutability and audit logging.
- Media & Entertainment:Petabyte-scale content libraries require S3-compatible gateway layers that present tape as object storage endpoints. Studios in Burbank and London's Soho district are displacing conventional hierarchical storage management middleware.
- Financial Institutions:SEC recordkeeping rules and GDPR Article 17 erasure requirements are forcing metadata architecture redesigns. German and French banks are retrofitting libraries with cryptographic shredding modules to satisfy BfDI and CNIL audit expectations.
- Healthcare Providers:Unpredictable imaging archive growth is driving subscription-based capacity licensing across hospital systems in Texas and California.
- Educational Institutions:Research data preservation with limited budgets favors open-source LTFS utilities over commercial platforms.
Media and entertainment holds the largest share; financial institutions are gaining share fastest under regulatory pressure.
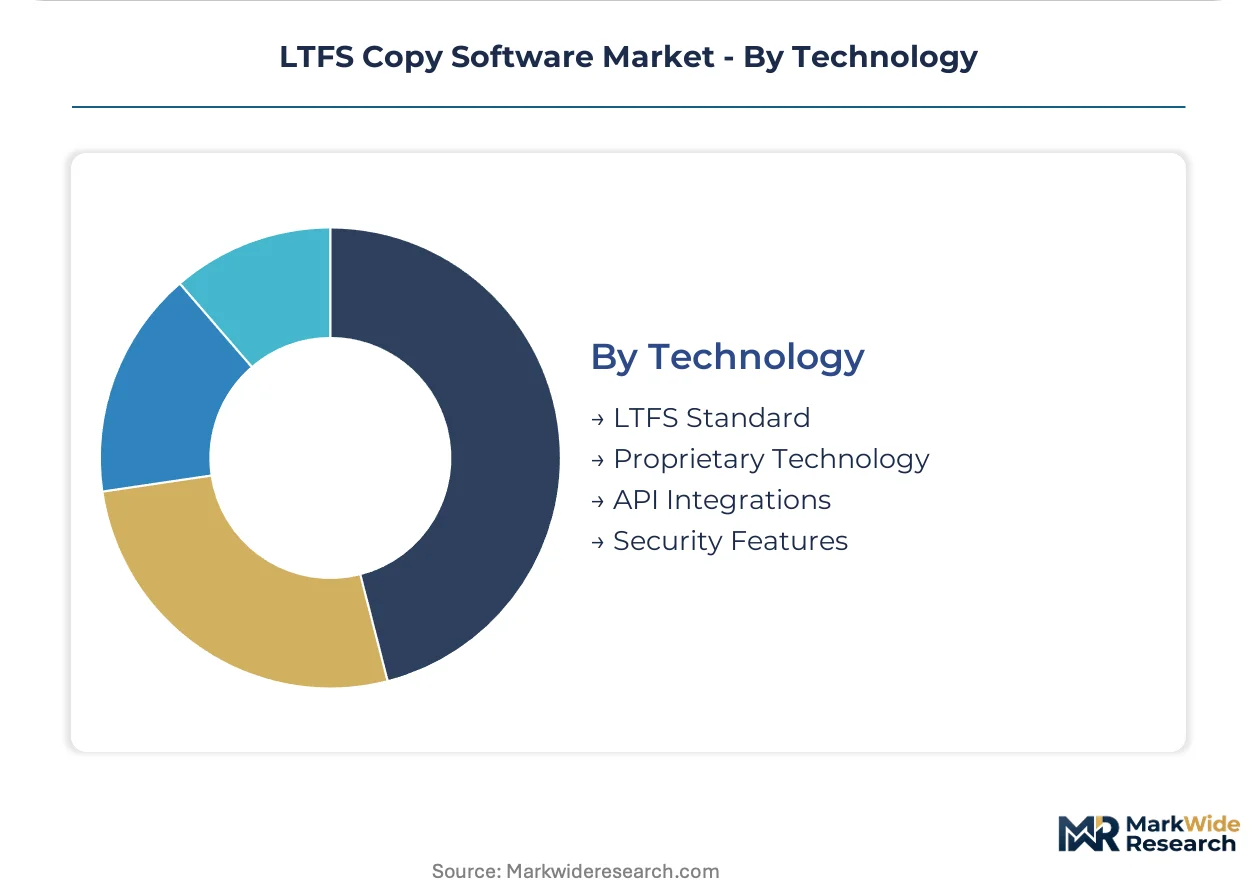
Technology:
Supply concentration in LTO drive manufacturing is elevating the strategic importance of API and security layers as differentiation vectors.
- LTFS Standard:The foundational open-format specification ensures cross-platform readability between Linux, Windows, and macOS systems. Baseline compliance is now table stakes across all procurement evaluations.
- API Integrations:Infrastructure-as-code templates for tape provisioning address gaps in automated data lifecycle management. DevOps teams in regulated industries are demanding programmatic control over tape libraries within CI/CD pipelines.
- Security Features:Encryption and access control modules align with ISO 27001 and IEC 27040 standards for offline storage media.
- Proprietary Technology:Vendor-specific extensions for advanced indexing or automated tiering create switching costs for enterprises with sunk library investments.
LTFS Standard holds the largest share; API integrations are expanding most quickly as automation requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal agencies deploy LTFS copy software for air-gapped compliance archives, while German financial institutions prioritize cryptographic shredding for GDPR erasure mandates. Japanese broadcasters and Indian research institutions favor open-source utilities over commercial platforms.
United States
Hyperscale data centers in Northern Virginia and federal records retention mandates sustain tape infrastructure investments. SEC recordkeeping rules and FISMA compliance obligations drive procurement of integrated LTFS platforms with unified audit trails. Los Angeles studios expand adoption for petabyte-scale streaming content archives.
Germany
Frankfurt financial institutions retrofit libraries with cryptographic shredding modules ahead of quantum-resistant encryption mandates. BfDI audit expectations and GDPR Article 17 erasure requirements force metadata architecture redesigns. Bavarian industrial data centers manage cold storage tiers through automated LTFS controllers.
Japan
Tokyo broadcasters and post-production houses manage long-form video archives through native file system accessibility. METI standards influence encryption module development for offline storage media. Osaka-based media workflows demand real-time metadata indexing for multi-petabyte partition handling.
United Kingdom
London financial services firms prioritize migration investments from legacy proprietary formats to LTFS 2.0 specifications. CNIL-aligned audit expectations shape how indexed metadata supports granular file-level deletion. Soho district studios displace conventional hierarchical storage management middleware with S3-compatible gateway layers.
India
Bangalore research institutions and Mumbai media post-production houses favor open-source LTFS utilities over commercial platforms. CDSCO data retention guidelines for clinical trials sustain tape archive demand in pharmaceutical clusters. Hyderabad hyperscale facilities manage unpredictable imaging archive growth through subscription licensing models.
LTFS Copy Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in LTFS copy software supply. Tier-one vendors anchor workflows within broader data protection platforms, while specialists concentrate on high-performance tape automation or vertical workflow expertise. Three archetypes dominate: hardware-heritage integrators, multi-tier platform vendors, and automation specialists. Competitive moves center on API-native controller development and hybrid cloud orchestration partnerships.
Within the hardware-heritage tier, IBM leverages tape infrastructure integration across mainframe and storage environments. Veritas Technologies and Quantum Corporation exemplify divergent specialization strategies—Veritas through broad platform coverage incorporating LTFS as one archive tier, Quantum through deep vertical expertise in media and entertainment workflows. These three occupy positions that reflect the market's segmentation between integrated enterprise solutions and targeted automation capabilities.
| Leading Market Players |
|---|
| Commvault Systems |
| Veritas Technologies |
| IBM |
| Dell Technologies |
| Cohesity |
| Quantum Corporation |
| Veeam Software |
| NetApp |
| Spectra Logic |
| Others |
Supply & Pricing Matrix
ISO 27001 and IEC 27040 certification requirements for offline storage media create dual gates for LTFS copy software vendors, simultaneously filtering supply-side qualification and enabling tiered pricing power for compliant platforms. Federal agencies and financial institutions demand audit-ready encryption modules, compressing procurement evaluation to certified providers while elevating price premiums for integrated security stacks.
Pricing Analysis
Long-term enterprise licensing contracts dominate procurement for federal and healthcare segments, while subscription-based capacity licensing gains traction among hyperscale operators managing unpredictable archive growth. Price differentiation rests on certification grade and vertical integration depth, with FISMA-compliant integrated platforms commanding substantial premiums over standalone utilities. Cost compression in cloud-native tiers is intensifying because QLC NAND competition erodes tape's total-cost-of-ownership advantage for sub-seven-year retention. Healthcare systems in Texas and California exhibit highest price sensitivity, favoring operational expenditure models that align costs with actual consumption.
Supply Chain Analysis
Extended lead times for LTO-9 drive assemblies from Japan and the United States signal inventory constraints across tape hardware procurement channels. Manufacturing concentrates among licensed producers in Japan, the United States, and China, with precision tape head components drawing from specialized semiconductor foundries in Taiwan and South Korea. Single-source vulnerability in LTO drive mechanics creates supply risk for enterprises dependent on specific automation form factors. Distribution runs through direct OEM relationships for hyperscale deployments and value-added resellers serving mid-market media workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LTFS copy software market constitutes a defensive moat anchored in regulatory entrenchment, where FISMA and SEC recordkeeping mandates create structural switching costs that protect incumbent positions against substitute storage technologies.
For Market Incumbents: Compound platform stickiness through deeper API-native controller development that embeds tape orchestration within DevOps pipelines, defending against cloud-native archival substitutes. Prioritize backward integration into LTO drive firmware layers to capture quantum-resistant encryption upgrade cycles before NIST standards crystallize. For New Entrants and Emerging Players: Anchor in open-source LTFS utility gaps among Indian research institutions and Mumbai post-production houses, where CDSCO data retention guidelines sustain demand without incumbent platform saturation. Target healthcare systems in California and Texas through subscription-based capacity licensing that matches unpredictable imaging archive growth patterns. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across API integration and security module development, favoring acquisition of specialist firms with proven DevOps pipeline deployments over greenfield platform builds. Watch for NIST post-quantum cryptographic standard finalization as the inflection signal triggering firmware upgrade cycles across installed tape libraries.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Controller Development | Enables automated tiering between on-premises tape libraries and AWS S3-compatible object storage endpoints. |
| Quantum-Resistant Encryption Integration | Positions platforms ahead of NIST post-quantum cryptographic mandates affecting federal archive compliance. |
| Hybrid Cloud Orchestration Partnership | Addresses variable retrieval latency requirements across Los Angeles streaming content operations. |
| Vertical Workflow Specialization | Captures media and entertainment demand in London's Soho district through S3-compatible gateway layers. |
| Subscription Licensing Expansion | Aligns costs with unpredictable imaging archive growth across Texas and California healthcare systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and LTO consortium technical specifications. Data protection executives, federal IT procurement officers, and media archive administrators provided qualitative inputs on deployment timelines and vendor selection criteria. Platform engineers and integration specialists supplied technical validation on API architecture and DevOps pipeline compatibility. Bottom-up estimates of tape library shipments and software attach rates were triangulated against top-down assessments of federal compliance spending and healthcare imaging archive growth.
Segmentation dimensions modeled include deployment model, organization size, vertical workflow, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed base growth assumptions, LTO-9 density adoption curves, and cloud-tiering penetration rates. Forecast inputs incorporated FISMA compliance obligation trajectories and GDPR Article 17 erasure requirement implementations affecting metadata architecture redesigns.
Decision-makers should treat outputs as directional under assumptions of sustained federal retention mandates and stable LTO hardware supply; material deviation in quantum computing timelines or flash cost compression would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Problem Management Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Subscription Management Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Construction Software Market
Software & Services
Ccaas Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Global Customer Service Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Telecom Billing Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Denmark Software As a Service (Saas) Market
Software & Services
Family Law Software Market