
 Global Investor Relationship Management Software Market | 2026-2036
Global Investor Relationship Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Investor Relationship Management Software Market Foresight
Capital-intensity divergence between cloud-native entrants and legacy on-premises vendors is collapsing as subscription economics normalize R&D recovery cycles across the sector. Dynamo Software leverages its vertical specialization in alternative assets to sustain premium pricing in fund administration workflows. Allvue Systems anchors its competitive position through an integrated front-to-back platform spanning investor relations through portfolio analytics. Irwin differentiates by dominating the Canadian-listed issuer segment before extending capabilities southward into US capital markets.
Investor Relationship Management Software constitutes a category of enterprise applications designed to centralize limited partner data, automate capital-call notifications, and maintain audit trails of all investor-facing communications with SOC 2 Type II certification as a baseline security parameter. Its primary commercial purpose is reducing operational drag in fundraising cycles while satisfying regulatory documentation burdens for private fund managers. Cloud-based deployment leads absolute revenue contribution as asset managers abandon self-managed infrastructure, while compliance management solutions within the solution-type dimension command outsized margin pools due to jurisdictional complexity. Data analytics capabilities represent the fastest-expanding segment as general partners seek predictive signals on investor commitment likelihood across sovereign wealth funds and pension allocators.
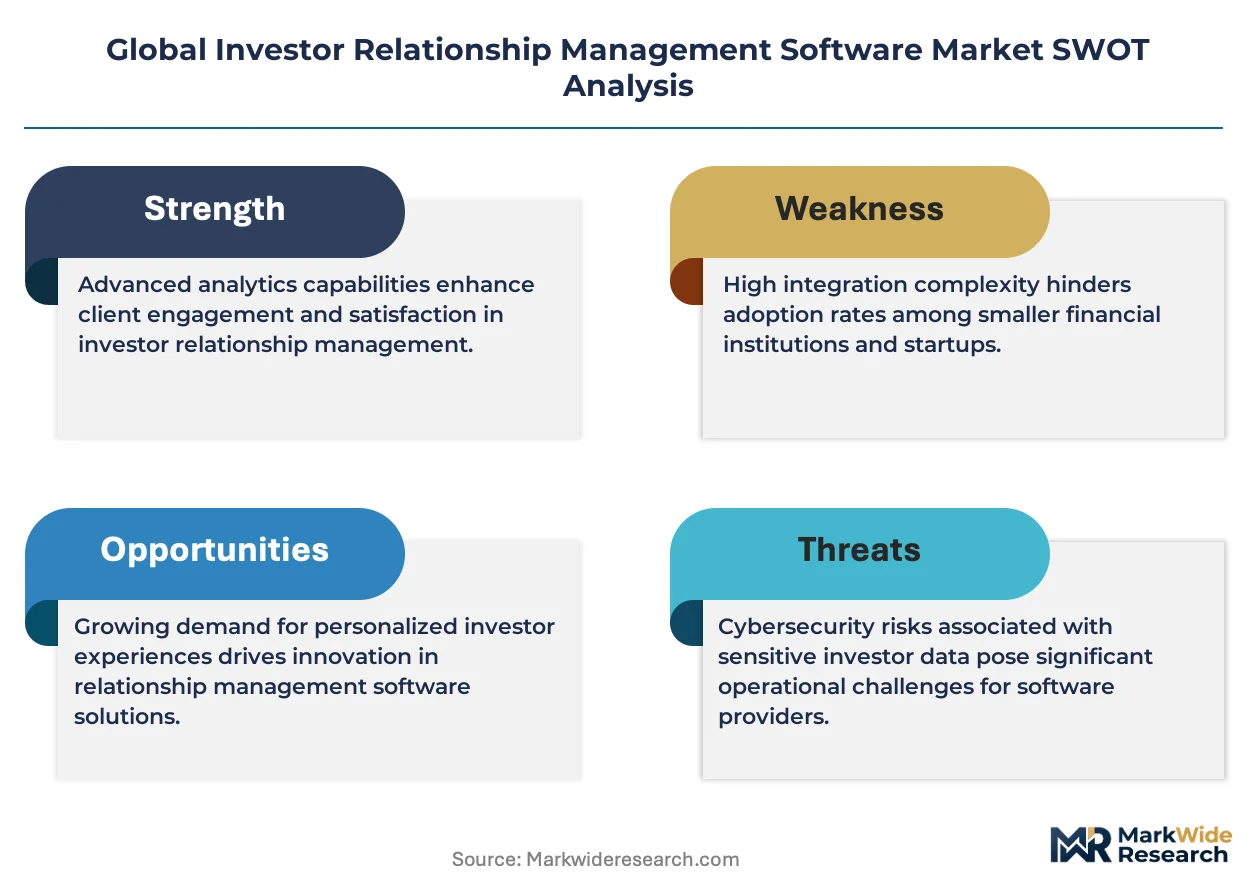
The SEC's private fund adviser rules and the EU's AI Act jointly reshape product roadmaps, with the former mandating quarterly reporting standardization and the latter imposing algorithmic transparency on automated investor-matching tools. GDPR retention requirements in Europe and emerging data-localization directives from China's SAMR add compliance layers that favor vendors with multi-tenant regional architecture. Stakeholders must monitor whether emerging SEC custody rule revisions will force additional workflow reconfiguration ahead of implementation deadlines.
Market Dynamics
Cloud-native architecture is displacing on-premises infrastructure as asset managers prioritize elastic scalability over capital-intensive server ownership, compressing deployment timelines from quarters to weeks.
Growth Catalysts
- SEC Private Fund Adviser Rules:Quarterly reporting standardization mandates compel general partners to adopt automated compliance workflows, accelerating platform procurement cycles among mid-market fund administrators.
- Sovereign Wealth Fund Digitization:Pension allocators in Norway, Singapore, and Abu Dhabi now require API-first data exchange protocols, forcing managers to upgrade legacy CRM systems.
- Generative AI Integration:Natural language processing tools automate capital-call narrative generation, reducing operational headcount in fund administration functions.
Market Restraints
- Multi-Tenant Security Architecture Costs:SOC 2 Type II certification and regional data-localization requirements inflate R&D expenditure for vendors serving cross-border fund structures.
- Concentrated Buyer Power:The top fifty alternative asset managers control a disproportionate share of contract value, compressing pricing leverage for mid-tier software providers.
- Legacy System Entrenchment:Custom-built investor portals deployed during the 2010s private equity boom create switching friction through embedded workflow dependencies.
Strategic Opportunities
- Secondaries Market Expansion:GP-led continuation funds and LP stake sales require specialized transfer agency modules that incumbent platforms lack, opening white space for modular entrants.
- EU AI Act Compliance Tools:Algorithmic transparency requirements for automated investor-matching engines create premium pricing potential for vendors with embedded audit-trail functionality.
- Wealth Manager Convergence:Family offices and registered investment advisers are adopting institutional-grade LP communication tools, extending addressable market beyond traditional private fund managers.
Industry Challenges
- Quantitative Investor Relations Talent Scarcity:Firms struggle to hire professionals who combine alternative asset domain expertise with data engineering capabilities for predictive analytics deployment.
- Cross-Border Data Fragmentation:China's SAMR localization directives, GDPR retention rules, and emerging ASEAN data governance frameworks force costly regional infrastructure replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Investor Relationship Management Software Market |
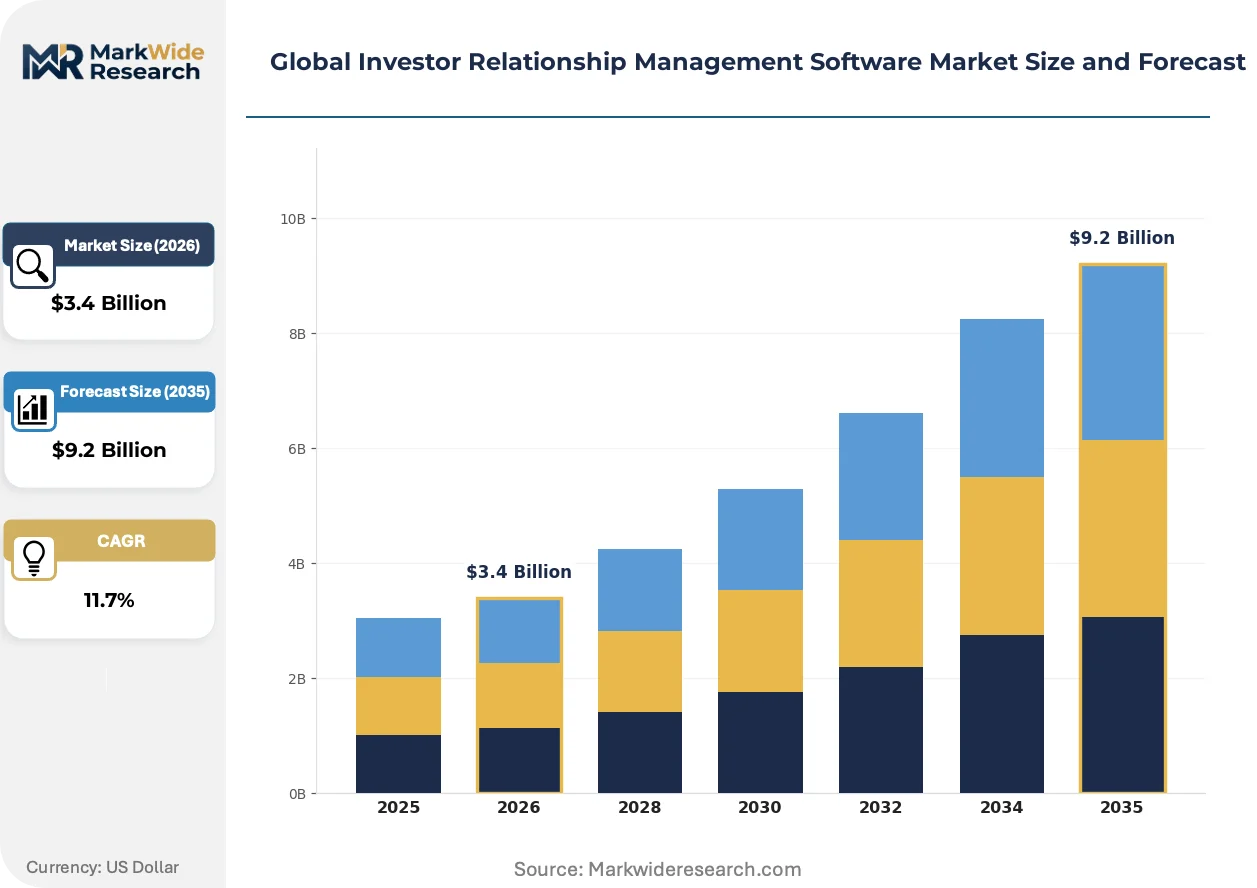
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.2 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Hosted Solution Type: Investor Communication, Data Analytics, Compliance Management, Reporting Automation, Portfolio Monitoring End User: Asset Managers, Private Equity Firms, Hedge Funds, Venture Capitalists, Family Offices Investor Type: Institutional Investors, Retail Investors, Sovereign Wealth Funds, Pension Funds, Angel Investors |
| Companies Covered | Affinity, Irwin, Juniper Square, Carta, Backstop Solutions, Allvue Systems, 4Degrees, Vessel, Dynamo Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Investor Relationship Management Software Market Shifts & Advancements
Predictive analytics engines are reshaping how general partners anticipate commitment behavior, while regulatory automation modules absorb compliance complexity that previously required manual legal review.
Embedded machine learning for investor propensity scoring is displacing heuristic-based relationship management in fundraising workflows. Large buyout firms with dedicated data science teams deploy these tools to prioritize outreach sequences, compressing capital-raise timelines by surfacing commitment signals from historical interaction patterns. The technology is displacing traditional relationship-manager intuition as the primary allocation determinant in competitive fundraises.
The EU AI Act's algorithmic transparency mandates impose documentation burdens on automated investor-matching features. Vendors must now maintain technical files explaining training data provenance and decision logic for supervisory audits. European-domiciled fund managers face the steepest compliance ramps, accelerating procurement of platforms with pre-certified explainability modules.
Subscription pricing models are supplanting perpetual license structures across the buyer base. Asset managers prefer operational expenditure treatment for software costs, aligning vendor incentives with ongoing platform utilization rather than upfront deployment. This shift is most pronounced among emerging managers in the United States and United Kingdom, where cash-flow management priorities favor predictable monthly outlays over capital calls for IT infrastructure.
Global Investor Relationship Management Software Market Segmentation
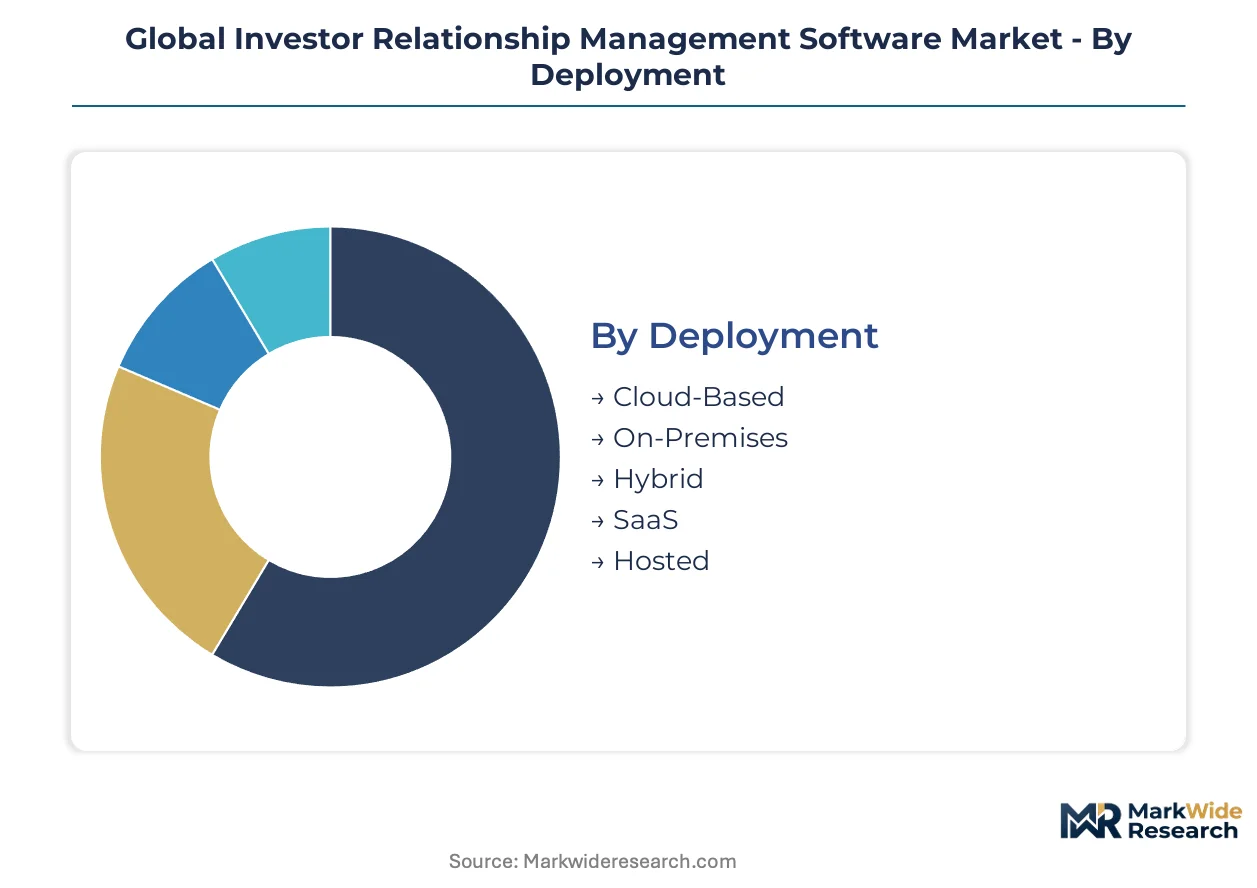
Segmentation in investor relationship management software reveals distinct procurement patterns across deployment architectures and buyer sophistication tiers. Asset managers select platforms based on regulatory jurisdiction complexity, fund structure scale, and existing technology stack entrenchment.
Deployment:
Geographic spread varies sharply: cloud-native solutions dominate North American and Western European procurement, while hybrid and on-premises deployments persist in jurisdictions with strict data-localization mandates.
- Cloud-Based:Multi-tenant architectures enable elastic scaling for mid-market fund administrators managing volatile AUM flows. Demand concentrates among emerging managers in the United States and United Kingdom seeking operational expenditure treatment for software costs.
- On-Premises:Self-managed infrastructure remains entrenched among sovereign wealth funds and large pension allocators in China and the Middle East with internal security mandates. Procurement cycles extend to 12-18 months due to custom integration requirements.
- Hybrid:Split configurations allow sensitive investor data to reside on local servers while leveraging cloud analytics engines.
- SaaS:Subscription-native platforms accelerate deployment timelines from quarters to weeks for cross-border fund structures.
- Hosted:Dedicated single-tenant instances serve asset managers with SOC 2 Type II certification requirements in specific regulatory regimes.
Cloud-Based holds the largest share; momentum sits with SaaS as subscription economics normalize across the sector.
Solution Type:
Cost tier stratification separates compliance-heavy modules from commoditized communication tools, with premium pricing attaching to jurisdictional complexity.
- Compliance Management:Automated workflow engines address SEC quarterly reporting standardization and EU AI Act algorithmic transparency mandates. Demand concentrates among European-domiciled fund managers facing the steepest documentation ramps for automated investor-matching features.
- Data Analytics:Predictive engines for investor propensity scoring displace heuristic-based relationship management in competitive fundraises. Large buyout firms with dedicated data science teams deploy these tools to prioritize outreach sequences.
- Investor Communication:Capital-call notification automation and LP portal management form the baseline functionality layer.
- Reporting Automation:Standardized document generation reduces legal review cycles for private fund advisers.
- Portfolio Monitoring:Real-time dashboards track commitment pacing and distribution waterfalls for limited partners.
Compliance Management commands premium pricing; Data Analytics is gaining share fastest as general partners seek predictive signals on commitment likelihood.
End User:
Application intensity varies by fund structure complexity, with private equity and hedge fund workflows driving the most sophisticated feature requirements.
- Asset Managers:Broad category spanning mutual fund complexes to alternatives specialists with divergent LP communication protocols.
- Private Equity Firms:GP-led continuation funds and LP stake sales in the secondaries market require specialized transfer agency modules absent from incumbent platforms.
- Hedge Funds:High-frequency redemption cycles and prime brokerage relationships demand real-time investor liquidity tracking.
- Venture Capitalists:Early-stage fund managers prioritize lightweight deployment with minimal IT overhead.
- Family Offices:Convergence toward institutional-grade LP communication tools extends addressable market beyond traditional private fund managers.
Private Equity Firms anchor procurement volume; Family Offices represent the steepest expansion trajectory as wealth manager adoption accelerates.
Investor Type:
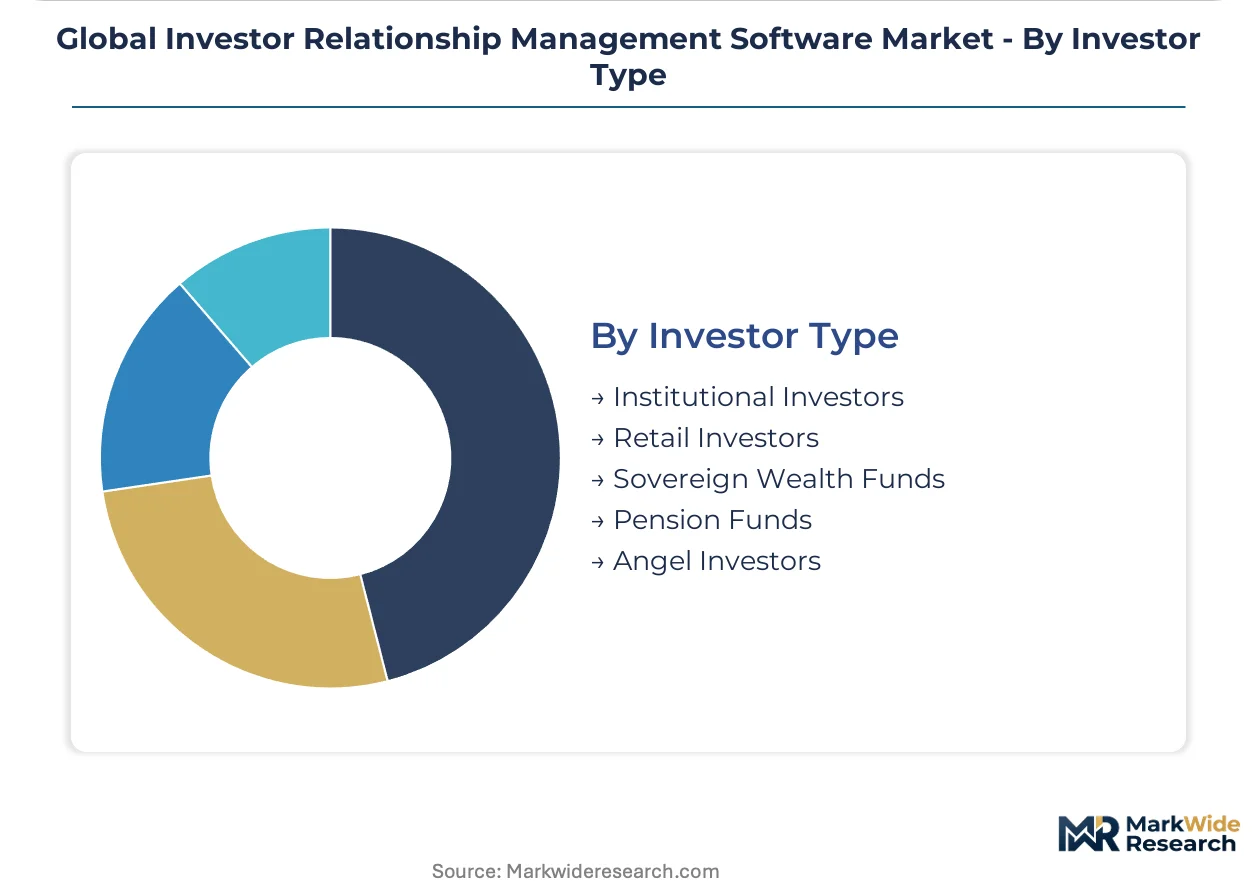
Customer type determines platform configuration depth, with institutional and sovereign allocators requiring API-first data exchange protocols.
- Institutional Investors:Insurance companies and endowments mandate granular fee transparency and side-letter tracking functionality.
- Sovereign Wealth Funds:Norway's Government Pension Fund Global, GIC Private Limited in Singapore, and ADQ in Abu Dhabi now require standardized API protocols, forcing manager technology upgrades.
- Pension Funds:Public sector allocators in Canada and the Netherlands impose ESG integration requirements in reporting modules.
- Retail Investors:Democratization of private market access through interval funds and tender offer programs creates demand for simplified portal experiences.
- Angel Investors:Individual accredited participants in syndicate structures require minimal viable functionality at compressed price points.
Sovereign Wealth Funds drive the most demanding specifications; Retail Investors are climbing the fastest as regulatory access expansion proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European procurement cycles elongate under compliance complexity. German and French asset managers absorb margin pressure from EU AI Act implementation timelines. Asian markets fragment between Singapore's API-first standards and China's data-localization mandates.
United States
Private capital depth and SEC quarterly reporting mandates drive platform upgrades among mid-market fund administrators. The SEC's private fund adviser rules compel automated compliance workflow adoption. New York and Boston anchor procurement volume as general partners prioritize operational expenditure treatment for software costs.
United Kingdom
Subscription pricing preference among emerging managers accelerates SaaS-native vendor penetration. GDPR retention requirements layer complexity onto cross-border fund structures. London's fintech cluster houses the highest concentration of cloud-native deployment decisions in European alternative assets.
Germany
Institutional allocator demand for granular fee transparency shapes platform configuration requirements. BaFin scrutiny of automated investor-matching tools elevates documentation burdens. Frankfurt's fund administration sector leads continental procurement of explainability-certified modules.
Singapore
Sovereign wealth fund digitization mandates API-first data exchange protocols for manager-facing systems. MAS guidelines on technology risk management shape vendor selection criteria. The city-state's fund services hub concentrates regional headquarters decisions for Asia-Pacific platform rollouts.
China
Data-localization directives from SAMR force regional infrastructure replication for cross-border fund structures. Domestic asset managers prioritize self-managed security architectures over multi-tenant cloud options. Shanghai's private equity cluster sustains on-premises deployment preference despite global SaaS momentum.
Global Investor Relationship Management Software Market Competitive Landscape
Concentration sits with vertical specialists commanding premium pricing in alternative asset workflows. The vendor base stratifies across three tiers: integrated front-to-back platforms, compliance-heavy modular specialists, and geography-focused regional champions. Dominant competitive moves include portfolio diversification into adjacent fund administration tools and strategic partnerships with data analytics providers.
Among vertical specialists, Dynamo Software, Allvue Systems, and Irwin anchor distinct positioning archetypes. Dynamo Software exemplifies the premium-priced fund administration specialist. Allvue Systems occupies the integrated platform tier spanning investor relations through portfolio analytics. Irwin represents geography-first expansion patterning, dominating Canadian-listed issuer segments before extending capabilities into US capital markets. These three illustrate how specialization vectors—vertical depth, functional breadth, and geographic sequencing—structure competitive differentiation in investor relationship management software procurement decisions.
| Leading Market Players |
|---|
| Affinity |
| Irwin |
| Juniper Square |
| Carta |
| Backstop Solutions |
| Allvue Systems |
| 4Degrees |
| Vessel |
| Dynamo Software |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-week procurement cycles for SOC 2 Type II certification audits compress vendor cash conversion timelines while amplifying pricing power for pre-certified platforms. This lead-time band concentrates supply-side leverage among established cloud-native providers with existing compliance infrastructure, forcing emerging entrants to absorb front-loaded certification costs or cede premium-tier contracts.
Pricing Analysis
The customization-premium spread widens to three-to-five multiples between configured-to-order compliance modules and standard investor communication packages. Subscription-SaaS tiered pricing dominates as asset managers prioritize operational expenditure treatment, with price differentiation anchored in certification grade and vertical integration depth. Cost compression in mid-market segments intensifies as buyer consolidation concentrates contract leverage among the top fifty alternative asset managers. Emerging managers in the United States and United Kingdom exhibit highest price sensitivity, while sovereign wealth funds in Singapore and Abu Dhabi demonstrate lowest elasticity due to security mandate rigidity.
Supply Chain Analysis
Strategic-stockpile preferences dominate among asset managers in China and the Middle East, where data-localization directives from SAMR and internal security mandates favor self-managed infrastructure reserves. Software development concentrates in the United States, the United Kingdom, and India, with cloud infrastructure provisioning drawing from hyperscaler regions in Ireland, Singapore, and Virginia. Supply chain risk centers on single-source vulnerability for specialized compliance automation engines. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving fund administration workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors face intensifying substitution pressure from vertically integrated fund administration platforms that bundle investor relations functionality at marginal cost. Defense requires strategic consolidation of differentiation moats before buyer consolidation completes.
For Market Incumbents: Consolidate API-first architecture investments to defend against modular entrants targeting sovereign wealth fund digitization mandates. Deepen backward integration into predictive analytics engines to offset margin pressure from generative AI commoditization of capital-call narrative generation. Prioritize SOC 2 Type II certification maintenance as a renewal barrier against lower-cost cloud-native challengers. For New Entrants and Emerging Players: SOC 2 Type II fast-track certification represents the critical path to contract eligibility among mid-market fund administrators. White space concentrates in secondaries market transfer agency modules and EU AI Act explainability-certified compliance tools. Geographic entry should sequence through Canadian-listed issuer segments before extending capabilities into US capital markets, mirroring proven expansion patterns. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment segments as subscription economics normalize R&D recovery cycles. Long-term viability favors platforms with embedded regulatory automation absorbing compliance complexity that previously required manual legal review. Acquisition target archetypes include modular specialists with pre-certified explainability modules for European-domiciled fund managers. The signal to watch is SEC custody rule revision timing, which may force additional workflow reconfiguration and platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies investor relations through portfolio analytics for front-to-back workflow consolidation. |
| Acquisition of Specialist Firm | Captures secondaries market transfer agency capabilities absent from incumbent platforms. |
| Strategic Partnership | Secures API-first data exchange protocols required by Norway's Government Pension Fund Global. |
| Geographic Expansion | Establishes regional infrastructure replication for China's SAMR data-localization mandates. |
| Product Launch | Deploys explainability-certified modules addressing EU AI Act algorithmic transparency requirements. |
Research Methodology
A spread of perspectives from chief technology officers at alternative asset managers, compliance officers navigating SEC private fund adviser rules, fund administration operations directors, and platform integration specialists converged on the working assumptions. Primary interviews combined with secondary validation from SEC regulatory filings, MAS technology risk management guidelines, EBA stress test disclosures, and hyperscaler capex reports. Bottom-up contract value analysis triangulated against top-down AUM-weighted platform penetration estimates.
Segmentation dimensions modeled span deployment architecture, solution type, end-user category, and investor type across the projection horizon. CAGRs derived from installer-base growth rates, replacement cycle acceleration, and regulatory mandate compliance deadlines. Forecast inputs incorporated sovereign wealth fund API protocol adoption curves and generative AI integration penetration in fund administration functions.
Underlying assumptions cover stable SEC implementation timelines and EU AI Act enforcement sequencing, with deviation risk concentrated in custody rule revision scope and SAMR data-localization directive expansion. Revision becomes warranted when regulatory compliance cost thresholds cross levels that trigger platform consolidation rather than modular upgrade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Calorie Metering Software Market
Software & Services
Aviation Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
Global Municipal Software Market
Software & Services
Electronic Batch Records Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
UK Point of Sale Software Market
Software & Services
Design Engineering Software Market
Software & Services
Global Customer Service Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Compensation Software Market
Software & Services
Over-The-Air Software Update Market