
 Brush Cleaner Market | 2026-2036
Brush Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Brush Cleaner Market Outlook
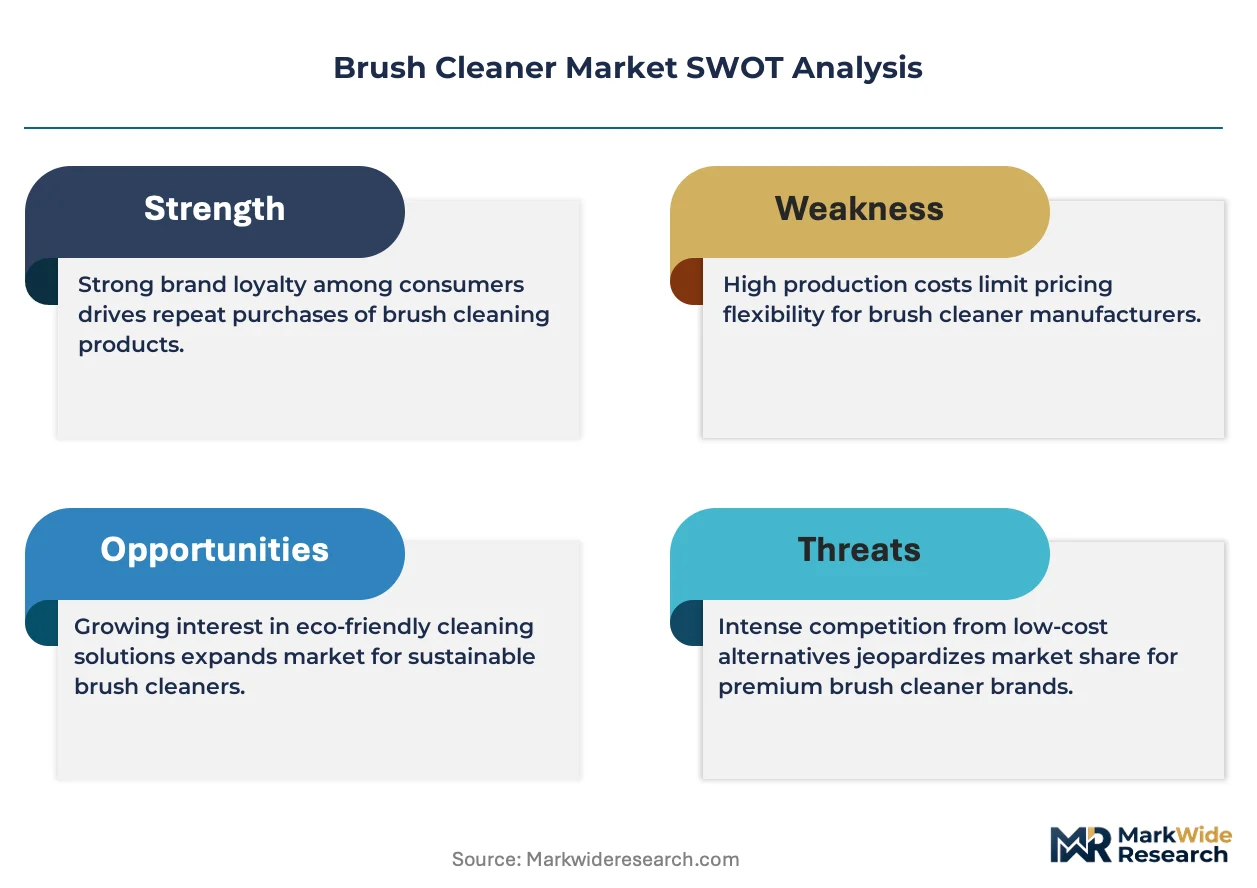
The split between premium solvent-free formulations and commodity mineral-spirit blends is repositioning procurement standards across art supply and industrial channels. Gordon Brush leverages synthetic-bristle specialization to anchor its industrial maintenance contracts. Tanis Brush competes through geographic dominance in North American automotive OEM brush cleaning programs. Schaefer Brush Manufacturing differentiates via extended R&D intensity in biodegradable surfactant chemistry.
Brush cleaners are formulated solutions designed to dissolve paint, adhesive, or particulate buildup from bristle, filament, or foam brush heads, typically incorporating surfactants, solvents, or enzymatic agents with pH ranges between 6.5 and 9.0 to preserve bristle integrity. Their primary purpose spans extending tool lifespan in professional painting, maintaining hygiene in cosmetic brush applications, and ensuring process consistency in industrial coating operations. Liquid cleaners lead volume in art supply and cosmetics channels where controlled dosing matters, while industrial demand gravitates toward chemical-based formulations that strip heavy acrylic or epoxy residues. Biodegradable materials represent the fastest-growing segment as California and EU jurisdictions restrict volatile organic compound emissions.
EPA regulates solvent content under VOC emission standards, while REACH governs chemical substance registration and restriction across European supply chains, both frameworks elevating compliance costs for legacy petroleum-based formulations. OSHA workplace exposure limits further shape industrial brush cleaner selection in manufacturing environments. Stakeholders must monitor pending state-level clean chemistry mandates and assess captive formulation capacity versus third-party supply dependence.
Market Dynamics
REACH chemical restrictions and EPA VOC emission standards are compressing formulation options for legacy petroleum-based brush cleaners while accelerating capital deployment into biodegradable surfactant chemistry across European and North American supply chains.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH registration deadlines for hazardous substances are forcing cosmetic and industrial brush cleaner manufacturers to reformulate with plant-derived surfactants, creating demand pull for biodegradable alternatives.
- Automotive OEM brush maintenance protocols:Tier-1 suppliers in Germany and the US Midwest are mandating solvent-free cleaning systems to meet ESG disclosure requirements and reduce workplace exposure incidents.
- California Air Resources Board VOC limits:The state's progressive emission caps on art supply and cosmetic brush cleaners are driving R&D investment into low-VOC enzymatic formulations that preserve synthetic bristle integrity.
Market Restraints
- Petroleum distillate price volatility:Mineral spirit and naphtha input costs fluctuate with crude oil benchmarks, squeezing margin stability for commodity brush cleaner producers dependent on legacy solvent blends.
- Specialty surfactant supply concentration:Biodegradable alkyl polyglucoside production clusters in Western Europe, creating geographic vulnerability for North American formulators seeking clean-label alternatives.
- Enzymatic stability limitations:Protease and lipase additives in brush cleaners degrade at temperature extremes above 40°C, restricting shelf life and distribution range for bio-based formulations.
Strategic Opportunities
- Underpenetrated Indian cosmetic manufacturing:CDSCO regulatory alignment with EU cosmetic safety standards is opening procurement channels for solvent-free brush cleaners among Mumbai and Bengaluru-based contract manufacturers.
- Industrial coating robotics maintenance:Automated paint application systems in automotive and aerospace facilities require precision brush cleaning protocols, creating demand for pH-neutral, non-corrosive formulations.
- EU CSRD supply chain disclosure mandates:Extended producer responsibility frameworks are incentivizing brush cleaner suppliers to offer take-back programs and refillable concentrate systems.
Industry Challenges
- Formulation chemist talent scarcity:The intersection of green chemistry expertise and surfactant application knowledge is narrowing the qualified candidate pool for R&D leadership roles.
- Biodegradability certification timelines:OECD 301B and 301F testing protocols require 28-day minimum evaluation periods, delaying product launch schedules for reformulated lines.
- Legacy equipment compatibility:Existing industrial brush cleaning stations in automotive paint shops require retrofitting to handle water-based formulations without corrosion damage to steel reservoirs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brush Cleaner Market |
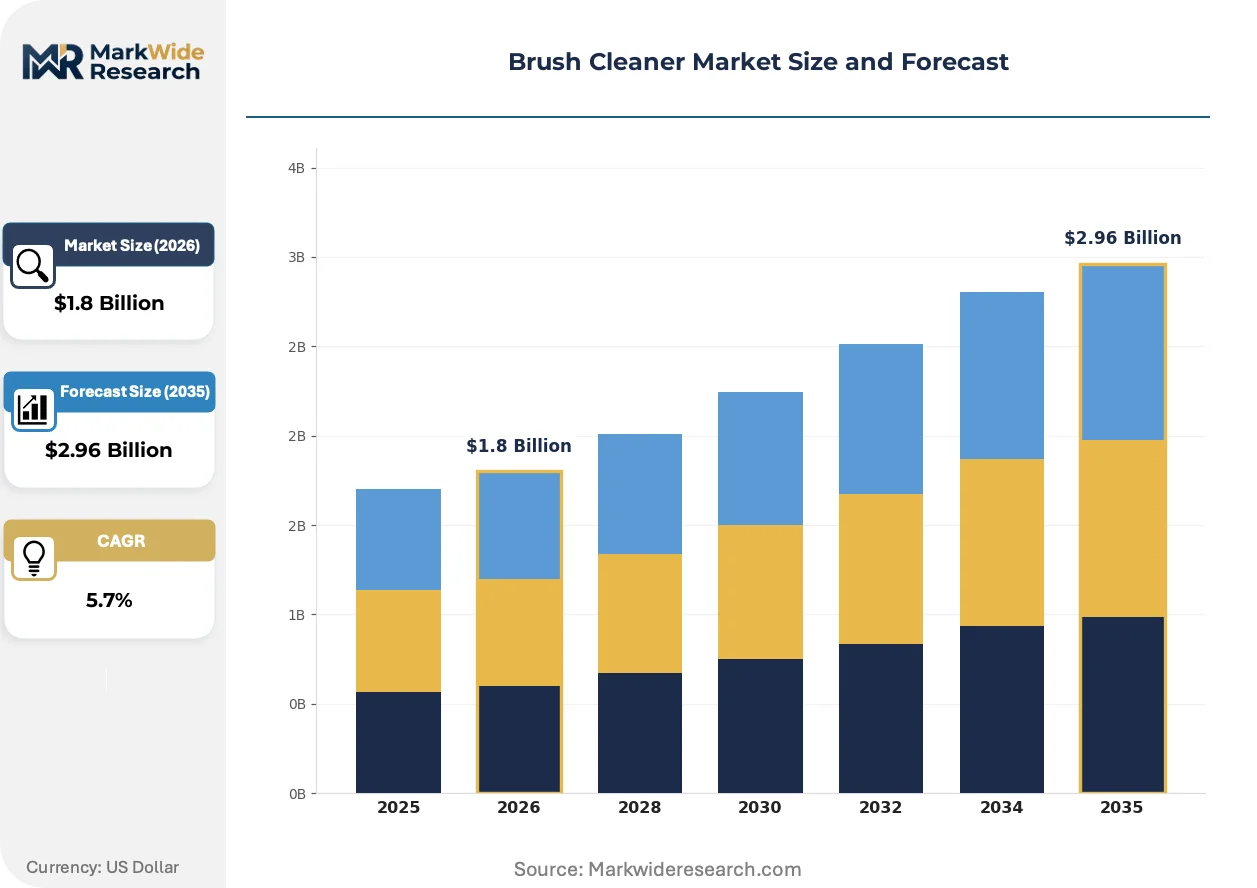
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Solid Cleaners, Spray Cleaners, Wipes Material: Synthetic, Natural, Biodegradable, Chemical-Based Container Type: Bottle, Jar, Tube, Spray Can Usage: Art Supplies, Cosmetics, Automotive, Industrial |
| Companies Covered | Schaefer Brush Manufacturing, Precision Brush, Brush Research Manufacturing, Mill-Rose, Cocker-Weber Brush Company, Kumex Industrial Brushes, Gordon Brush, Tanis Brush, Osborn International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brush Cleaner Market Strategic Shifts
Formulation chemistry is pivoting from petroleum-derived solvents to bio-based enzymatic systems, while regulatory disclosure requirements and procurement digitization are reshaping how buyers evaluate supplier compliance credentials.
Enzymatic brush cleaners utilizing immobilized lipase and cellulase blends are electrifying residue removal performance for acrylic and oil-based paints without bristle damage. Professional art supply retailers and cosmetic brush manufacturers are adopting these systems at accelerated pace to preempt regulatory restrictions. This technology is electrifying competitive positioning by enabling premium pricing for certified biodegradable products while compressing demand for mineral-spirit commodity blends.
REACH Annex XIV authorization requirements for persistent organic pollutants are eliminating certain chlorinated solvents from industrial brush cleaner formulations across EU manufacturing supply chains. Chemical manufacturers face reformulation deadlines or substitution mandates for legacy products used in automotive and aerospace coating maintenance. German industrial brush users are responding fastest, with captive formulation facilities investing in surfactant synthesis capabilities to secure supply chain autonomy.
Cosmetics manufacturers are consolidating brush cleaner suppliers around ESG-verified partners capable of documenting carbon intensity and chemical safety through blockchain-anchored certificates. This consolidation is displacing fragmented distributor networks with direct procurement relationships between formulators and beauty brand technical teams. The shift is most visible in California and EU markets where clean beauty certification programs require ingredient transparency down to ppm thresholds.
Brush Cleaner Market Segmentation
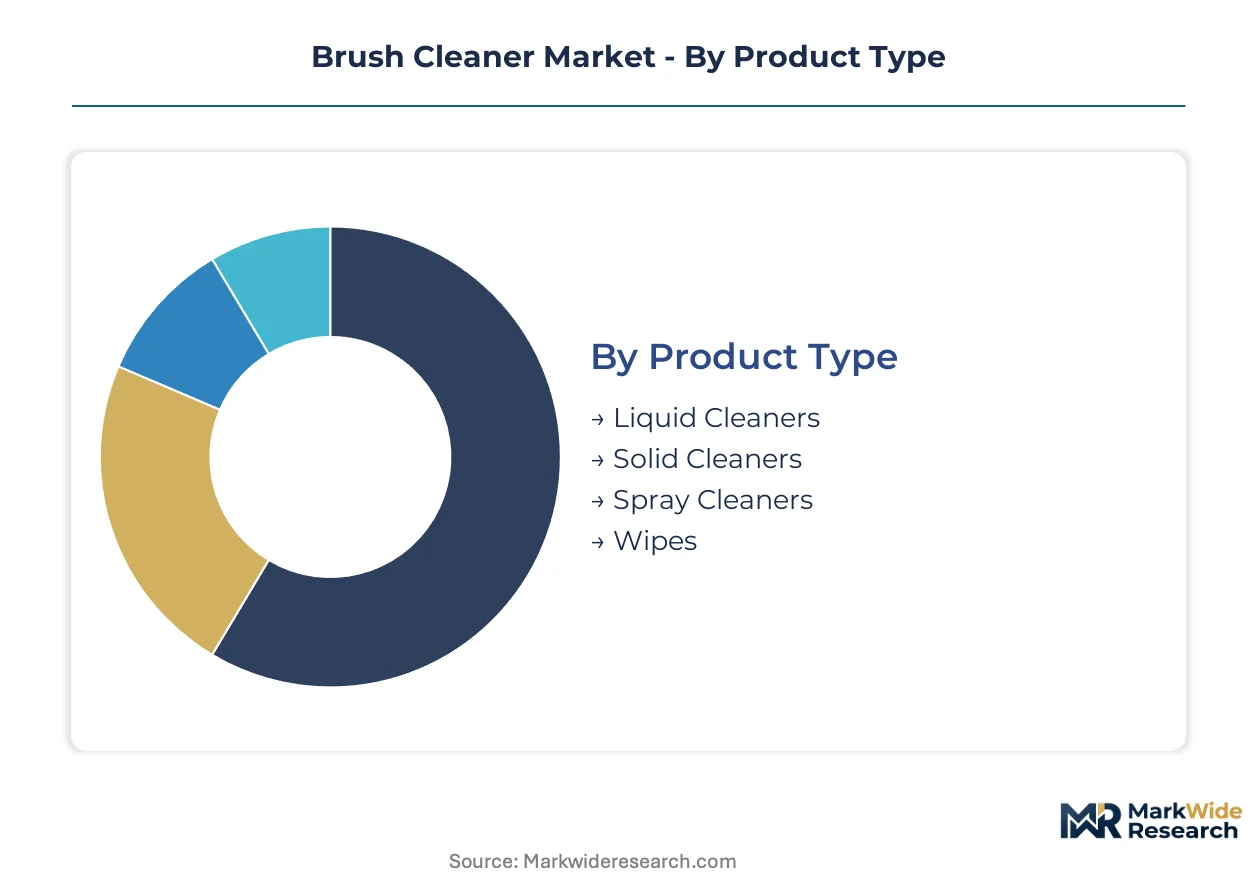
Brush cleaner procurement splits sharply across formulation chemistry, packaging modality, and end-use compliance requirements. Buyers in cosmetics and automotive channels prioritize solvent-free certifications, while industrial users balance residue-stripping power against VOC exposure limits.
Product Type:
Formulation physics dictates application precision and dosing control across professional and consumer channels.
- Liquid Cleaners:Surfactant-solvent blends in aqueous or alcohol bases dominate art supply and cosmetic applications where controlled saturation prevents bristle damage. Demand concentrates in California and EU markets where CARB and REACH VOC caps restrict petroleum-derived alternatives.
- Solid Cleaners:Concentrated soap bars and balm formulations eliminate spill risk and reduce shipping weight for travel retail and professional kit assembly. German cosmetic manufacturers are expanding solid format procurement to meet EU Green Deal packaging reduction targets.
- Spray Cleaners:Aerosol and pump-dispersed solvents deliver targeted application for industrial brush maintenance in automotive paint booths.
- Wipes:Pre-saturated towelettes serve on-location cosmetic artists and field maintenance crews requiring portability without liquid transport compliance.
Liquid cleaners lead on scale; solid cleaners lead on momentum.
Material:
Raw material sourcing separates premium certified formulations from commodity blends in procurement evaluations.
- Synthetic:Petroleum-derived surfactants and glycol ethers remain cost-competitive for heavy-duty industrial residue removal where biodegradability certification is not contractually mandated.
- Natural:Plant-derived solvents from citrus terpenes and pine derivatives serve art supply channels seeking reduced odor profiles in studio environments.
- Biodegradable:Alkyl polyglucoside and enzymatic systems degrade under OECD 301B testing protocols. EU automotive OEMs in Germany and France are mandating biodegradable brush cleaners for ESG disclosure compliance, accelerating formulation investment.
- Chemical-Based:Chlorinated and aromatic hydrocarbon blends persist in aerospace and marine coating maintenance where epoxy and polyurethane removal demands aggressive solvent action.
Biodegradable materials climb the fastest; chemical-based formulations retain the largest installed base.
Container Type:
Packaging format selection reflects distribution channel requirements and refill system economics.
- Bottle:HDPE and PET containers with precision-dose caps dominate professional art supply and cosmetic bulk procurement. German retailers are piloting refill station networks to reduce single-use plastic intensity under EU CSRD extended producer responsibility frameworks.
- Jar:Wide-mouth containers accommodate solid cleaner and balm formats popular in premium cosmetic brush care kits.
- Tube:Collapsible aluminum and laminate tubes serve travel-size cosmetic segments and field maintenance kits where space efficiency outweighs unit cost.
- Spray Can:Pressurized aerosol systems deliver solvent blends for industrial brush cleaning stations in automotive manufacturing facilities.
Bottles lead on volume; jars gain share fastest in premium repositioning.
Usage:
End-use specifications diverge on residue type, hygiene standards, and workplace exposure protocols.
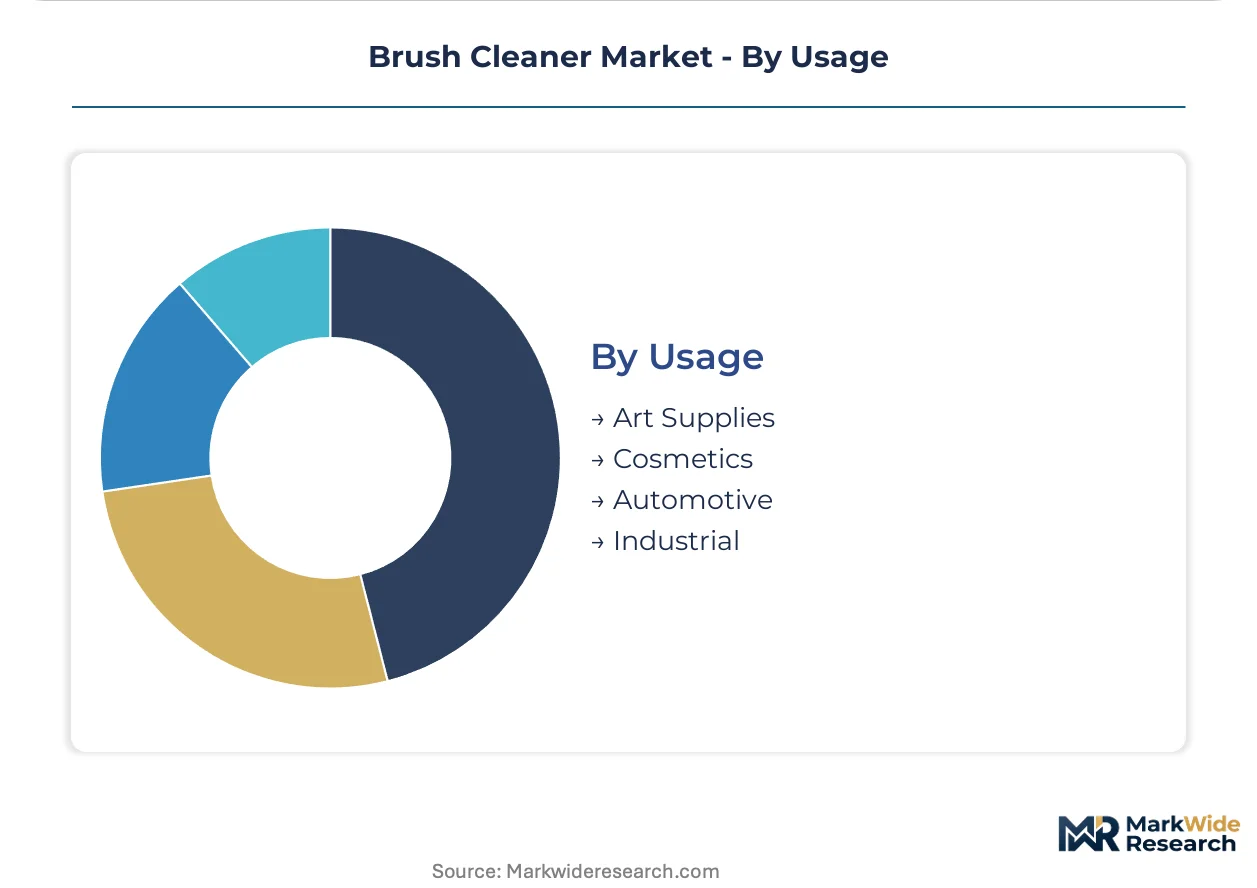
- Art Supplies:pH-neutral formulations preserving natural hair and synthetic bristle integrity dominate professional artist procurement. California art supply distributors face CARB VOC limits that exclude mineral-spirit alternatives from retail shelves.
- Cosmetics:FDA cosmetic safety standards and EU 1223/2009 regulations mandate preservative-free or low-phenoxyethanol formulations for facial brush applications. Clean beauty certification programs in France and Italy are consolidating supplier relationships around ESG-verified partners.
- Automotive:Tier-1 paint application suppliers in Germany and the US Midwest mandate solvent-free cleaning protocols to reduce workplace exposure incidents and meet customer ESG disclosure requirements.
- Industrial:Heavy acrylic, epoxy, and adhesive removal in coating and composite manufacturing drives demand for high-solvency formulations despite regulatory pressure.
Industrial usage leads on scale; cosmetics usage shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and industrial brush maintenance specialists cluster in Germany, California, and the UK, anchoring regional innovation hubs for solvent-free chemistry and automotive OEM compliance protocols.
Germany
Automotive paint application suppliers in Stuttgart and Munich mandate solvent-free brush cleaners for ESG disclosure compliance. REACH Annex XIV authorization deadlines eliminate chlorinated solvents from industrial formulations by 2026. Bavarian chemical manufacturers invest in captive alkyl polyglucoside synthesis to secure biodegradable surfactant supply.
United States
California art supply distributors face CARB VOC caps that exclude mineral-spirit alternatives from retail shelves. EPA emission standards compress formulation options for petroleum-based cleaners in Midwest automotive plants. Chicago and Detroit industrial clusters retrofit cleaning stations for water-based enzymatic systems.
United Kingdom
London-based cosmetic contract manufacturers consolidate supplier relationships around ESG-verified partners for clean beauty certification. UK REACH divergence from EU frameworks creates dual compliance burdens for cross-border formulators. Manchester industrial brush users adopt pH-neutral protocols for aerospace coating maintenance.
France
Parisian luxury cosmetic houses drive demand for preservative-free brush cleaners meeting EU 1223/2009 standards. ANSM cosmetic safety inspections accelerate reformulation away from phenoxyethanol preservatives. Lyon chemical clusters specialize in immobilized enzyme production for premium art supply channels.
India
Mumbai and Bengaluru contract manufacturers expand solvent-free brush cleaner procurement as CDSCO aligns with EU cosmetic safety standards. Domestic surfactant producers invest in alkyl polyglucoside capacity to reduce import dependence from Western Europe. Gujarat chemical parks host pilot biodegradable formulation facilities for export markets.
Brush Cleaner Market Competitive Environment
Top-tier vendors anchor premium biodegradable formulations, while commodity mineral-spirit blenders defend volume positions in industrial maintenance contracts. The vendor base stratifies across three archetypes: synthetic-bristle specialists securing automotive OEM programs, enzymatic chemistry innovators capturing clean beauty premiums, and geographic consolidators dominating regional distribution networks. Competitive moves concentrate on strategic partnerships with surfactant suppliers and portfolio diversification into solid-format cleaners.
Among North American fabricators, Gordon Brush and Tanis Brush exemplify divergent positioning strategies. Gordon Brush occupies a position within the synthetic-bristle specialization archetype, serving industrial maintenance contracts through material expertise. Tanis Brush represents geographic consolidation logic, anchoring automotive OEM programs through proximity to Midwest manufacturing clusters. Schaefer Brush Manufacturing sits within the R&D-intensive tier, reflecting investment patterns in biodegradable surfactant chemistry visible across German industrial brush supply chains.
| Leading Market Players |
|---|
| Schaefer Brush Manufacturing |
| Precision Brush |
| Brush Research Manufacturing |
| Mill-Rose |
| Cocker-Weber Brush Company |
| Kumex Industrial Brushes |
| Gordon Brush |
| Tanis Brush |
| Osborn International |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap German chemical manufacturers anchor supply-side discipline through captive alkyl polyglucoside synthesis, translating raw material control into pricing power for biodegradable brush cleaner formulations. This ownership pattern insulates premium-tier producers from petroleum distillate volatility while compressing margins for commodity mineral-spirit blenders dependent on spot naphtha markets.
Pricing Analysis
Bundled concentrate-plus-refill service contracts separate premium biodegradable suppliers from transactional mineral-spirit vendors. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: OECD 301B-validated enzymatic formulations command brand premiums, CARB-compliant mid-tier products compete on volume scale, and unclassified petroleum blends face price erosion from crude-linked input costs. Cosmetic OEMs in California and France show least price sensitivity due to clean beauty disclosure mandates, while Midwest automotive maintenance contractors prioritize unit cost minimization.
Supply Chain Analysis
Domestic-content mandates under EU Green Deal extended producer responsibility frameworks are reshaping sourcing patterns for North American formulators seeking European market access. Biodegradable surfactant production clusters in Germany, France, and the Netherlands supply alkyl polyglucoside and immobilized enzyme inputs. Supply chains rest on citrus terpene feedstocks from Mediterranean agricultural processors and pine derivative extraction from Nordic forestry operations. Single-source vulnerability concentrates in Western European specialty surfactant synthesis. Distribution runs through direct procurement relationships between formulators and beauty brand technical teams, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in enzymatic formulation premiums and solid-format packaging economics, with biodegradable certification investments compressing per-unit costs through volume scale in EU and California procurement channels.
For Market Incumbents: Acquire captive surfactant synthesis capacity to secure supply chain autonomy against REACH Annex XIV substitution deadlines. German automotive OEM brush maintenance contracts require solvent-free certification investment to defend positioning against emerging enzymatic chemistry specialists. Consolidate formulation chemist talent through targeted recruitment in green chemistry programs. For New Entrants and Emerging Players: Mumbai and Bengaluru contract manufacturers represent an underserved buyer archetype as CDSCO aligns with EU cosmetic safety standards. White-space targets include solid-format balm production for travel retail and pH-neutral robotic maintenance formulations for aerospace coating facilities. Direct technical sales to beauty brand R&D teams bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mineral-spirit commodity blenders facing regulatory displacement, while enzymatic chemistry innovators capture scarcity premiums. Long-term viability favors formulators with OECD 301B certification infrastructure and refill system economics. The signal to watch is California CARB enforcement intensity against non-compliant art supply distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Synthesis | Captive alkyl polyglucoside production secures supply against REACH registration bottlenecks. |
| Enzymatic Formulation Certification | OECD 301B validation unlocks premium pricing in EU automotive OEM procurement channels. |
| Solid Format Product Line Expansion | EU Green Deal packaging reduction targets accelerate German cosmetic manufacturer adoption. |
| Direct Procurement Relationship Development | Blockchain-anchored ESG certificates displace fragmented distributor networks in California. |
| Refill Station Network Pilot | Extended producer responsibility frameworks incentivize take-back programs under EU CSRD. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with formulation chemists, cosmetic brand technical directors, automotive Tier-1 procurement managers, and industrial maintenance supervisors combined with secondary validation from REACH registration databases, EPA VOC emission filings, CARB compliance records, and EU CSRD disclosure frameworks. Trade flow analysis of alkyl polyglucoside and citrus terpene imports anchored geographic supply concentration assessments.
Input-output matrices map formulation chemistry inputs through packaging modalities to end-use compliance requirements across the projection horizon. Segmentation dimensions span product type, material certification tier, container format, and usage channel. CAGRs derive from elasticity-adjusted demand curves incorporating regulatory phase-in schedules and substitution elasticity estimates between petroleum-derived and bio-based alternatives. Forecast inputs include enzymatic stability degradation curves and surfactant production capacity expansion timelines.
Underlying measurement precision varies by segment; biodegradable materials and cosmetics usage carry tighter precision than industrial chemical-based formulations due to certification standardization. Forecasts reflect documented assumptions regarding REACH enforcement intensity and CARB compliance verification rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Fabric Care Market
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Janitorial Cleaning Equipment and Supplies Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Car Wash Detergents and Soaps Market