
 Fabric Freshener Market | 2026-2036
Fabric Freshener Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Freshener Market Foresight
Asset-light contract manufacturing is reconfiguring competitive dynamics in fabric fresheners, allowing challenger brands to scale without capital-intensive production facilities. Procter & Gamble leverages its captive supply network and R&D infrastructure to sustain formulation leadership across multiple delivery formats. Reckitt Benckiser anchors its position through concentrated pod innovations that command premium placement in European retail channels. Henkel competes via specialized industrial-grade solutions tailored to hospitality and healthcare laundering operations.
Fabric fresheners comprise aqueous or aerosol formulations containing odor-neutralizing compounds, fragrance encapsulation systems, and surface-active agents designed to refresh textiles between washes or extend wear cycles. Spray formats dominate household penetration due to immediate application convenience, while pod systems represent the fastest-growing structural segment as unit-dose convenience reshapes consumer purchasing patterns. The hospitality application channel commands distinct margin pools through institutional volume contracts and customized scent branding programs. Synthetic formulations retain volume leadership, though natural ingredient segments are gaining shelf space amid clean-label procurement shifts.
EPA Safer Choice standards and EU REACH chemical registration frameworks are tightening permissible volatile organic compound thresholds, compelling reformulation investments across multinational portfolios. The EU F-Gas Regulation and state-level California Air Resources Board mandates are accelerating propellant transitions in aerosol delivery systems. Stakeholders must monitor evolving biodegradability certifications and regional chemical disclosure requirements to maintain market access and avoid compliance-driven SKU rationalization.
Market Dynamics
Pod-based delivery systems are compressing traditional spray format margins while EPA Safer Choice mandates force surfactant chemistry overhauls across manufacturer portfolios.
Growth Catalysts
- Post-pandemic hospitality protocols:North American hotel chains are institutionalizing linen refresh programs between guest stays, creating recurring volume demand for industrial-grade formulations.
- REACH chemical registration frameworks:EU regulatory pressure on volatile organic compounds is accelerating biodegradable surfactant adoption, opening shelf space for reformulated product lines.
- Fragrance encapsulation systems:Microencapsulation technology enables extended-release scent profiles that command premium positioning in pod formats.
Market Restraints
- Propellant transition costs:California Air Resources Board mandates on hydrofluorocarbon propellants require aerosol line retooling, compressing margins for legacy format manufacturers.
- Biodegradable surfactant supply concentration:Specialty chemical producers in Germany and Switzerland control key input streams for EPA-compliant formulations, creating procurement bottlenecks.
- Technical performance gaps:Natural ingredient bases demonstrate shorter efficacy windows against synthetic counterparts, limiting clean-label product penetration in institutional contracts.
Strategic Opportunities
- Healthcare laundering verticals:Hospital systems in the United States are adopting fabric freshener protocols for patient gown and linen management between sterilization cycles.
- EU F-Gas Regulation tailwinds:Compressed air and mechanical spray systems qualify for regulatory preference, rewarding early movers in propellant-free delivery innovation.
- Direct-to-institution channels:Bypassing traditional retail distribution through hospitality supply cooperatives captures margin pools previously allocated to wholesale intermediaries.
Industry Challenges
- Formulation chemistry expertise scarcity:Biodegradable surfactant R&D requires specialized talent pools concentrated in Basel and Ludwigshafen chemical clusters.
- Safer Choice certification timelines:EPA review cycles for ingredient disclosure and toxicity testing extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Freshener Market |
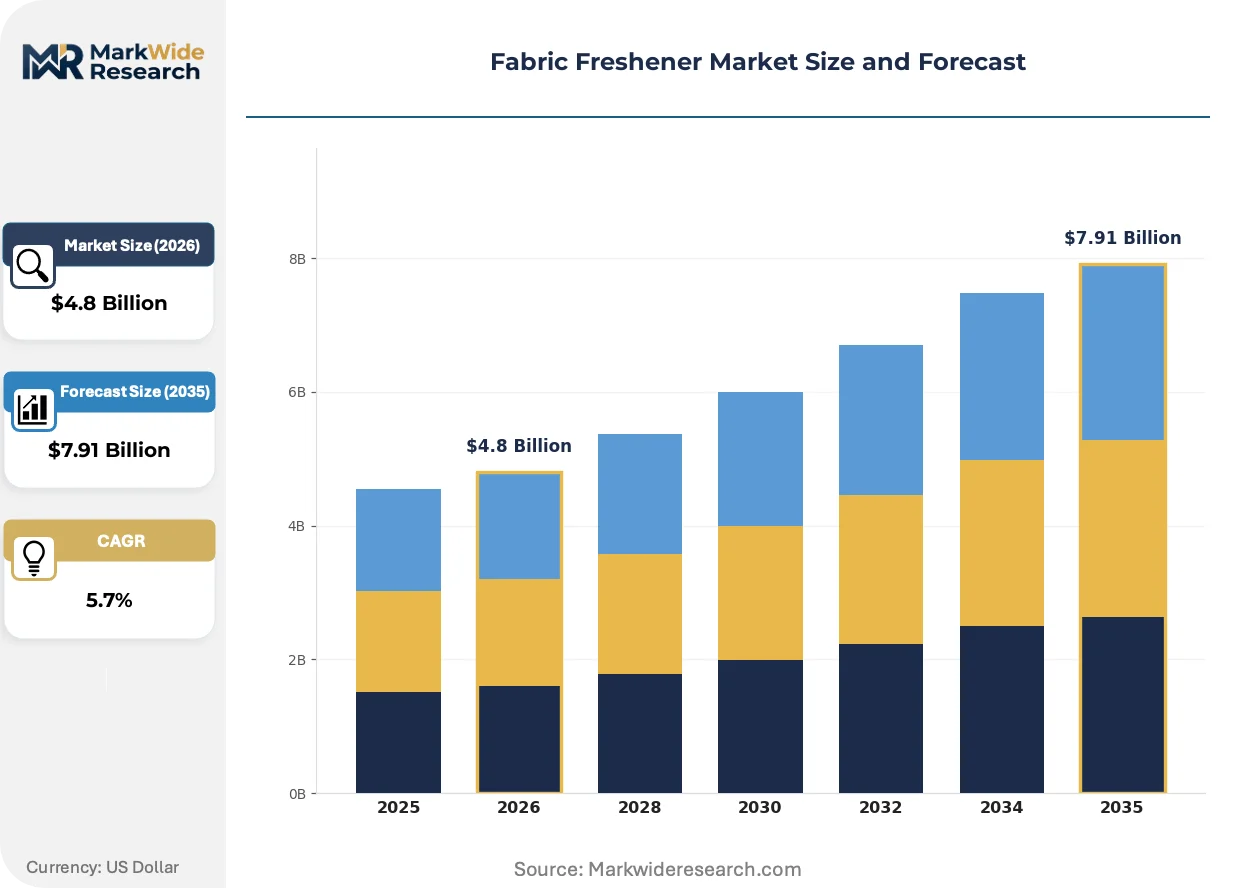
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Pods, Liquid, Sheet Application: Household, Industrial, Hospitality, Automotive Formulation: Natural, Synthetic, Concentrated, Ready-to-Use Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Drugstores |
| Companies Covered | Procter & Gamble, Reckitt Benckiser, Henkel, SC Johnson & Son, Clean Control Corporation, Kao Corporation, Church & Dwight, The Clorox Company, Godrej Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Freshener Market Shifts & Advancements
Delivery format innovation and chemical transparency mandates are restructuring competitive advantage around formulation chemistry rather than brand equity alone.
Microencapsulated fragrance technology is migrating from premium household segments toward institutional hospitality applications. Hotel operators in Florida and Arizona are piloting extended-wear linen programs using slow-release scent systems. The technology is migrating from consumer convenience positioning toward operational cost reduction in high-volume laundering environments.
EU F-Gas Regulation phase-down schedules are forcing propellant transitions in aerosol delivery systems. Manufacturers must reformulate pressurized products using compressed air or nitrogen alternatives. German and French retail channels are experiencing accelerated SKU turnover as non-compliant inventory exits distribution.
Unit-dose pod purchasing is displacing bulk spray replenishment cycles in United States mass retail. Walmart and Target are reallocating shelf space toward concentrated formats that reduce shipping weight and storage footprint. This behavioral shift concentrates procurement power with retailers capable of managing complex pod supply chains.
Fabric Freshener Market Segmentation
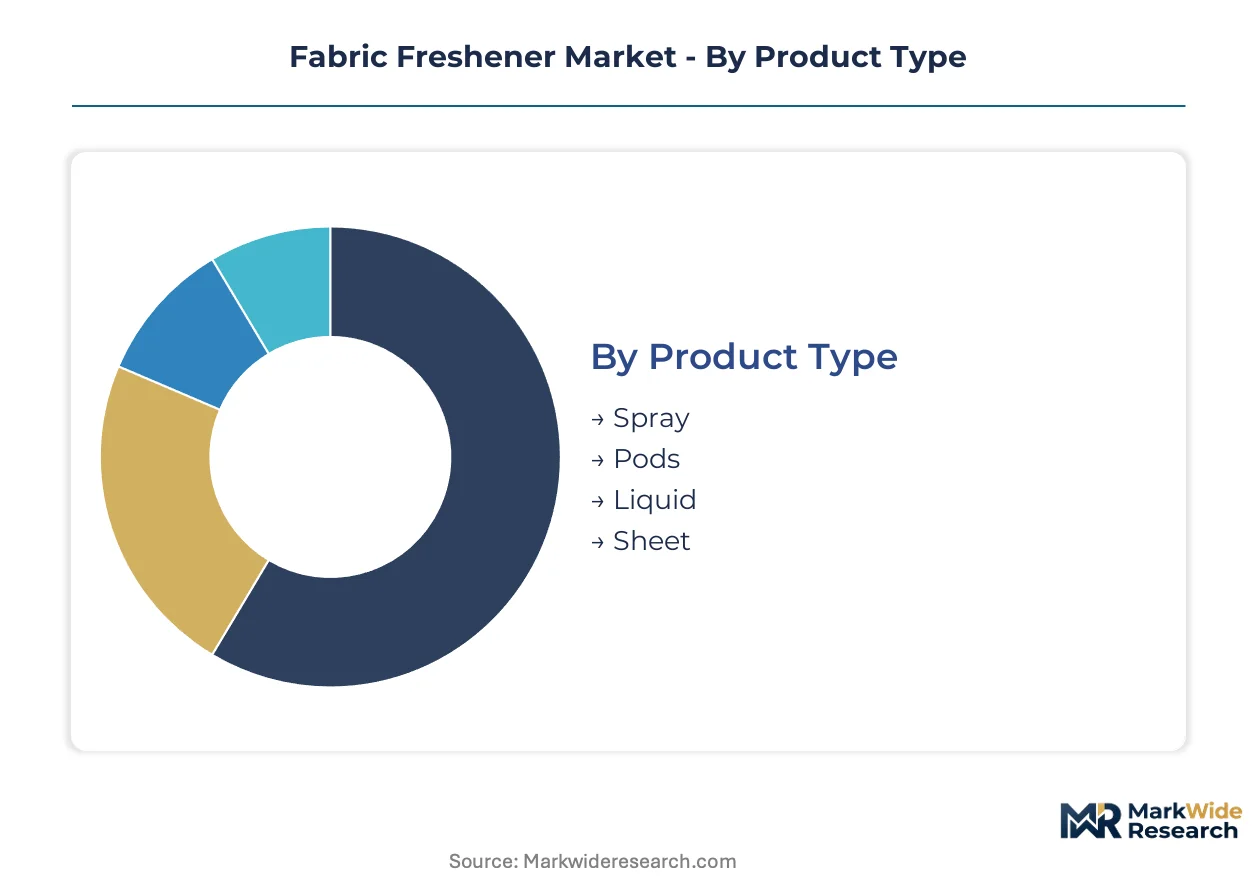
Segmentation in fabric fresheners reveals how delivery format preferences diverge sharply between household convenience buyers and institutional volume purchasers. Regulatory chemistry constraints and retail shelf-space economics create distinct margin architectures across each category boundary.
Product Type:
Mature spray formats coexist with emerging pod systems that are compressing traditional margin structures through unit-dose convenience.
- Spray:Aqueous or aerosol formulations dispensed through trigger mechanisms or pressurized canisters, typically containing fragrance oils, surfactants, and propellant systems. Demand concentrates in United States mass retail channels where immediate application convenience drives repeat purchase cycles, though California Air Resources Board mandates on hydrofluorocarbon propellants force ongoing reformulation investments.
- Pods:Pre-measured, water-soluble film pouches containing concentrated active ingredients that dissolve in washing machines or spray bottles upon dilution. Hospitality chains in Florida and Arizona are piloting extended-wear linen programs using pod-based slow-release scent systems, reducing operational costs in high-volume laundering environments.
- Liquid:Pourable concentrate formulations requiring manual dilution or direct application to textiles, common in industrial and commercial settings.
- Sheet:Fabric softener-style sheets infused with fragrance compounds for dryer-cycle deployment or drawer storage applications.
Spray retains volume leadership; pods hold the steepest expansion curve.
Application:
Cost tier separation distinguishes high-frequency household replenishment from contract-negotiated institutional procurement.
- Household:Consumer-grade formulations packaged for residential use, emphasizing ease of application and fragrance variety over chemical concentration. Walmart and Target are reallocating shelf space toward concentrated formats that reduce shipping weight and storage footprint, concentrating procurement power with retailers managing complex pod supply chains.
- Hospitality:Industrial-grade solutions tailored to hotel linen refresh programs between guest stays, featuring customized scent branding and bulk dispensing systems. North American hotel chains are institutionalizing these protocols amid post-pandemic hygiene requirements, creating recurring volume demand through multi-year supply contracts.
- Industrial:Large-scale formulations for manufacturing and processing facilities with specialized odor-neutralization requirements.
- Automotive:Compact, vehicle-specific applications for upholstery and interior textile refreshment.
Household commands absolute volume; hospitality delivers superior per-unit margins through contract structures.
Formulation:
Supply concentration in specialty chemical clusters shapes competitive access to compliant input streams.
- Synthetic:Petrochemical-derived surfactants and fragrance compounds offering extended efficacy windows and stable performance across temperature variations. Institutional contracts in the United States continue favoring synthetic bases due to proven technical performance, though EPA Safer Choice certification timelines extend product launch windows by 18-24 months for reformulated portfolios.
- Natural:Plant-derived or biodegradable ingredient bases including essential oils, enzymatic odor neutralizers, and surfactants from renewable feedstocks. EU REACH chemical registration frameworks are accelerating biodegradable surfactant adoption, opening shelf space for reformulated product lines in German and French retail channels.
- Concentrated:Reduced-water formulations requiring dilution prior to application, common in pod and liquid industrial formats.
- Ready-to-Use:Pre-diluted formulations for immediate application without consumer preparation steps.
Synthetic formulations retain institutional dominance; natural segments are climbing the fastest in European retail channels.
Distribution Channel:
Geography of procurement behavior separates digital-native convenience purchasing from planned stock-up trips.
- Supermarkets:Brick-and-mortar mass retail channels with high-frequency foot traffic and prominent shelf placement negotiations. The United States market shows demand concentrating here where premium pod formats are gaining shelf space in major retail channels, though behavioral shifts toward unit-dose purchasing are compressing traditional spray format margins.
- Online Retail:E-commerce platforms enabling subscription replenishment and direct-to-consumer brand building. Direct-to-institution channels through hospitality supply cooperatives are capturing margin pools previously allocated to wholesale intermediaries.
- Convenience Stores:Small-format retail with impulse-purchase positioning and limited SKU assortment.
- Drugstores:Health-and-wellness oriented retail channels emphasizing clean-label and hypoallergenic product positioning.
Supermarkets retain transaction volume leadership; online retail is expanding most quickly in subscription pod formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Safer Choice certification timelines and EU REACH chemical registration frameworks are redrawing procurement boundaries for fabric freshener manufacturers across major economies. Regulatory chemistry constraints now determine market access more than brand recognition.
United States
Post-pandemic hospitality protocols in Florida and Arizona are institutionalizing linen refresh programs between guest stays. The EPA's Safer Choice certification is pushing manufacturers toward biodegradable surfactant reformulations with 18-24 month review cycles. Walmart and Target in the Southeast are reallocating shelf space toward concentrated pod formats that reduce shipping weight.
Germany
Specialty chemical producers in Ludwigshafen and Basel clusters control key input streams for compliant formulations. The EU F-Gas Regulation is accelerating propellant transitions in aerosol delivery systems, forcing compressed air alternatives. German retail channels are experiencing accelerated SKU turnover as non-compliant inventory exits distribution.
France
Hotel operators in Provence-Alpes-Côte d'Azur are piloting extended-wear linen programs using slow-release scent systems. ANSM fragrance safety assessments are tightening disclosure requirements for encapsulated compounds. Paris-based hospitality supply cooperatives are capturing margin pools previously allocated to wholesale intermediaries.
China
Dual carbon goals under MEE oversight are pressuring petrochemical-derived surfactant producers toward renewable feedstocks. The Yangtze River Delta manufacturing belt is consolidating aqueous formulation capacity for export markets. Shanghai retail channels are testing unit-dose pod formats adapted from European design templates.
United Kingdom
Healthcare laundering verticals in London and the Midlands are adopting fabric freshener protocols for patient gown management between sterilization cycles. The UK Environment Agency is aligning chemical disclosure rules with REACH frameworks post-Brexit. Manchester-based contract manufacturers are scaling asset-light production for challenger brands.
Fabric Freshener Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base organizes around three archetypes: multinational conglomerates with captive supply networks, mid-scale regional formulators with hospitality specialization, and asset-light contract manufacturers enabling challenger brand entry. Consolidation pressure concentrates in aerosol format retooling and biodegradable surfactant R&D partnerships.
Among conglomerate-tier fabric freshener suppliers, Procter & Gamble, Reckitt Benckiser, and Henkel occupy positions defined by supply network scale and formulation infrastructure depth. Procter & Gamble exemplifies the captive manufacturing archetype with integrated R&D-to-retail control. Reckitt Benckiser represents concentrated pod innovation positioning. Henkel anchors the industrial-grade specialization vector for hospitality and healthcare verticals.
| Leading Market Players |
|---|
| Procter & Gamble |
| Reckitt Benckiser |
| Henkel |
| SC Johnson & Son |
| Clean Control Corporation |
| Kao Corporation |
| Church & Dwight |
| The Clorox Company |
| Godrej Consumer Products |
| Others |
Supply & Pricing Matrix
Overcapacity in German specialty surfactant facilities is compressing input costs for EPA-compliant formulations while simultaneously eroding pricing power among mid-tier contract manufacturers serving North American retail channels.
Pricing Analysis
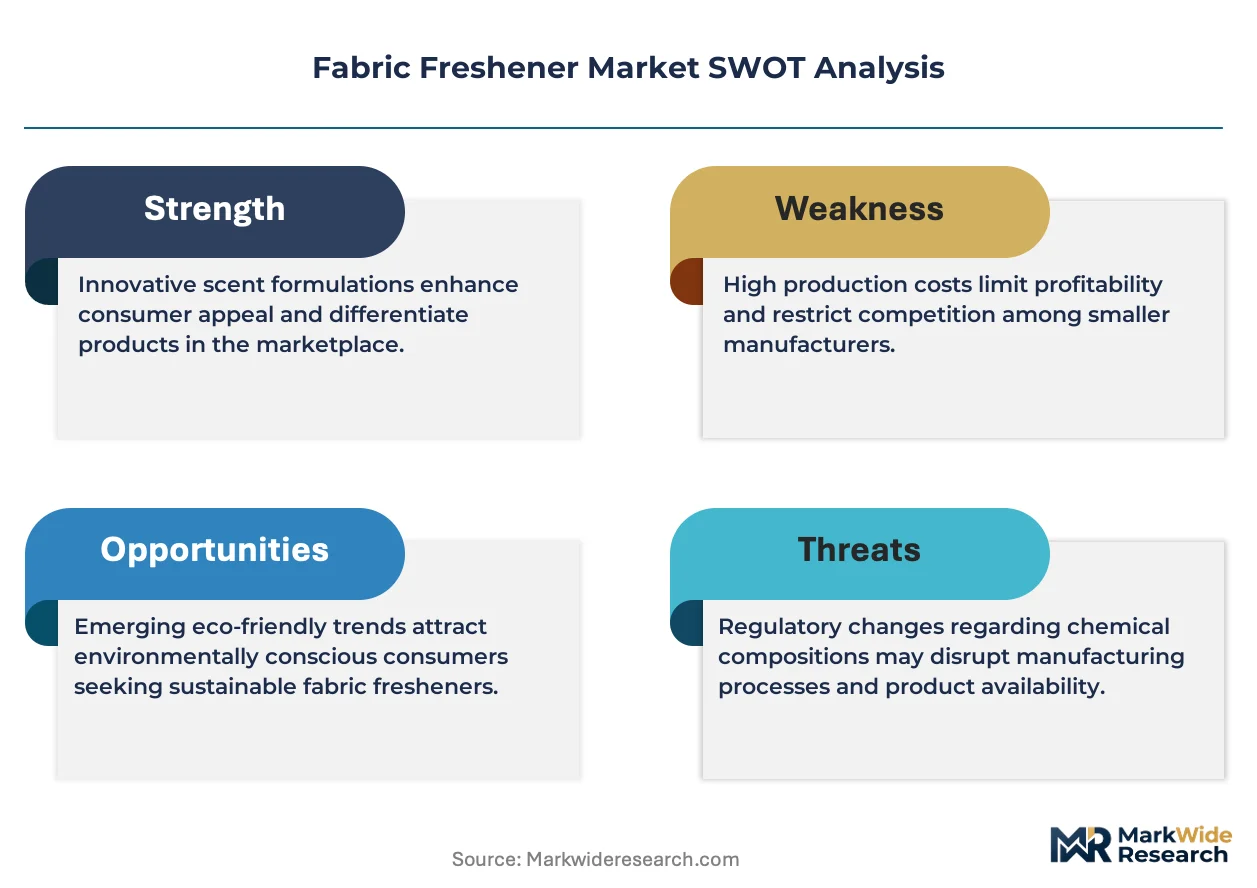
Certification level creates the primary spread across fabric freshener tiers, with EPA Safer Choice and EU REACH-compliant formulations commanding premium positioning against uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by biodegradability grade and fragrance encapsulation technology. Pricing pressure stems from California Air Resources Board mandates forcing aerosol line retooling investments. Mass retail buyers exhibit highest price sensitivity, while hospitality procurement through multi-year contracts demonstrates lowest sensitivity due to operational cost reduction priorities.
Supply Chain Analysis
Asset-light contract manufacturers in Manchester, Basel, and Ludwigshafen hold dominant capacity for biodegradable surfactant formulation. Supply concentrates in Germany, Switzerland, and the United States for compliant input streams. Key dependencies include plant-derived surfactants, microencapsulated fragrance compounds, and water-soluble pod films. Single-source vulnerability in German specialty chemical clusters poses structural risk. Distribution runs through hospitality supply cooperatives, mass retail chains, and direct-to-institution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from concentrated pod formats displacing traditional spray replenishment cycles, requiring defensive repositioning around formulation chemistry expertise and captive supply networks.
For Market Incumbents: Build regulatory certification moats through accelerated EPA Safer Choice portfolio conversion and EU REACH pre-registration investments. Deepen backward integration into biodegradable surfactant production via Ludwigshafen and Basel cluster partnerships to secure input access. Counter pod-format challengers by controlling hospitality supply cooperative channels through multi-year linen refresh program contracts.
For New Entrants and Emerging Players: Healthcare laundering verticals in the United States represent underpenetrated white-space with lowest incumbent saturation. Target hospital systems adopting patient gown refresh protocols between sterilization cycles as anchor accounts. Deploy direct-to-institution sales models bypassing wholesale intermediaries to capture margin pools.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hospitality supply cooperatives with multi-year linen refresh contracts. Five-to-ten year viability favors acquisition targets with EPA Safer Choice certification pipelines and established pod-format manufacturing partnerships. Monitor California Air Resources Board enforcement timelines as inflection signal for aerosol-dependent portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Backward Integration | Captures Ludwigshafen and Basel cluster capacity to secure EPA-compliant input streams. |
| Pod Format Manufacturing Scale-Up | Aligns with Walmart and Target shelf space reallocation toward concentrated unit-dose formats. |
| EPA Safer Choice Certification Pipeline | Accelerates 18-24 month review cycles to preempt regulatory-driven SKU rationalization. |
| Hospitality Supply Cooperative Partnership | Bypasses wholesale intermediaries to capture margin pools in Florida and Arizona linen programs. |
| Compressed Air Propellant Transition | Qualifies for EU F-Gas Regulation preference while avoiding California Air Resources Board penalties. |
Research Methodology
The analysis maps spray, pod, liquid, and sheet delivery formats, each validated through procurement directors at hospitality chains, category buyers at mass retailers, formulation chemists at specialty surfactant producers, and supply planners at contract manufacturers. Primary interview insights triangulate against customs trade data, EPA Safer Choice certified product registries, EU REACH registration databases, and Nielsen retail audit data. Bottom-up volume modeling reconciles with top-down market sizing across segmentation dimensions.
Assumptions held fixed include regulatory enforcement timelines for EPA Safer Choice and EU F-Gas Regulation, while surfactant feedstock cost trajectories and pod adoption rates varied across sensitivity scenarios. The projection horizon spans delivery format, application channel, formulation type, and distribution channel segments, with CAGRs derived from regression analysis of historical volume patterns and forward-looking procurement intent signals. Forecast inputs incorporate hospitality linen refresh program expansion rates and biodegradable surfactant capacity utilization.
Practitioners should monitor California Air Resources Board enforcement actions, EU F-Gas Regulation phase-down schedules, and German specialty chemical cluster capacity announcements for early signals of forecast revision. Quarterly review of EPA Safer Choice certification timelines and hospitality contract renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Carpet and Rug Shampoo Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Cleaning Trolleys Market