
 Clean Label Preservatives Market | 2026-2036
Clean Label Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Preservatives Market Insights
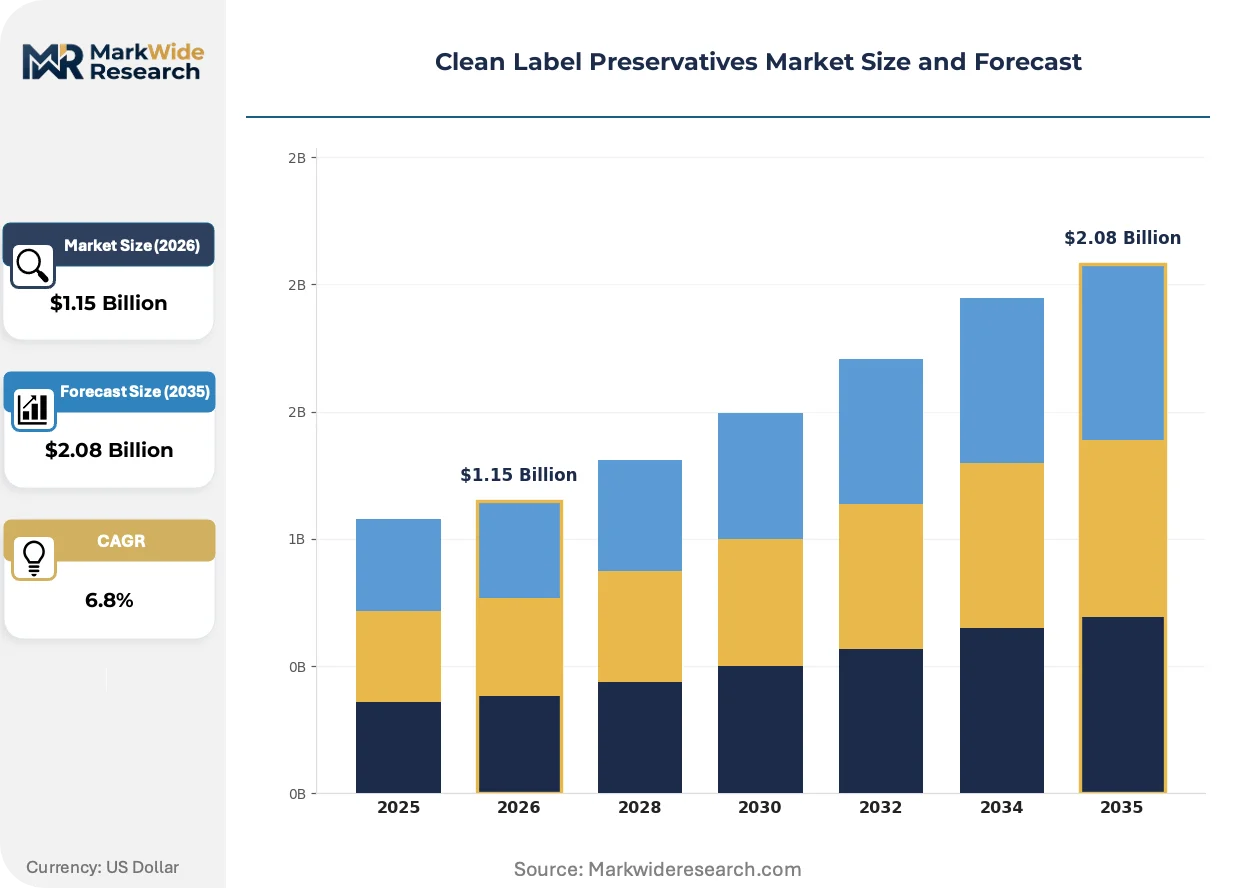
Subscription-based formulation support is restructuring how clean label preservatives reach commercial buyers. Cargill leverages its integrated fermentation infrastructure to supply cultured dextrose and vinegar-based systems at scale. Kerry Group plc anchors European beverage accounts with buffered vinegar and rosemary extract portfolios. DSM-Firmenich AG differentiates through its biotech-derived antimicrobial peptides, competing on performance parity with traditional synthetics.
Clean label preservatives comprise antimicrobial compounds, acidulants, and antioxidant extracts derived from fermentation or botanical sources, typically characterized by recognizable ingredient declarations and exclusion of synthetic chemicals such as benzoates or sorbates. These substances function primarily to inhibit spoilage organisms, retard oxidative rancidity, and extend shelf stability in processed foods and consumer products without triggering consumer avoidance. Fermented preservatives occupy the deepest margin pools due to capital-intensive bioreactor requirements and limited supplier bases, while plant-based extracts represent the fastest-expanding category as extraction yields and standardization improve. Powder and liquid forms split demand by application velocity, with powders dominating dry-mix bakery and nutritional supplement channels where dosing precision and distribution uniformity matter most.
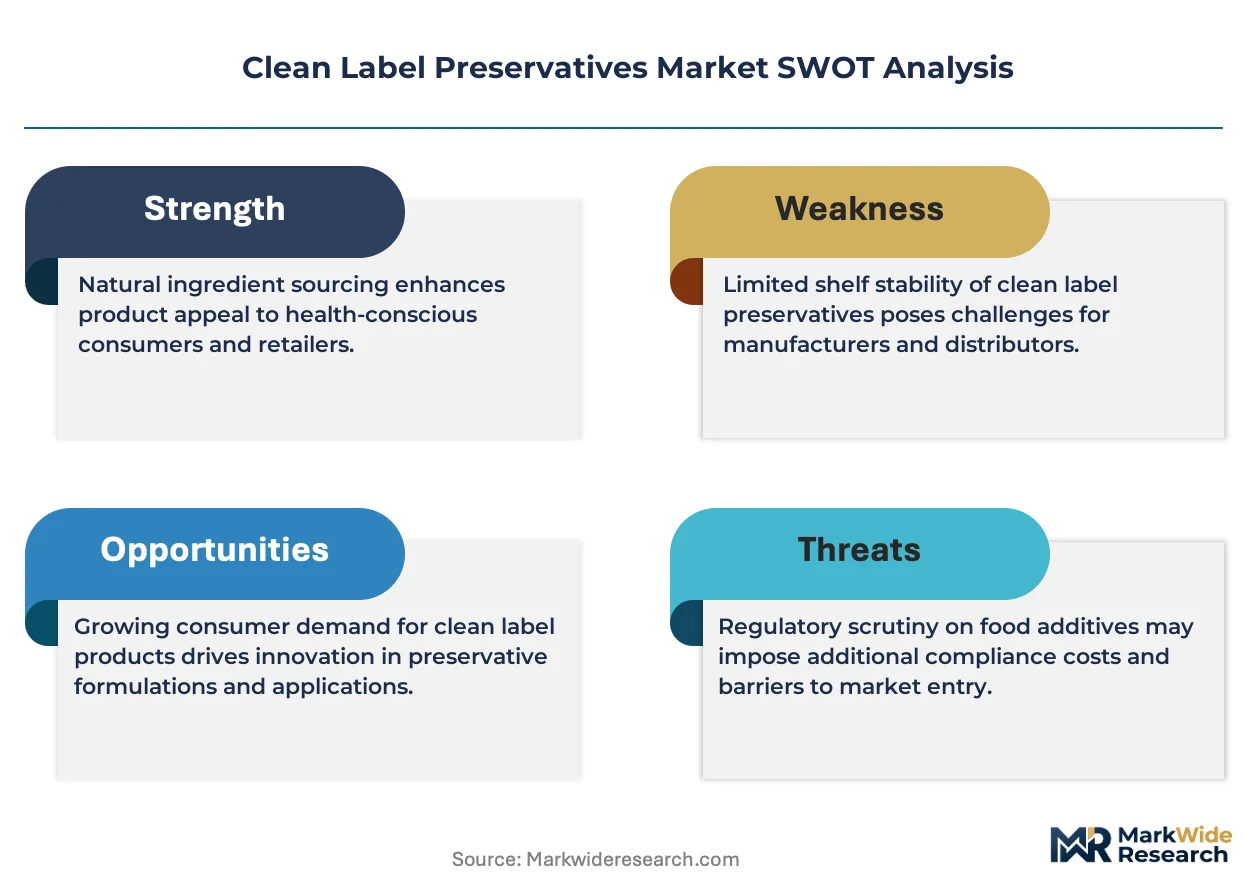
Regulators in the United States, Europe, and Japan are tightening additive approval frameworks, with the FDA maintaining its Generally Recognized As Safe notification pathway and EMA-aligned food safety bodies enforcing EFSA-driven purity benchmarks that synthetic alternatives increasingly fail. REACH and RoHS compliance costs are rising for imported synthetic preservative precursors, tilting procurement toward domestically sourced fermentation and botanical supply chains. Stakeholders must monitor evolving positive-list criteria across multiple jurisdictions and pre-position natural preservative portfolios before regulatory exclusions harden.
Market Dynamics
Fermentation capacity scarcity is compressing formulation timelines as food manufacturers race to replace synthetic preservatives ahead of regulatory deadlines. Clean label preservatives now face a structural bottleneck between bioreactor throughput and reformulation velocity.
Growth Catalysts
- EU F-Gas Regulation:Synthetic additive restrictions are redirecting R&D budgets toward cultured dextrose and vinegar-based systems. Formulation teams accelerate natural preservative trials to maintain shelf-life claims.
- Buffered vinegar technology:Acidulant stabilization advances are expanding clean label viability into high-moisture applications previously dominated by benzoates. Beverage and sauce manufacturers adopt these systems for flavor-neutral preservation.
- Germany:Bakery and dairy premium positioning commands dedicated clean label shelf space. Retailers mandate recognizable ingredient panels as a condition for category captaincy.
Market Restraints
- Bioreactor capital intensity:Fermentation-based antimicrobial production requires specialized stainless-steel infrastructure with extended commissioning timelines. Limited equipment suppliers extend lead times for capacity expansion.
- Botanical extract yield variability:Rosemary and green tea antioxidant concentration fluctuates with harvest conditions and extraction batch consistency. Standardization protocols add processing cost layers.
- EFSA purity benchmarks:Natural preservative approval pathways demand extensive safety dossiers that synthetic alternatives bypass through grandfathered status. Submission backlogs delay market entry.
Strategic Opportunities
- Japan:METI's clean label guidance for processed foods creates first-mover advantage for antimicrobial peptide suppliers. Local partnership requirements favor technology licensing over direct export.
- Active packaging convergence:Oxygen-scavenging films combined with surface-applied fermented preservatives extend protection without ingredient list modification. Meat and seafood processors pilot these hybrid systems.
- Subscription formulation services:Preservative suppliers are embedding technical support into recurring revenue models. Small and mid-sized manufacturers access shelf-life optimization without in-house microbiology teams.
Industry Challenges
- Microbiome assay standardization:Clean label preservative efficacy testing lacks harmonized protocols across retail private label requirements. Divergent spoilage organism panels force redundant validation work.
- Legacy equipment compatibility:Powdered fermented preservatives require modified pneumatic conveying systems to prevent caking and dosing inconsistency. Retrofit costs strain capital planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Preservatives Market |
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Organic, Fermented, Plant-Based End User: Food Manufacturers, Beverage Producers, Personal Care, Pharmaceuticals Application: Food Preservation, Cosmetic Formulations, Nutritional Supplements, Bakery Products Form: Powder, Liquid, Gel, Granule |
| Companies Covered | Cargill, Archer Daniels Midland Company, Kerry Group plc, Tate & Lyle PLC, Ingredion Incorporated, DuPont de Nemours, DSM-Firmenich AG, Corbion, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Preservatives Market Trends and Innovations
Biotechnology-derived preservation systems are compressing the performance gap with synthetic benchmarks while regulatory exclusion lists expand. Three convergent developments are restructuring competitive positioning around scale, certification, and technical service depth.
Antimicrobial peptide platforms derived from lactic acid bacteria fermentation are integrating into high-risk food matrices where plant extracts show insufficient potency. Ready-to-eat meat processors adopt these biotech solutions for listeria control without clean label trade-offs. The technology is integrating into supplier portfolios as a performance tier above traditional cultured dextrose.
REACH authorization requirements for synthetic preservative precursors are tightening import compliance burdens on non-EU chemical suppliers. Domestic fermentation capacity within the European Economic Area commands sourcing preference as downstream liability risks mount. German and Dutch food safety authorities are accelerating natural additive positive-list reviews to fill anticipated supply gaps.
Ingredient declaration transparency has become a procurement filter for retail category managers evaluating supplier partnerships. Clean label preservative buyers now demand full supply chain documentation from fermentation feedstock through final formulation. This verification intensity is most pronounced in German discounter and premium retail channels where consumer litigation exposure concentrates.
Clean Label Preservatives Market Segmentation
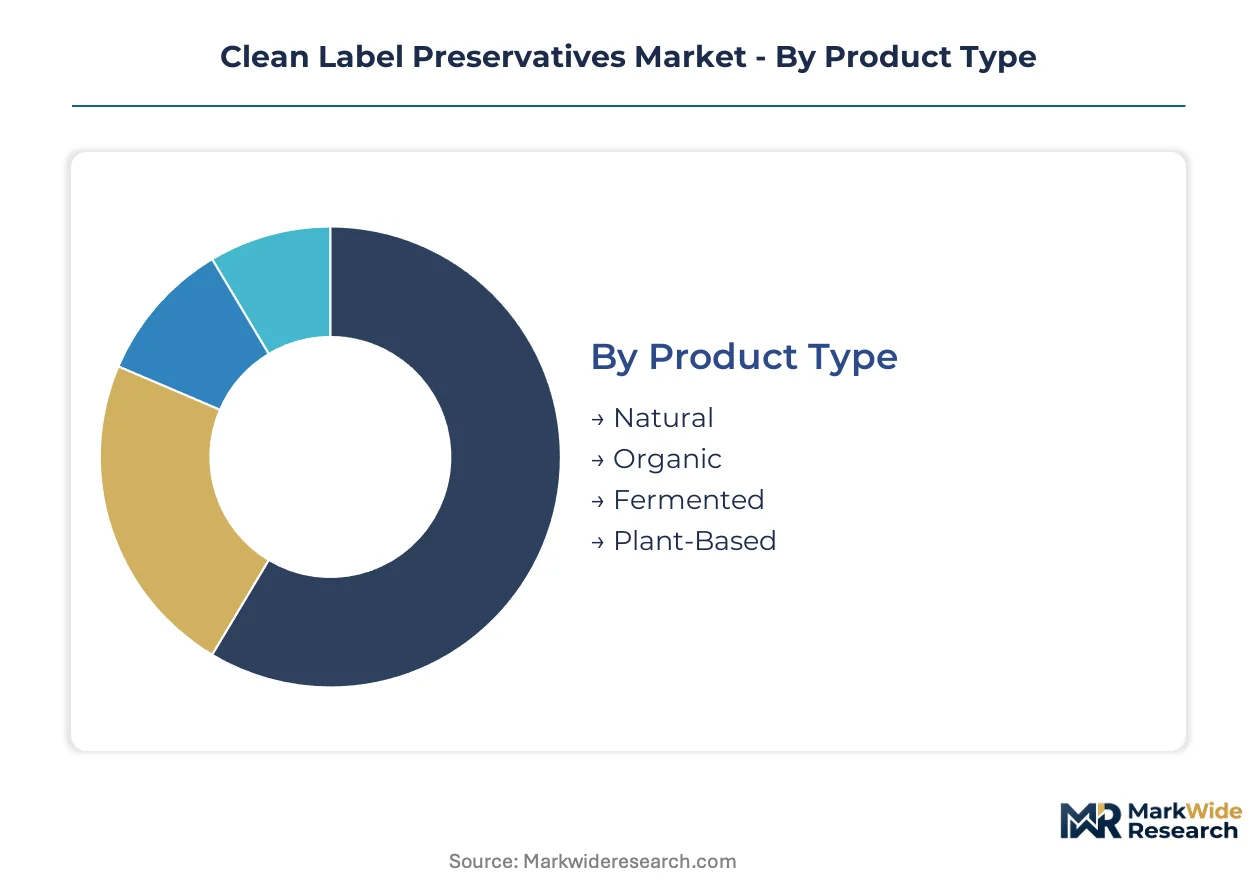
Clean label preservative suppliers configure production assets around distinct technical specifications and end-use requirements. Segmentation reveals where fermentation capacity, extraction yields, and formulation complexity create divergent margin structures across the value chain.
Product Type:
Fermentation technology and botanical sourcing define performance tiers and capital intensity within this axis.
- Fermented:Cultured dextrose and antimicrobial peptides produced via controlled bioreactor environments deliver synthetic-comparable shelf-life extension. Demand concentrates in ready-to-eat meat processing where listeria control requirements are non-negotiable. Bioreactor scarcity extends lead times for new capacity.
- Plant-Based:Rosemary extract, green tea catechins, and citrus-derived flavonoids function as antioxidant preservatives with recognizable ingredient declarations. German bakery and dairy manufacturers prioritize these systems for retail shelf positioning. Harvest variability forces standardization investments that compress margins.
- Natural:Minimally processed acidulants and botanicals meeting broad consumer recognition standards without organic certification overhead.
- Organic:Certified organic preservation systems commanding premium positioning in North American and European natural retail channels.
Fermented leads on scale; plant-based leads on momentum.
End User:
Procurement sophistication and reformulation velocity separate buyer tiers across downstream industries.
- Food Manufacturers:Packaged goods producers drive bulk volume through integrated fermentation supply contracts. EU F-Gas Regulation compliance deadlines accelerate synthetic replacement timelines. Reformulation teams prioritize performance-validated natural alternatives over experimental extracts.
- Beverage Producers:Buffered vinegar systems and cultured dextrose solutions address pH-neutral preservation requirements. High-moisture applications previously dependent on benzoates now adopt flavor-neutral acidulant technologies. Kerry Group anchors this segment with technical service depth.
- Personal Care:Cosmetic formulators seek paraben replacements in emulsion and aqueous systems.
- Pharmaceuticals:Excipient-grade natural preservatives for oral and topical dosage forms with USP-NF compliance requirements.
Food manufacturers dominate procurement volume; beverage producers are expanding most quickly.
Application:
Shelf-life extension requirements and spoilage risk profiles determine specification intensity across use cases.
- Food Preservation:Broad-spectrum antimicrobial systems for processed meats, sauces, and prepared meals where pathogen control is critical. DSM-Firmenich's peptide platforms compete directly with legacy synthetic benchmarks. Regulatory exclusion lists in Europe and Japan redirect R&D investment toward biotech-derived solutions.
- Bakery Products:Mold inhibition in high-moisture baked goods drives demand for cultured wheat and raisin juice concentrates. German retailers mandate clean label ingredient panels as a condition for category captaincy. Powdered formats dominate for distribution uniformity in dry mixes.
- Cosmetic Formulations:Preservation of emulsions and aqueous personal care products against yeast and mold.
- Nutritional Supplements:Oxidation prevention in oil-based softgels and powdered formulations with extended stability requirements.
Food preservation commands the deepest technical requirements; bakery products are gaining share fastest.
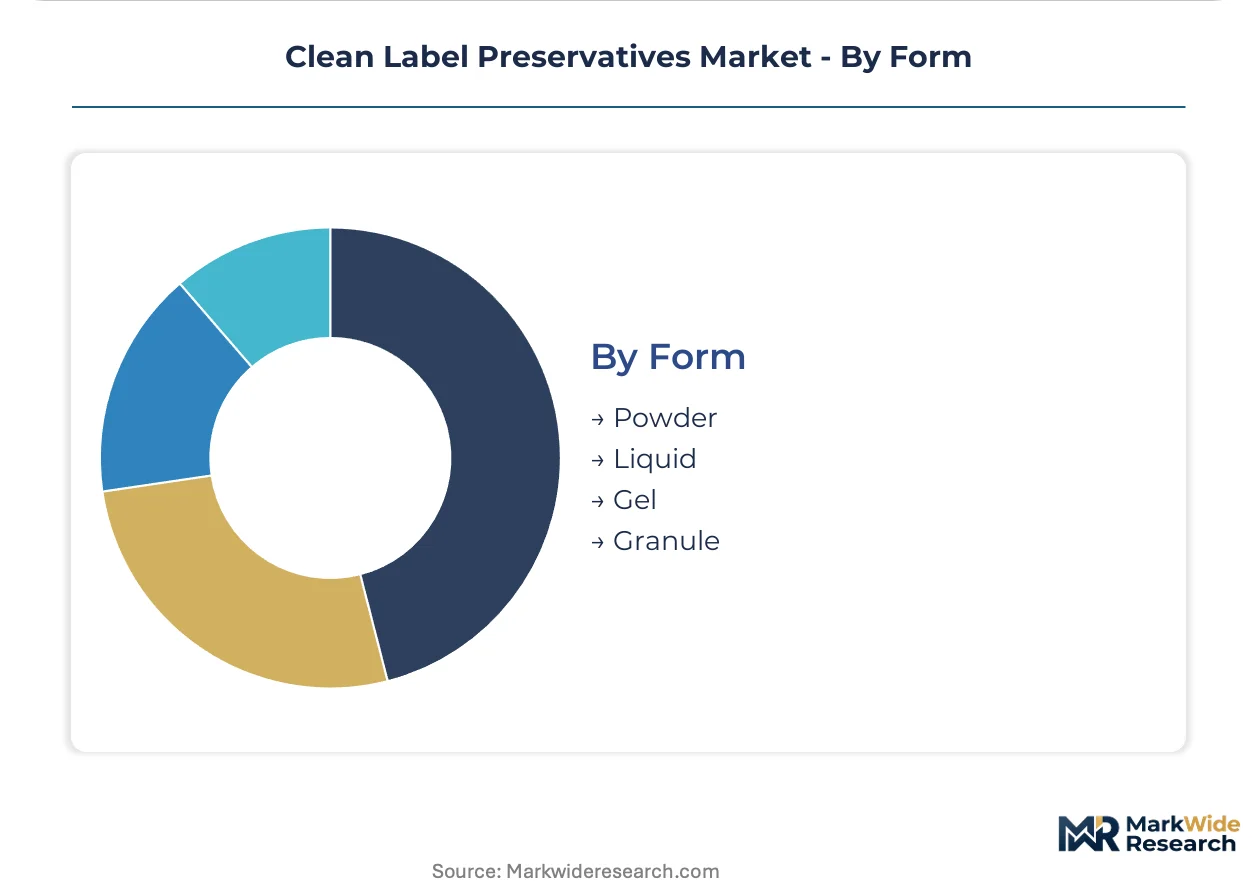
Form:
Physical state determines handling infrastructure compatibility and dosing precision across manufacturing environments.
- Powder:Free-flowing fermented preservatives and botanical extracts for dry-mix applications. Pneumatic conveying modifications prevent caking and dosing inconsistency. Nutritional supplement and bakery channels prioritize this format for batch uniformity.
- Liquid:Buffered vinegar systems and aqueous extracts for beverage and sauce manufacturing. Direct pump integration reduces handling complexity. Cargill's integrated fermentation infrastructure supplies at scale.
- Gel:Thickened preservation systems for topical cosmetic and pharmaceutical applications.
- Granule:Intermediate particle size for controlled dissolution in specific processing conditions.
Powder leads installed base; liquid is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium shelf positioning for clean label bakery and dairy applications, while the United States drives fermentation capacity investment through FDA's GRAS notification pathway. Regulatory divergence between EU F-Gas restrictions and Japan's METI clean label guidance is redirecting supplier investment toward multi-jurisdictional compliance infrastructure.
Germany
Retail category captains mandate recognizable ingredient panels as a condition for shelf access, concentrating procurement power with Rewe, Edeka, and Aldi Süd. The EU F-Gas Regulation accelerates synthetic preservative phase-outs in processed foods. Bavaria's Ingolstadt and Munich industrial corridors host formulation R&D clusters where buffered vinegar systems undergo flavor-neutral optimization for high-moisture applications.
United States
Packaged goods manufacturers pursue cultured dextrose and antimicrobial peptide platforms for ready-to-eat meat processing. The FDA maintains its Generally Recognized As Safe notification pathway, allowing faster market entry than EFSA's dossier requirements. Chicago and Minneapolis-St. Paul anchor Midwest fermentation supply chains serving national bakery and beverage accounts.
Japan
METI's clean label guidance for processed foods creates procurement preference for biotech-derived preservation systems with local partnership structures. The PMDA enforces stringent purity benchmarks for antimicrobial additives in high-risk food matrices. Osaka-Kobe and Nagoya industrial zones concentrate beverage formulation facilities adopting buffered vinegar technologies for pH-neutral applications.
Netherlands
Rotterdam-Antwerp port logistics support import substitution for fermentation feedstocks as REACH authorization burdens tighten on synthetic precursors. EFSA-driven purity benchmarks redirect R&D budgets toward domestically sourced botanical extracts. Wageningen University's food innovation cluster advances standardization protocols for rosemary and green tea antioxidant concentration.
France
ANSM and DGCCRF enforcement of additive labeling transparency drives paraben replacement demand in cosmetic and personal care formulations. The EU Green Deal redirects public research funding toward fermentation infrastructure. Paris-Saclay and Lyon biotech corridors host antimicrobial peptide development programs targeting performance parity with legacy synthetic benchmarks.
Clean Label Preservatives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated fermentation houses commanding premium positioning in high-risk food matrices while toll processors serve mid-tier reformulation demand. The vendor base concentrates around three strategic archetypes: bioreactor-scale fermentation operators, botanical extraction specialists with harvest control agreements, and hybrid platforms combining antimicrobial peptides with active packaging integration. Dominant competitive moves include backward integration into fermentation feedstock supply and technology licensing partnerships for Japan's local partnership requirements.
Within the integrated fermentation tier, Cargill and DSM-Firmenich AG exemplify divergent scale strategies. Cargill leverages its captive agricultural supply chains to stabilize cultured dextrose input costs. DSM-Firmenich AG occupies a position bridging pharmaceutical-grade peptide platforms with food safety applications. Kerry Group plc represents the technical service archetype, embedding shelf-life optimization expertise into recurring revenue relationships with beverage and sauce manufacturers.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| DuPont de Nemours |
| DSM-Firmenich AG |
| Corbion |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Bioprocess engineering talent scarcity in the Netherlands and Germany widens pricing spreads between fermentation-derived antimicrobial tiers and commodity botanical extracts. Labor-cost differentials between specialized bioreactor operators and standard extraction facilities translate directly into premium positioning for peptide-based preservation systems.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for cultured dextrose and buffered vinegar systems as bioreactor commissioning accelerates. Three-tier pricing structure across premium antimicrobial peptides, standard fermented acidulants, and economy-grade botanical extracts reflects performance validation depth and EFSA dossier completion status. Price differentiation stems from certification grade and volume scale, with synthetic-replacement urgency compressing margins in the standard tier. Food manufacturers with EU F-Gas compliance deadlines show lowest price sensitivity; mid-tier beverage reformulators face acute cost compression.
Supply Chain Analysis
Direct-to-beverage-manufacturer channels handle high-velocity liquid preservative demand, while ingredient distributors serve fragmented bakery accounts. Supply concentrates in Germany, the Netherlands, and the United States, with Rotterdam-Antwerp port logistics anchoring European feedstock flows. Raw material dependencies center on non-GMO corn dextrose, pharmaceutical-grade fermentation media, and standardized rosemary oleoresin. Single-source vulnerability around stainless-steel bioreactor equipment extends capacity expansion timelines. Distribution runs through integrated fermentation houses for multinational accounts and regional toll processors for mid-tier reformulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a regulatory compounder, accelerating synthetic preservative phase-outs and redirecting formulation procurement toward validated natural alternatives.
For Market Incumbents: Anchor defensive positioning through backward integration into fermentation feedstock supply and captive bioreactor capacity expansion in Bavaria. Certification investment for EFSA positive-list pre-positioning counters emerging entrant dossier submissions. Channel control via subscription-based technical service contracts locks in beverage manufacturer switching costs. For New Entrants and Emerging Players: Antimicrobial peptide platform licensing offers a technology-first wedge into Japan's METI-guided procurement preference. White-space targets include pH-neutral sauce applications and active packaging convergence pilots with meat processors. A go-to-market angle through Wageningen University research partnerships accelerates standardization protocol credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale botanical extract specialists with harvest control agreements but incomplete EFSA dossiers. Long-term viability centers on regulatory exclusion list expansion and bioreactor capacity scarcity persistence. The signal to watch is EFSA submission backlog clearance rates as an inflection indicator for natural preservative market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Commissioning in Germany and the Netherlands addresses fermentation scarcity and compresses lead times for antimicrobial peptide supply. |
| EFSA Positive-List Pre-Positioning | Early dossier submission secures grandfathered status ahead of synthetic additive exclusion deadlines under EU F-Gas Regulation. |
| Subscription Formulation Services | Recurring revenue embedding of shelf-life optimization expertise locks in SME manufacturer relationships without in-house microbiology. |
| Active Packaging Integration | Hybrid oxygen-scavenging films with surface-applied fermented preservatives extend protection without ingredient list modification. |
| Japan Technology Licensing | METI local partnership requirements favor licensing structures over direct export for antimicrobial peptide market entry. |
Research Methodology
Bottom-up food manufacturer and beverage producer modeling reconciled against top-down fermentation capacity and botanical extraction tracking forms the analytical core. Primary interviews with bioprocess engineering directors, retail category buyers at German discounters, EFSA regulatory affairs consultants, and bakery procurement leads combined with secondary validation from customs trade data, EFSA additive approval registers, SEC 10-K filings of listed ingredient suppliers, and Cefic chemical industry reports. Triangulation across these sources calibrates volume and value estimates.
Historical trendline analysis of synthetic preservative displacement rates and natural alternative adoption curves informs projection modeling across the analysis window. Segmentation dimensions include product type, end user, application, and form, with additional modeling of regulatory compliance tier and bioreactor scale class. CAGRs derive from fitted growth curves applied to base-year market sizing, stress-tested against EU F-Gas implementation timelines and EFSA dossier approval velocity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA regulatory backlog resolution and fermentation equipment supplier delivery schedules. Forecasts reflect documented assumptions regarding synthetic exclusion list expansion and antimicrobial peptide performance validation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
MMA Triazine Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Warehouse Fumigants Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market