
 Air Treatment Products Market | 2026-2036
Air Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
Air Treatment Products Market Analysis
The EU Green Deal is pivoting commercial building retrofit specifications across Europe toward energy-recovery ventilation and low-GWP refrigerant systems. Daikin Industries, Ltd dominates variable refrigerant flow technology for large-scale commercial deployments. Panasonic Corporation leverages its semiconductor-grade cleanroom expertise to differentiate industrial air purification offerings. Samsung Electronics Co., Ltd anchors smart home integration through IoT-enabled purifier ecosystems.
Air treatment products encompass mechanical and electrochemical systems designed to modify atmospheric composition through filtration, dehumidification, humidification, or thermal conditioning, typically operating across pressure differentials of 50–500 Pa with particulate capture thresholds down to 0.3 microns for HEPA-class media. These systems serve to maintain occupant health, protect process integrity, and preserve material stability in controlled environments. Air purifiers lead product type revenue pools due to recurring filter replacement economics, while UV-C technology segments command premium positioning in healthcare and pharmaceutical cleanroom applications. The residential end-user category sustains volume leadership across humidifier and dehumidifier sales, though industrial buyers generate higher per-unit margins through custom-engineered specifications.
EPA indoor air quality guidelines and the EU F-Gas Regulation jointly shape refrigerant selection and energy efficiency benchmarking for manufacturers seeking cross-border market access. The US FDA and EMA both enforce particulate and microbial contamination limits that directly specify HEPA filtration in pharmaceutical manufacturing environments. Stakeholders must monitor evolving refrigerant phase-down schedules and filter media supply chain origination requirements to preserve product certification continuity and avoid customs detention at points of import.
Market Dynamics
HEPA-grade filtration is modularizing across residential and commercial deployments as EPA indoor air quality advisories tighten particulate thresholds and healthcare procurement specifications cascade into adjacent building categories.
Growth Catalysts
- EPA Indoor Air Quality Guidelines:Healthcare facilities across the United States are expanding HEPA system procurement following updated federal particulate advisories, compressing upgrade cycles in acute care and outpatient settings.
- Activated Carbon Manufacturing Concentration:China's dominance in filter media assembly is driving cost efficiencies that accelerate replacement cycle economics for purifier OEMs serving price-sensitive consumer segments.
- UV-C Cleanroom Applications:Pharmaceutical manufacturers are specifying UV-C augmentation for microbial control in aseptic processing zones, extending technology penetration beyond traditional HVAC retrofit markets.
Market Restraints
- Refrigerant Input Volatility:Low-GWP refrigerant supply constraints under the EU F-Gas Regulation are compressing dehumidifier production margins and extending equipment lead times for industrial buyers.
- Filter Media Supply Concentration:Geographic clustering of activated carbon and HEPA substrate manufacturing in East Asia creates customs detention exposure and origination certification complexity at points of import.
- Technical Performance Ceiling:HEPA capture thresholds at 0.3 microns represent a physical limitation that constrains differentiation in premium residential segments without electrochemical augmentation.
Strategic Opportunities
- EU Green Deal Retrofit Mandates:Commercial building energy-recovery ventilation specifications are creating specification pull for integrated heat-exchange systems across Germany, France, and the Netherlands.
- IoT-Enabled Service Unbundling:Smart home ecosystems are enabling filter replacement subscription models that capture recurring revenue streams independent of initial hardware margins.
- Industrial Humidification Convergence:Semiconductor-grade cleanroom expertise is transferring to pharmaceutical and battery manufacturing environments, opening specification channels for precision humidity control systems.
Industry Challenges
- Certification Timeline Compression:Evolving refrigerant phase-down schedules under EPA and ECHA frameworks require continuous product requalification that strains engineering bandwidth and delays market entry.
- Legacy Building Integration Friction:Energy-recovery ventilation retrofits face structural compatibility constraints with existing ductwork configurations, complicating sales engineering and installation cost estimation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Treatment Products Market |
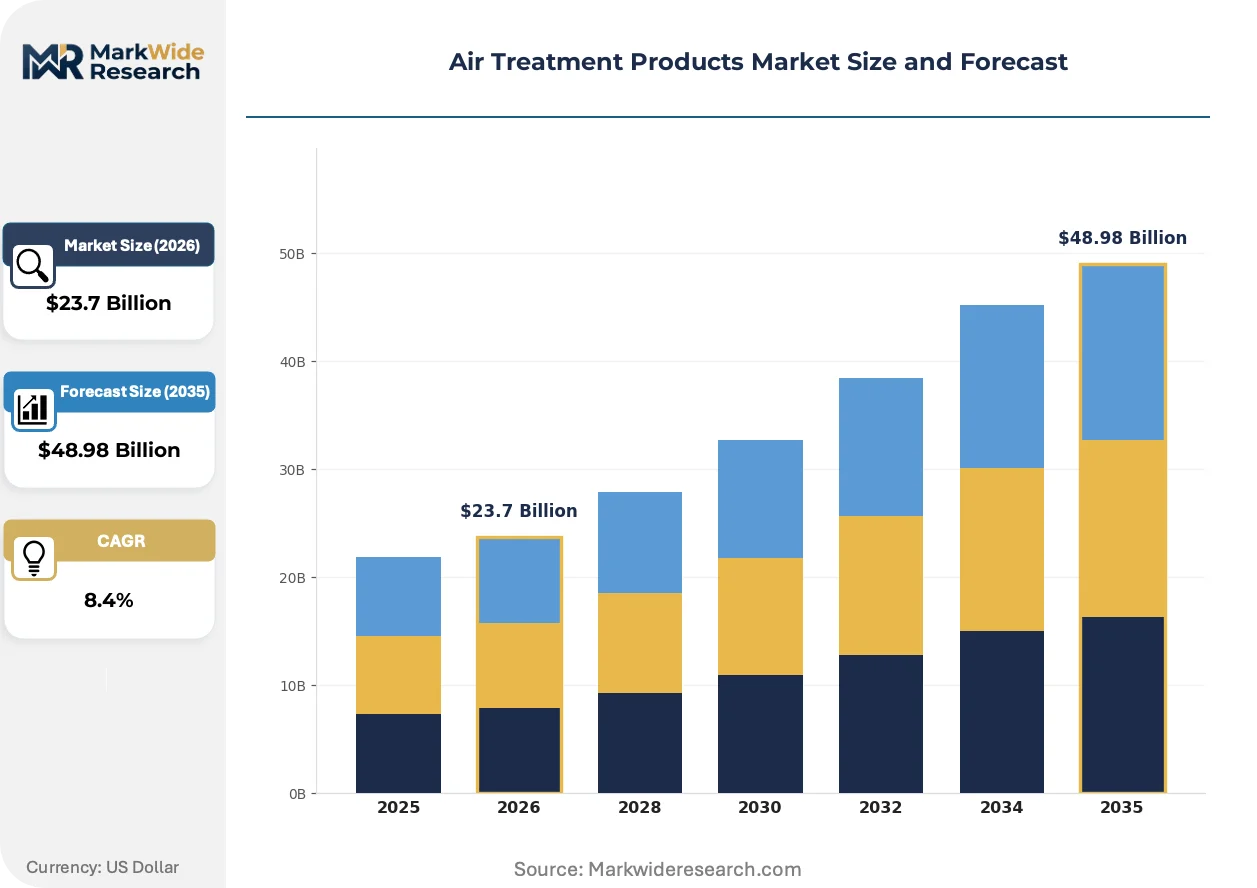
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Purifiers, Dehumidifiers, Humidifiers, Air Conditioners Application: Residential, Commercial, Industrial, Healthcare Technology: HEPA, Activated Carbon, UV-C, Ionizer End User: Homeowners, Businesses, Hospitals, Educational Institutions |
| Companies Covered | Samsung Electronics Co., Ltd, Atlas Copco AB, LG Electronics Inc., Panasonic Corporation, Honeywell International, Daikin Industries, Ltd, Sharp Corporation, Koninklijke Philips N.V., Dyson Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Treatment Products Market Emerging Trajectories
Electrochemical and IoT architectures are converging to reshape how air treatment systems are specified, procured, and monetized across residential and industrial buyer segments.
Photocatalytic oxidation is modularizing as a stackable stage within multi-stage filtration architectures, enabling pharmaceutical cleanroom operators to add VOC destruction capability without replacing existing HEPA infrastructure. Industrial buyers in the United States and Germany are piloting this configuration for solvent recovery zones. The technology is modularizing what were previously monolithic purification systems into upgradeable component ecosystems.
The EU F-Gas Regulation is compressing hydrofluorocarbon availability for dehumidification equipment, forcing manufacturers to accelerate natural refrigerant adoption in industrial product lines. This transition is elevating capital requirements for production retooling and compressing margins on legacy equipment inventories. European industrial buyers are responding by extending equipment life cycles and deferring replacement decisions pending refrigerant pathway clarity.
Facility managers are unbundling air quality monitoring from equipment procurement, deploying standalone sensor networks that drive replacement filter demand through data-triggered replenishment rather than calendar schedules. This pattern is displacing traditional distributor relationships with direct-to-facility consumables contracts. The shift is most visible in United States healthcare systems and German automotive manufacturing plants where ISO 14644 cleanroom classifications mandate continuous environmental verification.
Air Treatment Products Market Segmentation
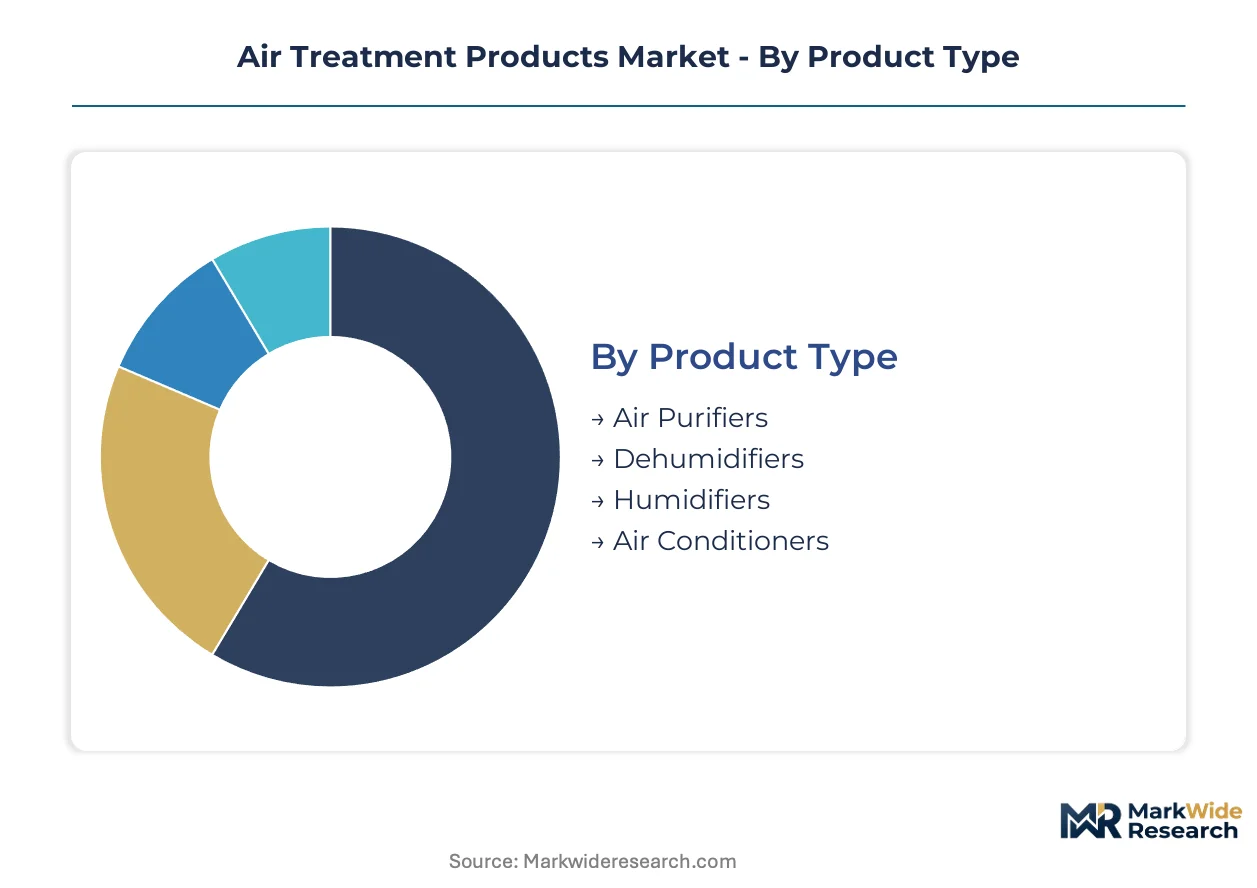
Air treatment procurement patterns diverge sharply across buyer contexts, with replacement-cycle economics and regulatory compliance requirements reshaping how OEMs configure product portfolios and distribution channels. Segmentation reveals where hardware margins compress against consumables revenue and which technology tiers command specification premiums.
Product Type:
Upgrade cycles vary dramatically by product category, with filter-replacement dependencies and refrigerant phase-down timelines creating divergent revenue durability profiles.
- Air Purifiers:Multi-stage filtration architectures incorporating HEPA and activated carbon media dominate residential and healthcare specifications. Recurring filter replacement economics sustain manufacturer margins long past initial hardware sales, with EPA indoor air quality advisories compressing replacement intervals in United States healthcare facilities.
- Dehumidifiers:Industrial-grade systems utilizing low-GWP refrigerants face supply constraints under EU F-Gas Regulation phase-down schedules. German manufacturing plants and pharmaceutical cleanrooms drive specification demand as ECHA workplace exposure limits tighten moisture control requirements.
- Humidifiers:Evaporative and ultrasonic technologies serve residential winter heating seasons with minimal consumables attachment.
- Air Conditioners:Thermal conditioning systems with integrated air filtration represent capital-intensive infrastructure with extended replacement horizons.
Volume placements concentrate in Air Purifiers; the faster expansion belongs to Dehumidifiers.
Application:
End-use environments impose distinct performance thresholds, with regulatory enforcement intensity determining whether buyers prioritize first-cost minimization or lifecycle certification compliance.
- Residential:Price-sensitive consumers drive demand for compact HEPA units and seasonal humidification equipment. China's concentration in activated carbon filter manufacturing enables cost-efficient replacement cycles for mass-market purifier OEMs.
- Healthcare:Acute care facilities and outpatient clinics specify HEPA-grade systems with UV-C augmentation following EPA indoor air quality advisories. FDA and EMA microbial contamination limits mandate continuous environmental verification, elevating consumables attachment rates.
- Commercial:Office and retail deployments balance occupant comfort against energy-recovery ventilation retrofit economics under EU Green Deal specifications.
- Industrial:Semiconductor, pharmaceutical, and battery manufacturing environments require precision humidity control and particulate capture to ISO 14644 cleanroom classifications.
Residential captures unit volume leadership; Healthcare generates the steepest margin expansion trajectory.
Technology:
Technology selection follows end-use contamination profiles, with modular architectures enabling staged capability upgrades without full system replacement.
- HEPA:Mechanical filtration media capturing 0.3-micron particulates at 99.97% efficiency anchors healthcare and pharmaceutical specifications. Physical capture thresholds constrain differentiation without electrochemical augmentation in premium residential segments.
- Activated Carbon:Adsorptive media for VOC and odor control relies on East Asian manufacturing concentration, creating customs detention exposure and origination certification complexity at United States and European points of import.
- UV-C:Germicidal irradiation systems command premium positioning in aseptic processing zones and HVAC retrofit markets.
- Ionizer:Electrostatic precipitation technologies face ozone emission scrutiny from EPA and ECHA frameworks.
HEPA maintains installed base dominance; UV-C is climbing the fastest on pharmaceutical cleanroom specifications.
End User:
Procurement authority and technical specification capability vary sharply across buyer types, fragmenting distribution channel requirements and service bundling economics.
- Homeowners:Individual consumers purchase through retail and direct-to-consumer channels with limited technical evaluation capacity. Smart home integration and subscription filter replenishment models are displacing traditional distributor relationships.
- Hospitals:Healthcare system procurement departments enforce FDA and EMA contamination limits through qualified supplier programs with continuous compliance verification. United States acute care facilities expanded HEPA system procurement following updated federal particulate advisories.
- Businesses:Commercial facility managers deploy standalone sensor networks that trigger filter replacement through data rather than calendar schedules.
- Educational Institutions:School districts and universities balance budget constraints against occupant density and aging infrastructure retrofit requirements.
Homeowners drive absolute unit placements; Hospitals deliver the most durable consumables revenue attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the activated carbon filter manufacturing concentration that supplies purifier OEMs worldwide, while regulatory divergence across major economies fragments specification standards and compliance pathways.
United States
Healthcare systems in Houston and Boston expanded HEPA procurement following EPA indoor air quality advisories. FDA contamination limits for pharmaceutical manufacturing mandate continuous environmental verification. The Southeast manufacturing corridor around Atlanta hosts contract assembly operations serving price-sensitive consumer segments.
Germany
Industrial dehumidifier demand concentrates in Bavaria's automotive and pharmaceutical clusters as ECHA workplace exposure limits tighten. The EU F-Gas Regulation compresses hydrofluorocarbon availability for equipment retrofits. Stuttgart-based engineering firms pilot natural refrigerant systems for cleanroom humidity control.
China
Activated carbon substrate and HEPA media assembly dominates the Yangtze River Delta around Suzhou and Ningbo. MIIT industrial standards govern filter efficiency certifications for domestic and export markets. Shenzhen electronics corridors integrate air purification modules into smart home ecosystems for Southeast Asian export.
Japan
Semiconductor-grade cleanroom expertise in Osaka and Nagoya transfers to pharmaceutical and battery manufacturing specifications. METI energy efficiency benchmarks shape residential purifier design requirements. Kansai-region fabricators supply precision humidification systems to domestic and South Korean chipmakers.
India
Residential air purifier sales accelerate in Delhi-NCR and Mumbai as BIS efficiency labeling expands coverage. CDSCO pharmaceutical manufacturing rules specify environmental monitoring for sterile processing zones. Gujarat chemical corridors drive industrial dehumidification demand for moisture-sensitive synthesis operations.
Air Treatment Products Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and certification compliance burden. The vendor base stratifies between diversified electronics conglomerates with captive distribution and specialized climate-control engineering houses with regional fabrication footprints. Three archetypes dominate: smart-home ecosystem integrators leveraging IoT platforms; industrial-grade system specialists with cleanroom certification authority; and mass-market OEMs competing on filter replacement cycle economics. Capacity expansion and portfolio diversification represent the dominant competitive moves as refrigerant phase-down timelines compress product requalification windows.
Within the diversified electronics tier, Samsung Electronics Co., Ltd and LG Electronics Inc exemplify ecosystem-first positioning, while Daikin Industries, Ltd occupies a specialist position in variable refrigerant flow architectures. Panasonic Corporation anchors the industrial-grade segment through semiconductor cleanroom heritage. Honeywell International represents the diversified industrial conglomerate archetype with cross-sector environmental control capabilities.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd |
| Atlas Copco AB |
| LG Electronics Inc. |
| Panasonic Corporation |
| Honeywell International |
| Daikin Industries, Ltd |
| Sharp Corporation |
| Koninklijke Philips N.V. |
| Dyson Limited |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-validated HEPA systems and mass-market residential units manifests in both pricing premiums and supply chain qualification burdens. The EU F-Gas Regulation and EPA refrigerant phase-downs simultaneously reshape input costs and procurement specifications across tiered buyer segments.
Pricing Analysis
Outcome-based pricing anchored to cleanroom uptime guarantees dominates pharmaceutical and semiconductor procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644-validated industrial systems from healthcare-grade HEPA deployments and residential purifier hardware. Cost compression in mass-market activated carbon replacement cycles intensifies because China's manufacturing concentration enables aggressive OEM sourcing. Hospitals and pharmaceutical manufacturers exhibit the lowest price sensitivity due to FDA and EMA contamination liability exposure, while residential consumers drive volume through seasonal promotional elasticity.
Supply Chain Analysis
Qualification gating through HEPA media certification and low-GWP refrigerant approval concentrates supplier pools and extends onboarding timelines. Manufacturing gravity centers on China for activated carbon substrate and HEPA media assembly, Germany for precision dehumidification engineering, and Japan for semiconductor-grade cleanroom components. Raw material dependencies encompass borosilicate glass fiber for filtration media, synthetic zeolites for desiccant systems, and natural refrigerant compounds for industrial dehumidifiers. Single-source vulnerability in East Asian filter media production creates customs detention exposure at United States and European import points. Distribution runs through qualified supplier programs in healthcare and direct-to-facility consumables contracts in industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Air Treatment Products Market functions as a cost-of-compliance arena where the EU F-Gas Regulation and EPA refrigerant phase-downs erect engineering qualification barriers that protect incumbent positions from unqualified entrants.
For Market Incumbents: Cement defensible positioning through backward integration into HEPA media manufacturing and captive refrigerant reclamation infrastructure. Natural refrigerant system certification investments create moats against commodity competitors facing requalification delays. Channel control through IoT-enabled filter subscription platforms displaces traditional distributor relationships and locks in consumables revenue attachment. For New Entrants and Emerging Players: Facility management service providers represent the most accessible channel partner type for bypassing entrenched OEM-distributor relationships. Underpenetrated precision humidification specifications in battery manufacturing environments offer white-space expansion with lower certification burdens than pharmaceutical cleanrooms. Direct-to-facility sensor network deployment creates data-driven filter replenishment contracts independent of hardware margins. For Investors and Strategic Acquirers: Re-rating potential sits with industrial-grade system specialists possessing semiconductor cleanroom heritage given pharmaceutical manufacturing capacity expansion and battery factory buildouts. Long-term viability hinges on refrigerant pathway clarity and filter media supply diversification across the next decade. The signal to watch is ECHA workplace exposure limit tightening in German industrial clusters as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant System Certification | EU F-Gas Regulation compliance preserves market access for European industrial buyers. |
| HEPA Media Backward Integration | Captive borosilicate glass fiber production mitigates East Asian supply concentration risk. |
| IoT Filter Subscription Platforms | Data-triggered replenishment models displace calendar-based distributor relationships in healthcare. |
| Semiconductor Cleanroom Expertise Transfer | ISO 14644 certification authority opens pharmaceutical and battery manufacturing specifications. |
| Energy-Recovery Ventilation Retrofit Partnerships | EU Green Deal mandates create specification pull for integrated heat-exchange systems in commercial buildings. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with HVAC engineering directors, pharmaceutical facility managers, hospital procurement officers, and filter media manufacturing executives combined with EPA enforcement databases, EU ECHA substance restriction registers, and MIIT industrial standard publications. Bottom-up equipment shipment tracking and top-down end-use demand estimation were triangulated for cross-validation.
Data-stream reconciliation across product type, application, technology tier, and end-user procurement authority shaped the analytical framework throughout the projection horizon. CAGRs were derived from replacement cycle compression in healthcare and industrial segments alongside refrigerant transition timelines. Modeled inputs encompassed HEPA system upgrade intervals, activated carbon replacement frequencies, and low-GWP refrigerant adoption curves.
Caveats apply where EPA refrigerant phase-down acceleration or ECHA workplace exposure limit revisions could materially shift the outlook. Forecasts reflect assumptions regarding filter media supply chain stability and certification continuity at points of import. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or MIIT export standard modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Vaporized Hydrogen Peroxide Sterilization Systems Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Clinical Grade Disinfectant Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Disinfecting Wipes Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Hypochlorite Bleaches Market