
 UK Hypochlorous Acid Market | 2026-2036
UK Hypochlorous Acid Market Size, Share, and Industry Trends Forecast 2026-2036
UK Hypochlorous Acid Market Analytics
The UK Health Security Agency's tightened environmental cleaning protocols is pivoting hospital procurement toward electrochemically generated hypochlorous acid solutions. Aqualution Systems Ltd leverages on-site generation technology to bypass chlorine supply chain bottlenecks for NHS trusts. INOVYN anchors industrial-scale sodium hypochlorite feedstock supply that underpins downstream HOCl formulation capacity. Envirolyte Eca Uk Ltd specializes in compact electrolysis units designed for food processing plant integration.
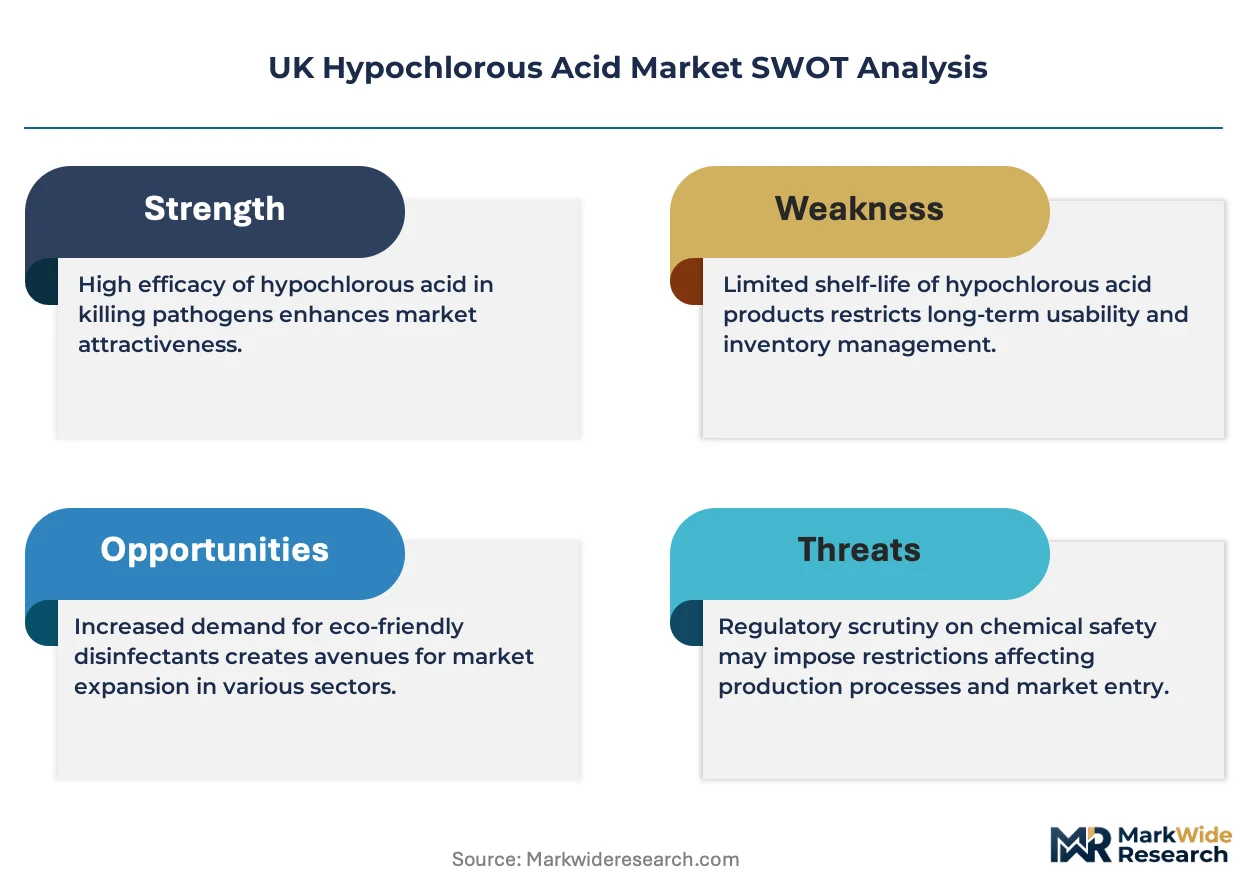
Hypochlorous acid is a weak, unstable acid with the chemical formula HOCl, formed when chlorine dissolves in water and partially dissociates; electrochemical activation produces stabilized solutions at neutral pH with oxidation-reduction potential typically ranging from 700 to 900 mV, functioning as a broad-spectrum antimicrobial agent effective against bacteria, viruses, and spores without the irritancy of conventional chlorine disinfectants. Liquid formulations dominate current volume owing to established dosing infrastructure in healthcare and food safety applications, while wound care represents the fastest-expanding application segment as MHRA-registered medical device approvals accumulate for chronic ulcer management. Gel and tablet formats remain niche but occupy higher-margin positions in consumer retail and field-deployed agricultural sanitation.
The Health and Safety Executive enforces Biocidal Products Regulation compliance for active substance suppliers, while the Food Standards Agency mandates hazard analysis critical control point validation for food contact sanitizers. The Medicines and Healthcare products Regulatory Agency governs medical device claims for wound irrigation formulations, creating a three-track regulatory landscape that fragments market access requirements. Stakeholders must monitor divergence between GB-bespoke biocide authorizations and retained EU regulatory frameworks as the UK develops independent chemical safety assessment capacity.
Market Dynamics
The UK Health Security Agency's environmental cleaning standards revision is forcing NHS procurement corridors to abandon quaternary ammonium compounds in favor of electrochemically activated hypochlorous acid solutions.
Growth Catalysts
- Biocidal Products Regulation substitution mandates:The retained EU framework and developing GB-bespoke authorizations accelerate quaternary ammonium compound phase-out across English healthcare facilities.
- Electrochemical activation technology maturation:On-site generation systems eliminate chlorine supply chain bottlenecks for National Health Service trusts in Greater London and the West Midlands.
- Wound care medical device approvals:MHRA-registered formulations for chronic ulcer management expand addressable clinical applications beyond surface disinfection.
Market Restraints
- Electrolysis equipment capex intensity:Compact electrolysis units for food processing integration require substantial upfront investment that constrains mid-scale processor adoption.
- Shelf stability technical limitation:Hypochlorous acid's inherent instability necessitates cold chain logistics or on-site generation, elevating total cost of ownership versus stabilized alternatives.
- Three-track regulatory fragmentation:Divergent Health and Safety Executive, Food Standards Agency, and Medicines and Healthcare products Regulatory Agency compliance pathways multiply market access costs for formulation suppliers.
Strategic Opportunities
- Scottish NHS procurement corridor expansion:Healthcare facilities across Scotland demonstrate accelerating adoption rates for electrochemically activated water applications.
- Agricultural sanitation field deployment:Tablet and gel format development targets livestock biosecurity protocols with portable, dose-controlled application systems.
- Food contact sanitizer HACCP validation:Food Standards Agency mandate expansion creates certified supplier preference in meat processing and ready-to-eat manufacturing segments.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in electrolysis cell design and oxidation-reduction potential stabilization remains concentrated among limited technical consultancies.
- Biocide authorization timeline compression:Developing UK independent chemical safety assessment capacity creates uncertainty intervals between retained EU framework expiry and GB-bespoke approval finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Hypochlorous Acid Market |
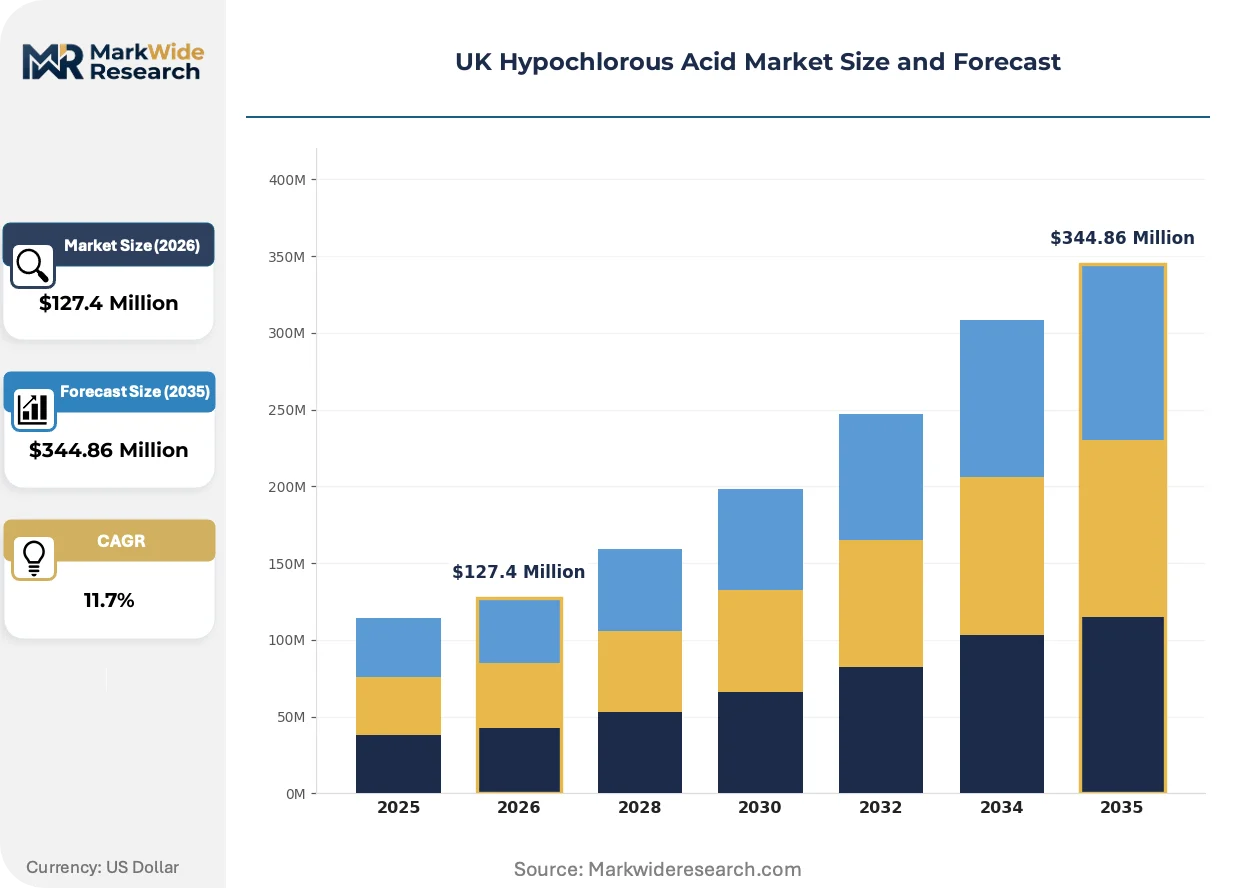
| Market Size in 2026 | $127.4 Million |
| Market Size in 2035 | $344.86 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gel, Powder, Tablet Application: Disinfection, Cleaning, Sanitization, Wound Care End User: Healthcare, Food Industry, Household, Agriculture Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Aqualution Systems Ltd, INOVYN, Envirolyte Eca Uk Ltd, BASF SE, Lenntech B.V., Nouryon, Lonza, Arkema S.A., Well-Tech Innovation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Hypochlorous Acid Market Evolving Landscape
Electrochemical process intensification is compressing equipment footprints while elevating solution stability, reshaping competitive differentiation around generation technology rather than bulk formulation chemistry.
Membraneless electrolysis cell architecture is unifying pH control and oxidation-reduction potential precision in single-vessel systems. Food processing plants in Yorkshire and Lancashire are adopting these compact units for continuous sanitization loops. The technology is unifying previously separate acidification and chlorination process steps, reducing capital deployment by half for mid-scale processors.
The UK Health Security Agency's updated environmental cleaning standards are mandating sporicidal efficacy validation for surface disinfectants in acute care settings. This regulatory pressure accelerates substitution of quaternary ammonium compounds with hypochlorous acid across NHS England procurement specifications. Wound irrigation formulations face heightened scrutiny under Medicines and Healthcare products Regulatory Agency medical device registration pathways.
Hospital supply chains are consolidating vendor relationships around full-service electrochemical system providers. NHS trusts in the West Midlands are replacing chemical procurement contracts with equipment lease arrangements bundled with maintenance and consumables. This restructuring concentrates purchasing authority within integrated facilities management departments rather than infection control nursing teams.
UK Hypochlorous Acid Market Segmentation
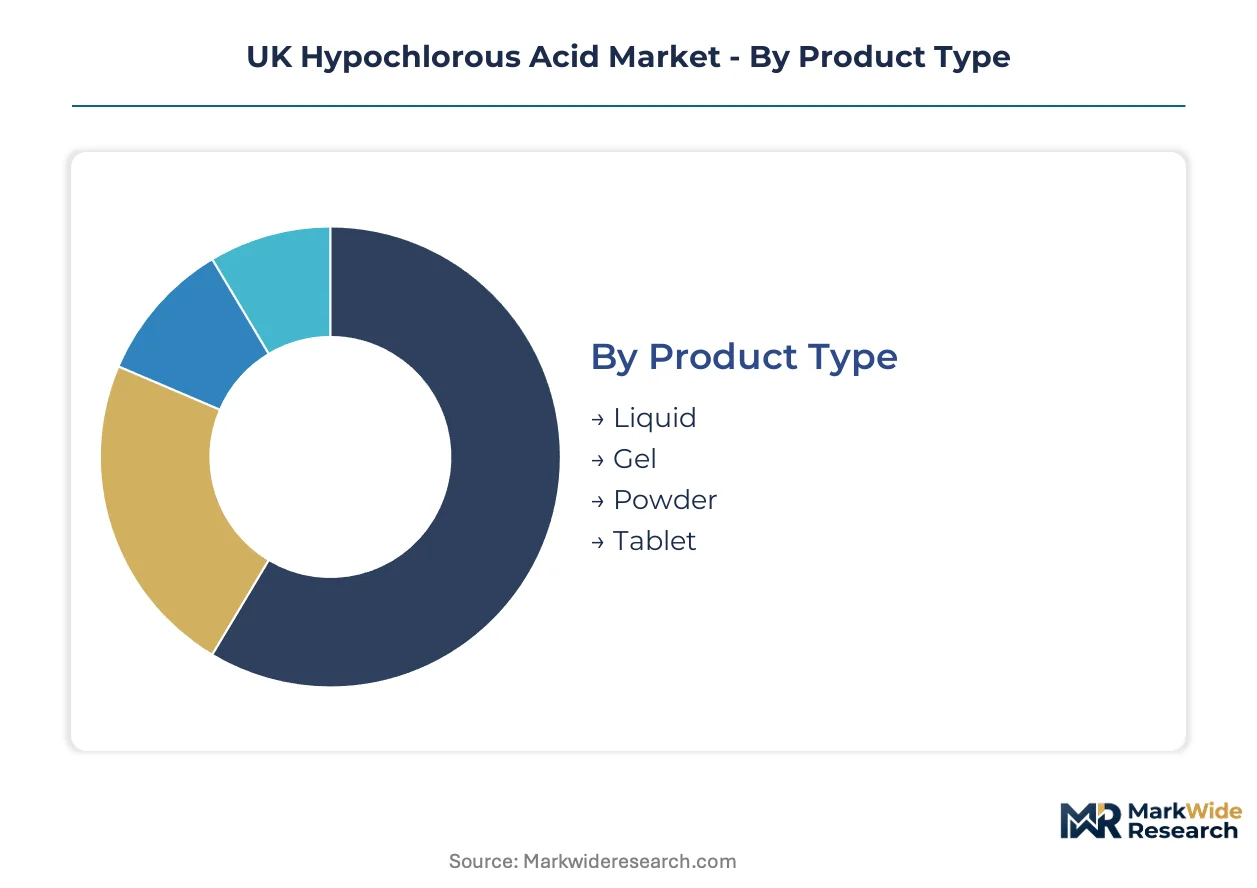
Segmentation in the UK hypochlorous acid market reveals how regulatory pathways fragment commercial opportunity. Each dimension carries distinct certification burdens that reshape competitive positioning and margin structures across NHS procurement, food safety validation, and consumer retail channels.
Product Type:
Liquid formulations require MHRA medical device registration for wound care claims, while gel and tablet formats face lighter Food Standards Agency biocidal validation for food contact applications.
- Liquid:Electrochemically activated solutions at neutral pH with oxidation-reduction potential between 700-900 mV dominate NHS England procurement corridors in Greater London and the West Midlands, driven by surface disinfection mandates under UK Health Security Agency environmental cleaning standards.
- Gel:Viscous formulations enable sustained contact time for chronic ulcer management applications. Demand concentrates in community wound care settings across Scotland where MHRA-registered medical device approvals are accumulating fastest.
- Powder:Lyophilized precursors require reconstitution before activation. These formats serve field-deployed agricultural sanitation where cold chain logistics prove impractical.
- Tablet:Compressed effervescent formats target portable livestock biosecurity protocols. Yorkshire and Lancashire food processors are piloting these for dose-controlled sanitization loops.
Liquid sits at the top of the volume ranking, with gel climbing the fastest.
Application:
Application segments diverge sharply on margin structure, with clinical wound care commanding premium pricing against commoditized surface disinfection contracts.
- Disinfection:Sporicidal efficacy validation under UK Health Security Agency acute care standards is displacing quaternary ammonium compounds across NHS trusts. Electrochemical activation technology eliminates chlorine supply chain bottlenecks for hospital procurement.
- Cleaning:General environmental sanitation applications face downward price pressure from bulk sodium hypochlorite alternatives. West Midlands facilities management departments are consolidating vendor relationships around full-service system providers.
- Sanitization:Food contact sanitizer claims require Food Standards Agency HACCP validation. Meat processing and ready-to-eat manufacturing segments in Yorkshire demonstrate certified supplier preference.
- Wound Care:Chronic ulcer management formulations carry MHRA medical device registration requirements. Scottish healthcare facilities are expanding adoption rates for electrochemically activated irrigation solutions.
Disinfection captures the largest volume position, with wound care gaining share fastest.
End User:
End user concentration determines regulatory exposure intensity, with healthcare and food industry segments facing the most stringent multi-agency compliance burdens.
- Healthcare:NHS procurement corridors enforce three-track compliance across Health and Safety Executive biocidal authorizations, Food Standards Agency validation, and MHRA medical device registration. Greater London trusts are replacing chemical contracts with equipment lease arrangements.
- Food Industry:HACCP-mandated sanitizer requirements concentrate demand in meat processing clusters. Lancashire processors are adopting membraneless electrolysis units for continuous sanitization loops.
- Household:Consumer retail formats face lighter regulatory entry barriers but compete on price against established bleach brands.
- Agriculture:Livestock biosecurity protocols favor portable tablet and gel formats for field deployment without fixed generation infrastructure.
Healthcare dominates absolute volume, with food industry expanding most quickly.
Distribution Channel:
Channel structure reflects customer scale and technical complexity, with direct sales capturing integrated system deployments and online channels serving fragmented consumer demand.
- Online:E-commerce platforms serve household consumers and small agricultural operators with standardized tablet and liquid formats. Regulatory compliance responsibility shifts to importers under retained EU Biocidal Products Regulation frameworks.
- Retail:Pharmacy and agricultural supply chains stock gel and liquid formats for wound care and livestock applications. Shelf stability limitations constrain product range depth.
- Direct Sales:Electrochemical system providers lease on-site generation equipment to NHS trusts with bundled maintenance contracts. West Midlands facilities management departments are consolidating purchasing authority through this channel.
- Distributors:Specialized chemical distributors serve mid-scale food processors with bulk liquid formulations and compact electrolysis units.
Direct sales leads in value terms, with online demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemical water treatment technology originated in UK industrial chemistry laboratories during the 1970s, with commercial scale-up accelerating through National Health Service procurement reforms in the 2010s. Regional demand now concentrates in England's healthcare corridors and Scotland's expanding clinical networks.
Greater London
NHS trusts in Greater London are replacing bulk chemical contracts with on-site generation equipment leases bundled with maintenance services. UK Health Security Agency environmental cleaning standards mandate sporicidal efficacy validation for acute care surface disinfectants. University College London Hospitals NHS Foundation Trust exemplifies this procurement shift through consolidated facilities management purchasing authority.
West Midlands
West Midlands healthcare facilities demonstrate the fastest equipment adoption rates outside London, driven by integrated care system consolidation. Health and Safety Executive Biocidal Products Regulation compliance costs are accelerating vendor relationship consolidation around full-service electrochemical system providers. Birmingham Women's and Children's NHS Foundation Trust anchors regional procurement corridor development for wound irrigation applications.
Yorkshire and Lancashire
Food processing clusters in Yorkshire and Lancashire are piloting membraneless electrolysis units for continuous sanitization loops in meat processing plants. Food Standards Agency HACCP validation requirements for food contact sanitizers create certified supplier preference in ready-to-eat manufacturing segments. Bradford and Preston processing facilities lead adoption of compact electrolysis technology for dose-controlled application systems.
Scotland
Scottish healthcare facilities are expanding adoption of electrochemically activated water for wound irrigation applications faster than English counterparts. Medicines and Healthcare products Regulatory Agency medical device registration pathways for chronic ulcer management formulations are accumulating approvals fastest in NHS Scotland procurement corridors. Glasgow and Edinburgh hospital networks drive regional demand concentration for MHRA-registered gel formulations.
UK Hypochlorous Acid Market Competitive Landscape
Capital-heavy electrochemical equipment manufacturers compete with asset-light formulation specialists in a bifurcated competitive structure. The market exhibits tiered concentration: industrial-scale sodium hypochlorite feedstock suppliers anchor upstream supply, mid-scale electrolysis system integrators occupy the technology layer, and regional formulation packagers serve fragmented end-use segments. Three archetypes dominate: on-site generation technology providers, bulk chemical distributors with downstream blending capacity, and specialized medical device registrants. Competitive moves concentrate on equipment lease contract capture and MHRA registration pathway acceleration.
Among UK-based specialists, Aqualution Systems Ltd and Envirolyte Eca Uk Ltd represent the on-site generation technology archetype, while INOVYN anchors industrial-scale feedstock supply capacity. Aqualution Systems Ltd exemplifies equipment-lease bundling strategies targeting NHS procurement consolidation. Envirolyte Eca Uk Ltd occupies a position serving food processing integration requirements. INOVYN sits within the upstream chemical supply tier that underpins downstream formulation capacity across all application segments.
| Leading Market Players |
|---|
| Aqualution Systems Ltd |
| INOVYN |
| Envirolyte Eca Uk Ltd |
| BASF SE |
| Lenntech B.V. |
| Nouryon |
| Lonza |
| Arkema S.A. |
| Well-Tech Innovation |
| Others |
Value Network & Pricing Analysis
Electrochemical engineering specialists concentrated in Greater London and the West Midlands command premium compensation that propagates through equipment lease pricing tiers. Labor-cost differentials between these UK technical hubs and emerging Scottish engineering clusters widen the spread between premium on-site generation contracts and mid-market electrolysis unit deployments.
Pricing Analysis
Equipment-lease bundling dominates NHS procurement corridors, separating full-service system providers from commodity chemical suppliers. Price differentiation hinges on MHRA medical device registration tier and oxidation-reduction potential stabilization precision. Cost compression in standard-grade surface disinfection contracts intensifies as bulk sodium hypochlorite alternatives retain foothold. Mid-scale food processors in Yorkshire demonstrate highest price sensitivity, while acute care trusts in Greater London prioritize sporicidal efficacy validation over unit economics.
Supply Chain Analysis
Industrial-grade salt and membrane electrolysis cell components rest on German and Japanese specialty chemical producers for precision-manufactured electrodes. UK-based feedstock blending draws from INOVYN's Runcorn chlorine production and imported sodium hypochlorite precursors. Single-source vulnerability concentrates in advanced membrane materials for long-life electrolysis cells. Distribution runs through NHS Supply Chain consolidated procurement for healthcare segments, with direct manufacturer relationships dominating food processing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scotland's accelerating wound care adoption against England's maturing disinfection procurement creates a geographic-arbitrage window for electrochemical system providers. Regulatory divergence between retained EU biocidal frameworks and developing GB-bespoke authorizations compounds cost differentials across UK borders.
For Market Incumbents: Extend equipment lease contract terms to lock in NHS procurement consolidation before Scottish corridor competition intensifies. Deepen backward integration into electrode manufacturing to offset German specialty supplier pricing power. Anchor defensive positioning around MHRA medical device registration acceleration for chronic ulcer management formulations. For New Entrants and Emerging Players: Capture agricultural sanitation white space in livestock biosecurity protocols where portable tablet formats bypass fixed infrastructure requirements. Target Yorkshire and Lancashire food processing clusters piloting membraneless electrolysis for HACCP-validated sanitizer supply. Lead with dose-controlled application system demonstrations rather than chemical commodity positioning. For Investors and Strategic Acquirers: Water technology conglomerates with healthcare verticals are the most active acquirer in this space, seeking electrochemical activation IP to complement existing disinfection portfolios. Long-term viability hinges on GB-bespoke biocide authorization timeline compression and Scottish NHS procurement corridor maturation. Monitor MHRA medical device approval velocity for wound irrigation formulations as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Manufacturing | Captive electrode supply reduces German specialty chemical producer dependency for NHS equipment lease contracts. |
| MHRA Medical Device Registration Acceleration | Chronic ulcer management formulation approvals unlock premium wound care pricing in Scottish procurement corridors. |
| Membraneless Electrolysis Technology Licensing | Yorkshire food processors adopt compact continuous sanitization loops halving capital deployment requirements. |
| Scottish NHS Procurement Corridor Expansion | Glasgow and Edinburgh hospital networks drive fastest regional adoption for electrochemically activated irrigation solutions. |
| Portable Tablet Format Development | Livestock biosecurity protocols in field-deployed agricultural sanitation favor dose-controlled application without fixed generation infrastructure. |
Research Methodology
Direct dialogue with NHS procurement managers, infection control nursing leads, food processing plant engineers, and electrochemical system technical directors grounded qualitative assessment. Secondary validation drew from UK Health Security Agency environmental cleaning standards documentation, Health and Safety Executive biocidal product registrations, MHRA medical device approval databases, and Food Standards Agency HACCP validation records. Bottom-up equipment installation tracking and top-down chemical consumption estimates were triangulated against NHS Supply Chain contract disclosures.
Segment-level demand projections across liquid, gel, powder, and tablet formulations were generated through the analysis window. Modeling incorporated application splits between disinfection, cleaning, sanitization, and wound care, cross-referenced with end-user concentration in healthcare, food industry, household, and agricultural segments. CAGRs were derived from electrolysis unit deployment trajectories and MHRA registration pipeline velocity. Forecast inputs included UK Health Security Agency mandate expansion timelines and Scottish NHS procurement budget allocations.
Biocide authorization timeline delays, electrochemical equipment capex cycle compression, and wound care reimbursement policy shifts are the dominant revision risks. Forecasts embed assumptions around GB-bespoke regulatory framework finalization and retained EU alignment periods. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Sulfuryl Fluoride Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market