
 Warehouse Fumigants Market | 2026-2036
Warehouse Fumigants Market Size, Share, and Industry Trends Forecast 2026-2036
Warehouse Fumigants Market Analytics
ISO 9001 certification for fumigant manufacturing and application services is reorganizing competitive access across developed markets. BASF SE leverages its integrated chemical production network to sustain cost advantages in phosphine tablet supply. Syngenta anchors its position through proprietary formulation patents and direct distribution to agricultural cooperatives. Degesch America Inc. competes on specialized application equipment and technician training protocols.
Warehouse fumigants are volatile or gaseous biocidal compounds, typically aluminum phosphide or magnesium phosphide formulations, that release phosphine gas upon exposure to atmospheric moisture to eliminate insect infestations in stored commodities. The primary commercial purpose is to maintain commodity integrity during extended storage periods while meeting phytosanitary export requirements. Phosphine-based products lead volume shipments due to lower unit economics and established residue tolerance profiles, while sulfuryl fluoride is gaining share in temperature-sensitive pharmaceutical and food-grade warehouses where corrosion concerns limit metal phosphide use. Gas formulations dominate operational deployment for their penetration depth into bulk grain masses, though pelletized solid forms retain relevance in smaller facilities lacking pressurized application infrastructure.
The US EPA regulates fumigant registration and tolerance limits under FIFRA, while the EU enforces REACH substance authorization and MRL standards through EFSA, collectively tightening permissible exposure thresholds and reshaping product development priorities. India's Central Insecticides Board under the Ministry of Agriculture mandates label compliance and handler certification, constraining informal supply channels. Stakeholders must monitor evolving residue standards in destination export markets and align formulation portfolios accordingly.
Market Dynamics
The US EPA's phasedown of methyl bromide under the Montreal Protocol is forcing immediate reformulation across commercial grain storage operations, redirecting procurement toward phosphine and sulfuryl fluoride alternatives while compressing legacy product margins.
Growth Catalysts
- Phytosanitary Export Mandates:The EU's MRL standards through EFSA are compelling warehouse operators in grain-exporting nations to upgrade fumigation protocols to maintain market access for bulk commodities.
- India:The Central Insecticides Board's handler certification requirements under the Ministry of Agriculture are professionalizing application services and consolidating demand around registered suppliers.
- Aluminum Phosphide Tablet Automation:Precision dosing equipment is reducing gas waste in large-scale silo operations and cutting per-ton treatment costs for commercial grain handlers.
Market Restraints
- Active Ingredient Supply Concentration:Phosphine precursor manufacturing clusters in China create vulnerability to export license disruptions and freight cost volatility.
- REACH Authorization Timelines:ECHA's substance evaluation procedures for fumigant actives extend registration cycles and freeze formulation development budgets for European suppliers.
- Corrosion Limitations in Metal Phosphides:Sulfuryl fluoride is capturing pharmaceutical and electronics warehouse contracts where moisture-activated phosphine damages sensitive equipment.
Strategic Opportunities
- Brazil:ANVISA's expanding residue monitoring program for soybean exports is generating demand for certified fumigation services in underpenetrated interior storage corridors.
- Integrated Pest Management Bundles:Fumigation providers are combining gas treatment with aeration monitoring and residue testing to capture recurring revenue from agricultural cooperatives.
- Remote Gas Monitoring Convergence:IoT sensor networks paired with phosphine detection systems are enabling real-time concentration management and reducing technician deployment costs.
Industry Challenges
- Certified Fumigator Shortages:EPA's applicator licensing requirements and state-level continuing education mandates are constraining field technician availability during peak harvest windows.
- ISO 9001 Compliance Burden:Third-party certification for manufacturing and application services demands 12-18 month documentation cycles that exclude smaller regional operators from tender participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehouse Fumigants Market |
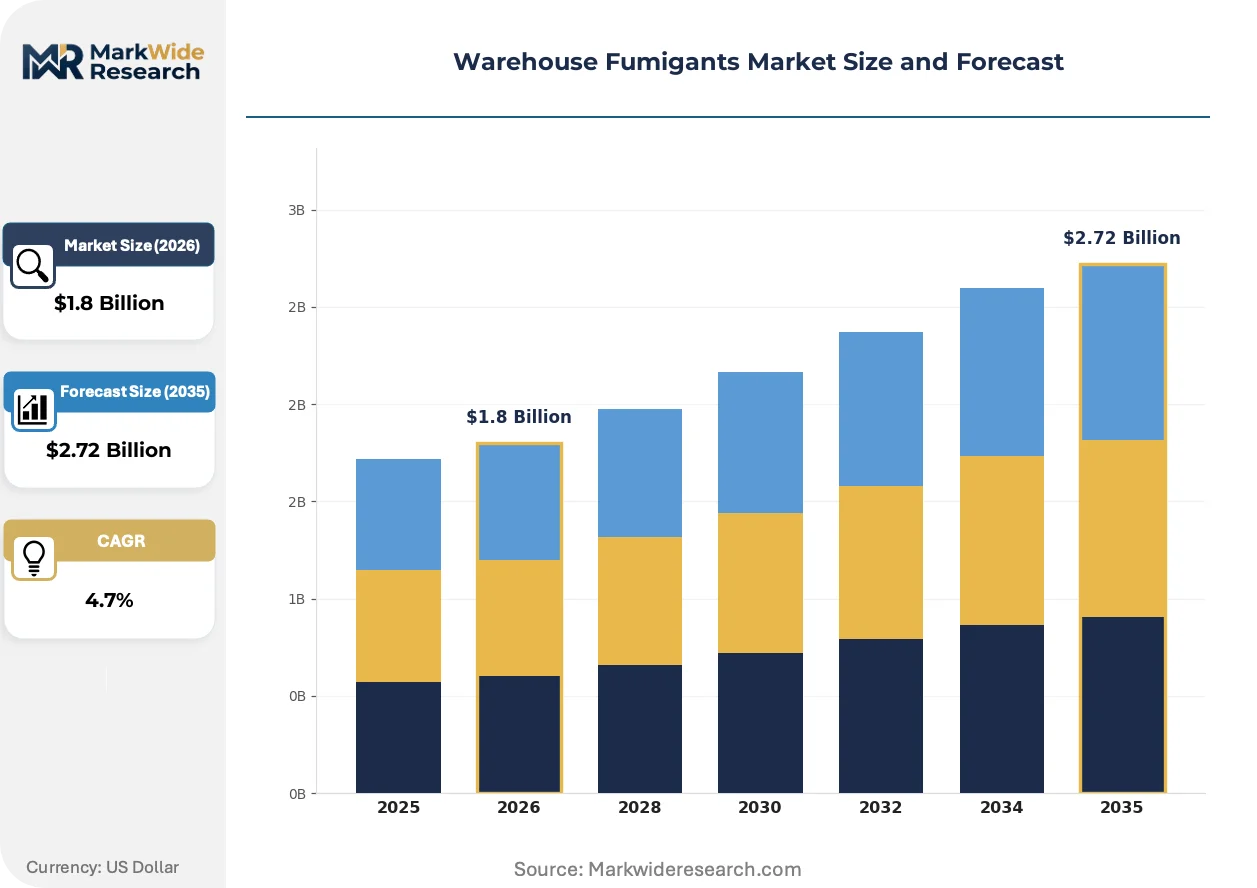
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Bromide, Phosphine, Sulfuryl Fluoride, Ethyl Formate Application: Crop Storage, Grain Fumigation, Pest Control, Wood Preservation Form: Gas, Liquid, Solid, Pellet End User: Agriculture, Food & Beverage, Pharmaceuticals, Logistics |
| Companies Covered | Degesch America Inc., Syngenta, UPL, Nippon Chemical Industrial Co. Ltd, Ikeda Kogyo Co., Ltd., BASF SE, ADAMA Ltd, Corteva Agriscience, Industrial Fumigation Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehouse Fumigants Market Evolving Landscape
Formulation chemistry and application hardware are converging to reduce human exposure risk while extending treatment efficacy periods in bulk grain masses. These shifts are compressing the operational gap between large commercial silos and smaller warehouse facilities.
Controlled-release phosphine formulations are decomposing at moisture-triggered rates that sustain lethal gas concentrations for extended periods without manual reapplication. Pharmaceutical warehouse operators in temperature-sensitive storage environments are adopting these systems to eliminate corrosion risks associated with traditional metal phosphide pellets. The technology is decomposing the historical performance gap between automated large-silo infrastructure and smaller facilities lacking pressurized gas distribution networks.
REACH substance authorization through ECHA is tightening permissible exposure thresholds for fumigant residues in stored commodities. European warehouse operators are reformulating application protocols and extending aeration periods to meet descending MRL ceilings. Grain export facilities in Germany and the Netherlands are investing in automated aeration systems to accelerate residue dissipation and maintain phytosanitary clearance timelines.
Grain handlers are consolidating procurement around full-service fumigation contracts that bundle gas supply, application labor, and residue compliance documentation. Agricultural cooperatives in the US Midwest are displacing spot purchases of raw phosphine tablets with annual service agreements that transfer regulatory liability to specialized providers. This pattern is most visible in Iowa and Illinois, where large-scale corn and soybean storage operators face intensified EPA inspection frequency and export documentation requirements.
Warehouse Fumigants Market Segmentation
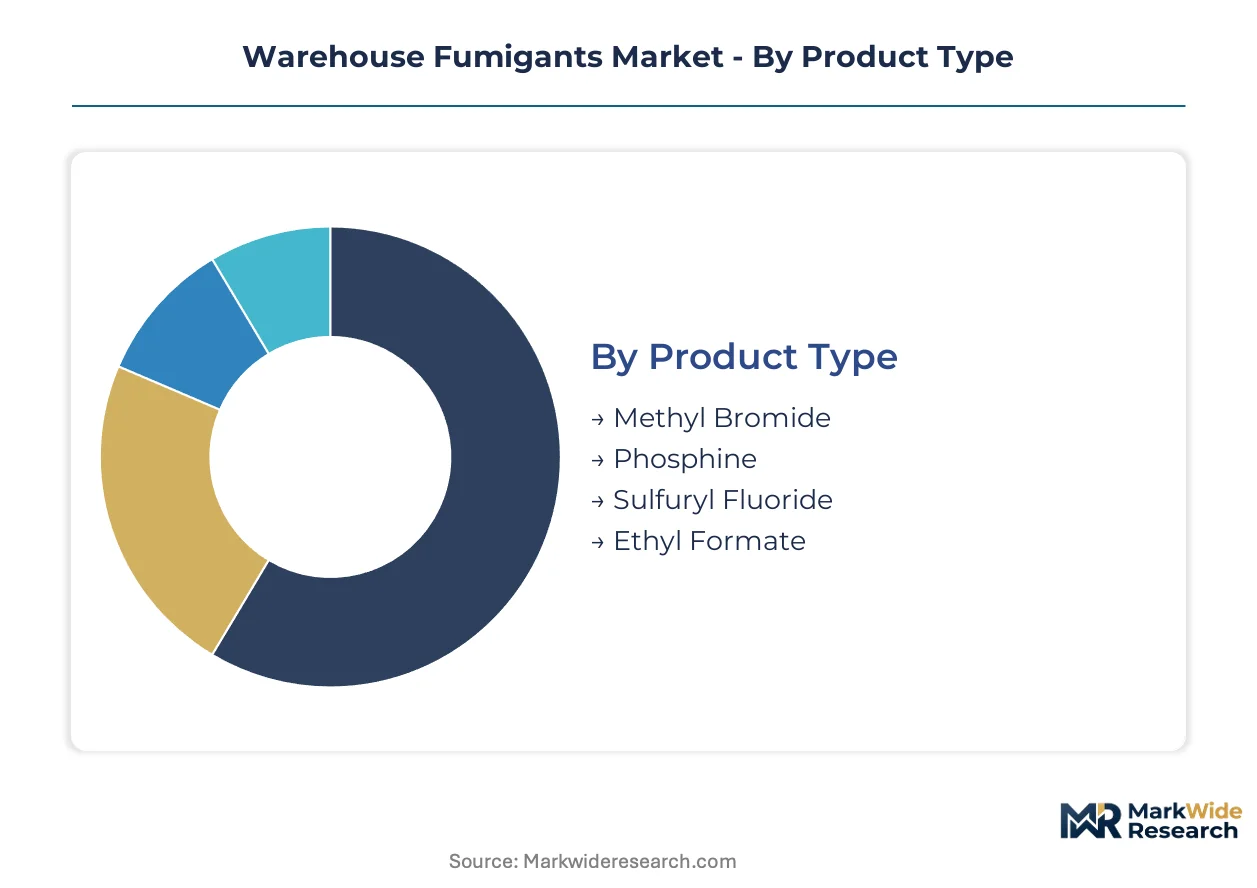
Warehouse fumigant procurement patterns diverge sharply across regulatory jurisdictions and commodity storage requirements. Formulation selection, application method, and end-use certification demands create distinct commercial pockets within the broader market structure.
Product Type:
EPA's phasedown mandates under the Montreal Protocol and REACH substance authorization timelines through ECHA are segmenting procurement by regulatory compliance burden rather than pure efficacy metrics.
- Phosphine:Aluminum and magnesium phosphide formulations release phosphine gas upon moisture exposure, delivering lethal concentrations against stored-product insects at lower unit economics than alternatives. Demand concentrates in US Midwest grain elevators and commercial silo operations where established residue tolerance profiles simplify export documentation. EPA applicator licensing requirements and state continuing education mandates sustain replacement cycles among registered suppliers.
- Sulfuryl Fluoride:This non-corrosive gas penetrates bulk commodities without moisture activation, eliminating equipment damage risks in temperature-sensitive pharmaceutical warehouses and electronics storage facilities. Adoption accelerates in Germany and the Netherlands where EFSA's descending MRL ceilings favor shorter aeration periods and reduced residue uncertainty.
- Methyl Bromide:Legacy registrations persist in limited quarantine and pre-shipment applications exempt from Montreal Protocol phaseout schedules. Brazil's ANVISA residue monitoring for soybean exports maintains niche demand in certified export corridors.
- Ethyl Formate:Botanical-derived alternative with GRAS status for food-contact applications, attracting organic commodity handlers in Australia and specialty grain cooperatives seeking residue-free certification.
Established volume favors phosphine; emerging adoption favors sulfuryl fluoride.
Application:
Cost tier differentiation separates commodity-scale operations from precision-demanding specialty storage.
- Grain Fumigation:Bulk silo and warehouse treatments dominate operational deployment, with phosphine gas penetrating deep into corn and soybean masses during extended storage periods. Iowa and Illinois agricultural cooperatives consolidate procurement around full-service contracts bundling gas supply, application labor, and EPA compliance documentation.
- Crop Storage:On-farm bin and elevator applications require smaller-scale solid and pellet formulations where pressurized infrastructure is absent. India's Central Insecticides Board handler certification requirements professionalize services and consolidate demand around registered regional suppliers.
- Pest Control:Structural treatments for empty warehouses and transport vessels employ sulfuryl fluoride and methyl bromide alternatives where rapid aeration and minimal residue persistence are prioritized.
- Wood Preservation:Timber and pallet fumigation for export phytosanitary compliance maintains steady demand in Pacific Northwest lumber processing clusters and European hardwood distribution hubs.
Volume concentrates in grain fumigation; margin expansion concentrates in crop storage services.
Form:
Application infrastructure availability determines form selection across facility scale tiers.
- Gas:Pressurized distribution systems deliver uniform penetration in large commercial silos exceeding 10,000-ton capacity. Automated dosing equipment reduces per-ton treatment costs and gas waste for US commercial grain handlers facing intensified EPA inspection frequency.
- Pellet:Controlled-release phosphine formulations decompose at moisture-triggered rates, sustaining lethal concentrations without manual reapplication in smaller facilities lacking pressurized infrastructure. Pharmaceutical warehouses adopt these systems to eliminate corrosion risks from traditional metal phosphide exposure.
- Solid:Tablet and sachet formats retain relevance in developing markets with limited technician availability and basic storage infrastructure.
- Liquid:Ethyl formate and specialty formulations serve organic certification requirements and food-contact applications where gas residuals are restricted.
Gas dominates commercial scale; pellet formats are climbing fastest in specialty storage.
End User:
Customer type dictates certification burden and service bundling preferences.
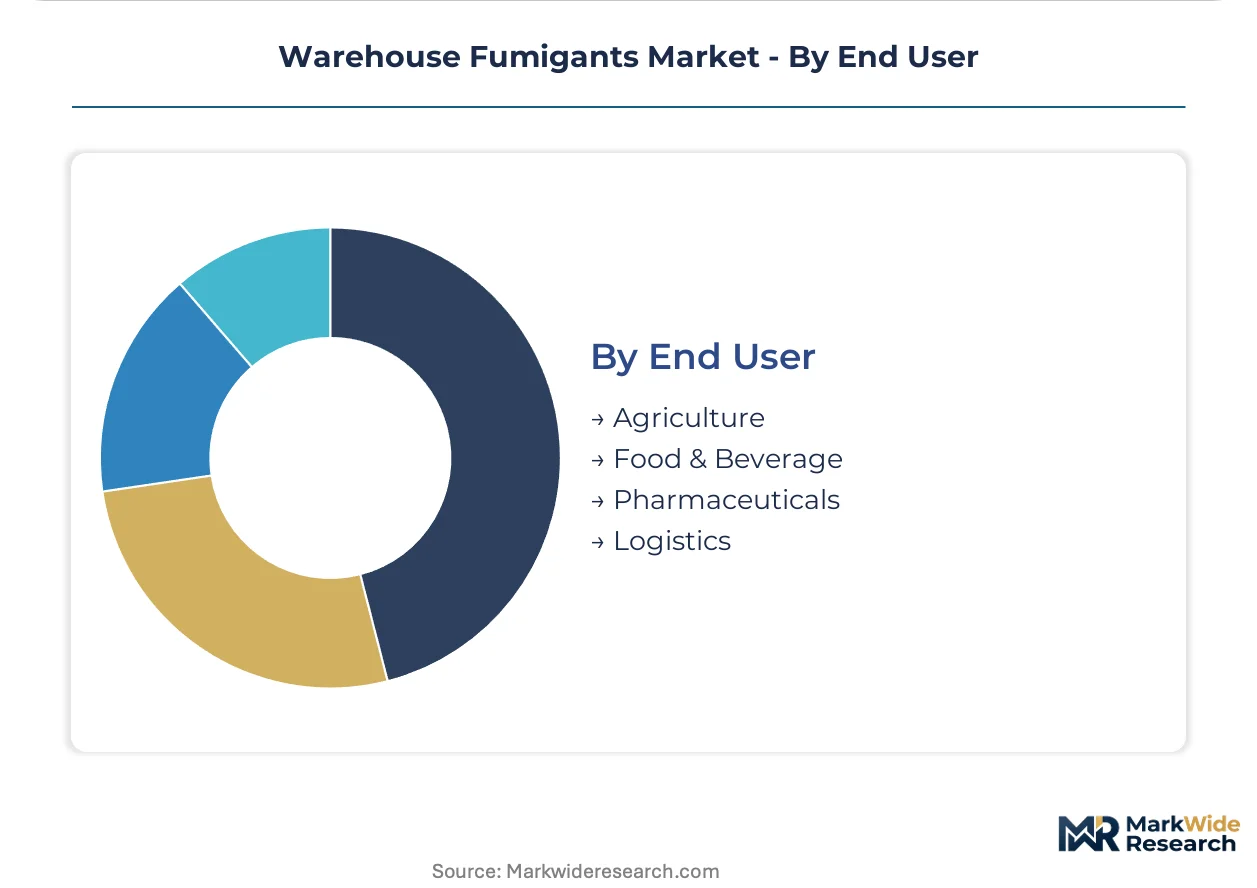
- Agriculture:Grain elevators, cooperatives, and on-farm storage operators generate baseline demand through seasonal treatment cycles. US Midwest operators displace spot tablet purchases with annual service agreements transferring regulatory liability to specialized fumigation providers.
- Food & Beverage:Processed commodity warehouses and beverage ingredient storage require residue documentation aligned with destination market MRL standards. EU export facilities invest in automated aeration systems to accelerate dissipation and maintain phytosanitary clearance timelines.
- Pharmaceuticals:Temperature-sensitive active ingredient storage demands non-corrosive sulfuryl fluoride treatments with validated aeration protocols. ISO 9001 certification for manufacturing and application services excludes smaller regional operators from tender participation.
- Logistics:Third-party warehousing and cross-dock facilities require rapid-turnaround treatments compatible with just-in-time inventory flows. IoT sensor networks paired with phosphine detection systems enable real-time concentration management and reduce technician deployment costs.
Agriculture anchors volume; logistics presents the steepest expansion trajectory for integrated monitoring services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain elevator operators and agricultural cooperatives concentrate procurement power in the United States, while export-oriented storage facilities in Germany and Brazil drive regulatory compliance investments. Chemical manufacturers and application service providers calibrate regional strategies against divergent residue standards and certification timelines.
United States
Midwest grain elevators in Iowa and Illinois sustain replacement cycles through seasonal corn and soybean storage demands. EPA applicator licensing requirements and state continuing education mandates constrain technician availability during peak harvest windows. Commercial silo operators around Chicago and Minneapolis displace spot tablet purchases with annual service agreements transferring regulatory liability to specialized providers.
Germany
EFSA's descending MRL ceilings compel warehouse operators to extend aeration periods and accelerate residue dissipation investments. REACH substance authorization through ECHA tightens permissible exposure thresholds and freezes formulation development budgets for domestic suppliers. Grain export facilities in Hamburg and Bremen deploy automated aeration systems to maintain phytosanitary clearance timelines for EU destination markets.
Brazil
ANVISA's expanding residue monitoring program for soybean exports generates demand for certified fumigation services in underpenetrated interior storage corridors. Phytosanitary mandates for bulk commodity shipments redirect procurement toward registered suppliers with documented compliance protocols. Agricultural cooperatives in Mato Grosso and Goiás upgrade treatment infrastructure to preserve market access for China-bound exports.
India
The Central Insecticides Board's handler certification requirements under the Ministry of Agriculture professionalize application services and consolidate demand around registered regional suppliers. On-farm bin and elevator applications require smaller-scale solid formulations where pressurized infrastructure is absent. Punjab and Haryana grain handlers adopt pelletized phosphine products as precision dosing equipment penetrates commercial storage networks.
Australia
Organic commodity handlers and specialty grain cooperatives seek residue-free certification through botanical-derived alternatives with GRAS status for food-contact applications. TGA-aligned phytosanitary standards for export shipments sustain baseline demand for conventional fumigation protocols. Storage operators in New South Wales and Victoria balance premium market access against treatment cost economics in wheat and barley export corridors.
Warehouse Fumigants Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive phosphine precursor production and specialized application service providers with certified technician networks. Market structure concentrates around three strategic archetypes: multinational agrochemical majors leveraging formulation patents, regional fumigation service companies bundling gas supply with compliance documentation, and equipment-integrated specialists automating dosing precision in large-scale silo operations. Dominant competitive moves include backward integration into phosphine tablet manufacturing and geographic expansion through distributor partnerships in underpenetrated grain-exporting corridors.
Within the integrated chemical tier, BASF SE anchors cost-position advantages through captive production network scale, while Syngenta occupies a patent-protected position via proprietary formulation portfolios directed toward agricultural cooperatives. Degesch America Inc. exemplifies the equipment-integrated specialist archetype, competing through specialized application hardware and technician training protocols rather than raw material leverage. These three entities collectively represent the competitive fault lines between manufacturing scale, intellectual property control, and service-intensive customer relationships.
| Leading Market Players |
|---|
| Degesch America Inc. |
| Syngenta |
| UPL |
| Nippon Chemical Industrial Co. Ltd |
| Ikeda Kogyo Co., Ltd. |
| BASF SE |
| ADAMA Ltd |
| Corteva Agriscience |
| Industrial Fumigation Company LLC |
| Others |
Value Network & Pricing Analysis
Phosphine precursor substitution for methyl bromide is redrawing manufacturing geography toward Chinese chemical clusters while compressing margin structures for legacy suppliers dependent on phased-out active ingredients. This input transition simultaneously elevates freight cost volatility as a pricing determinant and concentrates procurement leverage among buyers with volume scale.
Pricing Analysis
Annual cost-plus contracts indexed to aluminum and magnesium metal prices dominate commercial grain elevator procurement in the US Midwest. Three-tier pricing structure across ISO 9001-certified premium, registered-standard, and uncertified-economy levels separates agricultural cooperatives by documentation burden. Pricing pressure stems from EPA applicator licensing requirements that inflate service delivery costs. Spot purchasers of raw phosphine tablets exhibit highest price sensitivity; pharmaceutical warehouse operators prioritizing sulfuryl fluoride corrosion avoidance show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites phosphine precursor feedstock flows from Chinese manufacturing clusters to formulation plants in India and Southeast Asia. Active ingredient production centers on China, India, and Germany; aluminum phosphide tablet finishing occurs in the United States and Brazil. Supply chain risk rests on single-source vulnerability for phosphine gas precursor exports subject to Chinese environmental license suspensions. Distribution runs through agricultural cooperative procurement consortia and direct pharmaceutical warehouse contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural cooperative consolidation across Iowa and Illinois is shifting procurement leverage toward fewer buyers with larger volume blocks and stricter certification demands.
For Market Incumbents: Consolidate technician training networks to offset EPA licensing bottlenecks constraining peak-season deployment capacity. Deepen backward integration into phosphine tablet manufacturing to defend margin position against Chinese precursor price volatility. Lock long-term service agreements with Midwest grain elevators before cooperative procurement centralization accelerates.
For New Entrants and Emerging Players: Anchor in Brazil's interior soybean storage corridors where ANVISA residue monitoring is generating first-time certified fumigation demand. Target pharmaceutical logistics operators seeking sulfuryl fluoride alternatives to corrosion-prone phosphine systems. Lead with IoT-integrated remote gas monitoring as a differentiated service layer.
For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors equipment-integrated specialists with captive technician certification infrastructure. Five-to-ten year viability hinges on REACH authorization timelines and Montreal Protocol compliance trajectories. Acquisition targets should demonstrate EPA registration breadth and established agricultural cooperative relationships. Watch ECHA substance evaluation decisions as the inflection signal for European formulation portfolio viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive phosphine feedstock supply insulates margin structures from Chinese export license volatility. |
| ISO 9001 Certification Investment | Third-party quality accreditation unlocks tender participation for pharmaceutical warehouse contracts. |
| IoT Sensor Network Deployment | Real-time phosphine concentration monitoring reduces technician deployment costs for logistics operators. |
| Long-term Service Agreement Structuring | Annual contracts transfer regulatory liability from agricultural cooperatives to specialized fumigation providers. |
| Geographic Expansion through Distributor Partnerships | Local registration expertise accelerates market access in underpenetrated Brazilian interior storage corridors. |
Research Methodology
A spread of perspectives from grain elevator operations managers, EPA-certified fumigation technicians, agricultural cooperative procurement directors, and pharmaceutical warehouse compliance officers converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation against US EPA registration databases, EU REACH substance authorization records, customs trade flow data, and agricultural cooperative financial disclosures. Bottom-up volume estimates from facility-level treatment cycles triangulated against top-down chemical manufacturer shipment data.
Segmentation dimensions modeled span product type, application method, formulation form, and end-user category across the projection horizon. CAGRs derived from trend extrapolation of historical treatment cycle frequencies and regulatory-mandated product substitution rates. Forecast inputs incorporated EPA phasedown timelines for methyl bromide and EFSA descending MRL ceiling trajectories.
Underlying assumptions cover continued Montreal Protocol compliance enforcement and stable phosphine precursor export licensing from China, with deviation risk concentrated in REACH authorization delays and agricultural commodity trade flow disruptions. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and Chinese environmental policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Sulfuryl Fluoride Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Artificial Preservatives Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Latin America Cosmetic Preservatives Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Hypochlorous Acid Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market